
 Ghana Telecom Market | 2026-2036
Ghana Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Ghana Telecom Market Insights
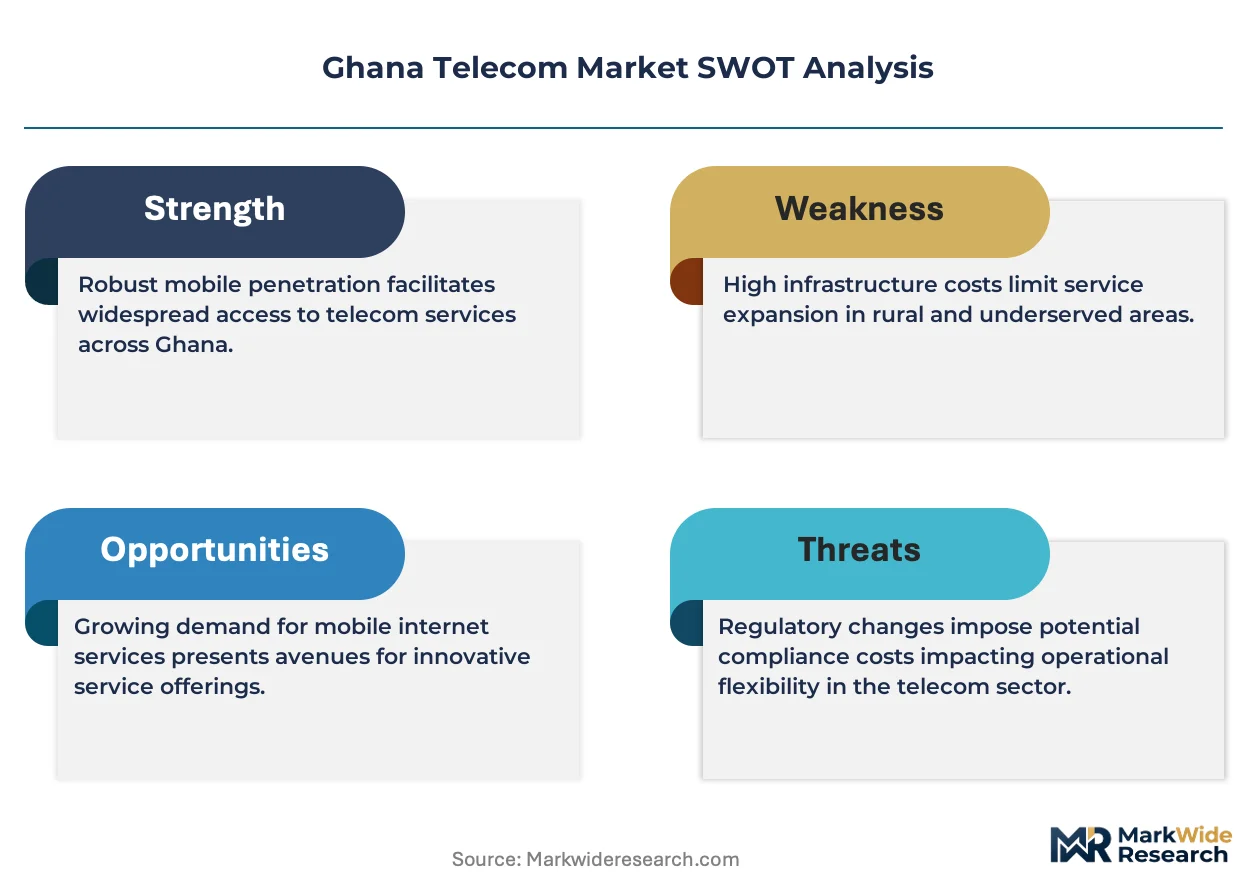
Software-defined network features bundled into enterprise subscriptions is pivoting how carriers monetize connectivity beyond raw bandwidth. MTN Ghana leverages its mobile money platform to anchor enterprise relationships with integrated voice-data-financial services. Telecel Ghana differentiates through aggressive fiber expansion into secondary cities, sustaining capital intensity where rivals defer. AT Ghana competes on price-transparent SME packages, occupying a mid-market position between premium fiber and basic wireless.
Ghana telecom encompasses the transmission infrastructure, switching systems, and access technologies enabling voice and data communication across licensed spectrum and fixed-line networks, with 4G LTE requiring base stations operating at 700 MHz, 800 MHz, and 2600 MHz bands to deliver throughput exceeding 100 Mbps in urban cells. The primary commercial purpose is to connect residential consumers, business enterprises, and government agencies to domestic and international digital services. Mobile data services generate the dominant revenue pool as smartphone penetration deepens, while fiber optic technology commands premium pricing despite deployment constraints. Fixed-line infrastructure remains structurally mature, with Ghana Telecommunications Company Limited maintaining legacy copper assets that serve institutional backhaul rather than residential access.
The National Communications Authority enforces quality-of-service benchmarks and interconnection tariffs that directly shape operator investment timelines and retail pricing floors. Ghana's Cybersecurity Act and data protection standards from the Data Protection Commission impose infrastructure compliance costs on cloud-based deployment models, particularly for financial and government customer segments. Spectrum allocation decisions from the Ministry of Communications determine which technology generations dominate specific geographic markets. Stakeholders must monitor pending 5G licensing frameworks and rural universal service fund disbursements to calibrate capital deployment against regulatory timelines.
Market Dynamics
Spectrum reallocation mandates from the National Communications Authority are compressing deployment timelines and forcing operators to accelerate infrastructure modernization across multiple frequency bands simultaneously.
Growth Catalysts
- Mobile money integration:Financial services embedded in telecom platforms deepen subscriber stickiness and expand average revenue per user across SME segments in Greater Accra.
- Fiber-to-the-home mandates:Commercial corridor densification requirements push 4G and fixed broadband convergence in Ashanti Region urban clusters.
- Cybersecurity Act compliance:Data protection standards from the Data Protection Commission drive cloud infrastructure investment among financial and government customer segments.
Market Restraints
- Capital intensity barriers:Fiber optic deployment costs concentrate infrastructure buildout in premium urban corridors, leaving secondary cities underserved.
- Legacy copper dependency:Ghana Telecommunications Company Limited's aging fixed-line assets impose maintenance burdens that divert resources from wireless modernization.
- Regulatory timeline uncertainty:Pending 5G licensing frameworks from the Ministry of Communications freeze long-term capital commitment decisions.
Strategic Opportunities
- Secondary city fiber expansion:Aggressive buildout into underserved urban centers beyond Accra and Kumasi captures latent SME demand.
- Software-defined network bundling:Enterprise subscription models monetize connectivity through value-added services rather than raw bandwidth arbitrage.
- Rural universal service fund access:Disbursement timelines from the Ministry of Communications create subsidy-backed entry points for infrastructure deployment.
Industry Challenges
- Interconnection tariff complexity:Quality-of-service benchmarks and pricing floors from the National Communications Authority constrain margin flexibility.
- Multi-band spectrum coordination:Operating base stations across 700 MHz, 800 MHz, and 2600 MHz bands simultaneously demands specialized engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ghana Telecom Market |
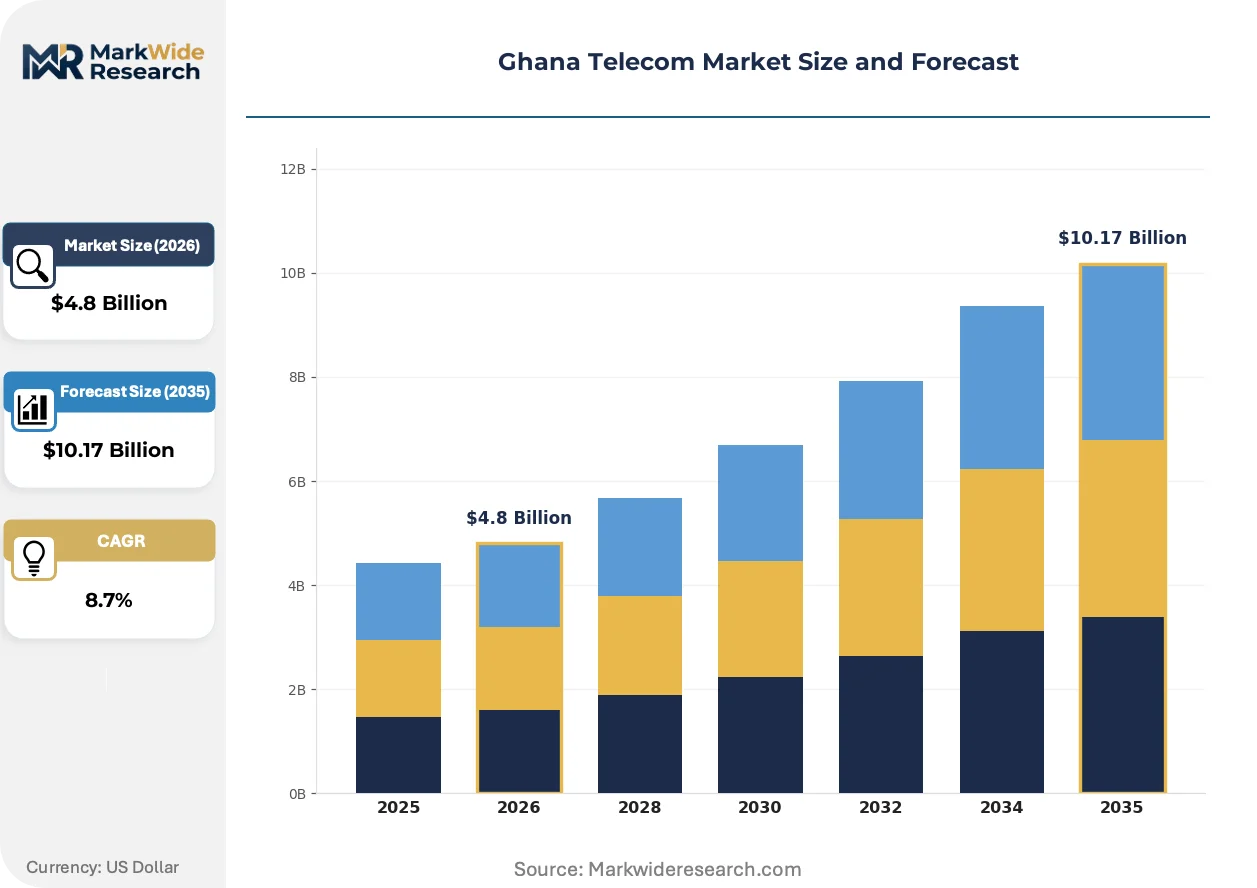
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed-line, Internet Services Technology: 2G, 3G, 4G, Fiber Optic Customer Type: Residential, Business, Government, Non-profit Deployment Model: On-premise, Cloud-based, Hybrid, Managed Services |
| Companies Covered | MTN Ghana, Telecel Ghana, AT Ghana, AirtelTigo, Glo Ghana, Vodafone Ghana, Surfline Communications, Scancom PLC Ghana Limited, Ghana Telecommunications Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ghana Telecom Market Trends and Innovations
Software-defined infrastructure is fragmenting traditional hardware-centric deployment models, enabling operators to virtualize network functions and compress time-to-market for new service launches.
Open radio access network architectures are modularizing base station deployment across Ghana's 4G densification projects. Rural and secondary city operators adopt these standards to reduce vendor lock-in and diversify equipment sourcing. The technology is modularizing capital expenditure patterns, allowing incremental capacity expansion without full hardware replacement cycles.
The National Communications Authority's quality-of-service benchmarks are tightening latency and throughput requirements for licensed operators. These mandates force infrastructure upgrades in dense urban cells and reshape competitive positioning around reliability metrics. Financial services customers in Accra face the steepest compliance costs as Cybersecurity Act provisions intersect with data protection standards.
Enterprise procurement of connectivity services is fragmenting from long-term bundled contracts toward modular, usage-based subscriptions. SMEs in Greater Accra commercial corridors now unbundle voice, data, and financial services rather than accepting operator-defined packages. This pattern concentrates among digitally transforming businesses seeking transparent, scalable cost structures.
Ghana Telecom Market Segmentation
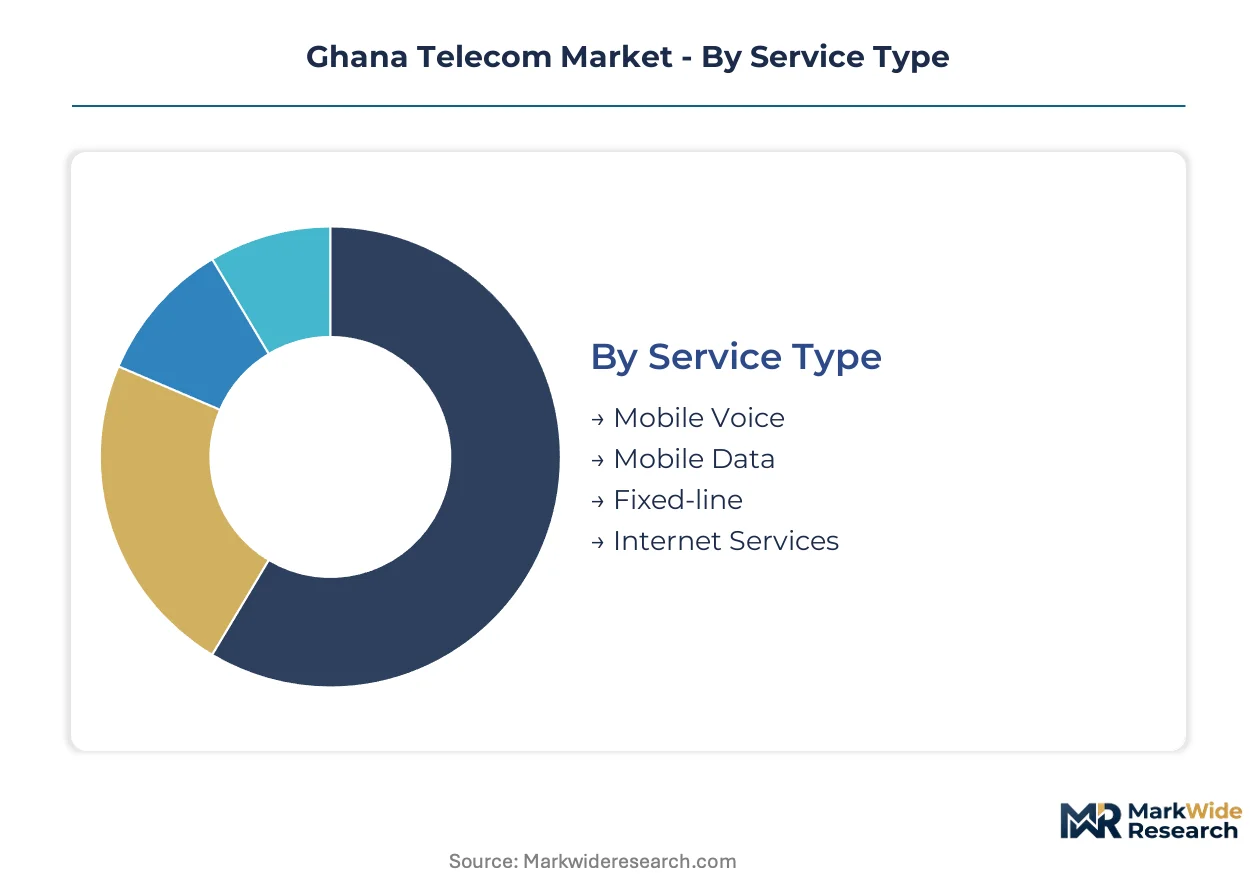
Ghana's telecom market fragments across service delivery modes, infrastructure generations, and customer procurement patterns. Each segmentation axis reveals distinct margin profiles and capital deployment priorities for licensed operators navigating spectrum constraints and enterprise digitization.
Service Type:
Revenue concentration follows data consumption intensity rather than legacy voice minutes.
- Mobile Data:4G LTE throughput exceeding 100 Mbps in urban cells anchors smartphone penetration in Greater Accra. SME digitization in commercial corridors accelerates per-gigabyte monetization as businesses unbundle from voice-centric packages.
- Mobile Voice:Traditional circuit-switched services retain stickiness through mobile money integration, though ARPU compression intensifies as over-the-top alternatives displace international calling. Network quality benchmarks from the National Communications Authority sustain infrastructure maintenance obligations.
- Fixed-line:Ghana Telecommunications Company Limited maintains legacy copper assets serving institutional backhaul rather than residential access. Structural maturity limits expansion capital as wireless substitution deepens.
- Internet Services:Fiber-to-the-home mandates in Ashanti Region urban clusters command premium pricing despite deployment cost barriers. Commercial corridor densification requirements reshape competitive positioning around latency reliability.
Volume sits with mobile voice; growth tilts toward mobile data.
Technology:
Capital cycles concentrate where spectrum reallocation mandates compress modernization timelines.
- 4G:Base stations operating at 700 MHz, 800 MHz, and 2600 MHz bands deliver urban throughput thresholds. Multi-band coordination demands specialized engineering talent as operators densify coverage in premium corridors.
- Fiber Optic:Deployment constraints limit buildout to premium urban markets, leaving secondary cities underserved despite latent SME demand. Telecel Ghana's aggressive expansion into secondary cities captures pricing power where rivals defer.
- 3G:Transitional infrastructure faces accelerated obsolescence as National Communications Authority spectrum mandates force reallocation toward 4G and pending 5G frameworks.
- 2G:Legacy GSM infrastructure sustains basic connectivity in rural peripheries pending universal service fund disbursement timelines from the Ministry of Communications.
Investment stock concentrates in 4G; expansion trajectory favors fiber optic.
Customer Type:
Procurement sophistication determines pricing transparency and contract modularity.
- Business:Enterprise subscriptions fragment toward usage-based models as SMEs in Greater Accra commercial corridors unbundle voice, data, and financial services. Software-defined network features enable value-added monetization beyond raw bandwidth.
- Government:Cybersecurity Act compliance intersects with Data Protection Commission standards, imposing infrastructure costs on cloud-based deployment models for financial and public sector segments.
- Residential:Smartphone penetration deepens average revenue per user through mobile money platform anchoring, particularly in urban consumption clusters.
- Non-profit:Cost-sensitive demand occupies mid-market positioning between premium fiber and basic wireless, often aggregating through managed service intermediaries.
Revenue scale aggregates with business customers; compliance complexity peaks in government.
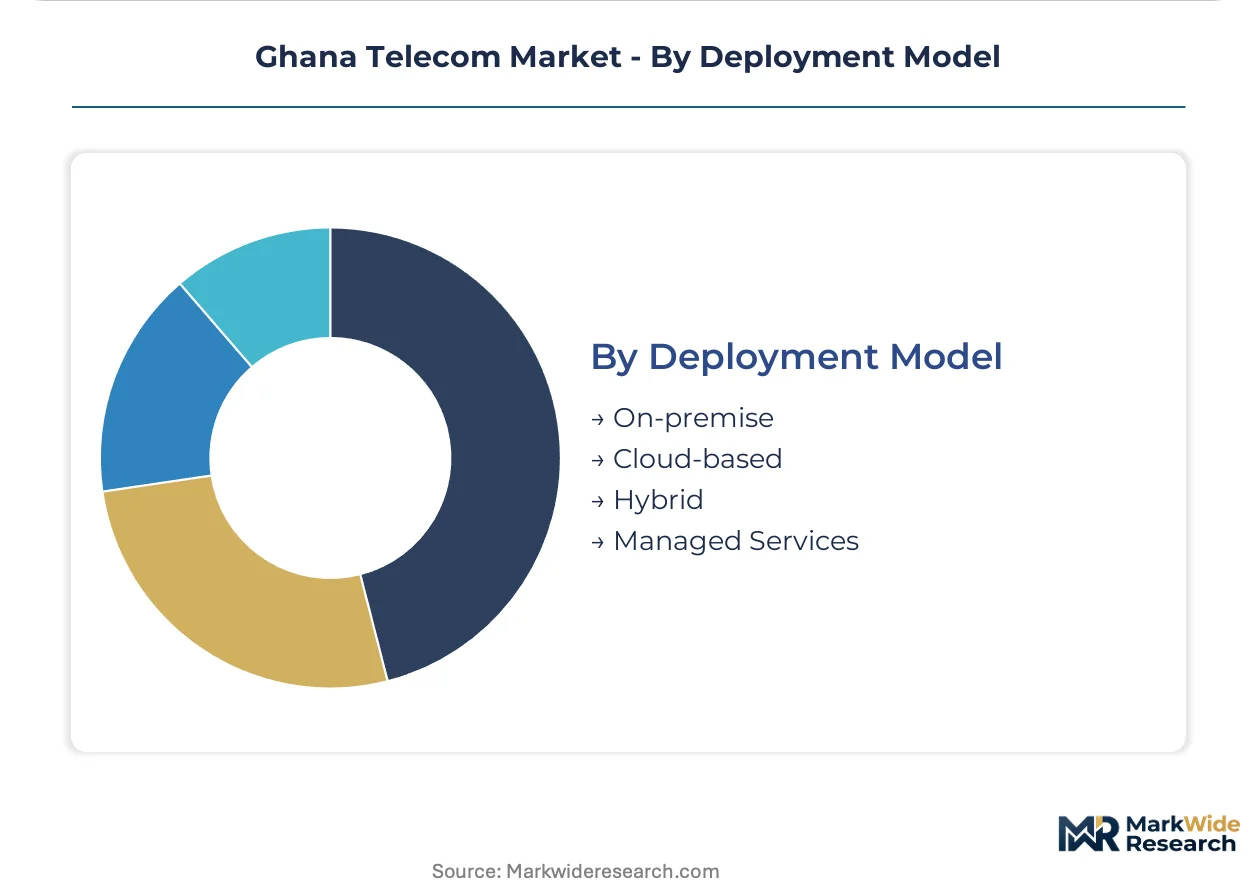
Deployment Model:
Cloud migration patterns reshape capital expenditure structures and vendor relationships.
- Cloud-based:Virtualized network functions compress time-to-market for new service launches, though Cybersecurity Act provisions impose compliance burdens on financial services customers in Accra.
- Hybrid:Enterprises balance latency-sensitive workloads on-premise with scalable cloud capacity, creating modular procurement patterns that operators monetize through software-defined subscription tiers.
- Managed Services:Outsourced infrastructure operation appeals to SMEs lacking specialized engineering talent for multi-band spectrum coordination across 700 MHz, 800 MHz, and 2600 MHz deployments.
- On-premise:Legacy institutional installations persist in government and financial segments where data sovereignty requirements intersect with data protection standards.
Installed base remains on-premise; adoption momentum shifts toward cloud-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ghana's telecom infrastructure production concentrates in Greater Accra's technology corridors, while consumption spreads across Ashanti Region commercial clusters and emerging secondary cities. This geographic divide shapes capital deployment priorities and spectrum allocation strategies. National Communications Authority mandates accelerate modernization timelines unevenly across regional markets.
Greater Accra
Mobile money integration and SME digitization drive data consumption intensity in Accra's commercial corridors. National Communications Authority quality-of-service benchmarks enforce latency thresholds that force infrastructure upgrades in dense urban cells. Fiber-to-the-home mandates cluster deployment around Tema port logistics zones and Airport City financial districts.
Ashanti Region
4G densification projects and fixed broadband convergence capture manufacturing and trading enterprise demand in Kumasi urban clusters. Spectrum reallocation mandates from the Ministry of Communications compress deployment timelines for multi-band base station coordination. Commercial corridor requirements reshape competitive positioning around reliability metrics in Adum and Kejetia market zones.
Western Region
Oil and gas logistics operations generate specialized enterprise connectivity demand around Takoradi port infrastructure. Cybersecurity Act compliance intersects with data protection standards for energy sector customers. Secondary city fiber expansion captures latent SME demand as Telecel Ghana extends buildout beyond premium urban corridors.
Northern Region
Rural universal service fund disbursement timelines from the Ministry of Communications create subsidy-backed entry points for basic wireless infrastructure. Legacy 2G GSM infrastructure sustains connectivity in peripheral agricultural zones pending modernization funding. Tamale metropolitan area concentrates limited fiber deployment around government and educational institutions.
Central Region
Tourism and port logistics dual-use corridors drive heterogeneous connectivity requirements around Cape Coast and Elmina heritage zones. Capital intensity barriers limit fiber optic buildout to institutional backhaul rather than residential access. Managed services appeal to hospitality SMEs lacking specialized engineering talent for multi-band spectrum coordination.
Ghana Telecom Market Competitive Landscape
Top-tier vendors anchor premium fiber and integrated financial services, while mid-market specialists compete on price-transparent SME packages and secondary city expansion. The vendor base concentrates around three licensed mobile network operators with infrastructure-sharing arrangements and spectrum coordination obligations. Strategic archetypes include mobile money platform integrators, aggressive fiber expanders, and mid-market price competitors. Dominant competitive moves encompass enterprise subscription unbundling and software-defined network feature bundling beyond raw bandwidth arbitrage.
Within the integrated platform tier, MTN Ghana and Telecel Ghana occupy positions exemplifying divergent capital deployment strategies. MTN Ghana anchors enterprise relationships through mobile money platform integration that bundles voice, data, and financial services. Telecel Ghana represents the fiber expansion archetype with aggressive buildout into secondary cities where rivals defer capital commitment. AT Ghana sits within the mid-market positioning between premium fiber and basic wireless, competing on price-transparent SME package structures. These three operators collectively illustrate how spectrum constraints and regulatory timelines reshape competitive positioning across Ghana's converging telecom and financial services landscape.
| Leading Market Players |
|---|
| MTN Ghana |
| Telecel Ghana |
| AT Ghana |
| AirtelTigo |
| Glo Ghana |
| Vodafone Ghana |
| Surfline Communications |
| Scancom PLC Ghana Limited |
| Ghana Telecommunications Company Limited |
| Others |
Pricing and Supply Chain Analysis
Base station equipment and fiber optic cable procurement costs cascade through subscription pricing tiers, with 700 MHz, 800 MHz, and 2600 MHz spectrum licensing fees compressing margin structures for operators serving Greater Accra SME clusters.
Pricing Analysis
Margin tightening in enterprise fiber subscriptions reflects multi-band base station coordination costs and specialized engineering talent scarcity. Three-tier pricing structure across premium fiber, standard wireless, and economy mobile voice segments stratifies by latency reliability and cybersecurity compliance bundling. Cost-down pressure on mid-market SME packages accelerates as AT Ghana and rivals compete on transparent usage-based models. Government and financial segments show lowest price sensitivity due to Cybersecurity Act mandates, while residential prepaid mobile voice exhibits highest elasticity.
Supply Chain Analysis
National Communications Authority local-content infrastructure mandates reshape equipment sourcing toward approved vendor lists and domestic installation partnerships. Base station hardware concentrates in China, South Korea, and Finland, while fiber optic cable draws from Japan, the USA, and Germany. Deployment rests on imported 4G LTE radio units, optical transmission gear, and power systems vulnerable to currency fluctuation and logistics chokepoints at Tema port. Distribution runs through licensed operator procurement departments directly to tower companies and civil works contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ghana's telecom market operates as a spectrum-constrained environment where 5G licensing timeline uncertainty props pricing power for incumbent 4G infrastructure holders.
For Market Incumbents: Deepen mobile money platform integration to anchor enterprise relationships against over-the-top financial service entrants. Expand fiber-to-the-home capacity in Ashanti Region commercial corridors before spectrum reallocation mandates accelerate. Prioritize software-defined network certification investments that differentiate subscription tiers beyond raw bandwidth arbitrage. For New Entrants and Emerging Players: Launch via managed services partnerships targeting secondary cities where Telecel Ghana's fiber expansion has created latent SME demand gaps. Focus white-space capture on Northern Region rural universal service fund disbursement timelines and Central Region tourism-hospitality clusters lacking specialized engineering talent. Pursue modular cloud-based deployment models that bypass heavy base station capital requirements. For Investors and Strategic Acquirers: Pending 5G licensing framework publication from the Ministry of Communications is the leading indicator that capital commitment decisions will unlock. Position acquisition screening around fiber infrastructure specialists with secondary city footprints and software-defined network capability stacks. Long-term viability hinges on operators bridging wireless and financial services convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Portfolio Optimization | Multi-band 700/800/2600 MHz coordination secures urban throughput leadership in Greater Accra. |
| Mobile Money Platform Extension | Voice-data-financial bundling deepens subscriber stickiness among SME digitization adopters. |
| Fiber Infrastructure Buildout | Secondary city expansion captures pricing power where rivals defer capital deployment. |
| Software-Defined Network Deployment | Virtualized functions compress time-to-market for enterprise subscription feature launches. |
| Cybersecurity Compliance Certification | Data Protection Commission alignment unlocks government and financial segment premiums. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Ghana telecom market assessment. Primary interviews with network planning executives, tower company operations managers, National Communications Authority officials, and enterprise IT procurement officers combined with National Communications Authority spectrum allocation records, Ministry of Communications policy documents, and operator annual reports. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from infrastructure deployment tracking.
Data-stream reconciliation across mobile data consumption metrics, base station deployment databases, and enterprise subscription pricing surveys informed the analytical framework. Segmentation dimensions modeled include service type, technology generation, customer procurement sophistication, and deployment architecture across the projection horizon. CAGRs derived from subscriber growth trajectories, ARPU compression patterns, and capital intensity ratios specific to 4G densification and fiber-to-the-home rollout cycles.
The model assumes a particular technology adoption path; alternative pathways for 5G infrastructure deployment would alter the outlook if licensing timelines accelerate or spectrum pricing structures shift. Forecasts reflect assumptions regarding National Communications Authority enforcement consistency and universal service fund disbursement pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Russia ICT Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
Angola Telecom Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Singapore Telecom Market
Telecommunications
Global LTE Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Oman Telecom Market
Telecommunications
Telecom Managed Services Market
Telecommunications
Telecommunication Service Market
Telecommunications
Kuwait Telecom Market
Telecommunications
A2P Messaging Market
Telecommunications
Austria ICT Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Telecom Services Market