
 Turkey Telecom Market | 2026-2036
Turkey Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Telecom Market Outlook
Project finance for shared tower infrastructure is fragmenting competitive barriers in Turkish telecom. Turkcell leverages its integrated mobile and fixed network footprint to sustain pricing power across Anatolia. Türk Telekom anchors national fiber backhaul capacity through state-linked concession structures. Vodafone Turkey competes on multinational procurement scale, importing equipment standards from its European parent operations.
Turkey telecom encompasses wireless and wireline communication services, transmission infrastructure, and subscriber equipment operating across licensed spectrum bands from 700 MHz to 3.5 GHz and fiber-optic cable systems with single-mode cores rated for 10 Gbps and higher throughput. Its primary purpose is enabling voice, data, and video exchange for consumer, enterprise, and public-sector endpoints. Mobile services dominate revenue generation through prepaid and postpaid subscriber bases, while fiber optic infrastructure represents the fastest-expanding capital allocation as operators replace aging copper loops. Enterprise plans command the most attractive margin pools due to long-term contracts and managed service attachments, though budget plans absorb the highest absolute subscriber volumes.
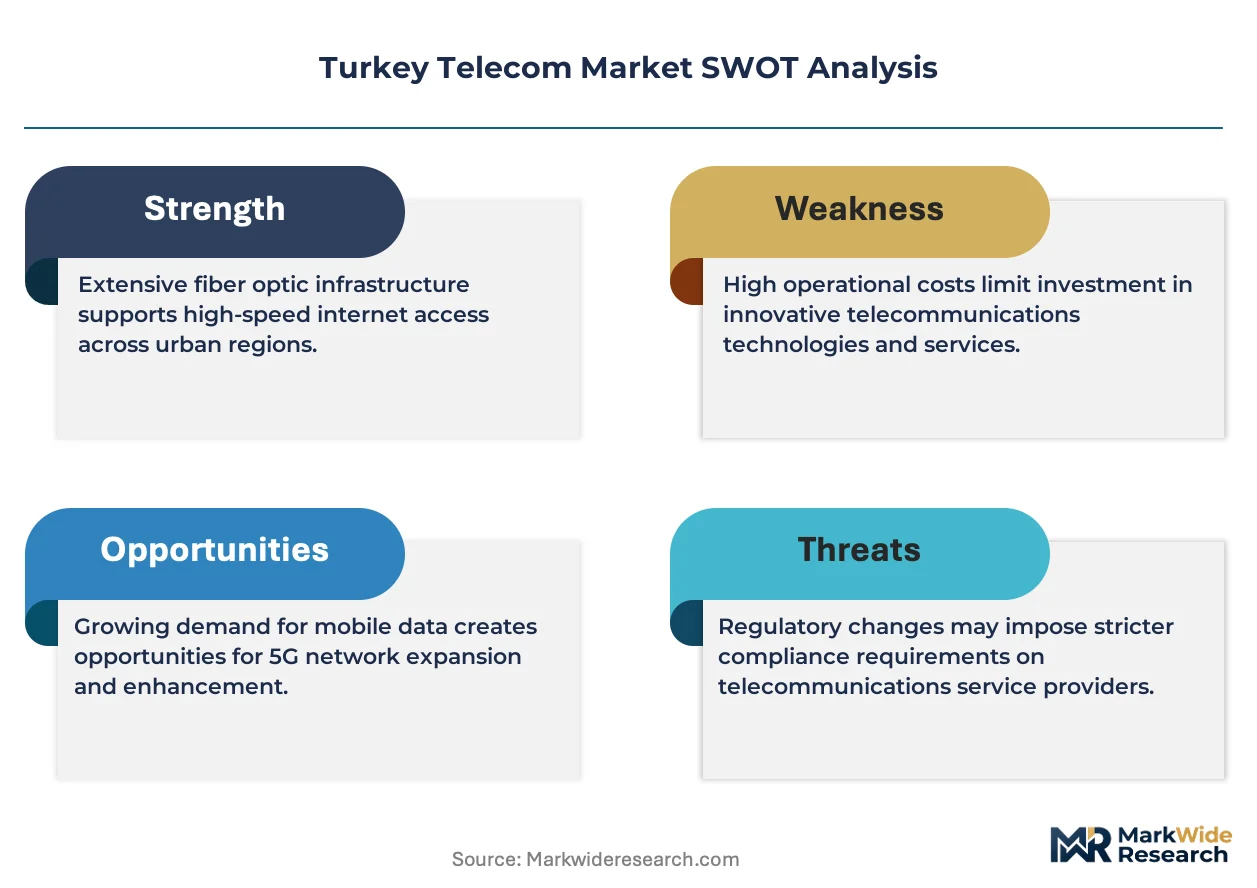
BTK licensing mandates shape spectrum allocation and interconnection tariffs, while the Personal Data Protection Authority (KVKK) imposes consent frameworks on customer data monetization. Turkey's alignment with EU CE marking for network equipment and GDPR-inspired KVKK provisions creates dual compliance obligations for imported infrastructure. Stakeholders must monitor BTK's pending 5G spectrum auction terms and KVKK enforcement precedents to calibrate capital deployment timelines against regulatory clarity.
Market Dynamics
BTK's pending 5G spectrum auction terms are compressing capital deployment timelines as operators delay infrastructure commitments pending regulatory clarity on license duration and coverage obligations.
Growth Catalysts
- Enterprise cloud connectivity:Turkish manufacturers are migrating production systems to hybrid cloud architectures, generating demand for low-latency fiber backhaul and edge computing nodes.
- BTK spectrum reforms:The regulator's streamlined licensing procedures for shared tower infrastructure are reducing barriers to rural network expansion.
- Ankara government-digitalization:Public-sector IT modernization mandates are creating anchor tenancy for secure data center and dedicated connectivity services.
Market Restraints
- Copper loop replacement capex:Aging last-mile infrastructure requires full fiber overbuild, straining operator balance sheets before revenue migration completes.
- Equipment import dependency:Network hardware sourced from concentrated East Asian supplier bases exposes procurement to currency volatility and logistics friction.
- KVKK consent frameworks:The Personal Data Protection Authority's strict customer data monetization rules limit targeted advertising revenue streams.
Strategic Opportunities
- Anatolia fiber underpenetration:Central and Eastern Anatolia provinces remain underserved by gigabit-capable fixed networks, offering first-mover expansion potential.
- Industrial IoT convergence:Integration of 5G radio access with private LTE networks is opening manufacturing campus deployments for system integrators.
- Smart city procurement frameworks:Istanbul Metropolitan Municipality's integrated sensor and connectivity tenders create bundled infrastructure opportunities.
Industry Challenges
- 5G RF engineering talent scarcity:Specialized skills for massive MIMO antenna configuration and network slicing remain concentrated among a limited pool of experienced engineers.
- Legacy billing system integration:Migration from prepaid-centric platforms to real-time charging for converged services requires complex middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Telecom Market |
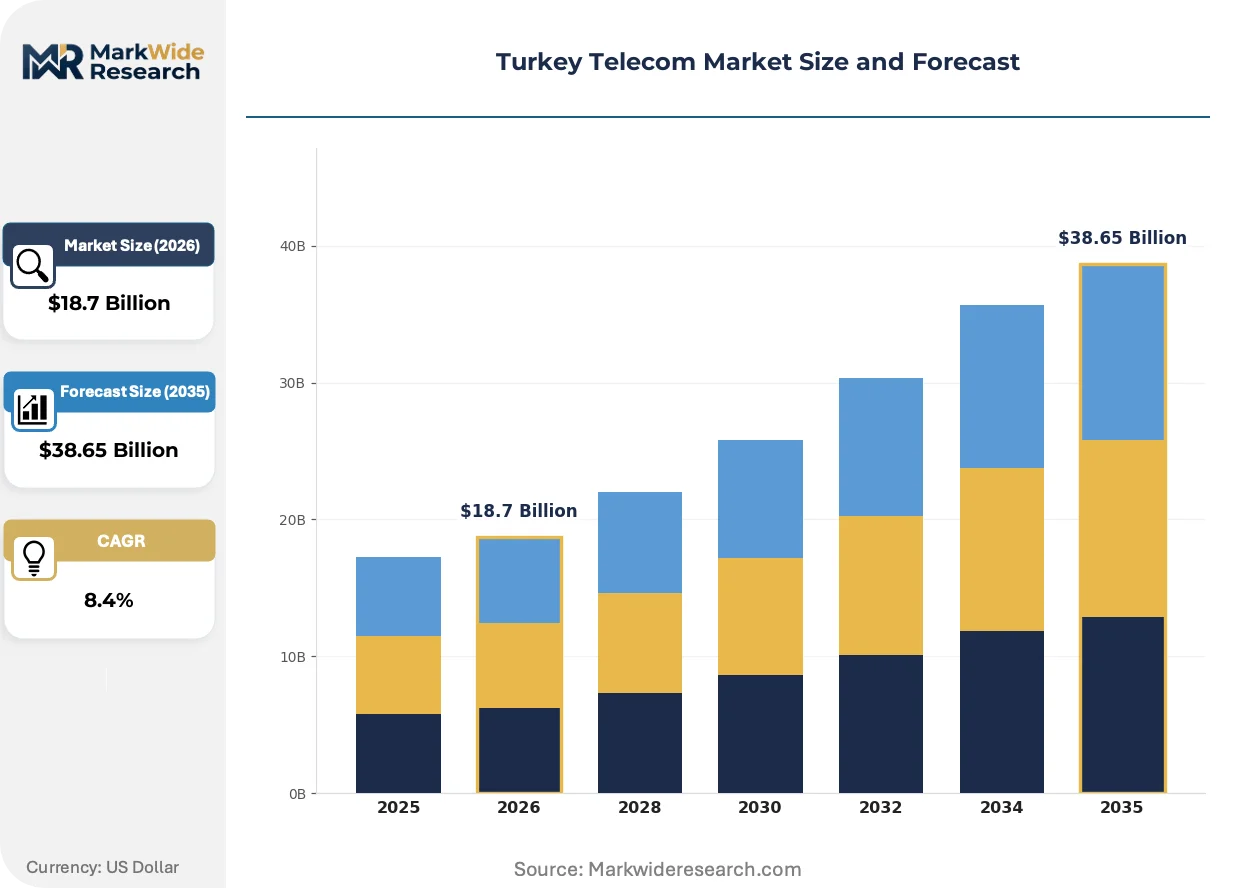
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Internet Services, Fixed-Line Services, Value-Added Services Technology: 4G LTE, 5G, Fiber Optic, Satellite Customer Type: Residential Customers, Small Businesses, Large Enterprises, Government Agencies Price Tier: Budget Plans, Mid-Range Plans, Premium Plans, Enterprise Plans |
| Companies Covered | Turkcell, Türk Telekom, Vodafone Turkey, Netgsm, Bimcell, TurkNet, Argela Technologies, Pocket eSIM, Lifemote Networks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Telecom Market Strategic Shifts
Open radio access network architectures are disrupting traditional vendor lock-in patterns across Turkish mobile infrastructure procurement. Operators now evaluate multi-vendor interoperability as a core specification criterion.
Virtualized baseband processing is rendering obsolete proprietary hardware-dependent RAN deployments. Turkcell and Vodafone Turkey are piloting containerized network functions in Istanbul testbeds. This shift is compressing equipment refresh cycles from seven-year hardware lifecycles to software-defined upgrade intervals.
BTK's alignment with EU CE marking for network equipment creates dual compliance obligations for imported infrastructure. The regulator's adoption of GDPR-inspired KVKK provisions extends data localization requirements to subscriber metadata. Equipment vendors must now certify against both Turkish type-approval and European conformity assessment frameworks.
Enterprise procurement patterns are consolidating around managed service contracts with guaranteed uptime SLAs. Manufacturing buyers in Bursa and Kocaeli industrial zones are unbundling connectivity from equipment ownership. This behavior is most visible among automotive suppliers seeking operational expenditure predictability for their digital transformation budgets.
Turkey Telecom Market Segmentation
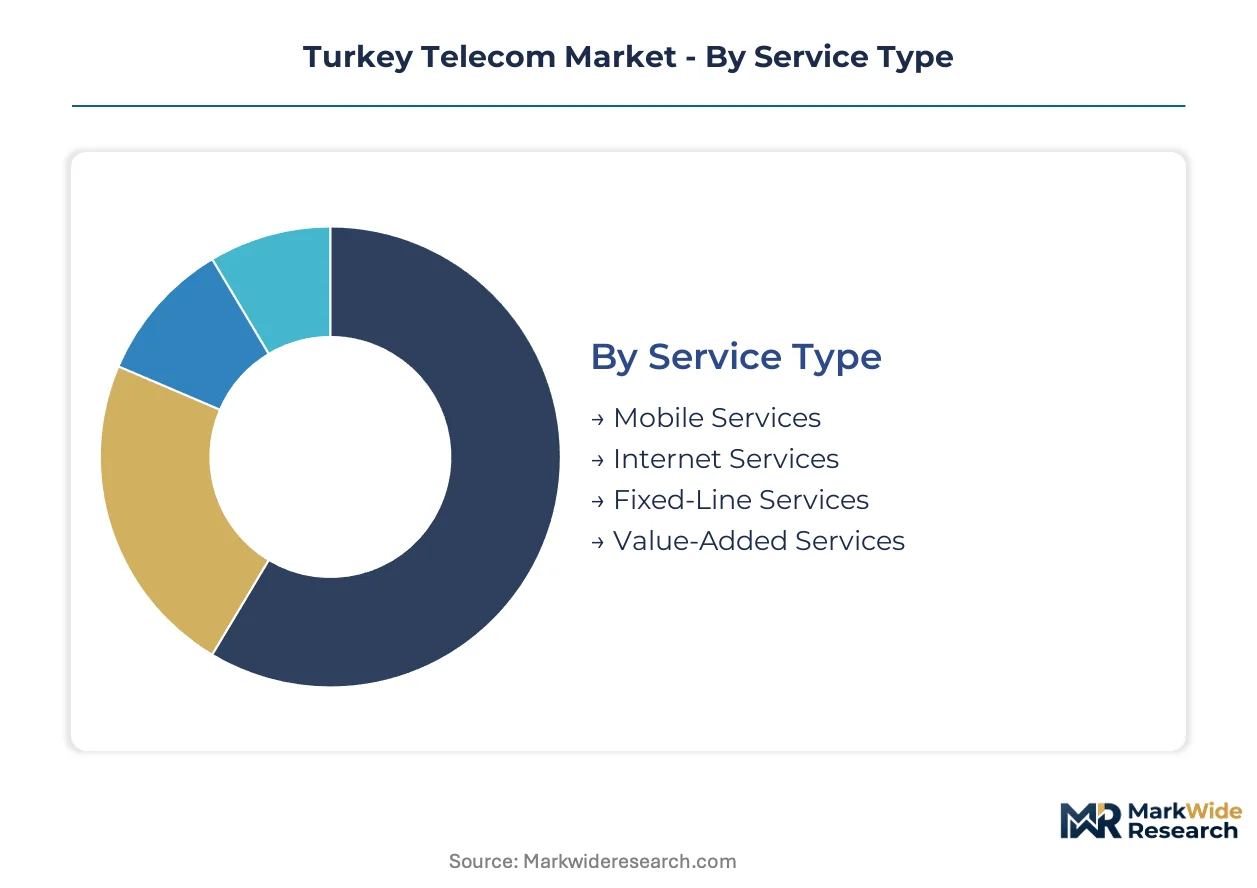
Segmentation in the Turkish telecom sector reveals distinct procurement patterns across customer tiers and infrastructure technologies. Understanding these divides enables operators to calibrate capital allocation between mass-market volume plays and high-margin enterprise contracts.
Service Type:
Use-case spectrum spans basic connectivity to complex managed services, with revenue concentration shifting from voice-centric legacy offerings toward data-intensive platforms.
- Mobile Services:Prepaid and postpaid cellular subscriptions dominate absolute subscriber volumes across Turkey's 85 million population. Istanbul's technology corridor and Ankara's government-digitalization cluster absorb disproportionate data traffic per capita.
- Internet Services:Fixed and mobile broadband subscriptions deliver the fastest-expanding revenue pool as fiber-to-the-home deployment accelerates in metropolitan zones. Copper loop replacement capex strains operator balance sheets before revenue migration from legacy DSL completes.
- Fixed-Line Services:Traditional PSTN voice connections continue declining as VoIP and mobile substitution erode the installed base. Rural Anatolia retains residual dependency for households beyond fiber buildout timelines.
- Value-Added Services:Cloud storage, cybersecurity bundles, and IoT platform access generate incremental ARPU from existing subscriber relationships. KVKK consent frameworks constrain targeted advertising revenue streams within this category.
The dominant share belongs to Mobile Services, while Internet Services is closing the gap fastest.
Technology:
Cost tier differentiation separates mature, depreciated networks from capital-intensive next-generation deployments requiring fresh spectrum and civil works investment.
- 4G LTE:Existing macro cell infrastructure provides nationwide coverage foundation using 800 MHz, 1800 MHz, and 2600 MHz bands. BTK spectrum reforms are streamlining licensing procedures for shared tower infrastructure to extend 4G reach into underserved provinces.
- 5G:Next-generation radio access networks operating in 3.5 GHz and pending mmWave allocations promise ultra-reliable low-latency connectivity. BTK's pending 5G spectrum auction terms are compressing capital deployment timelines as operators delay infrastructure commitments pending regulatory clarity.
- Fiber Optic:Single-mode cores rated for 10 Gbps and higher throughput anchor national backhaul capacity and last-mile gigabit services. Central and Eastern Anatolia provinces remain underserved, offering first-mover expansion potential.
- Satellite:Geostationary and emerging LEO constellations serve remote terrain where terrestrial fiber economics fail. Maritime and aviation mobility applications concentrate demand in coastal zones and Istanbul's air traffic corridor.
4G LTE holds the installed base advantage, though 5G commands the steepest expansion trajectory in forward capex planning.
Customer Type:
Volume concentration clusters in residential mass markets, while margin pools concentrate among institutional buyers with complex service requirements and contracted SLAs.
- Residential Customers:Individual households and family units generate highest absolute subscriber counts through prepaid mobile and bundled fixed-line packages. Price sensitivity dominates procurement behavior, with churn triggered by promotional undercutting.
- Small Businesses:Retail, hospitality, and professional services firms require reliable connectivity without dedicated network engineering staff. Managed WiFi and basic cloud backup attachments represent primary upsell opportunities.
- Large Enterprises:Manufacturing campuses in Bursa and Kocaeli industrial zones demand private LTE integration and guaranteed uptime SLAs. These buyers are unbundling connectivity from equipment ownership to achieve operational expenditure predictability.
- Government Agencies:Public-sector IT modernization mandates in Ankara create anchor tenancy for secure data center and dedicated connectivity services. Procurement runs through centralized frameworks with extended evaluation cycles.
Residential Customers absorb the volume lead, yet Large Enterprises are gaining share fastest as digital transformation budgets consolidate around managed service contracts.
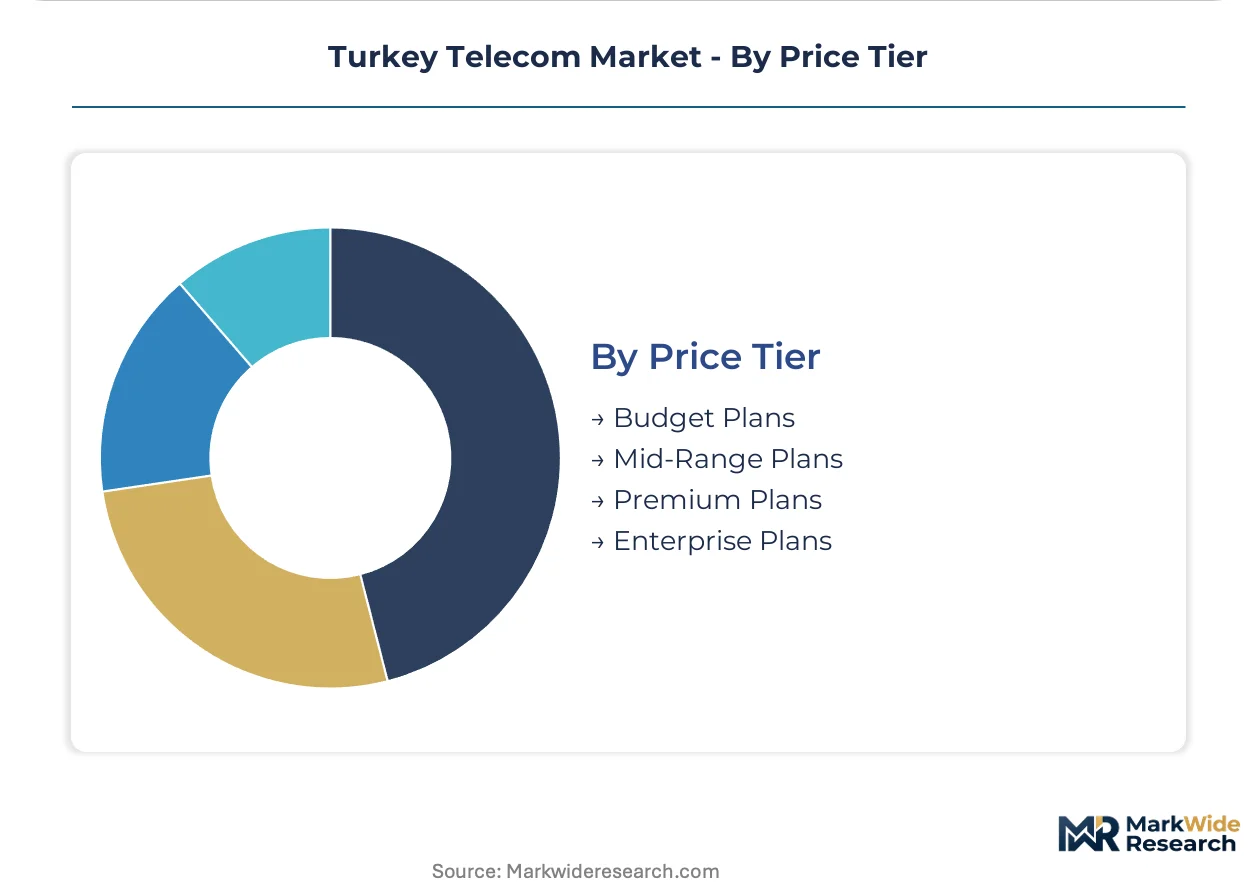
Price Tier:
Margin structure inversely correlates with subscriber scale, as premium positioning requires specialized engineering and account management resources that dilute at mass-market volumes.
- Budget Plans:Entry-level prepaid mobile and basic DSL offerings compete on absolute price point with minimal service differentiation. Subscriber acquisition costs dominate economics, with profitability hinging on network utilization efficiency.
- Mid-Range Plans:Standard postpaid mobile and fiber broadband bundles balance capacity allowances with moderate value-added inclusions. This tier captures the median Turkish household's willingness-to-pay for reliable connectivity.
- Premium Plans:High-data mobile allowances, symmetric gigabit fiber, and priority customer support target affluent urban demographics. Istanbul's technology corridor shows highest penetration of premium positioning.
- Enterprise Plans:Custom-contracted connectivity with guaranteed SLAs, dedicated account management, and managed security attachments command the most attractive margin pools. Long-term contract structures provide revenue visibility across multi-year horizons.
Budget Plans retain the subscriber count advantage, while Enterprise Plans are climbing the fastest in revenue contribution per connection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BTK's spectrum reforms and state-linked infrastructure concessions are redistributing capital deployment across Turkey's provincial map. Regional divergence between Istanbul's saturated technology corridor and Anatolia's underserved provinces shapes operator expansion priorities.
Istanbul Technology Corridor
Enterprise cloud connectivity from Turkish manufacturers and smart city procurement from the Metropolitan Municipality concentrate demand in this zone. BTK's streamlined licensing for shared tower infrastructure accelerates 5G testbed deployments. The corridor absorbs disproportionate data traffic per capita while fiber overbuild nears completion.
Ankara Government-Digitalization Cluster
Public-sector IT modernization mandates generate anchor tenancy for secure data centers and dedicated connectivity services. KVKK data localization requirements shape procurement frameworks for government agencies. Centralized evaluation cycles extend contract timelines but provide multi-year revenue visibility for compliant operators.
Bursa-Kocaeli Industrial Zone
Automotive suppliers and manufacturing campuses drive private LTE integration and industrial IoT convergence demand. Enterprise buyers here unbundle connectivity from equipment ownership to achieve operational expenditure predictability. Copper loop replacement capex strains balance sheets before fiber revenue migration completes.
Central Anatolia
Provinces in this sub-region remain underserved by gigabit-capable fixed networks despite accelerating fiber-to-the-home deployment timelines. BTK's pending 5G spectrum auction terms compress infrastructure commitments pending regulatory clarity on rural coverage obligations. First-mover expansion potential exists for operators willing to absorb upfront civil works investment.
Eastern Anatolia
Geographic constraints and lower population density delay terrestrial fiber economics, leaving satellite and fixed wireless access as interim solutions. Equipment import dependency from East Asian supplier bases exposes procurement to currency volatility in this capital-constrained zone. Shared tower infrastructure reforms aim to reduce competitive barriers to network expansion.
Turkey Telecom Market Competitive Environment
On the supply side, the industry is consolidating around integrated mobile-fixed network footprints and state-linked concession structures. Turkcell leverages its Anatolia-wide coverage to sustain pricing power, while Türk Telekom anchors national fiber backhaul through state concessions. Vodafone Turkey competes on multinational procurement scale. Strategic archetypes include integrated incumbents with legacy infrastructure, state-linked fixed-line operators, and multinational mobile subsidiaries. Dominant competitive moves involve fiber overbuild acceleration and shared tower infrastructure partnerships to defray rural deployment costs.
Within the integrated incumbent tier, Turkcell occupies a position exemplifying mobile-fixed convergence across provincial markets. Among state-linked operators, Türk Telekom represents the archetype of concession-anchored fiber dominance. Vodafone Turkey sits within the multinational subsidiary tier, importing equipment standards from European parent operations.
| Leading Market Players |
|---|
| Turkcell |
| Türk Telekom |
| Vodafone Turkey |
| Netgsm |
| Bimcell |
| TurkNet |
| Argela Technologies |
| Pocket eSIM |
| Lifemote Networks |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in 5G RF engineering talent across Istanbul's technology corridor drives both supplier premium pricing and operator wage inflation. Equipment vendors extract margin from this scarcity while Turkcell, Türk Telekom, and Vodafone Turkey absorb higher deployment costs. BTK's pending spectrum auction terms compound uncertainty, freezing long-term contract pricing until license duration clarity emerges.
Pricing Analysis
Certification level (BTK type-approval plus EU CE marking) creates the primary spread between premium network equipment and standard-tier alternatives. Pricing stratifies across enterprise-grade managed services, mid-range fiber broadband bundles, and budget prepaid mobile tiers. Cost compression in budget prepaid segments is intensifying because subscriber acquisition economics hinge on network utilization efficiency rather than ARPU expansion. Residential households in Central Anatolia exhibit highest price sensitivity, while manufacturing campuses in Bursa-Kocaeli demonstrate lowest sensitivity due to operational expenditure predictability requirements.
Supply Chain Analysis
Extended payment terms from East Asian equipment suppliers now stretch to 180 days for Turkish operators facing currency volatility. Network hardware concentrates in China, South Korea, and Taiwan, with single-mode fiber cores and massive MIMO antenna arrays drawing from these manufacturing bases. Logistics friction through the Suez Canal corridor and lira-dollar exchange rate swings constitute the dominant supply chain risk. Distribution runs through Türk Telekom's state-linked concession infrastructure for fiber backhaul, while mobile equipment flows via multinational procurement channels anchored to Vodafone Turkey's European parent operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized skills for network slicing and containerized baseband processing remain concentrated among fewer than 200 experienced engineers across Turkey. This capability scarcity constrains 5G deployment velocity and inflates compensation costs for all operators.
For Market Incumbents: Pre-empt emerging Open RAN vendor entrants by accelerating multi-vendor interoperability pilots in Istanbul testbeds. Lock in exclusive tower-sharing partnerships with passive infrastructure funds before BTK's shared licensing reforms mature. Defensive consolidation through backward integration into edge computing node deployment protects margin pools against cloud hyperscaler encroachment. For New Entrants and Emerging Players: Eastern Anatolia's fixed wireless access gap offers first-mover terrain where terrestrial fiber economics fail. Target satellite-LEO convergence for maritime and aviation mobility corridors along Turkey's coastal zones. Go-to-market through industrial IoT system integration partnerships with automotive suppliers seeking private LTE campus deployments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across 5G radio access infrastructure as software-defined refresh cycles compress hardware lifecycles. Long-term viability favors operators with state-linked concession structures providing fiber backhaul anchors. Acquisition target archetype: mid-tier fiber overbuilders with Anatolia footprint and BTK compliance certification. Watch BTK's 5G spectrum auction terms as the inflection signal for capex commitment waves.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Multi-Vendor Integration | Disrupts traditional vendor lock-in patterns across Turkish mobile infrastructure procurement specifications. |
| Fiber-to-the-Home Acceleration | Replaces aging copper loops in Central Anatolia provinces before revenue migration completes. |
| Shared Tower Infrastructure Partnership | Defrays rural deployment costs under BTK's streamlined licensing procedures for passive infrastructure. |
| Edge Computing Node Deployment | Captures low-latency demand from Turkish manufacturers migrating production systems to hybrid cloud. |
| Enterprise Managed Service Consolidation | Secures long-term contracts with guaranteed uptime SLAs from Ankara government-digitalization mandates. |
Study Parameters
A standing panel of network engineering directors, BTK regulatory affairs specialists, and enterprise IT procurement managers provided ongoing calibration against market developments. Primary fieldwork combined structured interviews with these stakeholders and secondary validation through BTK spectrum allocation filings, operator capex disclosures, and KVKK enforcement precedent databases. Bottom-up subscriber and infrastructure tallies triangulated against top-down revenue estimates from disclosed financial statements.
Scenario-bracketing around BTK's pending 5G auction terms and KVKK data localization enforcement intensity framed the projection horizon. Segmentation dimensions modeled include service type, technology tier, customer archetype, and price positioning across the analysis window. CAGRs derived from historical capex trajectories and forward contract visibility, with fiber deployment timelines and enterprise cloud adoption curves as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Open RAN specialist vendors or hyperscaler edge entrants would shift outcomes. Macroeconomic lira volatility, BTK regulatory deviation, or 5G equipment supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Sri Lanka Telecom Tower Market
Telecommunications
C-RAN Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
Ghana Telecom Market
Telecommunications
Portable Base Station (PBS) Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Philippines Telecom Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
Carrier Aggregation Solutions Market
Telecommunications
Cloud PBX Market
Telecommunications
Argentina ICT Market
Telecommunications
Finland Telecom Market
Telecommunications
5G in Defense Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Promotional Sms Market