
 China ICT Market | 2026-2036
China ICT Market Size, Share, and Industry Trends Forecast 2026-2036
China ICT Market Analysis
Market Context
China is rewriting the competitive map for information and communications technology through massive domestic semiconductor fabrication capacity expansion in Jiangsu and Hubei provinces. Huawei Technologies anchors national 5G infrastructure deployment with captive chip design capabilities that sustain supply chain resilience under export controls. Alibaba Group dominates cloud services through vertically integrated data center operations across Zhangjiakou and Heyuan. ByteDance leverages AI inference infrastructure to power content recommendation engines at continental scale.
Technical Definition and Structural Segments
Information and communications technology encompasses electronic systems, software protocols, and network infrastructure enabling data capture, transmission, processing, and storage across enterprise and consumer environments, with 5G base stations requiring sub-6 GHz and millimeter-wave spectrum allocation for latency-sensitive industrial automation. Software and services capture the dominant margin pool as enterprises shift from capital-intensive hardware procurement to subscription-based cloud platforms, while AI and IoT represent the fastest-expanding technology layers as manufacturers deploy computer vision for quality inspection and sensor networks for predictive maintenance in Shandong and Guangdong factory clusters. Hardware retains structural importance in government and defense verticals where on-premises deployment mandates prevail under data sovereignty requirements.
Regulatory Framework and Outlook
MIIT governs telecommunications licensing and spectrum allocation, while SAMR enforces anti-monopoly provisions that constrain platform concentration in cloud and e-commerce segments, and GB standards mandate interoperability testing for network equipment procurement. NMPA-aligned cybersecurity review procedures for critical information infrastructure operators create compliance thresholds that favor domestic vendors with established certification pathways. Stakeholders must monitor evolving data localization requirements and cross-border transfer rules that determine architectural choices between on-premises, hybrid, and managed deployment models.
Market Dynamics
State-directed capital allocation through MIIT's 5G deployment mandates and dual carbon goals is compressing procurement cycles for data center operators while forcing rapid enterprise cloud migration across manufacturing hubs.
Growth Catalysts
- MIIT Spectrum Mandates:Accelerated 5G base station rollouts in sub-6 GHz and millimeter-wave bands enable latency-sensitive industrial automation in Jiangsu factory clusters.
- Carbon-Neutral Data Centers:Dual carbon goals rewire energy procurement standards, driving replacement demand for liquid-cooled server infrastructure in Zhangjiakou and Heyuan facilities.
- Yangtze River Delta Concentration:Shanghai-Hangzhou-Suzhou corridor generates dense enterprise demand for hybrid cloud architectures and edge computing nodes.
Market Restraints
- Advanced Lithography Bottleneck:Extreme ultraviolet equipment import restrictions constrain domestic 7nm and below semiconductor fabrication capacity expansion in Hubei and Jiangsu.
- Polysilicon Supply Concentration:Xinjiang-based polysilicon refining dominates solar-grade material for data center renewable energy procurement, creating single-source vulnerability.
- GB Standards Friction:Mandatory interoperability testing for network equipment extends certification timelines and favors incumbent vendors with established testing relationships.
Strategic Opportunities
- Western Region Data Center Buildout:Guizhou and Inner Mongolia offer cool climates and abundant renewable energy for hyperscale facility deployment under east-data-west-computing policy.
- AI Inference at Edge:Convergence of 5G radio units with GPU-accelerated edge servers creates new deployment category for smart manufacturing quality inspection.
- SAMR Cloud Antitrust Remedies:Regulatory pressure on platform concentration opens procurement windows for second-tier domestic cloud providers in state-owned enterprise verticals.
Industry Challenges
- Compound Semiconductor Talent Gap:Shortage of silicon carbide and gallium nitride process engineers constrains power electronics localization for 5G base station amplifiers.
- Legacy ERP Integration Complexity:State-owned manufacturers struggle to interface cloud-native manufacturing execution systems with decades-old on-premises resource planning databases.
- Cross-Border Data Transfer Certification:NMPA-aligned security review procedures for critical information infrastructure create unpredictable approval timelines for multinational enterprise deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China ICT Market |
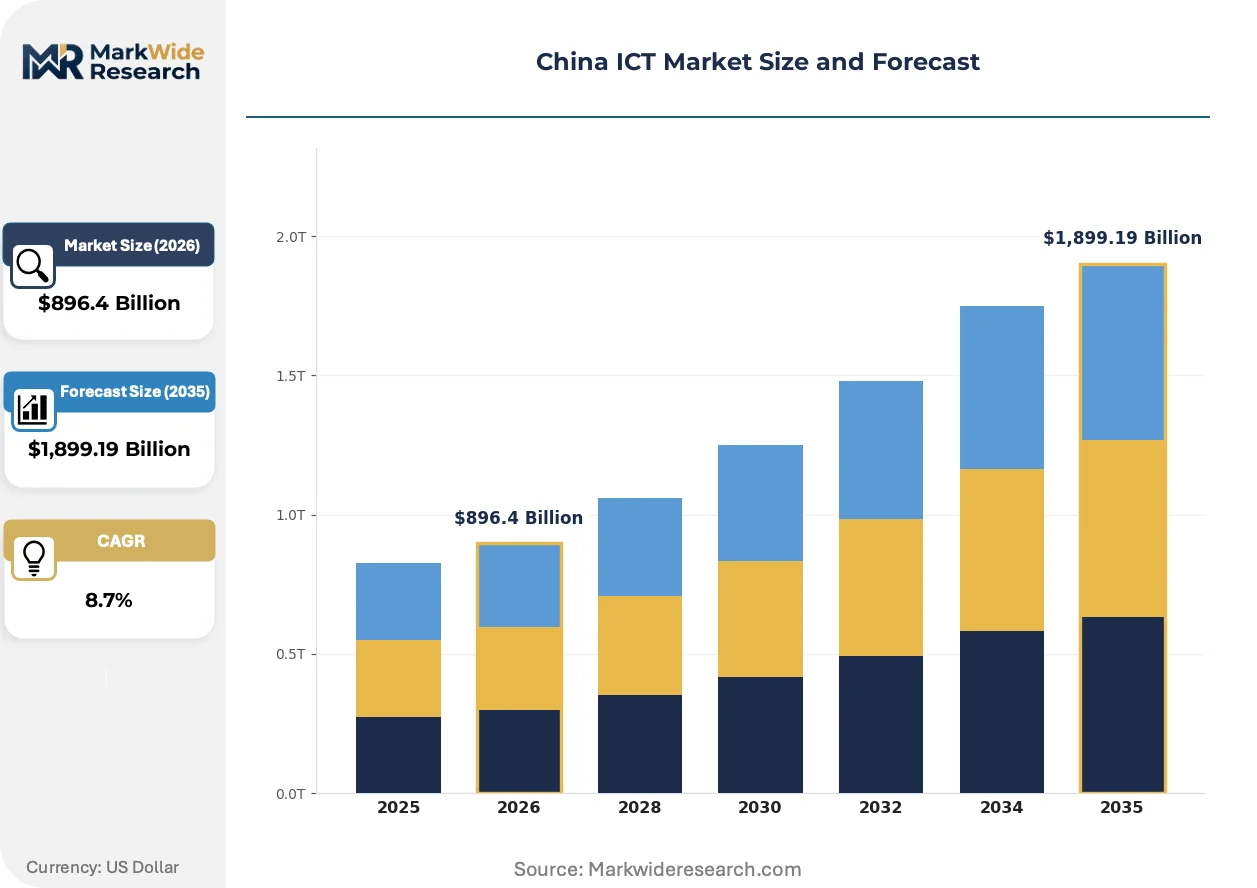
| Market Size in 2026 | $896.4 Billion |
| Market Size in 2035 | $1,899.19 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Networking, Services Technology: 5G, Cloud Computing, AI, IoT End User: Government, Education, Healthcare, BFSI Deployment: On-Premises, Cloud-Based, Hybrid, Managed |
| Companies Covered | Baidu, ByteDance, Tencent Holdings, NetEase, JD.com, Alibaba Group, Xiaomi, Meituan, Huawei Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China ICT Market Emerging Trajectories
Silicon-to-software architectural convergence is collapsing traditional hardware procurement cycles while regulatory pressure on carbon intensity forces infrastructure redesign across compute, network, and storage layers.
Silicon photonics interconnect technology replaces copper cabling between server racks and optical transport layers. Hyperscale operators in Zhangjiakou and Ulanqab deploy co-packaged optics to cut data center power consumption. This photonic integration is rendering obsolete discrete optical transceiver modules and their associated thermal management overhead.
MIIT's revised telecommunications licensing framework tightens energy efficiency thresholds for 5G base station procurement. Equipment vendors must demonstrate sub-1.5 kW per cell average power consumption to qualify for state-backed deployment subsidies. Northern province operators respond by prioritizing liquid-cooled macro base stations over traditional air-cooled architectures.
Subscription-based infrastructure-as-a-service contracts displace capital-intensive hardware ownership among mid-market manufacturers. Shandong and Guangdong factory clusters now procure compute and storage capacity through three-year operational expenditure agreements rather than five-year depreciation schedules. This financing rotation concentrates purchasing influence with cloud platform providers possessing balance sheet depth for asset-heavy deployment models.
China ICT Market Segmentation
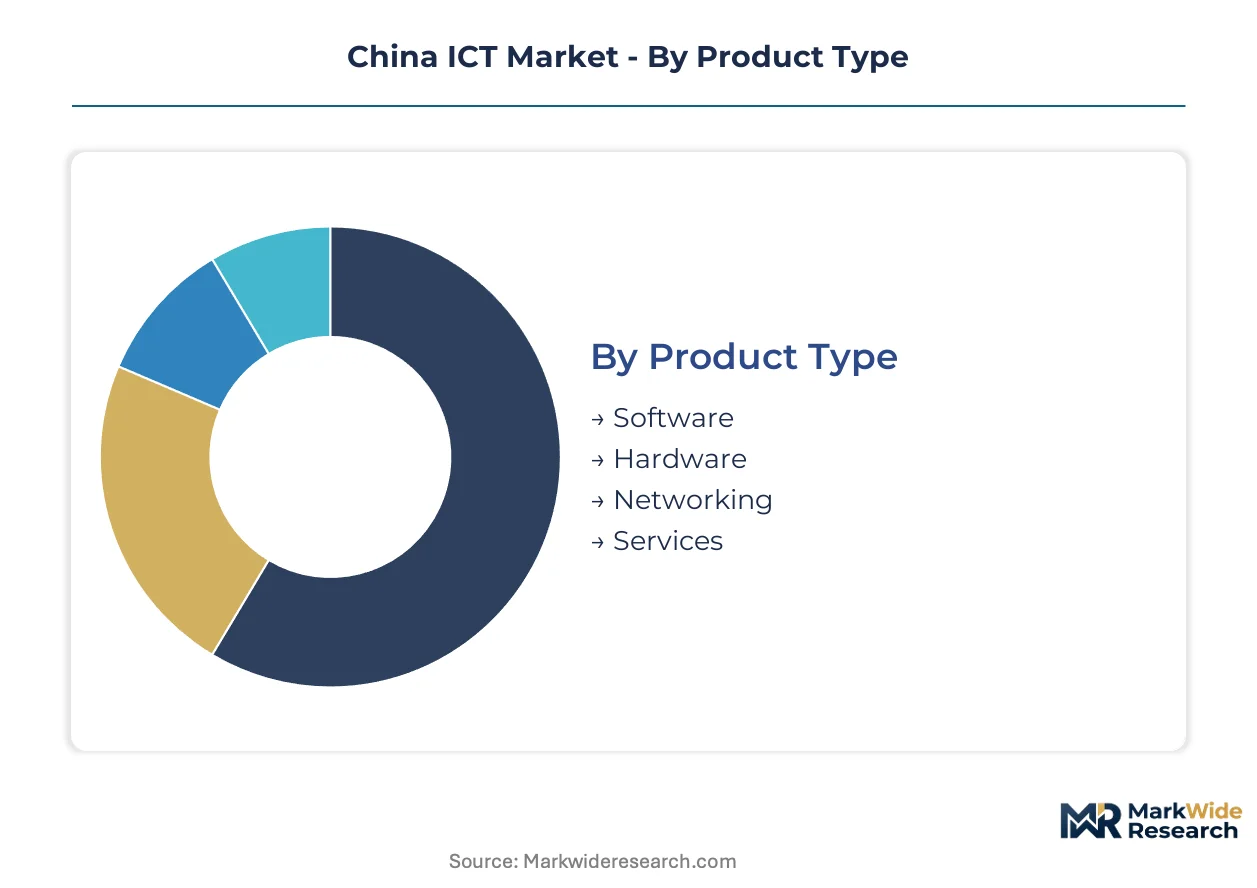
Segmentation in China's ICT market reveals divergent procurement rhythms across product categories, with subscription software refreshing annually while networking hardware cycles extend to seven years. Understanding these temporal patterns enables vendors to align R&D pipelines and inventory strategies with actual customer replacement behavior.
Product Type:
Software contracts renew fastest at 12-18 month cycles, while networking equipment turns slowest due to MIIT certification timelines and physical infrastructure longevity.
- Software:Cloud-native applications and enterprise resource planning platforms deploy through subscription licensing that compresses sales cycles. Jiangsu manufacturing clusters drive demand for manufacturing execution systems that interface with legacy equipment.
- Hardware:Servers, storage arrays, and client devices require capital approval processes that stretch procurement to 24-36 months. State-owned enterprises dominate volume through centralized purchasing frameworks.
- Networking:Routers, switches, and optical transport equipment operate on 5-7 year depreciation schedules tied to GB standards compliance windows.
- Services:Systems integration and managed support contracts span multi-year engagements with renewal rates concentrated in Q4 fiscal planning cycles.
Hardware anchors the volume base while software gains share at the steepest rate.
Technology:
Cost tier differentiation separates capital-intensive infrastructure layers from operational expenditure models that dominate enterprise budgeting.
- 5G:Sub-6 GHz and millimeter-wave base station deployment absorbs the largest infrastructure capital allocation under MIIT mandates. Yangtze River Delta corridor concentrates demand for industrial automation use cases.
- Cloud Computing:Public and private cloud platforms generate recurring revenue streams through reserved instance commitments. Zhangjiakou and Heyuan hyperscale facilities supply compute capacity to Beijing and Shanghai enterprises.
- AI:Training clusters and inference accelerators command premium pricing for computer vision and natural language processing workloads.
- IoT:Sensor networks and edge gateways deploy at volume scale for predictive maintenance in Shandong factory clusters.
5G infrastructure captures the dominant capital share while AI climbs fastest as enterprises prioritize intelligent automation.
End User:
Application urgency varies sharply across verticals, with government procurement frozen during political transition periods while healthcare digitization proceeds regardless of cycle.
- Government:National and provincial agencies drive demand for secure on-premises infrastructure under data sovereignty mandates. Dual carbon goals accelerate smart city sensor network deployment.
- Healthcare:Hospital digitization and telemedicine platforms expand regardless of budget cycles due to patient care imperatives and NMPA-aligned cybersecurity requirements.
- Education:K-12 and university procurement concentrates in summer installation windows with funding tied to annual fiscal appropriations.
- BFSI:Banking, financial services, and insurance verticals prioritize hybrid architectures that balance latency-sensitive trading systems with cloud-native customer channels.
Government procurement anchors the volume base while healthcare expands most quickly amid universal coverage digitization.
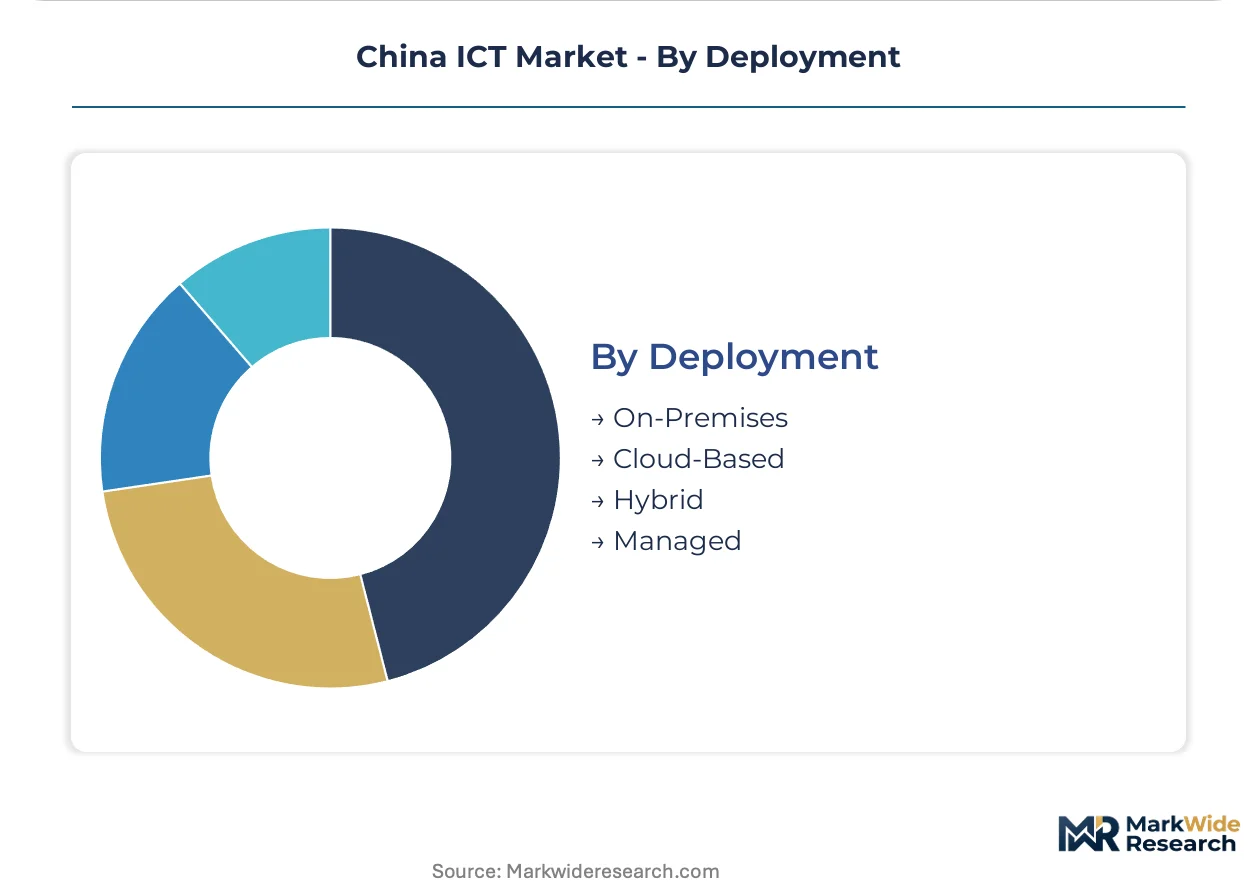
Deployment:
Customer type stratification separates state-owned enterprises with captive IT departments from mid-market manufacturers outsourcing infrastructure management entirely.
- On-Premises:Physical data center ownership persists in defense and critical infrastructure sectors where GB standards mandate air-gapped environments. Jiangsu and Hubei provinces concentrate server manufacturing that supplies these deployments.
- Cloud-Based:Public cloud consumption dominates among internet-native enterprises and export-oriented manufacturers seeking elastic capacity. Alibaba and Huawei clouds compete for enterprise workload migration.
- Hybrid:Split architectures allow sensitive data retention on-premises while bursting compute-intensive workloads to cloud regions. State-owned manufacturers favor this model for ERP integration.
- Managed:Third-party operation of infrastructure shifts talent requirements to service providers, appealing to mid-market manufacturers in Guangdong lacking internal cloud expertise.
On-premises deployment anchors legacy volume while cloud-based models gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Chinese provinces diverge sharply, with coastal manufacturing hubs prioritizing cloud-native architectures while western regions absorb hyperscale data center buildouts under east-data-west-computing policy directives.
Yangtze River Delta
Shanghai, Hangzhou, and Suzhou generate dense enterprise demand for hybrid cloud architectures and AI inference infrastructure. MIIT's 5G deployment mandates accelerate sub-6 GHz base station rollouts across Jiangsu factory clusters. Suzhou industrial parks deploy computer vision systems for quality inspection at continental scale.
Pearl River Delta
Shenzhen and Guangzhou anchor semiconductor packaging and consumer electronics manufacturing that drives IoT sensor network procurement. SAMR anti-monopoly enforcement constrains platform concentration in cloud services. Dongguan factory clusters adopt subscription-based manufacturing execution systems through three-year operational expenditure agreements.
Beijing-Tianjin-Hebei
State-owned enterprises and defense contractors sustain demand for on-premises infrastructure under data sovereignty requirements. NMPA-aligned cybersecurity review procedures create compliance thresholds favoring domestic vendors. Zhangjiakou hyperscale facilities supply compute capacity to Beijing enterprises through renewable-powered data centers.
Sichuan-Chongqing
Western computing hubs exploit cool climates and abundant hydropower for carbon-neutral data center operations. Dual carbon goals rewire energy procurement standards for liquid-cooled server infrastructure. Chongqing car manufacturers deploy edge computing nodes for predictive maintenance on assembly lines.
Western China
Guizhou and Inner Mongolia host hyperscale facilities under east-data-west-computing policy that migrates computational workloads from coastal demand centers. GB standards mandate interoperability testing for network equipment procurement. Ulanqab operators deploy silicon photonics interconnect technology to cut power consumption between server racks.
China ICT Market Vendor Landscape
Capability concentration sits with vertically integrated technology conglomerates; scale advantage sits with platform-native enterprises possessing balance sheet depth for asset-heavy deployment models. The vendor base stratifies across three tiers: state-affiliated infrastructure providers, internet-native cloud platforms, and specialized component suppliers. Dominant competitive moves include backward integration into captive semiconductor fabrication and strategic partnerships with provincial governments for data center land and power allocation.
Among technology conglomerates, Huawei Technologies and Alibaba Group exemplify the vertically integrated archetype with in-house chip design and hyperscale facility operations. ByteDance occupies a position within the AI-native tier, leveraging inference infrastructure for content recommendation at scale. These three anchors represent divergent strategic postures: infrastructure-centric supply chain control, platform-centric ecosystem lock-in, and application-centric compute optimization.
| Leading Market Players |
|---|
| Baidu |
| ByteDance |
| Tencent Holdings |
| NetEase |
| JD.com |
| Alibaba Group |
| Xiaomi |
| Meituan |
| Huawei Technologies |
| Others |
Supply Flow & Price Mechanics
Xinjiang polysilicon refining concentration for solar-grade material anchors renewable energy procurement costs for Zhangjiakou and Heyuan data center operators, compressing margin pools at the hyperscale facility tier while amplifying pricing power for domestic ingot suppliers.
Pricing Analysis
Long-term offtake contracts for liquid-cooled server infrastructure dominate procurement between state-owned manufacturers and domestic OEMs, locking in volume commitments across three-year depreciation windows. Price differentiation rests on GB standards certification tier and liquid cooling efficiency ratings, with MIIT-mandated sub-1.5 kW per cell consumption thresholds acting as gatekeepers for subsidy eligibility. Cost compression in networking equipment is intensifying because SAMR cloud antitrust remedies fragment platform concentration and open second-tier vendor procurement windows. Mid-market manufacturers in Shandong and Guangdong exhibit highest price sensitivity, while defense contractors absorbing on-premises infrastructure under data sovereignty mandates show least.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier financing arrangements between Jiangsu server manufacturers and downstream systems integrators, straining working capital across component tiers. Taiwan, South Korea, and the USA concentrate advanced lithography equipment and high-bandwidth memory supply, while domestic Hubei and Jiangsu fabrication draws from captive polysilicon, rare earth magnet, and silicon carbide substrate sources. Single-source vulnerability in extreme ultraviolet equipment imports under export controls threatens 7nm and below capacity expansion. Distribution runs through provincial government land allocation partnerships for data center power and site access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China ICT sits in early-cycle expansion as MIIT 5G deployment mandates and dual carbon goals force replacement demand across manufacturing hub infrastructure before saturation in coastal enterprise cloud penetration.
For Market Incumbents: Harden supply chain resilience through backward integration into captive semiconductor fabrication capacity in Hubei and Jiangsu, insulating against extreme ultraviolet equipment import restrictions. Fortify certification pathways with NMPA-aligned cybersecurity review procedures to maintain procurement preference under critical information infrastructure operator mandates. Prioritize liquid-cooled server R&D investment to capture dual carbon goal-driven replacement cycles in Zhangjiakou and Heyuan facilities. For New Entrants and Emerging Players: Western region data center buildout in Guizhou and Inner Mongolia under east-data-west-computing policy represents the most penetrable entry point, exploiting cool climates and abundant renewable energy for carbon-neutral hyperscale deployment. AI inference at edge convergence with 5G radio units creates unclaimed deployment category for smart manufacturing quality inspection. Pursue provincial government partnerships for land and power allocation as primary go-to-market mechanism. For Investors and Strategic Acquirers: Capital is best deployed toward compound semiconductor specialists possessing silicon carbide and gallium nitride process engineering capabilities, as talent scarcity constrains power electronics localization for 5G base station amplifiers. Long-term viability hinges on positioning for state-backed digital infrastructure program continuity across the next decade. Monitor MIIT spectrum allocation announcements for millimeter-wave band expansion as inflection indicator for industrial automation infrastructure spend acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Chip Design | Huawei Technologies sustains supply chain resilience under export controls through in-house semiconductor fabrication. |
| Provincial Government Data Center Partnership | Alibaba Group secures renewable-powered land and power allocation for Zhangjiakou hyperscale facility expansion. |
| GB Standards Certification Investment | Domestic vendors accelerate network equipment procurement timelines through established MIIT interoperability testing relationships. |
| AI Inference Infrastructure Deployment | ByteDance optimizes content recommendation engines through GPU-accelerated edge server convergence with 5G radio units. |
| Liquid-Cooled Server Architecture Transition | Hyperscale operators in Ulanqab cut power consumption through silicon photonics interconnect technology deployment. |
Methodological Framework
A spread of perspectives from MIIT policy officials, data center procurement directors at state-owned enterprises, cloud platform engineers at hyperscale operators, and compound semiconductor process engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against MIIT 5G deployment filings, SAMR anti-monopoly enforcement records, GB standards certification databases, and provincial government data center land allocation disclosures. Bottom-up enterprise demand modeling and top-down infrastructure investment flow analysis triangulated volume estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across product type, technology layer, end-use vertical, and deployment architecture dimensions. CAGRs derived from replacement cycle analysis for networking hardware against software subscription renewal patterns, incorporating MIIT spectrum mandate timelines and dual carbon goal compliance windows as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in state-directed capital allocation intensity or export control regime stringency would shift the trajectory. Forecasts reflect documented assumptions about provincial government procurement continuity and NMPA-aligned cybersecurity review procedure stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Smart Feature Phone Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
DECT System Market
Telecommunications
Kenya Telecom Market
Telecommunications
Indonesia ICT Market
Telecommunications
North America Telecom Expense Management Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Angola Telecom Market
Telecommunications
South Korea Telecom Market
Telecommunications
Fixed LTE Market
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Optical Fronthaul Market
Telecommunications
Germany Critical Communication Market