
 Ireland Telecom Market | 2026-2036
Ireland Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Ireland Telecom Market Insights
Copper decommissioning is recalibrating last-mile economics across Irish networks. Eir leverages its legacy infrastructure footprint to accelerate fiber-over-copper migration. Vodafone Ireland anchors enterprise-grade 5G standalone services for financial services clients in Dublin. Three Ireland competes aggressively on mobile data allowances to capture residential switching demand.
Ireland telecom encompasses voice, data, and internet services delivered through wireless and wireline infrastructure operating across licensed spectrum and fiber-optic cable networks with throughput parameters ranging from 100 Mbps residential fiber to 10 Gbps enterprise leased lines, serving consumer connectivity, business productivity, and public administration functions. Mobile data and fiber broadband lead structural expansion as consumers abandon fixed voice and DSL legacy platforms. Enterprise price tiers concentrate margin pools where SIRO and Virgin Media Ireland specialize in symmetrical gigabit services for technology and pharmaceutical campuses.
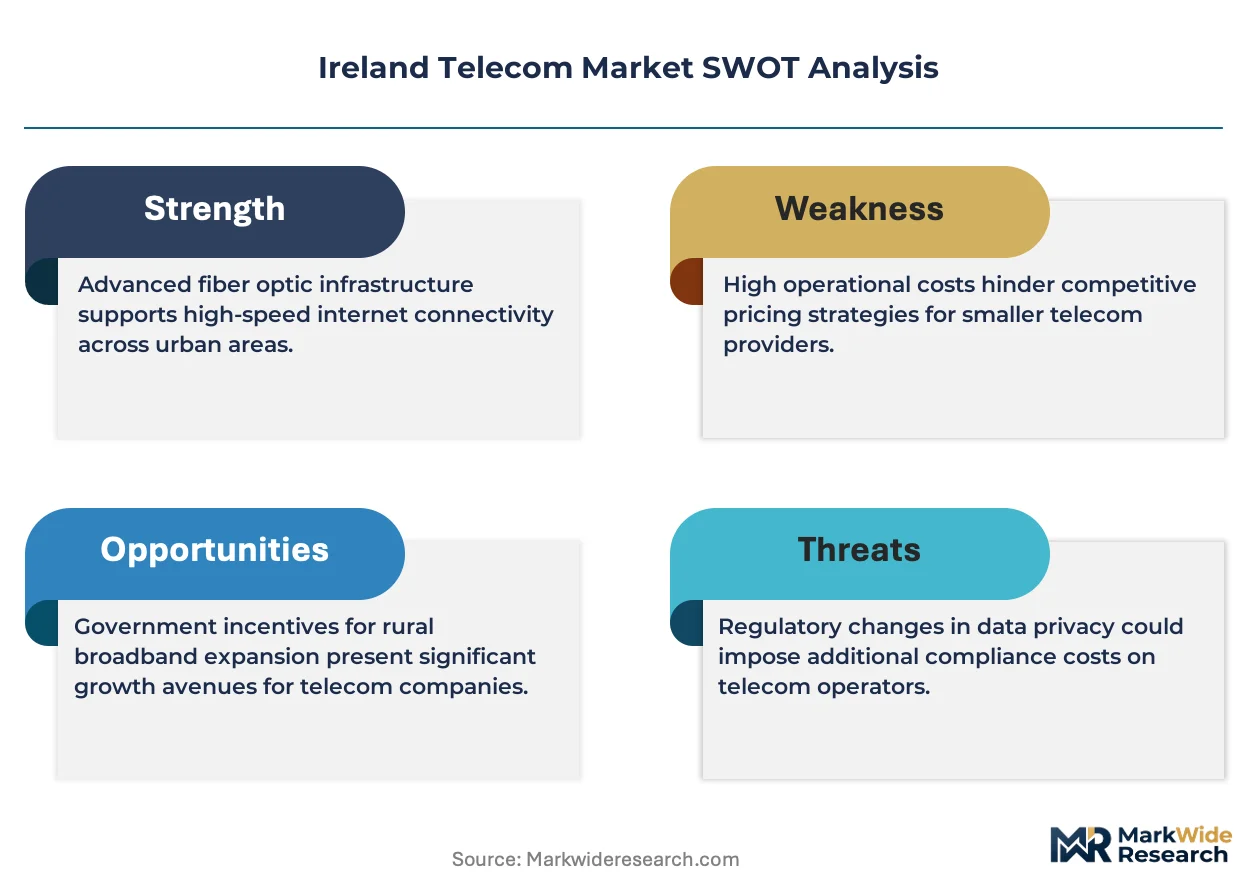
ComReg governs spectrum allocation and wholesale access pricing under EU Electronic Communications Code transposition, while the National Broadband Ireland state intervention model dictates rural fiber deployment timelines and competitive dynamics in underserved counties. GDPR and EU Cybersecurity Act compliance requirements shape enterprise procurement specifications for managed security and data sovereignty. Stakeholders must monitor ComReg's pending mobile spectrum auction decisions and assess whether SIRO's open-access wholesale model extends sustainable returns as fiber penetration saturates urban corridors.
Market Dynamics
Copper decommissioning timelines are compressing infrastructure investment cycles across Irish networks, forcing operators to accelerate fiber migration ahead of legacy service sunsets while ComReg's wholesale access mandates reshape competitive economics.
Growth Catalysts
- ComReg's National Broadband Plan:Universal high-speed access mandates by 2028 are channeling state capital into rural fiber deployments, opening addressable markets previously unserved by commercial infrastructure.
- Enterprise cloud migration:Technology and pharmaceutical campuses in Dublin's technology corridor are driving demand for symmetrical gigabit leased lines and low-latency connectivity.
- 5G standalone deployment:Financial services clusters require ultra-reliable wireless for trading floor redundancy and mobile workforce enablement.
Market Restraints
- Construction cost inflation:Civil works for fiber trenching in rocky rural topography have escalated input costs for National Broadband Ireland contractors.
- Wholesale access pricing floors:ComReg's regulated rates constrain retail margin expansion for operators dependent on open-access fiber infrastructure.
- Copper network stranded assets:Accelerated decommissioning timelines risk premature write-downs of legacy last-mile infrastructure.
Strategic Opportunities
- Midland and western counties:Counties Galway, Mayo, and Donegal remain underpenetrated for gigabit services as urban saturation intensifies.
- Smart agriculture connectivity:Precision farming and livestock monitoring applications are emerging as specialized verticals for low-power wide-area networks.
- GDPR-compliant edge computing:Data sovereignty requirements are creating demand for distributed infrastructure hosting sensitive enterprise workloads.
Industry Challenges
- Fiber splicing technician scarcity:Specialized field engineering capacity is constraining deployment velocity for both SIRO and open-access operators.
- Legacy PSTN interconnection:Maintaining voice service continuity during copper-to-fiber migration requires complex signaling gateway management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ireland Telecom Market |
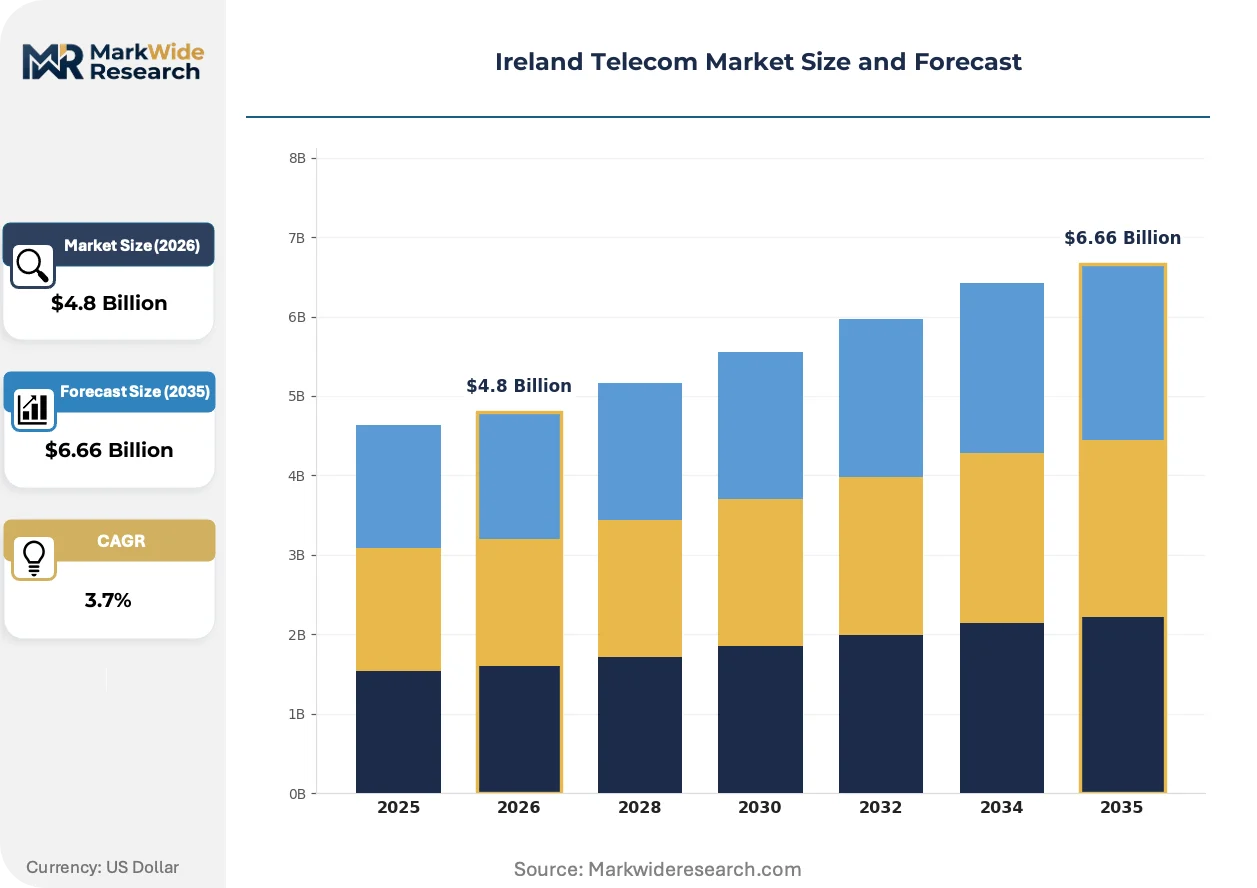
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, Mobile Data, Fixed Voice, Broadband Technology: 4G LTE, 5G, Fiber Optic, DSL End User: Residential, SMEs, Large Enterprises, Government Price Tier: Budget, Mid-Range, Premium, Enterprise |
| Companies Covered | Eir, Vodafone Ireland, Three Ireland, Virgin Media Ireland, Sky Ireland, Imagine Telecommunications, Pure Telecom, SIRO, National Broadband Ireland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ireland Telecom Market Trends and Innovations
Network function virtualization and software-defined infrastructure are dissolving traditional hardware boundaries, enabling operators to deploy services through cloud-native architectures rather than purpose-built appliances.
XGS-PON fiber technology is consolidating residential and enterprise access layers onto unified optical platforms, collapsing separate DSL and fiber network silos. Regional operators and wholesale fiber builders are adopting XGS-PON to serve both consumer gigabit tiers and business symmetrical services from common street cabinets. This convergence is compressing equipment vendor diversity and favoring suppliers with integrated optical line terminal portfolios.
ComReg's transposition of the EU Electronic Communications Code is mandating symmetric wholesale access obligations and tightened universal service definitions. The framework requires incumbents to publish reference offers for virtual unbundled local access at regulated prices. Smaller retail providers and regional fiber builders are leveraging these provisions to enter markets without parallel infrastructure construction.
Enterprise procurement patterns are fragmenting across multi-cloud connectivity requirements, with buyers unbundling network services from managed security and compute. Financial services firms in Dublin are sourcing dark fiber and wavelength services separately from managed SD-WAN overlays. This disaggregation is pressuring traditional bundled pricing and favoring specialized fiber infrastructure providers.
Ireland Telecom Market Segmentation
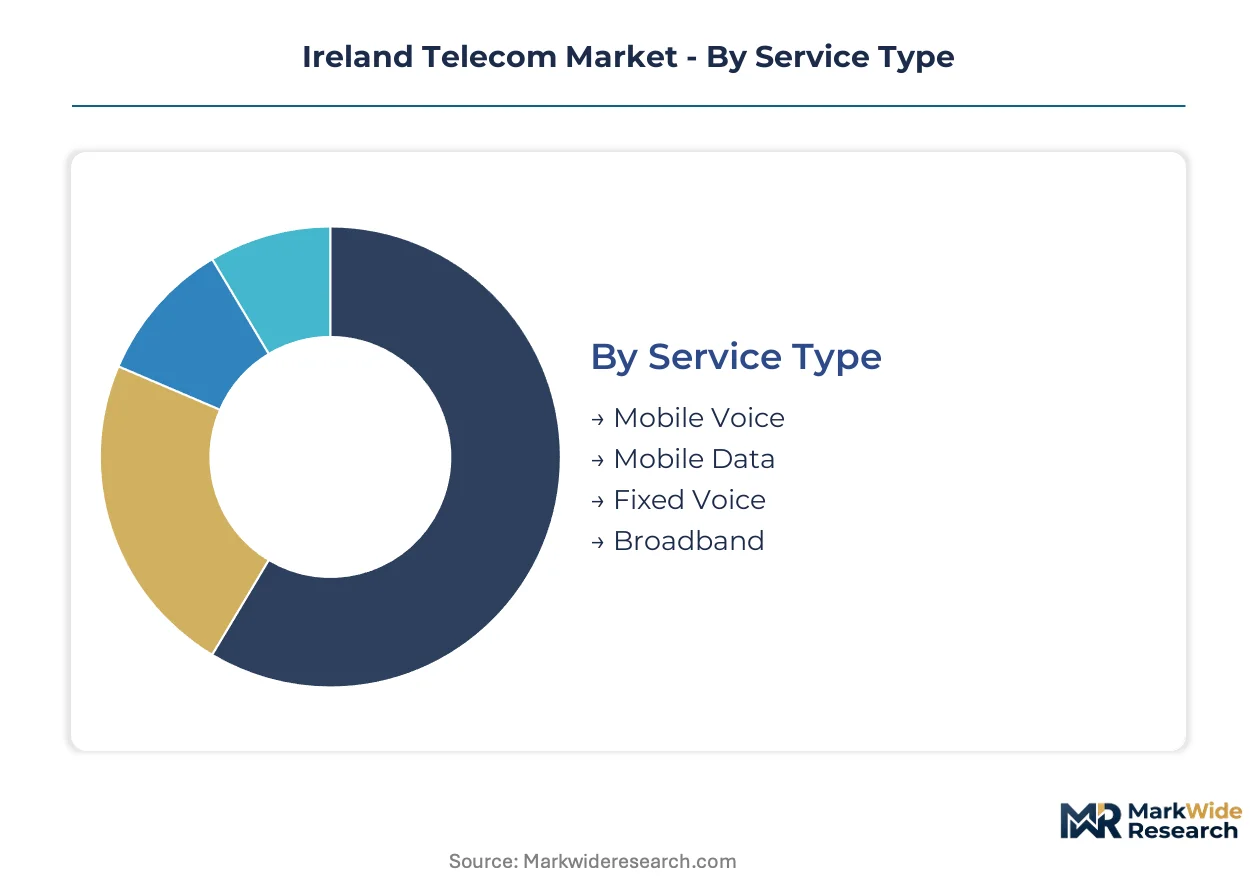
Service differentiation across Ireland's telecom landscape determines operator investment priorities and margin capture. Segmentation reveals where ComReg's regulatory pressure intersects with infrastructure economics and customer willingness to pay.
Service Type:
Volume concentrates in mass-market connectivity while premium economics flow from business-grade services.
- Mobile Data:Unmetered allowance packages dominate consumer acquisition strategies. Demand clusters in Dublin's technology corridor and surrounding Leinster counties where smartphone dependency and remote work infrastructure drive premium tier uptake.
- Broadband:Fiber-to-the-premises connections range from 100 Mbps residential tiers to 10 Gbps enterprise leased lines. SIRO and Virgin Media Ireland concentrate symmetrical gigabit deployments on technology and pharmaceutical campuses where latency sensitivity commands price premiums.
- Mobile Voice:Declining average revenue per user as over-the-top applications displace circuit-switched calling. Eir and Three Ireland bundle voice as a zero-margin retention tool within data-centric propositions.
- Fixed Voice:Copper PSTN infrastructure faces accelerated decommissioning under ComReg's migration timelines. Legacy service obligations constrain operator cost structures as fiber voice-over-IP replacement scales.
Mature deployment sits with Fixed Voice. Newer deployment is concentrated in Mobile Data.
Technology:
Legacy platforms yield to next-generation infrastructure as capital allocation shifts from maintenance to greenfield build.
- 5G:Standalone architecture enables network slicing for financial services clients requiring ultra-reliable wireless. Vodafone Ireland anchors enterprise-grade deployments for trading floor redundancy in Dublin's International Financial Services Centre.
- Fiber Optic:XGS-PON technology consolidates residential and enterprise access onto unified optical platforms. National Broadband Ireland mandates universal high-speed access by 2028, channeling state capital into rural deployments previously uneconomic for commercial infrastructure.
- 4G LTE:Capacity layer for mobile broadband in areas awaiting 5G standalone radio deployment. Three Ireland leverages extensive 4G spectrum holdings to compete on data allowance generosity.
- DSL:Copper-based delivery faces forced obsolescence as ComReg's wholesale access pricing and fiber migration timelines erode economic viability. Accelerated decommissioning risks stranded asset write-downs for operators with extensive legacy last-mile footprints.
Revenue contribution peaks with Fiber Optic. Infrastructure investment is climbing fastest for 5G.
End User:
Procurement sophistication varies sharply across customer scale, with enterprise buyers unbundling network services from managed security and compute.
- Large Enterprises:Financial services firms source dark fiber and wavelength services separately from managed SD-WAN overlays. GDPR and EU Cybersecurity Act compliance requirements shape procurement specifications for data sovereignty and edge computing infrastructure.
- SMEs:Price-sensitive segment migrating from DSL to fiber as copper decommissioning compresses legacy service availability. Regional operators target this cohort with simplified bundled propositions.
- Residential:Gigabit fiber penetration concentrates in urban corridors while midland and western counties await National Broadband Ireland intervention. Consumer switching behavior responds aggressively to promotional pricing from mobile operators.
- Government:Public administration connectivity requirements fall under universal service obligations with regulated pricing floors. Procurement emphasizes cybersecurity certification and data residency compliance.
Contract value concentrates with Large Enterprises. Addressable market expansion is proceeding fastest in Residential.
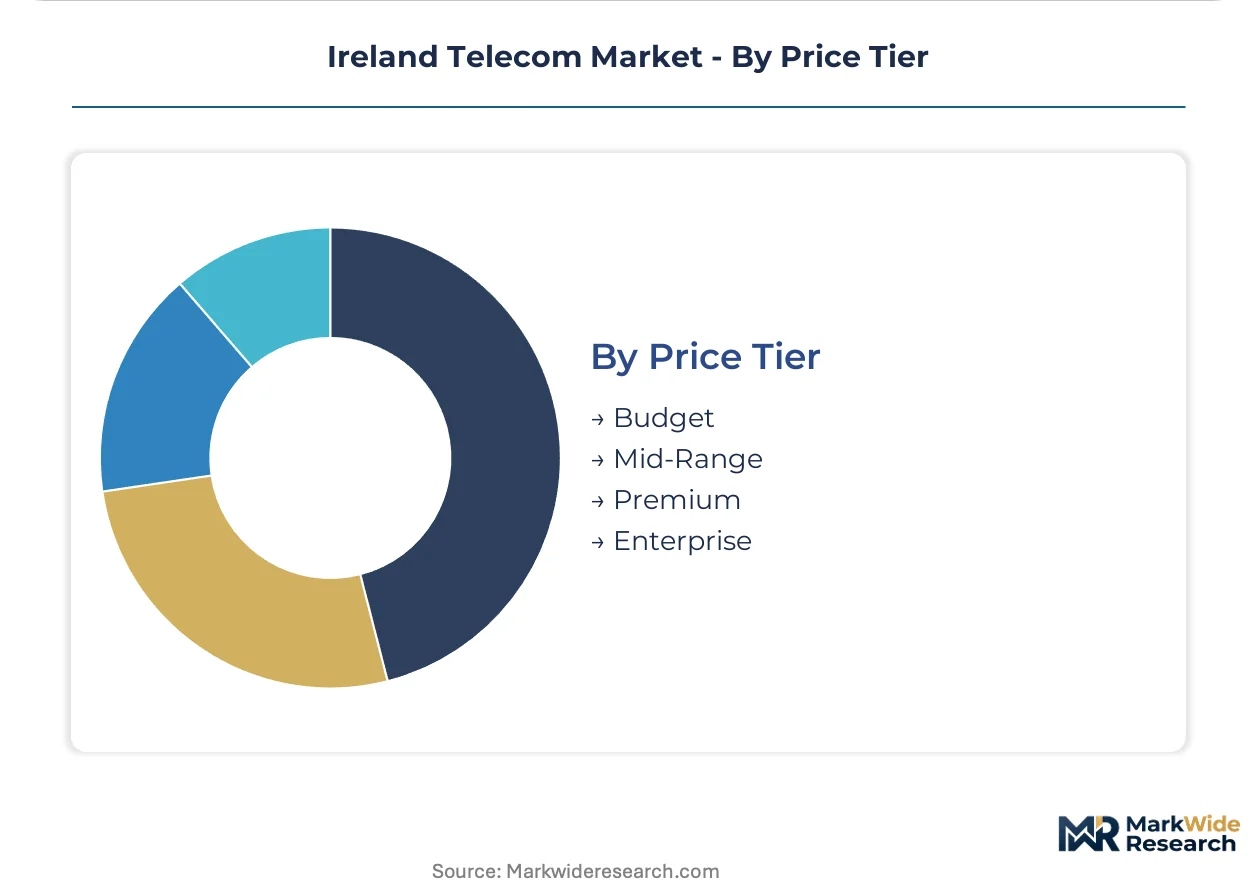
Price Tier:
Margin pools stratify by service bundling complexity and infrastructure ownership depth.
- Enterprise:Custom symmetrical connectivity with service level agreements guaranteeing uptime and latency performance. SIRO's open-access wholesale model enables retail providers to enter this segment without parallel infrastructure construction.
- Premium:Gigabit consumer tiers and small business packages with priority support and enhanced Wi-Fi hardware. Differentiation depends on fiber network depth and customer service reputation.
- Mid-Range:Standard fiber speeds between 100-500 Mbps representing the bulk of residential migration from copper. Competition intensifies as multiple operators overlay services on shared open-access infrastructure.
- Budget:Entry-level mobile data allowances and remaining DSL connections. Churn vulnerability is acute as promotional periods expire and competitors target switching incentives.
Margin stability sits with Enterprise. Subscriber volume is accumulating fastest in Mid-Range.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shannon Free Zone and Dublin's International Financial Services Centre concentrate enterprise connectivity demand through tax-advantaged facilities that anchor multinational technology and pharmaceutical operations requiring redundant fiber infrastructure.
Dublin and Leinster
Enterprise density in Dublin's technology corridor drives premium fiber and 5G uptake among financial services and pharmaceutical campuses. ComReg's wholesale access mandates under the EU Electronic Communications Code enable retail providers to overlay services on open-access infrastructure without parallel construction. The IFSC and Sandyford Business District host trading floors demanding ultra-low latency connectivity.
Cork and the South-West
Pharmaceutical manufacturing clusters around Cork Harbour and Ringaskiddy generate specialized demand for symmetrical gigabit services and redundant network paths. National Broadband Ireland's rural deployment timelines extend fiber reach into previously unserved townlands across County Cork. Apple and Pfizer operations anchor enterprise-grade procurement specifications.
Galway and the West
Medical technology manufacturing in Galway city and precision agriculture across Mayo and Roscommon create divergent connectivity requirements. ComReg's universal service obligations ensure baseline access while commercial fiber buildouts lag urban penetration rates. The Galway Technology Centre hosts indigenous software firms migrating from DSL to fiber.
Donegal and the North-West
Remoteness from commercial infrastructure corridors positions Donegal as dependent on National Broadband Ireland state intervention for gigabit access. Tourism and aquaculture operations in Killybegs and Letterkenny require specialized maritime and rural connectivity solutions. ComReg's rural wholesale pricing floors constrain retail margin expansion.
Limerick and the Mid-West
The Shannon Free Zone and University of Limerick campus generate mixed enterprise and research connectivity demand. Dell Technologies and Regeneron operations anchor multinational procurement patterns favoring managed security bundles. Regional operators target SME migration from copper with simplified fiber propositions.
Ireland Telecom Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with infrastructure-owning incumbents commanding enterprise pricing power while retail-only providers compete on acquisition cost. The market structures around three tiers: integrated infrastructure operators with fiber and spectrum assets, wholesale-dependent retail brands, and state-backed rural builders. Strategic moves concentrate on fiber splicing capacity acquisition, XGS-PON platform consolidation, and open-access wholesale partnership structures.
Among infrastructure-integrated operators, Eir, Vodafone Ireland, and Three Ireland exemplify divergent archetypes. Eir leverages legacy copper footprint economics to accelerate fiber migration. Vodafone Ireland anchors enterprise 5G standalone positioning. Three Ireland competes aggressively on mobile data allowance generosity to capture residential switching demand.
| Leading Market Players |
|---|
| Eir |
| Vodafone Ireland |
| Three Ireland |
| Virgin Media Ireland |
| Sky Ireland |
| Imagine Telecommunications |
| Pure Telecom |
| SIRO |
| National Broadband Ireland |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement unbundling of network services from managed security is compressing bundled pricing margins and forcing suppliers to restructure component sourcing. This demand-side fragmentation is reshaping how operators configure supply chains and where they extract pricing power.
Pricing Analysis
Short lead-time premiums for fiber splicing technicians and civil engineering crews are widening price spreads between expedited and standard deployment schedules. Subscription-based recurring revenue models dominate enterprise connectivity, with price differentiation resting on service level agreement tiers and latency guarantees. Cost compression in mid-range residential fiber is intensifying because multiple retail providers overlay services on shared open-access infrastructure. Residential consumers exhibit acute price sensitivity, while financial services firms in Dublin's IFSC demonstrate minimal elasticity for ultra-low latency services.
Supply Chain Analysis
CE marking and EU Cybersecurity Act certification requirements for network equipment are gating vendor participation and consolidating supplier lists around compliant manufacturers. Optical line terminal and fiber cable supply concentrates in China, Germany, and the United States. Raw material dependencies span high-purity glass fiber, semiconductor lasers, and specialized polymers for cable sheathing. Single-source vulnerability sits with XGS-PON chipset suppliers. Distribution runs through direct operator procurement with long-term framework agreements and specialized telecom distributors for maintenance spares.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ireland's telecom market sits in a copper-to-fiber transition phase, with XGS-PON technology systematically displacing legacy DSL infrastructure across both residential and enterprise access layers.
For Market Incumbents: Deploy fiber splicing capacity acquisition as the priority lever to constrain deployment velocity for competitors. Accelerate XGS-PON platform consolidation to collapse separate network silos and reduce vendor diversity. Secure long-term civil engineering partnerships to lock in trenching capacity ahead of National Broadband Ireland's rural buildout timelines. Defend against wholesale-dependent retail brands by deepening infrastructure ownership in Dublin's technology corridor where enterprise density sustains premium pricing. For New Entrants and Emerging Players: ComReg's transposition of the EU Electronic Communications Code in Ireland opens a window for virtual unbundled local access without parallel infrastructure construction. Target midland and western counties where gigabit penetration lags urban saturation and National Broadband Ireland intervention creates wholesale access opportunities. Pursue SME migration from copper with simplified fiber propositions bundled with zero-margin voice retention tools. Leverage open-access partnerships with SIRO to enter enterprise symmetrical gigabit segments without capital-intensive street cabinet deployment. For Investors and Strategic Acquirers: The window for entry favors regional fiber builders with established civil engineering relationships and ComReg wholesale access agreements. Long-term viability hinges on securing sustainable returns as fiber penetration saturates Dublin's urban corridors. Monitor SIRO's open-access wholesale model extension as the critical inflection signal for competitive dynamics in enterprise connectivity. Acquisition targets should demonstrate technician training pipelines and XGS-PON deployment scale.| Strategic Initiative | Industry Significance |
|---|---|
| XGS-PON Platform Consolidation | Unifies residential and enterprise access layers onto common optical infrastructure, reducing equipment vendor diversity. |
| Open-Access Wholesale Partnership | Enables retail providers to enter markets without parallel fiber construction under ComReg's symmetric access mandates. |
| Fiber Splicing Capacity Acquisition | Addresses technician scarcity constraining deployment velocity for both SIRO and competing operators. |
| Enterprise SD-WAN Overlay Development | Captures margin pools as financial services firms unbundle network services from managed security procurement. |
| Smart Agriculture Connectivity Vertical | Opens specialized revenue streams for low-power wide-area networks in Mayo and Roscommon precision farming applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with network planning executives, wholesale access managers, fiber deployment contractors, and enterprise procurement officers at financial services and pharmaceutical campuses. ComReg spectrum allocation decisions, National Broadband Ireland progress reports, and operator reference offers provided foundational regulatory and infrastructure data. Bottom-up modeling of addressable premises and top-down validation against reported subscriber metrics ensured triangulation integrity.
Segment-level granularity modeled service type, technology platform, end-user scale, and geographic cluster across the projection horizon. Mobile data and fiber broadband expansion trajectories incorporated ComReg's universal service obligation timelines and enterprise cloud migration patterns. CAGRs derived from subscriber penetration curves, average revenue per user trends, and infrastructure investment cycles specific to Irish regulatory economics.
The model assumes a particular technology adoption path; alternative pathways for 5G standalone displacement of fixed wireless access would alter the outlook. Forecasts incorporate assumptions regarding National Broadband Ireland deployment schedules and ComReg wholesale pricing floor stability. A model refresh is warranted upon material change in ComReg's pending mobile spectrum auction decisions or SIRO's wholesale rate structure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Japan 5G Small Cell Market
Telecommunications
5G Network and Service Assurance Market
Telecommunications
Sri Lanka Telecom Market
Telecommunications
Cambodia ICT Market
Telecommunications
Telecom Expense Management Market
Telecommunications
LTE Emergency Networks Market
Telecommunications
Global LTE Market
Telecommunications
5G in Defense Market
Telecommunications
Chile Telecom Market
Telecommunications
IP DECT Phones Market
Telecommunications
Africa Entertainment and Telecommunication Market
Telecommunications
Europe Managed SD-WAN Services Market
Telecommunications
Global 5G in Healthcare Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Managed Mobility Services (MMS) Market