
 Global B2B Telecommunication Market | 2026-2036
Global B2B Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Global B2B Telecommunication Market Foresight
Managed network service revenue is tilting from basic connectivity provisioning toward outcome-based network operations. Deutsche Telekom AG leverages its European fiber footprint to anchor long-term enterprise contracts with guaranteed latency thresholds. Cisco Systems Inc. competes through deep vertical integration of routing hardware with software-defined WAN orchestration. NTT Communications Corporation dominates the Asia-Pacific enterprise segment through its Arcstar Universal One platform and data center proximity.
Global B2B telecommunication encompasses dedicated voice, data, and managed network services sold to non-consumer organizations, typically delivered over MPLS, Ethernet, or cellular infrastructure with service-level agreements guaranteeing uptime, latency, and packet-loss parameters. These services enable inter-site corporate communication, cloud application access, and machine-to-machine coordination across distributed operations. Cloud connectivity and security solutions command expanding margin pools as enterprises abandon legacy MPLS backbones for SASE architectures. IoT connectivity represents the fastest-growing service type as utilities and logistics operators deploy massive sensor grids requiring cellular LPWAN or private 5G spectrum. Voice services remain a mature revenue line, though session initiation protocol trunking and unified communications-as-a-service bundles sustain carrier relevance.
The U.S. Federal Communications Commission shapes market access through spectrum auction design and net-neutrality enforcement, while the EU's GDPR and Cybersecurity Act impose data-localization and certification burdens on cross-border service providers. Japan's Ministry of Internal Affairs and Communications accelerates Open RAN mandates that diversify vendor ecosystems for enterprise network builds. Stakeholders must monitor how sovereign cloud requirements and AI-driven traffic management reshape procurement criteria for multinational connectivity contracts.
Market Dynamics
The migration from MPLS backbones to software-defined architectures represents the dominant structural force reshaping carrier economics, compressing legacy revenue pools while redistributing margin toward cloud-integrated network orchestration layers.
Growth Catalysts
- EU Digital Operational Resilience Act:Mandatory infrastructure upgrades across Frankfurt, Paris, and Amsterdam financial hubs are accelerating private fiber deployments with sub-10 millisecond latency guarantees for algorithmic trading platforms.
- Industrial IoT sensor grids:German automotive manufacturers are commissioning dedicated 5G campus networks to synchronize robotic assembly lines with real-time quality control systems across multi-facility operations.
- Private 5G spectrum allocation:Japan's Ministry of Internal Affairs and Communications enterprise spectrum licenses are enabling manufacturers in Osaka and Nagoya to bypass public network congestion for mission-critical automation.
Market Restraints
- Fiber deployment cost escalation:Rights-of-way negotiations and trenching expenses in dense European urban centers are extending payback periods for last-mile enterprise connectivity infrastructure.
- Vendor concentration in radio access equipment:Limited qualified suppliers for Open RAN-compliant baseband units are creating procurement bottlenecks for carriers diversifying beyond incumbent hardware ecosystems.
- Skilled network engineering scarcity:Proficiency in Kubernetes-orchestrated network function virtualization remains concentrated among a narrow labor pool, inflating implementation timelines for cloud-native architectures.
Strategic Opportunities
- SASE convergence:Bundling secure access service edge with SD-WAN subscriptions allows carriers to capture security spend previously allocated to standalone firewall vendors.
- India's enterprise digitization:TRAI's permissive OSP regime is enabling global carriers to establish captive network operations centers in Bengaluru and Hyderabad without joint venture requirements.
- Edge computing colocation:Proximity hosting for latency-sensitive AI inference workloads at carrier-neutral facilities is creating new revenue streams adjacent to traditional connectivity.
Industry Challenges
- Legacy billing system overhaul:Migrating from circuit-based invoicing to consumption-metered pricing requires multi-year core IT transformations that strain carrier operational bandwidth.
- Cross-border data sovereignty:Fragmented national cloud certification regimes are complicating unified service delivery for multinational enterprises operating across GDPR, China's PIPL, and Saudi Arabia's PDPL jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global B2B Telecommunication Market |
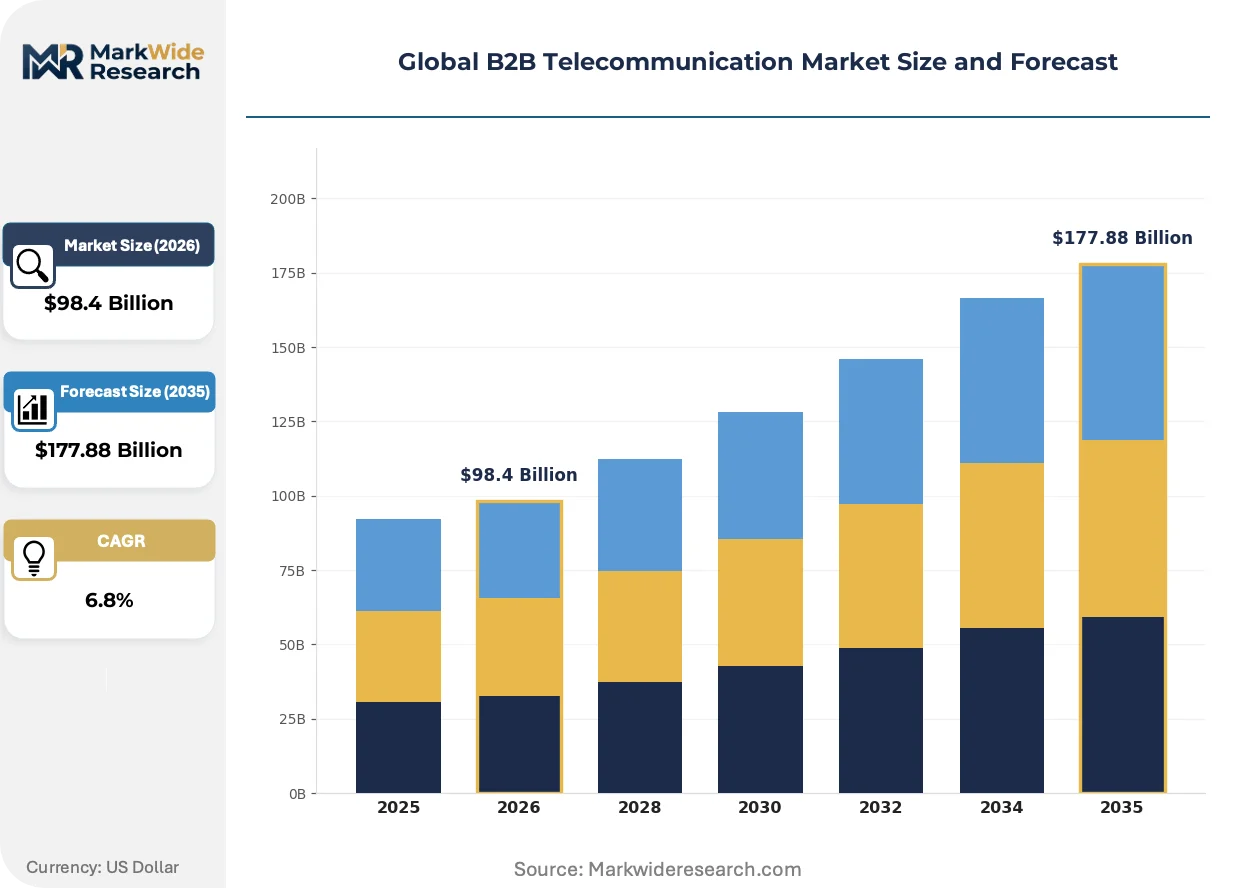
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $177.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Data, Managed Network, Cloud Connectivity, IoT Connectivity, Security Solutions Application: Unified Communications, Remote Collaboration, Customer Support, Supply Chain Management, Asset Tracking, Smart Buildings Distribution Channel: Direct Sales, Value-Added Resellers, System Integrators, Online Platforms, Wholesale Carriers, Consultants Customer Type: Enterprises, Small & Medium Businesses, Government Agencies, Educational Institutions, Financial Services, Transportation Providers |
| Companies Covered | AT&T Inc., Verizon Communications Inc., Deutsche Telekom AG, Vodafone Group Plc, Orange S.A., Cisco Systems Inc., NTT Communications Corporation, Telefonica S.A., China Mobile Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global B2B Telecommunication Market Shifts & Advancements
Artificial intelligence traffic management and zero-trust security integration are redefining how carriers architect enterprise-grade connectivity, shifting procurement criteria from bandwidth specifications toward outcome-guaranteed service level objectives.
Intent-based networking is rendering obsolete manual CLI configuration for enterprise WAN provisioning. Large pharmaceutical distributors in Switzerland and the Netherlands are adopting these self-healing architectures to maintain compliance with GDP temperature-monitoring requirements across cold-chain logistics networks. The technology is rendering obsolete traditional network operations center staffing models that relied on ticket-driven incident response.
The EU AI Act's risk classification framework is imposing algorithmic transparency requirements on carriers deploying predictive traffic engineering. Providers must now document training data provenance and decision logic for automated routing systems serving critical infrastructure clients. German energy utilities are demanding contractual indemnification clauses that shift liability exposure toward carriers whose AI-driven congestion management triggers SCADA communication failures.
Enterprise buyers are consolidating vendor relationships through multi-year integrated connectivity contracts that bundle cellular, fixed-line, and security services under single accountability structures. This pattern is displacing the historical practice of procuring voice, data, and security from separate specialized providers. The shift is most pronounced among Nordic manufacturing conglomerates seeking simplified governance of pan-European network estates.
Global B2B Telecommunication Market Segmentation
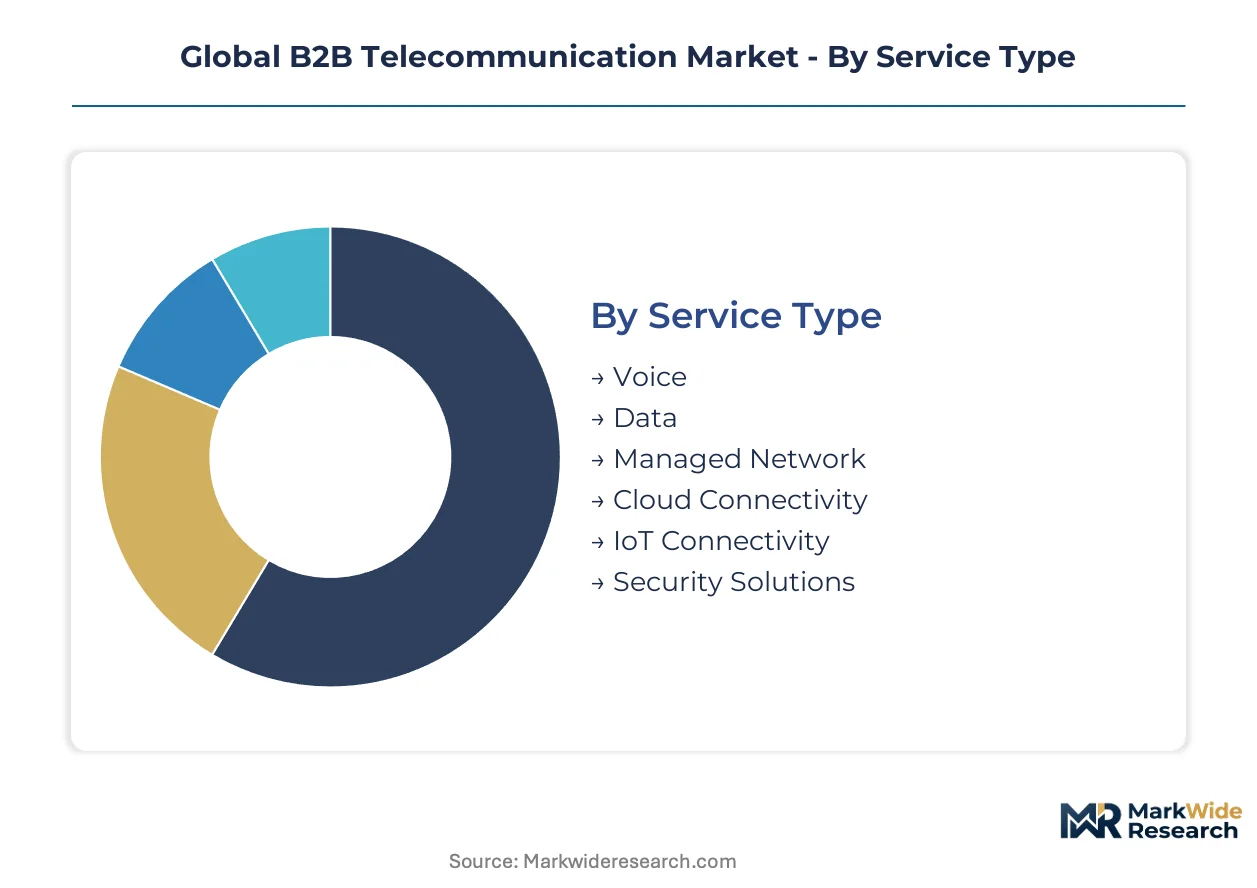
Enterprise procurement patterns across the Global B2B Telecommunication Market diverge sharply by operational scale, regulatory exposure, and legacy infrastructure burden. Service providers must architect distinct commercial models for each segment cluster, as a German automotive manufacturer's private 5G campus network specifications bear little resemblance to a Mumbai-based logistics SME's SD-WAN requirements.
Service Type:
Mature revenue lines anchor carrier balance sheets while emerging service categories capture incremental margin pools.
- Voice:Session initiation protocol trunking and unified communications-as-a-service bundles sustain relevance for financial trading floors and contact center operations. Swiss pharmaceutical distributors maintain redundant voice circuits for GDP-compliant cold-chain emergency protocols.
- Data:Dedicated Ethernet and MPLS circuits retain dominance in Frankfurt and Amsterdam financial hubs where sub-10 millisecond latency guarantees remain non-negotiable. Deutsche Börse members specify diverse fiber paths with automated failover for algorithmic trading platforms.
- Managed Network:Outcome-based network operations contracts replace basic connectivity provisioning as Nordic manufacturing conglomerates consolidate vendor relationships.
- Cloud Connectivity:Direct cloud on-ramps to AWS, Azure, and GCP regions displace traditional internet backhaul for enterprise SaaS workloads.
- IoT Connectivity:Cellular LPWAN and private 5G sensor grids expand fastest among German utilities deploying predictive maintenance networks.
- Security Solutions:SASE architecture bundles capture firewall spend previously allocated to standalone vendors.
Voice retains volume leadership; IoT Connectivity holds the steepest expansion curve.
Application:
Functional use cases stratify by latency tolerance, data sovereignty requirements, and integration complexity with operational technology systems.
- Unified Communications:Voice, video, and messaging convergence platforms serve distributed knowledge workers. Japanese automotive suppliers in Nagoya deploy these systems for real-time coordination with Osaka headquarters.
- Remote Collaboration:Low-latency video and desktop virtualization enable field engineer support. German wind turbine maintenance crews access augmented reality guidance via 5G slices.
- Customer Support:Omnichannel contact center platforms integrate voice, chat, and social media routing.
- Supply Chain Management:EDI replacement with API-driven logistics visibility demands consistent cross-border connectivity.
- Asset Tracking:GPS and RFID sensor networks monitor container fleets across Rotterdam and Hamburg port corridors.
- Smart Buildings:HVAC, lighting, and access control convergence requires building-grade cellular and fiber infrastructure.
Unified Communications commands the largest installed base; Smart Buildings is expanding most quickly.
Distribution Channel:
Route-to-market economics shift with deal size, technical complexity, and customer procurement maturity.
- Direct Sales:Carrier field organizations secure multi-year integrated contracts with guaranteed service level objectives. Deutsche Telekom AG anchors long-term enterprise relationships through dedicated account teams.
- Value-Added Resellers:Regional specialists bundle connectivity with vertical-specific software. French industrial automation resellers package private 5G with SCADA integration services.
- System Integrators:Accenture and Deloitte-class firms embed network services within digital transformation programs.
- Online Platforms:Self-service portals capture standardized connectivity for mid-market customers.
- Wholesale Carriers:Capacity resale enables regional operators to extend geographic coverage without fiber builds.
- Consultants:Technology advisory firms influence RFP specifications and vendor shortlists.
Direct Sales dominates enterprise value capture; Online Platforms are climbing the fastest.
Customer Type:
Organizational scale and sectoral regulation create divergent connectivity specifications and contractual risk profiles.
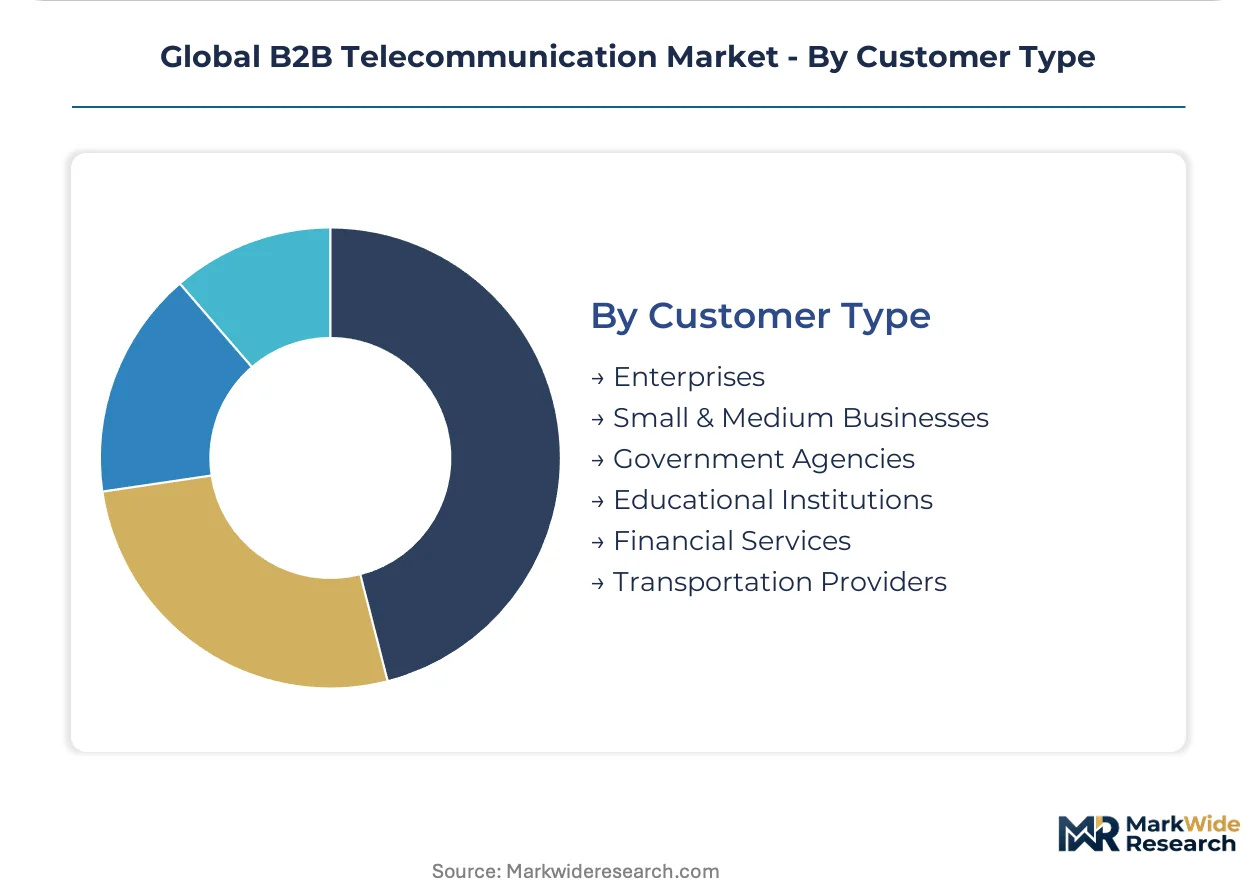
- Enterprises:Multinationals negotiate global master service agreements with unified billing and cross-border service level guarantees. DORA compliance mandates drive infrastructure resilience upgrades for EU-domiciled corporations.
- Small & Medium Businesses:Standardized SD-WAN and cloud connectivity packages with consumption-based pricing predominate.
- Government Agencies:Sovereign cloud and certified encryption requirements complicate vendor selection.
- Educational Institutions:Research networks demand high-capacity international links for data-intensive collaboration.
- Financial Services:Algorithmic trading and real-time payment systems require sub-5 millisecond latency with regulatory audit trails.
- Transportation Providers:Fleet telematics and passenger WiFi generate high-volume, price-sensitive connectivity demand.
Enterprises retain volume leadership; Financial Services holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany and Japan demonstrate the lowest price elasticity, accepting premium rates for guaranteed sub-10 millisecond latency, while Indian logistics SMEs and Brazilian mid-market manufacturers drive hard bargains on standardized SD-WAN packages.
United States
Financial services institutions in New York and Chicago are expanding private fiber deployments for algorithmic trading platforms. The FCC's spectrum auction design shapes carrier access to mid-band frequencies for enterprise 5G builds. Dallas-Fort Worth anchors a concentration of data center interconnect demand from cloud hyperscalers.
Germany
Industrial manufacturers in Bavaria and Baden-Württemberg are commissioning dedicated 5G campus networks for robotic assembly line synchronization. The EU's Digital Operational Resilience Act compels Frankfurt financial hubs to upgrade infrastructure resilience with automated failover systems. Stuttgart's automotive cluster represents Europe's densest concentration of private spectrum deployments for factory automation.
Japan
Manufacturers in Osaka and Nagoya are leveraging enterprise spectrum licenses to bypass public network congestion for mission-critical automation. METI's Open RAN mandates diversify vendor ecosystems for enterprise network builds. Tokyo's financial district demands redundant sub-5 millisecond circuits for real-time payment system continuity.
India
Global carriers are establishing captive network operations centers in Bengaluru and Hyderabad under TRAI's permissive OSP regime without joint venture requirements. The central bank's digital payment infrastructure push drives demand for secure enterprise connectivity. Maharashtra's manufacturing corridor is emerging as a testbed for industrial IoT sensor grids.
United Kingdom
London's trading floors maintain redundant voice circuits for emergency protocols alongside SIP trunking migrations. GDPR compliance mandates data-localization for cross-border service providers serving EU-domiciled clients. The Cambridge tech cluster is driving edge computing colocation demand for AI inference workloads.
Global B2B Telecommunication Market Competitive Landscape
Integrated carriers and specialized network orchestrators split the market based on enterprise appetite for single-accountability contracts versus best-of-breed component sourcing. Tier-1 telecom groups anchor long-term relationships through dedicated fiber assets and guaranteed service level objectives. Boutique SD-WAN specialists capture mid-market share with consumption-metered pricing. Dominant competitive moves include geographic footprint expansion through subsea cable investments and security capability augmentation via SASE portfolio integration.
Within the integrated carrier tier, Deutsche Telekom AG and NTT Communications Corporation exemplify archetypes leveraging continental fiber density to anchor multi-year enterprise contracts. AT&T Inc. occupies a position representing North American scale advantages in spectrum holdings and data center proximity. These entities sit within a competitive structure where European and Asia-Pacific incumbents compete through infrastructure ownership depth while North American players emphasize cloud partnership ecosystems.
| Leading Market Players |
|---|
| AT&T Inc. |
| Verizon Communications Inc. |
| Deutsche Telekom AG |
| Vodafone Group Plc |
| Orange S.A. |
| Cisco Systems Inc. |
| NTT Communications Corporation |
| Telefonica S.A. |
| China Mobile Ltd. |
| Others |
Supply & Pricing Matrix
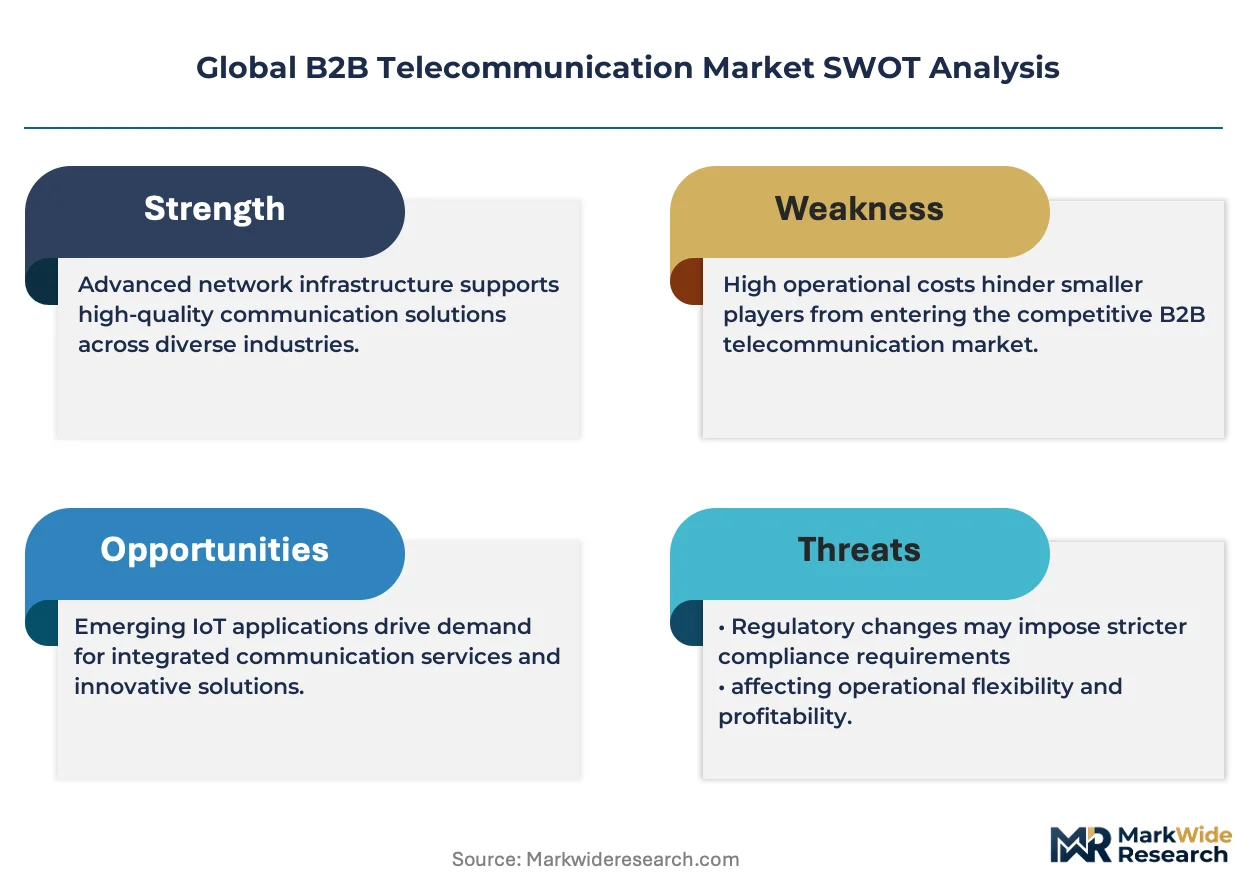
Regulatory chokepoints around Open RAN certification and fiber rights-of-way in dense European urban centers determine both the spread between premium latency-guaranteed tiers and basic connectivity packages, and the geographic shape of carrier infrastructure deployment priorities. Buyers in Frankfurt and Tokyo financial hubs accept substantial premiums for sub-5 millisecond circuits, while Indian logistics SMEs and Brazilian mid-market manufacturers compress margins on standardized SD-WAN packages.
Pricing Analysis
Multi-year service contracts with embedded security and edge computing attachments drive lifetime value beyond basic connectivity provisioning. Three-tier pricing structure across premium latency-guaranteed, standard managed network, and economy self-service tiers separates Deutsche Börse members from Mumbai-based logistics operators. Cost compression in the economy tier intensifies because hyperscaler cloud on-ramps commoditize basic bandwidth. Financial services institutions in London and Singapore demonstrate the lowest price sensitivity, while transportation providers and educational institutions negotiate aggressively on volume.
Supply Chain Analysis
Extended payment terms for radio access equipment and supply-chain finance facilities for fiber deployment subcontractors have become standard procurement practice among tier-1 carriers. Manufacturing concentration for Open RAN-compliant baseband units rests on Finland, South Korea, and Japan, while submarine cable systems and data center switches draw from Taiwan and China. Single-source vulnerability in qualified Open RAN vendors creates procurement bottlenecks for carriers diversifying beyond incumbent hardware ecosystems. Distribution runs through direct carrier field organizations for enterprise accounts, with value-added resellers capturing mid-market standardized packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security services and edge computing colocation represent the fastest-expanding recurring-revenue layers, outpacing hardware-centric connectivity provisioning as enterprises consolidate vendor relationships under outcome-based contracts.
For Market Incumbents: Entrench fiber ownership depth in Frankfurt, London, and Singapore financial corridors to anchor multi-year enterprise contracts with guaranteed latency thresholds against hyperscaler cloud-connectivity substitutes. Invest in Kubernetes-orchestrated network function virtualization certification programs to address skilled engineering scarcity that extends implementation timelines for cloud-native architectures. For New Entrants and Emerging Players: Build out captive network operations centers in Bengaluru and Hyderabad under TRAI's permissive OSP regime to serve India's accelerating enterprise digitization without joint venture encumbrances. Target mid-market manufacturing in Maharashtra's industrial corridor with consumption-metered SD-WAN packages bundled with industrial IoT sensor grid integration services. For Investors and Strategic Acquirers: The EU Digital Operational Resilience Act reshapes the acquisition landscape by mandating infrastructure resilience upgrades that favor carriers with existing automated failover systems and regulatory audit capabilities. Long-term viability across the analysis window hinges on SASE portfolio integration depth and private 5G spectrum license holdings. Monitor Open RAN vendor qualification timelines as the critical inflection signal for carrier procurement pattern shifts. Macroeconomic, regulatory, or technological deviation would prompt revision.| Strategic Initiative | Industry Significance |
|---|---|
| SASE Portfolio Integration | Bundles secure access service edge with SD-WAN to capture firewall spend previously allocated to standalone vendors. |
| Private 5G Spectrum Acquisition | Enables German automotive manufacturers to bypass public network congestion for robotic assembly line synchronization. |
| Edge Computing Colocation Buildout | Positions carrier-neutral facilities for latency-sensitive AI inference workloads adjacent to traditional connectivity revenue. |
| Open RAN Vendor Diversification | Addresses procurement bottlenecks as Japan's METI mandates diversify radio access equipment ecosystems. |
| Cloud Hyperscaler Partnership | Secures direct on-ramps to AWS, Azure, and GCP regions displacing traditional internet backhaul for enterprise SaaS workloads. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of carrier financial disclosures, spectrum allocation databases, and hyperscaler capex reports through structured interviews with network operations executives, enterprise IT procurement officers, regulatory affairs leads at telecommunications carriers, and systems integration specialists. Bottom-up triangulation across service-type revenue segmentation combines with top-down validation against national regulatory filings and infrastructure deployment permits.
Forecast inputs include modeled expansion across service type, application use case, distribution channel, and customer vertical dimensions, with additional granularity for latency-tier specifications and sovereign cloud certification requirements. CAGRs derive from regression analysis of historical carrier revenue disaggregation and projected enterprise procurement pattern shifts. Industry-specific inputs incorporate Open RAN deployment timelines, private 5G spectrum license issuance rates, and DORA compliance implementation schedules.
Practitioners should monitor regulatory revision triggers including EU AI Act algorithmic transparency mandates, FCC spectrum auction design modifications, and TRAI OSP regime adjustments for early signals of procurement criteria evolution. Forecasts reflect documented assumptions regarding enterprise cloud migration velocity and industrial automation investment cycles. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Switzerland Telecom Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Myanmar ICT Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Finland Telecom Market
Telecommunications
Mftpaas Market
Telecommunications
Telecommunication Service Market
Telecommunications
Thailand ICT Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market
Telecommunications
United States Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Australia Telecom Market
Telecommunications
Cloud PBX Market
Telecommunications
Super High Frequency Communication Market
Telecommunications
Myanmar Telecom Market