
 Podiatry Equipment Market | 2026-2036
Podiatry Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Podiatry Equipment Market Intelligence
The replacement of traditional stainless steel with lightweight titanium alloys in surgical instruments is consolidating the high-performance segment. DJO Global leverages its portfolio in rehabilitation equipment to address sports injury applications. Henry Schein controls crucial distribution channels to private podiatry clinics. NSK Ltd. specializes in high-precision surgical instruments and drills, differentiating on performance.
Podiatry equipment encompasses a broad category of medical devices used to diagnose, treat, and manage conditions affecting the foot, ankle, and lower leg. These instruments range from digital scanners with micron-level precision for custom orthotics to laser therapy systems for tissue regeneration. Their core function is to address pathologies from diabetic foot ulcers to sports-related injuries. Diagnostic devices and treatment units form the foundational product segments, while diabetic foot care applications are expanding quickly.
The market is governed by stringent medical device regulations, including the FDA's 510(k) clearance in the United States and the EU's Medical Device Regulation (MDR). These frameworks dictate device classification, clinical data requirements, and post-market surveillance. Future competitive advantage will hinge on integrating digital health technologies and demonstrating superior clinical outcomes in value-based care models.
Market Dynamics
The convergence of an aging global population with the rising prevalence of metabolic diseases like diabetes is the central force shaping the podiatry equipment market. This demographic pressure creates a sustained clinical need, while concurrent advances in digital imaging and materials science provide new tools to meet it.
Growth Catalysts
- Rising Diabetes Prevalence:The increasing incidence of diabetes mellitus, particularly in developed nations like the United States and Germany, elevates the risk of diabetic foot ulcers, directly driving demand for specialized diagnostic tools, wound care devices, and therapeutic equipment.
- Technological Advancements in Orthotics:The adoption of CAD/CAM systems and 3D printing technologies for fabricating custom orthotics is improving treatment efficacy and patient comfort, encouraging clinicians to invest in these modern digital workflows over traditional methods.
- Stricter Regulatory Standards:Implementation of frameworks like the EU's Medical Device Regulation (MDR) pushes manufacturers towards higher standards of quality and safety, spurring a replacement cycle as older, non-compliant equipment is phased out.
Market Restraints
- High Capital Investment:The significant upfront cost of advanced equipment, such as high-resolution digital scanners and therapeutic laser systems, poses a substantial financial barrier for small, independent podiatry clinics and solo practitioners.
- Stringent Regulatory Hurdles:Navigating the complex and time-consuming FDA 510(k) premarket notification process in the United States can delay the introduction of innovative devices and increase development costs for manufacturers.
- Reimbursement Inconsistencies:Variable and often inadequate reimbursement codes for podiatric procedures and custom devices across national and private insurance plans, especially in certain European countries, can limit patient access and curb provider investment.
Strategic Opportunities
- Tele-Podiatry and Remote Monitoring:Developing integrated hardware and software for remote patient monitoring, particularly for high-risk diabetic patients, offers a significant opportunity to extend clinical reach and improve preventative care models.
- Expansion in Emerging Economies:Untapped markets in Asia-Pacific, including India and China, present long-term growth potential as healthcare infrastructure develops and awareness of advanced foot care grows in response to rising lifestyle diseases.
- Sports Medicine Applications:There is a growing opportunity to adapt and market podiatry equipment, such as diagnostic ultrasound and shockwave therapy devices, for the diagnosis and treatment of sports-related injuries of the foot and ankle.
Industry Challenges
- Digital Workflow Integration:A primary operational challenge is the difficulty of integrating new digital podiatry scanners and CAD software with existing legacy Electronic Health Record (EHR) systems, leading to fragmented patient data and inefficient clinical workflows.
- Specialized Training Requirements:The increasing sophistication of diagnostic and therapeutic equipment necessitates specialized training for podiatrists and clinical staff, creating a skills gap that can slow the adoption rate of new technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Podiatry Equipment Market |
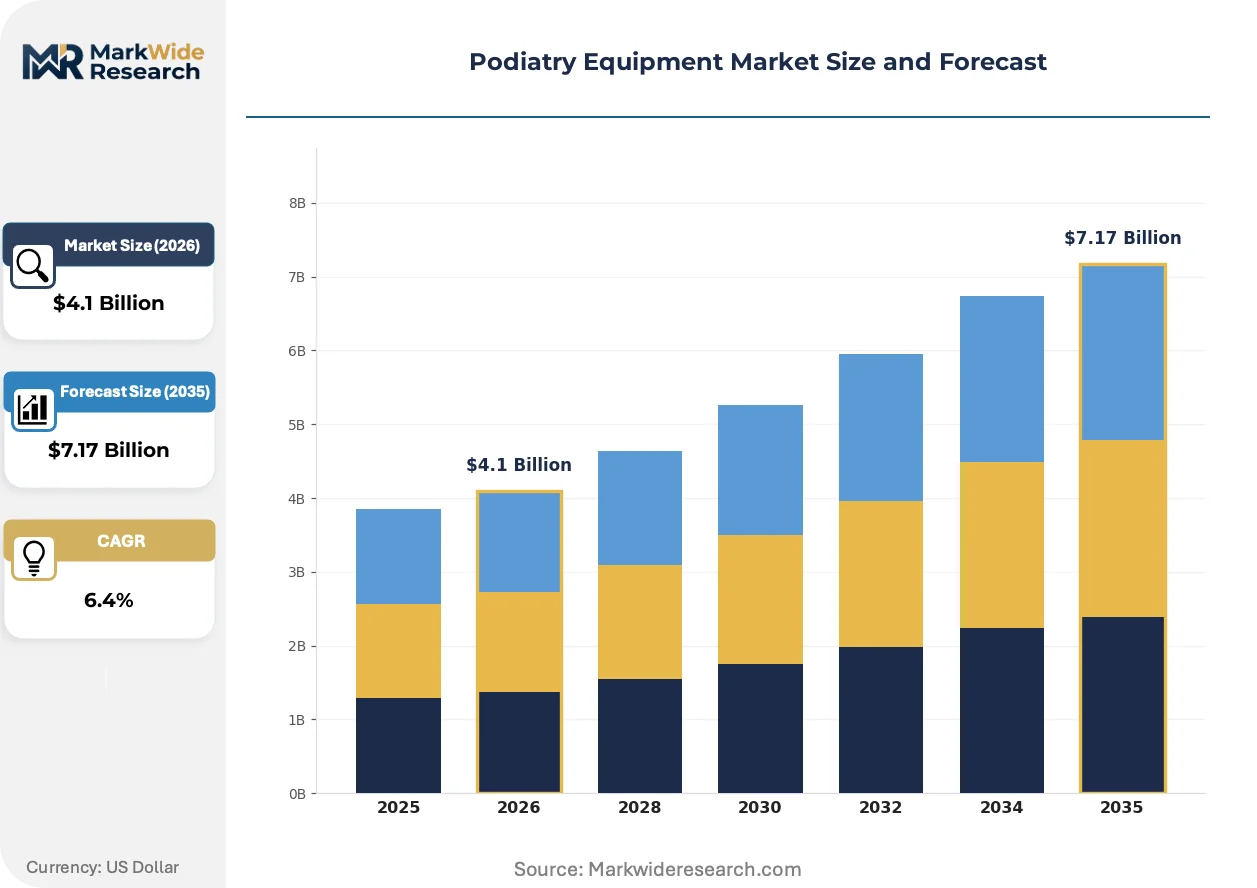
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Devices, Treatment Units, Surgical Instruments, Rehabilitation Equipment, Orthotic Devices Technology: Imaging Systems, Laser Therapy, Biomechanical Analysis, Ultrasonic, Digital Scanning Application: Foot Deformities, Diabetic Foot Care, Sports Injuries, Nail Disorders, Wound Management End User: Podiatry Clinics, Rehabilitation Centers, Ambulatory Surgical Centers, Orthopedic Centers, Sports Medicine Facilities |
| Companies Covered | DJO Global, A. Algeo Limited, Bauerfeind AG, Henry Schein, NAMROL Group, Vismara S.r.l., NSK Ltd., FAS Healthcare Ltd., Huntleigh Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Podiatry Equipment Market Strategic Shifts & Innovations
Patient-specific treatment models are defining the next phase of market evolution, shifting focus from generalized tools to customized therapeutic and diagnostic solutions. This movement is powered by digitalization, which enables a higher degree of precision and personalization in foot and ankle care.
Digital 3D scanners capture foot morphology with micron-level accuracy, providing a precise data set for diagnostics and device fabrication. Specialized podiatry clinics and custom orthotic laboratories are leading the adoption of this technology. This shift from physical plaster casting to digital data files is rewriting the workflow for custom orthotics, enabling faster production cycles and superior patient-specific designs.
The European Union's Medical Device Regulation (MDR) imposes stricter requirements for clinical evidence and post-market surveillance. This regulation compels manufacturers to generate more robust data on the safety and performance of their podiatry equipment. Treatment units and surgical instruments are most affected, with firms investing significantly in updated clinical trials to maintain their CE marking and market access within Europe.
Value-based healthcare models are altering procurement decisions for podiatry equipment. Hospital administrators and large clinic networks now prioritize devices that demonstrate clear clinical outcomes and reduce long-term patient costs, moving away from simple unit-price considerations. This trend is most visible in the United States and parts of Western Europe, especially for technologies used in diabetic foot ulcer management and prevention.
Podiatry Equipment Market Segmentation
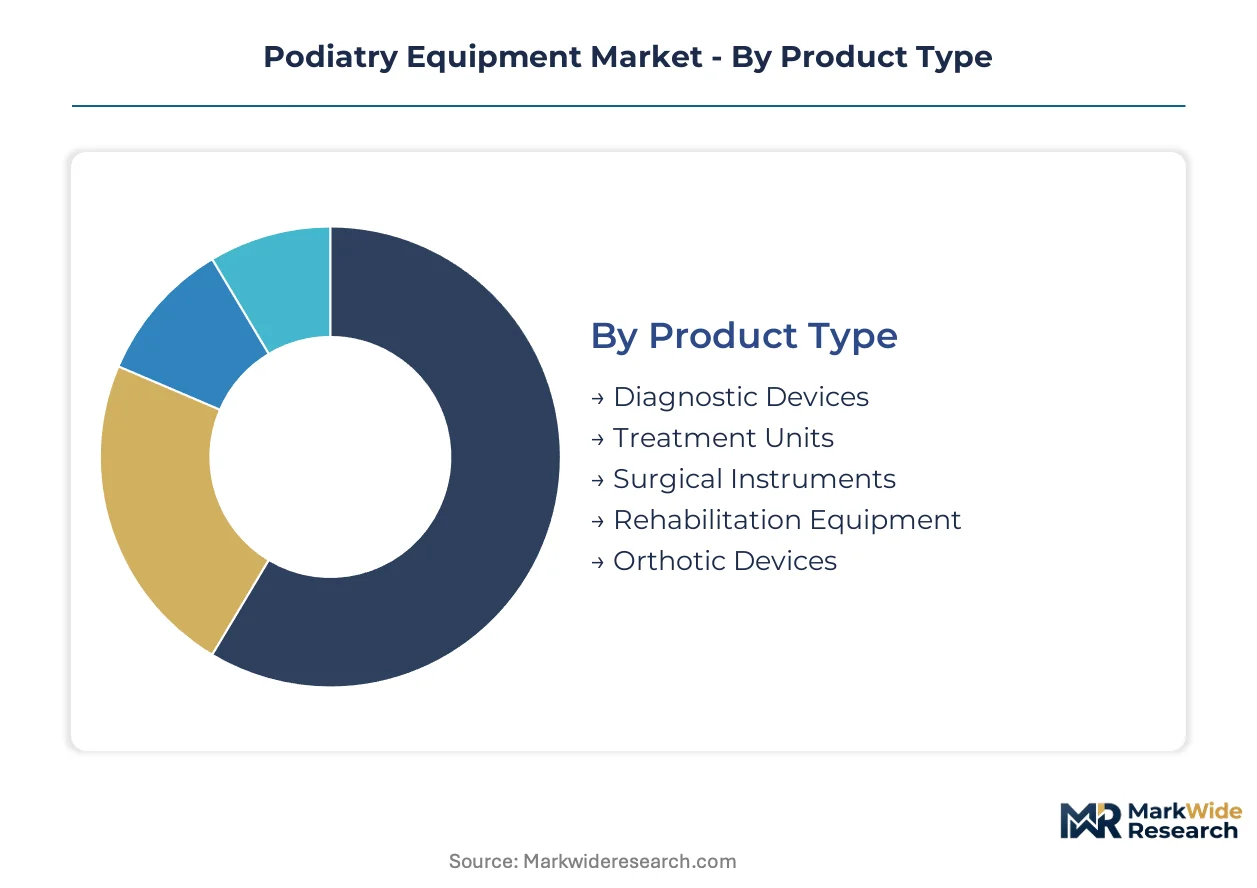
The podiatry equipment market segmentation reflects diverse clinical needs and technological advancements. Understanding these segments is crucial for manufacturers to tailor product development and for providers to optimize procurement strategies for specialized patient care.
Product Type:
The continuous upgrade and replacement cycles of medical devices significantly influence demand across product types.
- Diagnostic Devices:These instruments, including X-ray machines and advanced imaging systems, provide critical data for accurate pathology identification. Demand concentrates in specialized podiatry clinics seeking to enhance diagnostic precision for conditions like fractures and structural deformities.
- Treatment Units:Encompassing therapeutic lasers and shockwave therapy systems, these units deliver non-invasive or minimally invasive interventions. Adoption is high in facilities focused on tissue regeneration and pain management, particularly for chronic conditions.
- Surgical Instruments:This category includes scalpels, forceps, and specialized bone saws used in corrective and reconstructive foot and ankle surgery.
- Rehabilitation Equipment:Devices such as exercise machines, gait analysis systems, and balance trainers support post-operative recovery and injury prevention.
- Orthotic Devices:Custom and off-the-shelf inserts and braces provide support, correct biomechanical imbalances, and alleviate pain.
Diagnostic Devices sits at the top of the volume ranking, with Orthotic Devices climbing the fastest.
Technology:
Application-specific demands drive the evolution and adoption of various technologies within podiatry equipment.
- Digital Scanning:These systems capture precise 3D foot morphology data, enabling highly accurate custom orthotic fabrication and biomechanical analysis. Specialized orthotic laboratories and large podiatry clinics prioritize these systems for improved patient outcomes.
- Imaging Systems:Ranging from conventional X-ray to advanced MRI and CT, these technologies provide detailed anatomical visualization for diagnosis. Demand is robust in orthopedic centers and hospitals requiring comprehensive diagnostic capabilities for complex foot and ankle pathologies.
- Laser Therapy:Utilizing focused light for pain relief, anti-inflammatory effects, and tissue healing, these systems are employed in therapeutic applications.
- Biomechanical Analysis:Platforms that assess gait, pressure distribution, and movement patterns aid in diagnosing functional foot disorders and optimizing treatment plans.
- Ultrasonic:Diagnostic ultrasound devices offer real-time imaging of soft tissues, supporting guided injections and rapid assessment of conditions like plantar fasciitis.
Digital scanning technologies are gaining significant traction, particularly in custom orthotic fabrication.
Application:
Demographic shifts and disease prevalence heavily influence the demand for specific podiatry equipment applications.
- Diabetic Foot Care:This segment includes specialized diagnostic tools for neuropathy and vascular assessment, along with wound care devices and therapeutic footwear. The rising incidence of diabetes in the United States directly fuels the need for preventative and interventional solutions.
- Sports Injuries:Equipment for diagnosing and treating sprains, fractures, and overuse injuries, such as diagnostic ultrasound and shockwave therapy, falls into this category. Sports medicine facilities and rehabilitation centers are key adopters for athlete recovery.
- Foot Deformities:This application focuses on devices and instruments for correcting conditions like bunions, hammertoes, and flat feet.
- Nail Disorders:Lasers and specialized instruments address fungal infections, ingrown nails, and other common podiatric nail conditions.
- Wound Management:Advanced dressings, negative pressure wound therapy, and debridement tools are critical for treating chronic foot wounds, especially in diabetic patients.
The increasing prevalence of diabetes drives demand across diagnostic and therapeutic applications.
End User:
Specialized care delivery models dictate the type and volume of equipment purchased by various end-user facilities.
- Podiatry Clinics:These specialized outpatient facilities are primary purchasers of a wide array of diagnostic, therapeutic, and orthotic equipment. They invest in advanced digital scanning and laser therapy systems to offer comprehensive foot care services.
- Ambulatory Surgical Centers:ASCs acquire surgical instruments and related equipment for performing outpatient foot and ankle procedures. The shift towards less invasive surgeries drives their investment in specialized instrumentation.
- Rehabilitation Centers:These centers focus on post-injury or post-surgical recovery, utilizing equipment for physical therapy, gait analysis, and strength training.
- Orthopedic Centers:Offering a broader scope of musculoskeletal care, these centers integrate podiatry equipment for comprehensive lower limb diagnosis and treatment.
- Sports Medicine Facilities:Catering to athletes, these facilities use specialized diagnostic and therapeutic devices for sports-related foot and ankle injuries.
Specialized podiatry clinics remain central to patient care, while ambulatory surgical centers expand their procedural scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States demand for podiatry equipment remains strong due to its significant aging population and high diabetes prevalence. This demographic pressure drives continuous investment in advanced diagnostic and therapeutic solutions. European nations also prioritize foot health, while Asian economies expand their healthcare infrastructure.
United States
United States demand for podiatry equipment is substantial, driven by an aging population and high diabetes prevalence. The FDA's 510(k) clearance process guides market entry for new devices, ensuring safety standards. Boston's medical device hub fosters innovation in digital scanning and custom orthotic fabrication.
Germany
German healthcare providers exhibit strong demand for advanced podiatry solutions, responding to rising diabetes incidence. Adherence to the EU's Medical Device Regulation (MDR) ensures high quality and safety standards for equipment. Munich's medtech firms are actively developing next-generation therapeutic laser systems.
China
Chinese market expansion for podiatry equipment is fueled by developing healthcare infrastructure and increasing awareness of foot health. The NMPA regulates medical device approvals, influencing market access for foreign manufacturers. Shanghai's medical equipment manufacturing sector focuses on domestic production and innovation.
India
Indian healthcare advancements contribute to the growing demand for specialized podiatry equipment, particularly for diabetic foot care. The CDSCO oversees medical device regulations, impacting product development and market availability. Bengaluru's health tech startups are exploring tele-podiatry solutions for remote patient monitoring.
United Kingdom
United Kingdom demand for podiatry equipment is shaped by value-based healthcare models and chronic disease management. The MHRA ensures medical device compliance within the country, influencing procurement decisions. London's specialized podiatry clinics invest in advanced diagnostic imaging for comprehensive patient assessment.
Podiatry Equipment Market Key Industry Players
Global majors compete with regional champions across product innovation and distribution networks. The market structure exhibits a tiered approach, with large diversified players operating alongside specialized instrument manufacturers and niche technology providers. Strategic archetypes include rehabilitation equipment providers, high-precision instrument specialists, and crucial distribution channel managers. Portfolio diversification and strategic partnerships aimed at integrating digital health technologies represent dominant competitive moves.
Specialists in comprehensive foot care solutions include DJO Global, which leverages its portfolio in rehabilitation equipment to address sports injury applications. Henry Schein anchors crucial distribution channels, providing essential access to private podiatry clinics across various regions. NSK Ltd. exemplifies a focus on high-precision surgical instruments and drills, differentiating its offerings through advanced performance and technical accuracy for complex procedures. These players demonstrate varied approaches to market penetration and value creation within the diverse podiatry equipment landscape.
| Leading Market Players |
|---|
| DJO Global |
| A. Algeo Limited |
| Bauerfeind AG |
| Henry Schein |
| NAMROL Group |
| Vismara S.r.l. |
| NSK Ltd. |
| FAS Healthcare Ltd. |
| Huntleigh Healthcare |
| Others |
Cost & Logistics Intelligence
The divergence between high-precision surgical instruments and mass-produced orthotic components creates distinct pricing and supply chain structures in the podiatry equipment market. High-performance segments command premium pricing due to specialized materials and rigorous certification.
Pricing Analysis
Rising titanium alloy costs are passed through to premium surgical instrument prices. The dominant pricing model is per-unit transactional, with some value-based arrangements for integrated digital systems. Price differentiation stems from FDA 510(k) clearance and customization levels. Pricing softness affects mass-produced orthotics due to competition, making small clinics highly price-sensitive.
Supply Chain Analysis
EU Medical Device Regulation (MDR) requirements for robust clinical evidence are reshaping sourcing for European markets. Supply concentration for high-precision components centers on Germany and Japan, while mass-produced items source from China and India. Raw material dependencies include medical-grade plastics and specialized alloys like titanium. A structural risk is single-source vulnerability for advanced imaging sensors. Distribution runs through specialized medical distributors and direct sales channels to clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The podiatry equipment market presents a geographic-arbitrage opportunity, driven by varying regulatory approval timelines between the US FDA 510(k) process and the EU MDR. This creates distinct market entry points and cost structures for manufacturers.
For Market Incumbents:Hedge against the rising threat of digital health startups by deepening vertical integration into software platforms. Invest in R&D for AI-powered diagnostics and remote monitoring solutions to counter new entrant agility. Control crucial distribution channels through strategic partnerships with large clinic networks. Certify new products under both FDA 510(k) and EU MDR to maintain broad market access.
For New Entrants and Emerging Players:Digital 3D scanning technology offers a compelling wedge into the custom orthotics segment, particularly for specialized podiatry clinics. Target underpenetrated markets in Asia-Pacific where healthcare infrastructure is developing. A go-to-market angle involves offering integrated hardware-software bundles with subscription-based support, reducing upfront capital investment for practitioners. Focus on demonstrating superior clinical outcomes through rigorous data collection.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized technology providers offering digital scanning and AI-driven diagnostic solutions for the long term. Acquisition targets should prioritize firms with strong intellectual property in patient-specific treatment models and established clinical efficacy data. The signal to watch is accelerating adoption of tele-podiatry platforms, indicating a shift towards remote care delivery. Focus on companies with robust recurring revenue streams from software licenses.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-powered Diagnostic Software Launch | Enhances diagnostic precision and reduces clinician workload. |
| EHR System Integration Partnership | Streamlines clinical workflows and improves data continuity. |
| Geographic Expansion in Emerging Asia | Captures demand from developing healthcare infrastructure. |
| Value-based Care Model Advocacy | Aligns product offerings with payer incentives for procurement. |
| Acquisition of Digital Orthotics Lab | Deepens capabilities in patient-specific fabrication. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Interviews were conducted with podiatrists, hospital procurement managers, medical device engineers, and regulatory affairs specialists. Secondary data sources included FDA filings, EU MDR documentation, national health statistics, and medical journal databases. This approach facilitated robust bottom-up and top-down triangulation of market data.
The forecast window was anchored to historical reference periods, establishing baseline market performance and growth trajectories. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from an iterative process factoring in demographic shifts and technological adoption rates across the analysis window. Key forecast inputs included diabetes prevalence rates and medical device investment trends.
The model holds under current medical device regulatory stability and healthcare expenditure patterns; deviation in global economic downturns or unforeseen technological disruptions would shift projections. Forecasts reflect assumptions regarding clinical adoption rates and competitive dynamics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Global Refrigerated Incubators Market
Medical Equipment
Mortuary Refrigerator Market
Medical Equipment
Global Capnography Equipment Market
Medical Equipment
Orthopedic Operating Tables Market
Medical Equipment
Medical Equipment Management Software Market
Medical Equipment
Birthing Beds Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
India Massage Equipment Market
Medical Equipment
Global Gynecological Examination Chairs Market
Medical Equipment
Global Medical Lifting Slings Market
Medical Equipment
Medical Device and Equipment Tags Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Global Single-Arm Medical Pendant Market
Medical Equipment
Air Fluidized Therapy Beds Market
Medical Equipment
Stereotactic Biopsy Tables Market