
 India Electronic Security Market | 2026-2036
India Electronic Security Market Size, Share, and Industry Trends Forecast 2026-2036
India Electronic Security Market Outlook
Commercial enterprises and critical infrastructure operators is reorganizing demand patterns in the India Electronic Security Market, pulling investment away from basic residential installations. PRAMA Hikvision India Pvt. Ltd. dominates the CCTV camera segment through extensive local manufacturing and channel depth. Godrej Security Solution anchors the access control category with its long-standing institutional relationships and nationwide service coverage. Dahua Technology India Pvt. Ltd. competes aggressively on price-performance metrics in the IP surveillance tier.
Electronic security encompasses integrated systems for surveillance, access management, intrusion detection, and fire safety, typically operating through networked IP architectures with video analytics, biometric authentication, and centralized monitoring dashboards. The primary purpose is threat prevention, real-time incident response, and regulatory compliance for asset protection across physical and digital perimeters. CCTV Cameras constitute the largest product category by installed base, though biometric Access Control Systems command superior margins due to integration complexity and recurring software licensing. IP Surveillance is displacing Analog Cameras as the dominant technology platform, while Monitoring services generate the most predictable revenue streams within the service portfolio.
BIS mandates product certification for electronic security equipment, compelling manufacturers to align with national quality standards before market entry. CDSCO oversight intersects where biometric systems process health-adjacent data, while state-level police nodal agencies shape procurement specifications for city surveillance projects. Stakeholders must track how the PLI scheme for electronics manufacturing alters domestic production economics against import-dependent competitors.
Market Dynamics
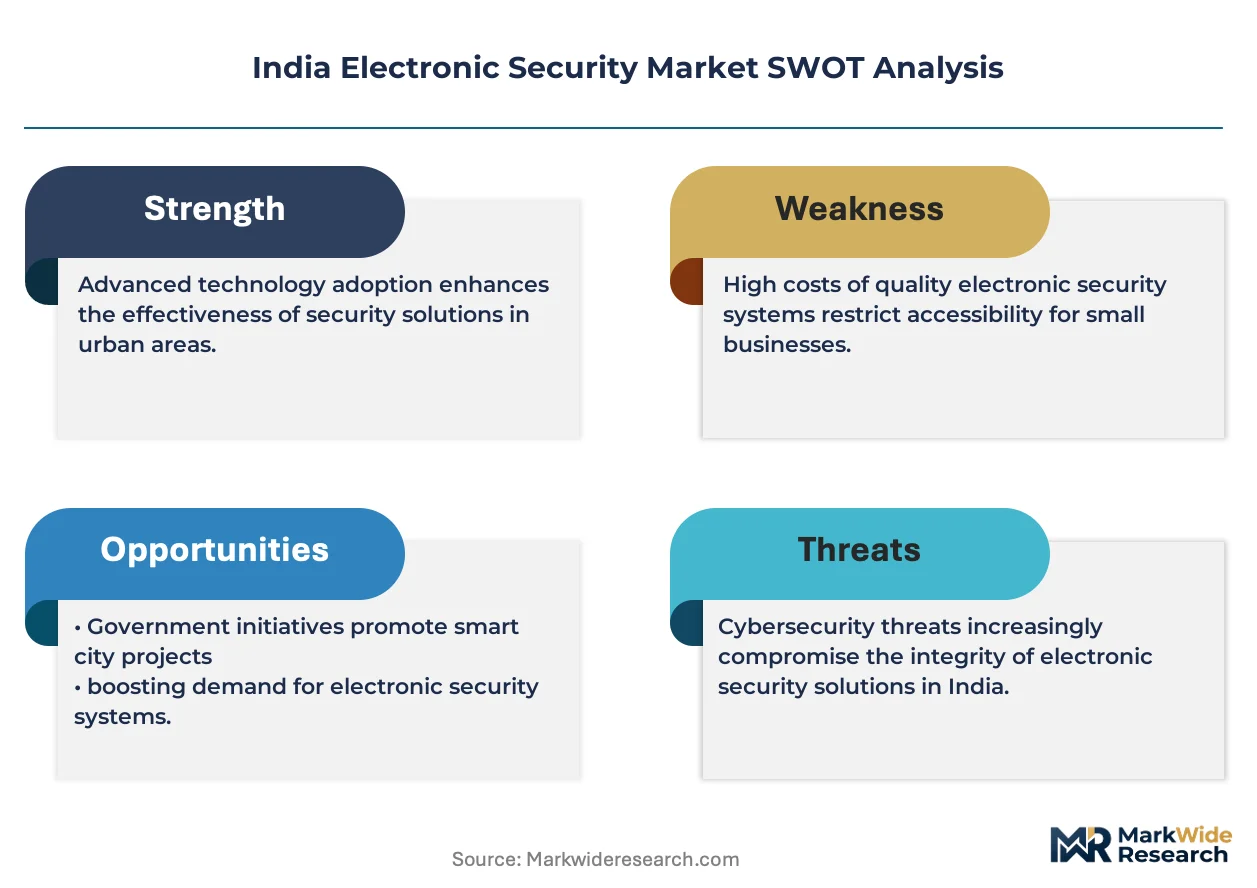
IP surveillance architectures are compressing installation timelines and collapsing the traditional analog-to-digital upgrade cycle across Indian commercial and government buyers. The BIS certification mandate and PLI scheme for electronics manufacturing are simultaneously raising entry barriers and reshaping domestic production economics.
Growth Catalysts
- Smart City Mission:Urban infrastructure projects in Maharashtra and Karnataka are mandating networked surveillance and biometric access systems for municipal command centers.
- BIS Certification Mandate:Compulsory quality standards for electronic security equipment are filtering out substandard imports and legitimizing certified domestic manufacturers.
- Data Center Expansion:Hyperscale facility construction in Chennai, Hyderabad, and Mumbai is driving demand for multi-layered physical security with integrated monitoring dashboards.
Market Restraints
- Semiconductor Input Volatility:Image sensors and edge processing chips face supply concentration risk from Taiwan and South Korean foundries.
- Skilled Integration Labor Shortage:Certified system integrators capable of IP-networked deployments remain concentrated in Delhi-NCR, Mumbai, and Bengaluru.
- Legacy Analog Lock-in:Existing coaxial infrastructure in tier-2 and tier-3 commercial estates slows full-platform replacement decisions.
Strategic Opportunities
- Underserved Tier-2 Cities:Surat, Indore, and Coimbatore retail corridors lack adequate electronic security penetration relative to transaction volumes.
- Convergence of Video Analytics and Biometrics:Facial recognition integrated with access control systems opens premium pricing in banking and pharmaceutical manufacturing.
- PLI Scheme Localization:Production-linked incentives for electronics manufacturing enable cost-competitive domestic assembly of cameras and control panels.
Industry Challenges
- BIS Certification Timeline Compression:Testing and approval cycles for new product variants lag behind rapid technology refresh rates.
- Interoperability with Legacy Analog:Hybrid system architectures demand specialized engineering talent that commands premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Electronic Security Market |
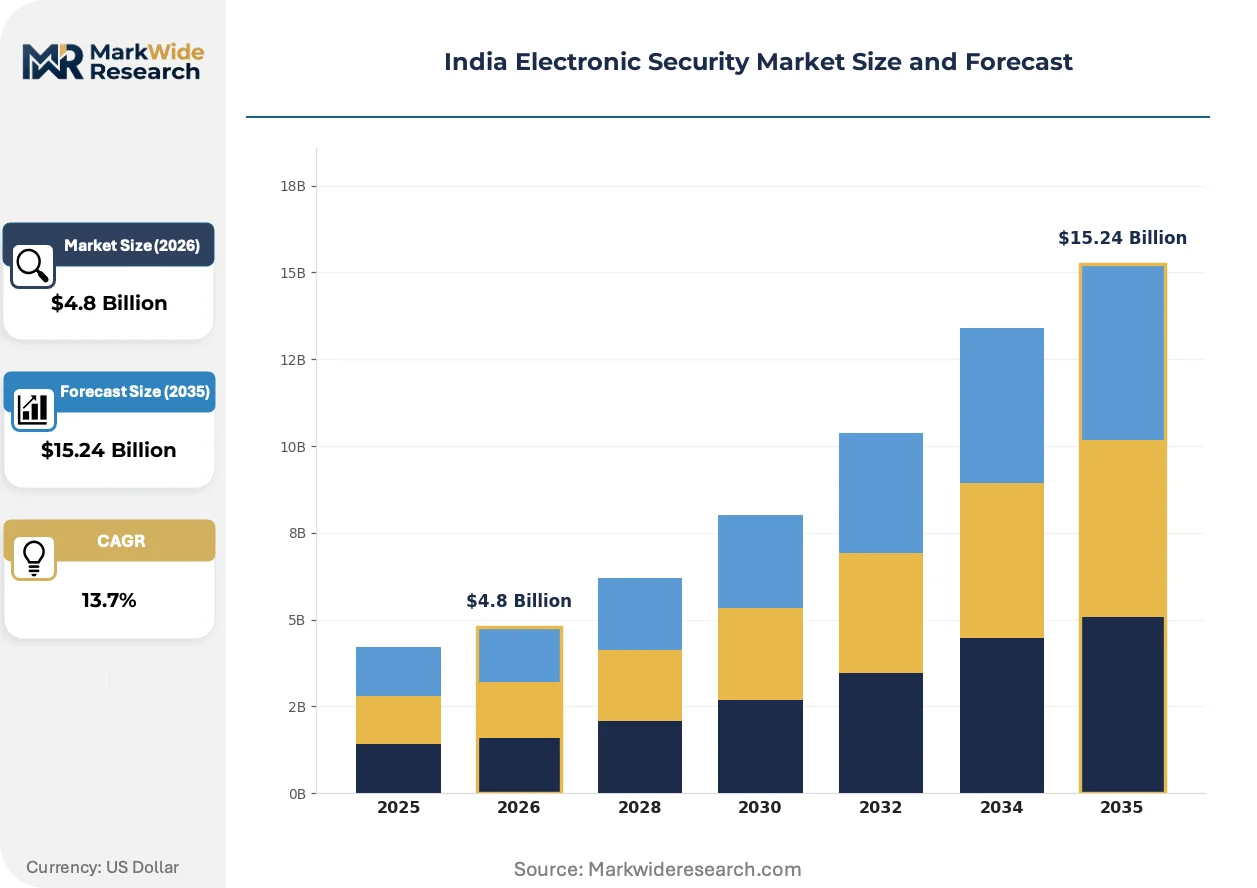
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CCTV Cameras, Access Control Systems, Intrusion Alarms, Fire Safety Systems End User: Residential, Commercial, Industrial, Government Technology: IP Surveillance, Analog Cameras, Biometrics, Wireless Systems Service Type: Installation, Maintenance, Monitoring, Consulting |
| Companies Covered | Honeywell International Inc., Sis Limited, PRAMA Hikvision India Pvt. Ltd., Godrej Security Solution, Zicom Electronic Security Systems Ltd, Dahua Technology India Pvt. Ltd., Bosch Ltd., Axis Communications AB, Aditya Infotech Ltd. (CP PLUS), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Electronic Security Market Strategic Shifts
Artificial intelligence at the network edge is rewriting performance benchmarks for threat detection and response latency. Three convergent developments are compressing the traditional security technology refresh cycle.
Edge-based video analytics is supplanting centralized server processing for real-time facial recognition and behavioral anomaly detection. Large-format retail chains and logistics hubs in Gujarat and Tamil Nadu are deploying these systems at scale. The shift is collapsing bandwidth requirements and enabling faster incident response without cloud dependency.
BIS certification protocols are tightening electromagnetic compatibility and cybersecurity testing requirements for IP-connected security devices. Manufacturers must now submit firmware vulnerability assessments alongside hardware specifications. This is lengthening product launch timelines but elevating trust premiums for certified equipment in government procurement.
Banking and pharmaceutical buyers are unbundling hardware purchase from monitoring service contracts. System integrators in Mumbai and Bengaluru are responding with subscription-based managed security offerings. This reconfiguration is visible most acutely in Maharashtra, where financial institutions prefer operational expenditure models over capital-intensive ownership.
India Electronic Security Market Segmentation
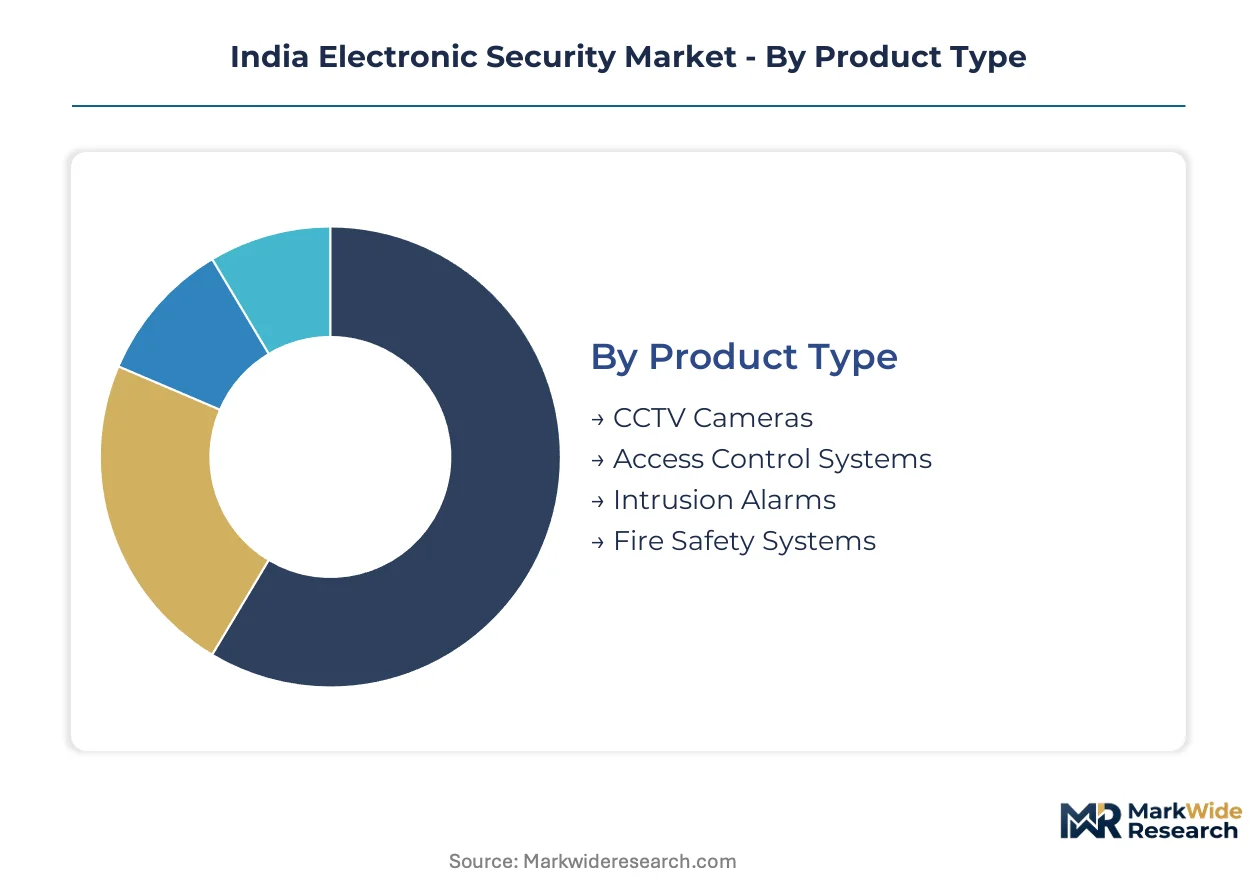
Segmentation in the India Electronic Security Market exposes how procurement priorities diverge between compliance-driven government buyers and margin-focused commercial operators. Understanding these fault lines clarifies where technology investments concentrate and which service models capture recurring revenue.
Product Type:
BIS certification requirements create asymmetric barriers across hardware categories, favoring domestic manufacturers with testing laboratory relationships and penalizing import-dependent product lines.
- CCTV Cameras:Networked IP cameras with edge analytics capabilities dominate new installations across Maharashtra and Karnataka smart city corridors. Municipal command centers in Mumbai and Pune are mandating ONVIF-compliant devices with centralized video management platforms, compressing procurement cycles for certified suppliers.
- Access Control Systems:Biometric readers and card-based entry systems integrate with workforce management software in IT parks and pharmaceutical manufacturing zones. Demand concentrates in Hyderabad's HITEC City and Bengaluru's Electronic City, where multi-tenant facilities require tenant-specific credential administration.
- Intrusion Alarms:Perimeter sensors and motion detectors with GSM connectivity serve residential colonies and small commercial establishments in tier-2 cities.
- Fire Safety Systems:Smoke detection and suppression equipment with building management system integration targets data centers and hospital infrastructure.
CCTV Cameras handles the majority of throughput; Access Control Systems is gaining share fastest on integration complexity and recurring software licensing.
End User:
Customer type determines contract structure, with government buyers favoring capital expenditure models and commercial operators shifting toward operational expenditure arrangements.
- Commercial:Retail chains, banking branches, and logistics warehouses in Gujarat and Tamil Nadu are deploying multi-layered security with video analytics and centralized monitoring. Large-format retail in Ahmedabad and Coimbatore is driving demand for facial recognition integrated with point-of-sale systems.
- Government:Smart city projects and critical infrastructure protection mandate BIS-certified equipment with domestic value-addition requirements. Municipal corporations in Surat and Indore are issuing tenders for city-wide surveillance networks with command center integration.
- Industrial:Manufacturing facilities and process plants require explosion-proof cameras and access control with time-attendance integration.
- Residential:Gated communities and apartment complexes in Delhi-NCR and Mumbai Metropolitan Region adopt DIY wireless systems with mobile app interfaces.
Commercial captures the dominant revenue share; Government is expanding most quickly on smart city mission allocations.
Technology:
Platform choice reflects infrastructure maturity, with greenfield installations favoring IP architectures and legacy estates confronting hybrid migration costs.
- IP Surveillance:Networked cameras with Power over Ethernet and edge processing capabilities are displacing analog infrastructure in new construction. Data center builds in Chennai and Hyderabad mandate IP-based physical security with API integration into facility management platforms.
- Biometrics:Fingerprint and facial recognition systems command premium pricing in banking and pharmaceutical manufacturing where regulatory compliance requires audit trails. Installations in Mumbai's financial district are integrating biometric access with HR systems for automated compliance reporting.
- Analog Cameras:Coaxial-based systems persist in tier-3 commercial estates with existing cable infrastructure.
- Wireless Systems:Cellular and WiFi-connected devices serve temporary deployments and remote monitoring applications.
IP Surveillance carries the volume base; Biometrics shows the steepest expansion trajectory on margin premiums.
Service Type:
Revenue model innovation is unbundling hardware from ongoing service relationships, with monitoring contracts generating predictable cash flows.
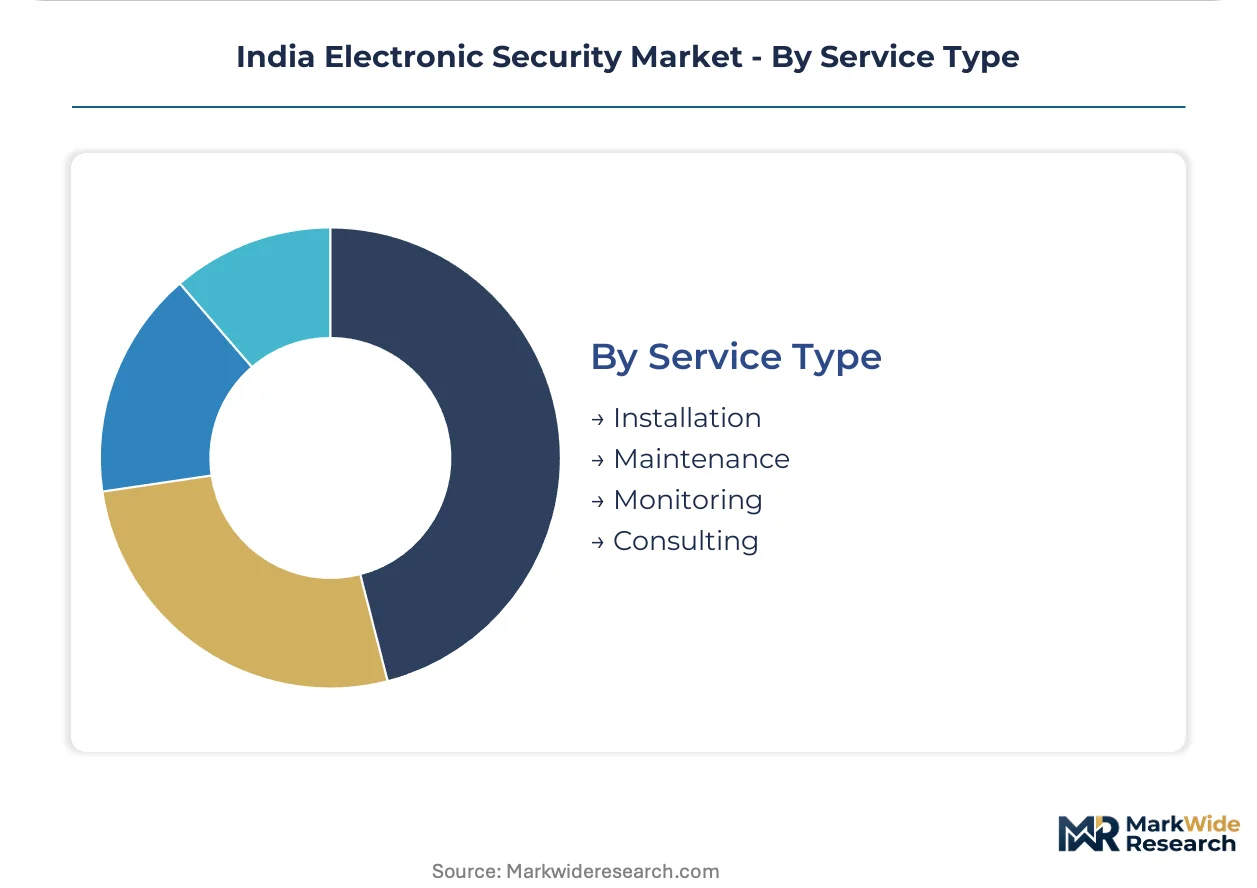
- Monitoring:Centralized surveillance with human operator oversight and automated alert escalation is shifting to subscription pricing. Banking institutions in Maharashtra are preferring per-location monthly fees over capital-intensive ownership, restructuring vendor economics toward recurring revenue.
- Installation:System integration with network configuration and calibration demands certified technicians concentrated in Delhi-NCR, Mumbai, and Bengaluru. Project timelines compress as IP architectures simplify cabling requirements versus legacy analog deployments.
- Maintenance:Preventive service contracts with firmware updates and hardware replacement clauses.
- Consulting:Security audits and risk assessment services for compliance with BIS standards and industry-specific regulations.
Installation commands the largest project value; Monitoring is climbing the fastest on operational expenditure preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial buyers concentrate in western and southern India, while government procurement clusters around smart city corridors in Maharashtra and Karnataka. BIS certification requirements and PLI scheme incentives are reshaping supplier geography toward domestic manufacturing hubs.
Maharashtra
Mumbai and Pune municipal corporations are deploying city-wide IP surveillance networks with integrated command centers. The state police nodal agency mandates BIS-certified equipment for all smart city tenders. Data center construction in Navi Mumbai and Thane is driving multi-layered physical security procurement with API-integrated monitoring dashboards.
Karnataka
Bengaluru's Electronic City and Whitefield IT corridors require tenant-specific biometric access systems for multi-tenant facilities. The state urban development department channels smart city mission funds toward networked surveillance infrastructure. Mysuru and Mangaluru are emerging as secondary deployment zones for retail and logistics security.
Gujarat
Ahmedabad and Surat retail corridors are deploying facial recognition integrated with point-of-sale systems for large-format chains. The state's industrial promotion policies attract electronic security system integrators to Gandhinagar and Vadodara manufacturing zones. GIFT City financial district mandates compliance-grade access control with audit trail capabilities.
Tamil Nadu
Chennai's hyperscale data center builds require IP-based physical security with facility management platform integration. Coimbatore's manufacturing and logistics hubs are adopting edge-based video analytics for behavioral anomaly detection. The state's electronics manufacturing policy aligns with PLI scheme incentives for domestic camera assembly.
Telangana
Hyderabad's HITEC City and Financial District demand biometric access control with HR system integration for automated compliance reporting. The state police department's city surveillance project specifications favor ONVIF-compliant IP cameras with centralized video management. Pharma manufacturing zones in Genome Valley require audit-trail-capable security systems.
India Electronic Security Market Competitive Environment
Player mix skews toward diversified conglomerates with security divisions alongside pure-play specialists. Market structure shows moderate consolidation at the premium tier with fragmented competition in mid-market segments. Two strategic archetypes dominate: integrated solution providers bundling hardware with monitoring services, and component specialists competing on price-performance metrics. Competitive moves center on PLI scheme leveraging for domestic manufacturing scale and subscription-based service model transitions.
Within the diversified conglomerate tier, Honeywell International Inc. and Godrej Security Solution exemplify players with long-standing institutional relationships and nationwide service coverage. Among pure-play specialists, PRAMA Hikvision India Pvt. Ltd. and Dahua Technology India Pvt. Ltd. occupy positions representing extensive local manufacturing and aggressive price-performance positioning respectively. Bosch Ltd. and Axis Communications AB sit within the premium-tier import-dependent segment where BIS certification timelines create competitive friction. Sis Limited and Zicom Electronic Security Systems Ltd. represent the monitoring-services archetype with recurring revenue models.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Sis Limited |
| PRAMA Hikvision India Pvt. Ltd. |
| Godrej Security Solution |
| Zicom Electronic Security Systems Ltd |
| Dahua Technology India Pvt. Ltd. |
| Bosch Ltd. |
| Axis Communications AB |
| Aditya Infotech Ltd. (CP PLUS) |
| Others |
Value Chain & Pricing Dynamics
IP camera sensor substitution for analog CCD modules is simultaneously compressing component costs and redrawing procurement geography toward Taiwan and South Korean foundries, while BIS certification requirements add compliance premiums that stratify final equipment pricing across domestic and import-dependent manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels tracks the analog-to-IP technology transition, with edge-analytics-enabled cameras commanding certification-grade premiums over legacy coaxial units. Price differentiation rests on BIS compliance status and software licensing depth, not hardware alone. Cost compression in the standard tier is intensifying because Dahua and Hikvision domestic assembly lines exploit PLI scheme benefits. Government smart city tenders show the least price sensitivity due to audit-trail mandates, while tier-2 retail chains exhibit acute sensitivity to upfront capital outlays.
Supply Chain Analysis
Taiwan Strait transit vulnerability underwrites concentrated risk for CMOS image sensor supply, with Sony and Omnivision wafer output feeding Indian assembly lines through Singapore and Hong Kong logistics nodes. Semiconductor inputs draw from Taiwan, South Korea, and Japan, while aluminum die-cast housings and lens assemblies source from China and Vietnam. Single-source vulnerability concentrates in 12nm and below edge-processing chips. Distribution runs through Delhi-NCR, Mumbai, and Bengaluru-based system integrators who bundle installation with monitoring service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Electronic Security Market sits at a regulatory-technology inflection where BIS mandates and PLI incentives are simultaneously accelerating domestic manufacturing scale and collapsing import-dependent margin structures.
For Market Incumbents: Compound channel depth in Maharashtra and Karnataka smart city corridors by embedding monitoring service subscriptions into municipal tender responses. Acquire certified system integrator capabilities in Hyderabad and Chennai to preempt semiconductor input volatility from disrupting project timelines. PLI scheme leverage in Gujarat assembly zones anchors cost position against price-aggressive Chinese competitors. For New Entrants and Emerging Players: Differentiate on facial recognition integration for pharmaceutical manufacturing and banking compliance use cases where audit-trail requirements sustain premium pricing. Target Surat, Indore, and Coimbatore retail corridors with hybrid analog-IP migration packages that minimize infrastructure replacement costs. Go-to-market through regional IT hardware distributors with existing SME relationships rather than direct enterprise sales. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors monitoring-service revenue models over hardware-centric valuations. Five-to-ten-year viability hinges on recurring software licensing attach rates and PLI scheme qualification status. Acquisition targets should demonstrate BIS laboratory relationships and municipal procurement track records. Watch PLI scheme beneficiary announcements as inflection indicators for domestic manufacturing economics.| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Localization | Production-linked incentives enable cost-competitive domestic camera assembly in Gujarat and Tamil Nadu zones. |
| Subscription-Based Monitoring | Per-location monthly fees restructure vendor economics toward recurring revenue in Maharashtra banking clusters. |
| Biometric-Video Convergence | Facial recognition integration with access control opens premium pricing in Mumbai financial district deployments. |
| Tier-2 City Expansion | Surat and Coimbatore retail corridors offer penetration gaps relative to transaction volumes and security spend. |
| BIS Certification Investment | Testing laboratory relationships filter substandard imports and legitimize certified equipment in government tenders. |
Study Parameters
Two parallel data streams informed the analysis: structured interviews with system integrators, municipal procurement officers, and data center facility managers across Delhi-NCR, Mumbai, Bengaluru, Hyderabad, and Chennai; and secondary validation against BIS certification records, PLI scheme beneficiary disclosures, state police nodal agency tender documents, and electronics manufacturing customs data. Bottom-up triangulation of installation project pipelines with top-down state-level smart city budget allocations anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-user archetype, technology platform, and service delivery model, with particular weighting for IP surveillance displacement rates and biometric adoption curves in regulated industries. CAGRs were derived from installed base turnover assumptions and technology refresh cycle compression observed in municipal and commercial deployments. Forecast inputs incorporated semiconductor supply lead time volatility and BIS certification timeline lag effects.
The analysis sits within stated boundaries; outcomes outside sustained PLI scheme funding and stable Taiwan semiconductor supply would require recalibration. Practitioners should keep alternative scenarios live as BIS testing capacity constraints and import tariff adjustments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security and Surveillance
Explosive Vapour Detector Market
Security and Surveillance
Global X-Ray Security Scanner Market
Security and Surveillance
Security Intelligence Market
Security and Surveillance
Global School and Campus Security Market
Security and Surveillance
Swimming Pool Alarm Market
Security and Surveillance
Signal Jammer Market
Security and Surveillance
Europe People Screening Market
Security and Surveillance
Global Cargo Inspection Market
Security and Surveillance
Crowdsourced Security Market
Security and Surveillance
Air Cargo Security Equipment Market
Security and Surveillance
Face Smart Lockers Market
Security and Surveillance
Europe Anti-Piracy Protection Market
Security and Surveillance
Commercial Security Market
Security and Surveillance
Global Security Advisory Services Market
Security and Surveillance
Electronic Alarms Market
Security and Surveillance
Security Holograms Market