
 Audio Capacitor Market | 2026-2036
Audio Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
Audio Capacitor Market Outlook
Software-defined audio tuning and firmware-upgradable crossover networks is hardening as a recurring revenue layer atop hardware sales. Panasonic sustains manufacturing scale across radial and surface-mount lines for professional audio OEMs. Nichicon anchors premium electrolytic supply for Japanese high-fidelity brands. KEMET (YAGEO) competes through ceramic specialization in compact consumer electronics where space constraints dominate design.
An audio capacitor stores and releases electrical energy in passive circuits, with typical capacitance values spanning picofarads to millifarads and voltage ratings from 6.3V to 100V depending on dielectric material and construction. Electrolytic variants use aluminum oxide layers for high capacitance density in power supply filtering, while film capacitors employ polypropylene or polyester dielectrics for low distortion in signal paths. Electrolytic types lead in automotive audio due to bulk energy storage demands under engine-bay thermal stress. Ceramic segments dominate consumer electronics where miniaturization and surface-mount compatibility reduce assembly cost. Film capacitors command margin pools in professional audio where phase linearity and thermal stability justify premium positioning.
Japan's METI enforces JIS standards for electronic component reliability that shape export qualification requirements for audio capacitors bound for integrated amplifier manufacturers. China's SAMR administers GB standards and dual carbon goals that restrict electrolyte formulations and mandate energy-efficient production audits. REACH and RoHS in Europe limit hazardous substances in dielectric coatings and termination finishes. Stakeholders must monitor how evolving material compliance rules interact with capacitance density roadmaps and thermal performance benchmarks across next-generation audio platforms.
Market Dynamics
Automotive audio electrification is compressing design cycles as electric vehicle platforms eliminate engine noise masking, forcing capacitor manufacturers to engineer thermal-stable components for cabin-integrated amplifier modules.
Growth Catalysts
- China's dual carbon goals:GB standards for electronic components are tightening material purity requirements, accelerating replacement demand for legacy electrolytic stock across East Asian manufacturing clusters.
- Software-defined audio tuning:Firmware-upgradable crossover networks are hardening as a recurring revenue layer atop hardware sales, pulling premium film capacitor demand from professional audio OEMs.
- Electric vehicle platform expansion:Automotive audio systems now require bulk energy storage components that withstand engine-bay thermal stress without aluminum oxide degradation.
Market Restraints
- Aluminum foil supply concentration:Electrolytic anode foil production concentrates in Japanese and Chinese smelters, creating input cost volatility when energy prices spike.
- REACH substance restrictions:ECHA limitations on hazardous dielectric coatings force reformulation of termination finishes, adding certification friction for European-bound shipments.
- Ceramic capacitance density limits:Barium titanate dielectrics face physical constraints in high-voltage audio filtering applications, ceding share to bulkier film alternatives.
Strategic Opportunities
- South Korean EV audio integration:Hyundai and Kia platform consolidation creates captive demand for thermally ruggedized capacitor modules in premium cabin systems.
- India's PLI scheme for electronics:Component manufacturing incentives are attracting electrolytic assembly lines previously concentrated in coastal China.
- Polypropylene film convergence with GaN amplifiers:Gallium nitride switching speeds demand phase-linear signal path components that polyester dielectrics cannot match.
Industry Challenges
- Electrolyte formulation chemist scarcity:Specialized expertise in ethylene glycol and boric acid blends for high-temperature audio applications concentrates at aging Japanese technical institutes.
- JIS certification timeline compression:METI reliability standards require extended thermal cycling tests that delay new product qualification for integrated amplifier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Audio Capacitor Market |
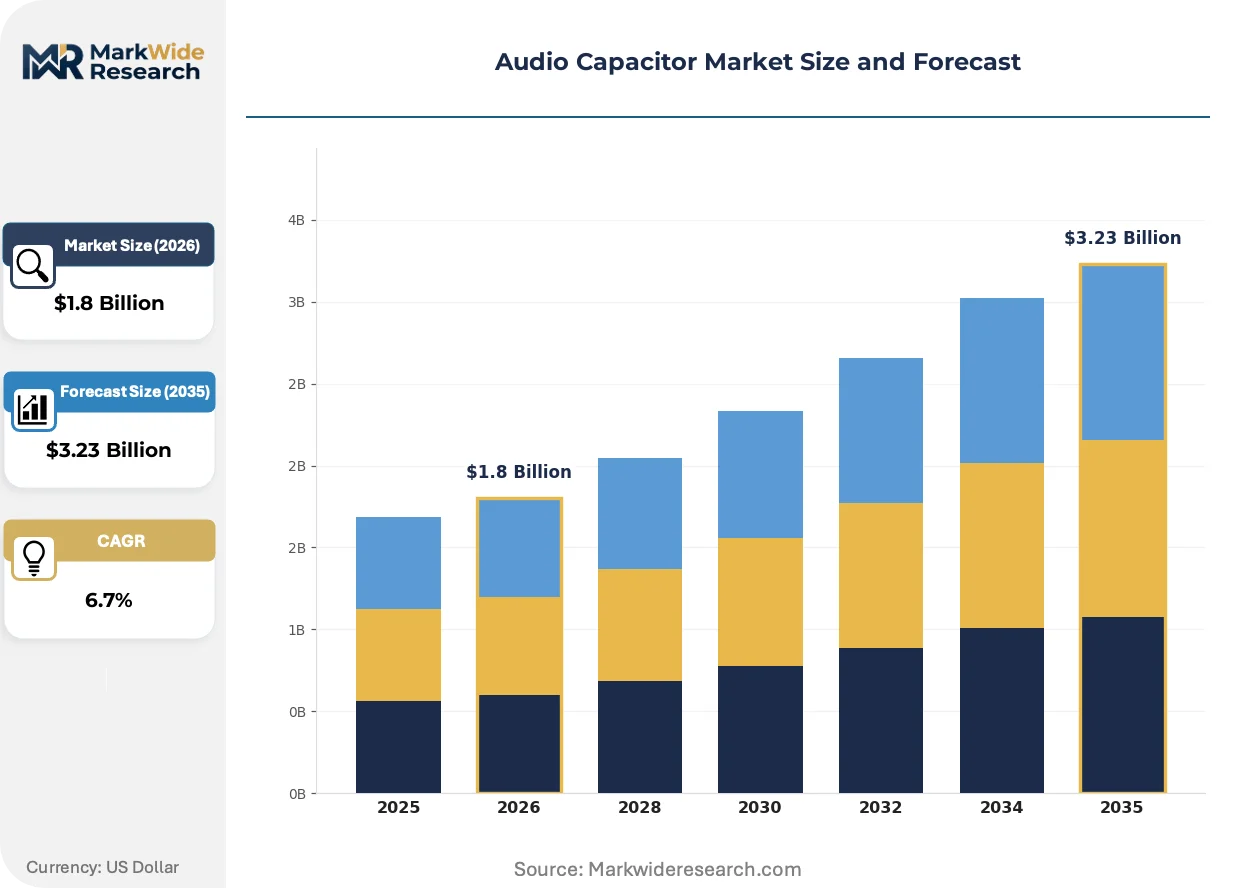
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electrolytic, Ceramic, Film, Tantalum Application: Consumer Electronics, Industrial Equipment, Automotive Audio, Professional Audio Form Factor: Surface Mount, Through Hole, Axial, Radial Capacitance Value: Low Capacitance, Medium Capacitance, High Capacitance, Ultra High Capacitance |
| Companies Covered | Nichicon, Panasonic, ELNA, KEMET (YAGEO), Nippon Chemi-Con, Cornell Dubilier Electronics, TDK Corporation, Vishay, Rubycon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Audio Capacitor Market Strategic Shifts
Capacitor technology is bifurcating between miniaturized surface-mount ceramics for portable devices and thermally engineered film constructions for fixed installations, with material science advances driving both tracks simultaneously.
Polypropylene metallized film technology is electrifying professional audio crossover design. High-end loudspeaker manufacturers in Germany and Japan are adopting segmented electrode patterns that self-heal during voltage spikes. This construction is compressing field failure rates below electrolytic alternatives while commanding margin pools that justify premium positioning.
REACH and RoHS amendments in Europe are restricting halogenated flame retardants in capacitor encapsulants. ECHA substance evaluations now cover brominated compounds previously standard in polyester film coatings. Automotive audio suppliers serving German OEMs are accelerating migration to phosphorus-based alternatives, with qualification timelines extending component release cycles.
After-sales firmware updates are unbundling hardware replacement cycles. Professional audio rental houses now prioritize capacitors rated for decade-long service intervals over initial cost minimization. This preference shift concentrates procurement authority with technical directors in Japan and South Korea who specify JIS-certified components for touring systems.
Audio Capacitor Market Segmentation
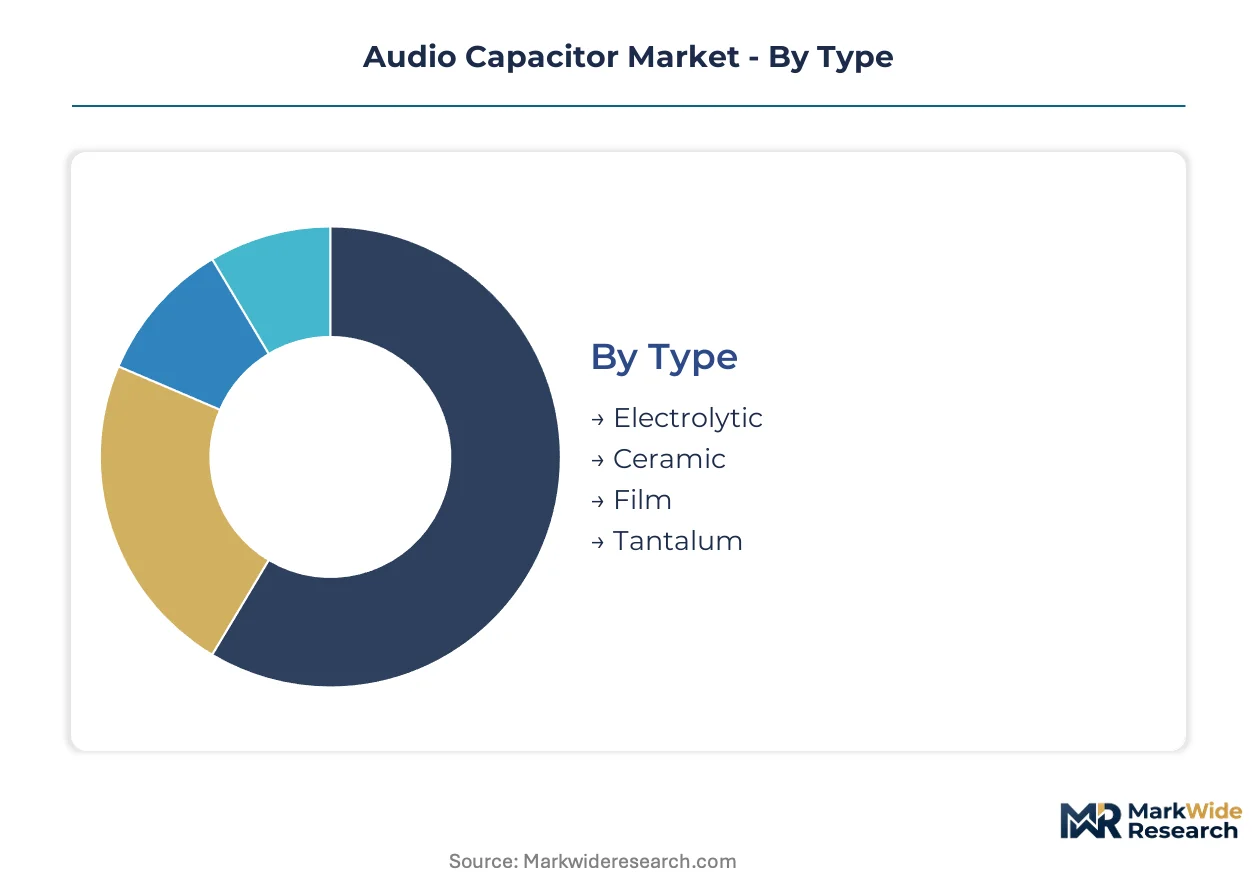
Audio capacitor procurement splits across four structural axes that determine certification burdens, thermal specifications, and margin capture. Each segmentation layer filters which manufacturers qualify for automotive OEM supply versus professional audio integration.
Type:
Electrolytic and film variants carry the heaviest certification loads for automotive and professional audio, while ceramic and tantalum face lighter REACH and RoHS screening for consumer electronics.
- Electrolytic:Aluminum oxide dielectric layers deliver high capacitance density for power supply filtering in engine-bay amplifier modules. Demand concentrates with Hyundai and Kia platform suppliers in South Korea where thermal cycling requirements exceed 150°C operational thresholds.
- Film:Polypropylene and polyester dielectrics achieve phase linearity for crossover networks in German and Japanese high-fidelity loudspeaker systems. Japanese METI JIS certification extends qualification timelines for integrated amplifier manufacturers sourcing segmented electrode constructions.
- Ceramic:Barium titanate formulations dominate surface-mount consumer electronics where miniaturization reduces assembly cost in Shenzhen and Dongguan manufacturing clusters.
- Tantalum:Manganese dioxide cathodes serve compact portable devices requiring stable capacitance across temperature swings in South Korean smartphone supply chains.
Electrolytic sits at the top of the volume ranking, with film climbing the fastest.
Application:
Automotive audio demands the most rigorous thermal and vibration specifications, while professional audio prioritizes decade-long service intervals over initial cost.
- Automotive Audio:Electric vehicle platforms eliminate engine noise masking, forcing bulk energy storage components that withstand cabin-integrated thermal stress without aluminum oxide degradation. South Korean EV audio integration at Hyundai and Kia creates captive demand for ruggedized modules.
- Professional Audio:Firmware-upgradable crossover networks harden as recurring revenue layers, pulling premium film capacitor procurement toward technical directors in Japan and South Korea who specify JIS-certified components for touring systems.
- Consumer Electronics:Miniaturization drives ceramic specialization in compact devices where space constraints dominate design decisions across East Asian manufacturing.
- Industrial Equipment:Extended service intervals prioritize reliability over cost in factory automation systems requiring stable filtering across voltage fluctuations.
Automotive audio commands the steepest expansion trajectory, while consumer electronics maintains volume dominance.
Form Factor:
Surface-mount compatibility reduces labor cost in high-volume consumer assembly, while through-hole and radial constructions serve repairable professional and industrial installations.
- Surface Mount:Pick-and-place automation compatibility dominates smartphone and portable device production in Shenzhen electronics clusters.
- Through Hole:Manual soldering accessibility supports aftermarket repair channels for vintage audio equipment in European and North American markets.
- Axial:Cylindrical lead configurations suit vintage guitar amplifier restorations where original footprint preservation matters.
- Radial:Vertical lead arrangements maximize board density in automotive amplifier modules where height constraints intersect with vibration resistance requirements.
Surface mount leads absolute shipment volumes, with radial gaining share fastest in automotive integration.
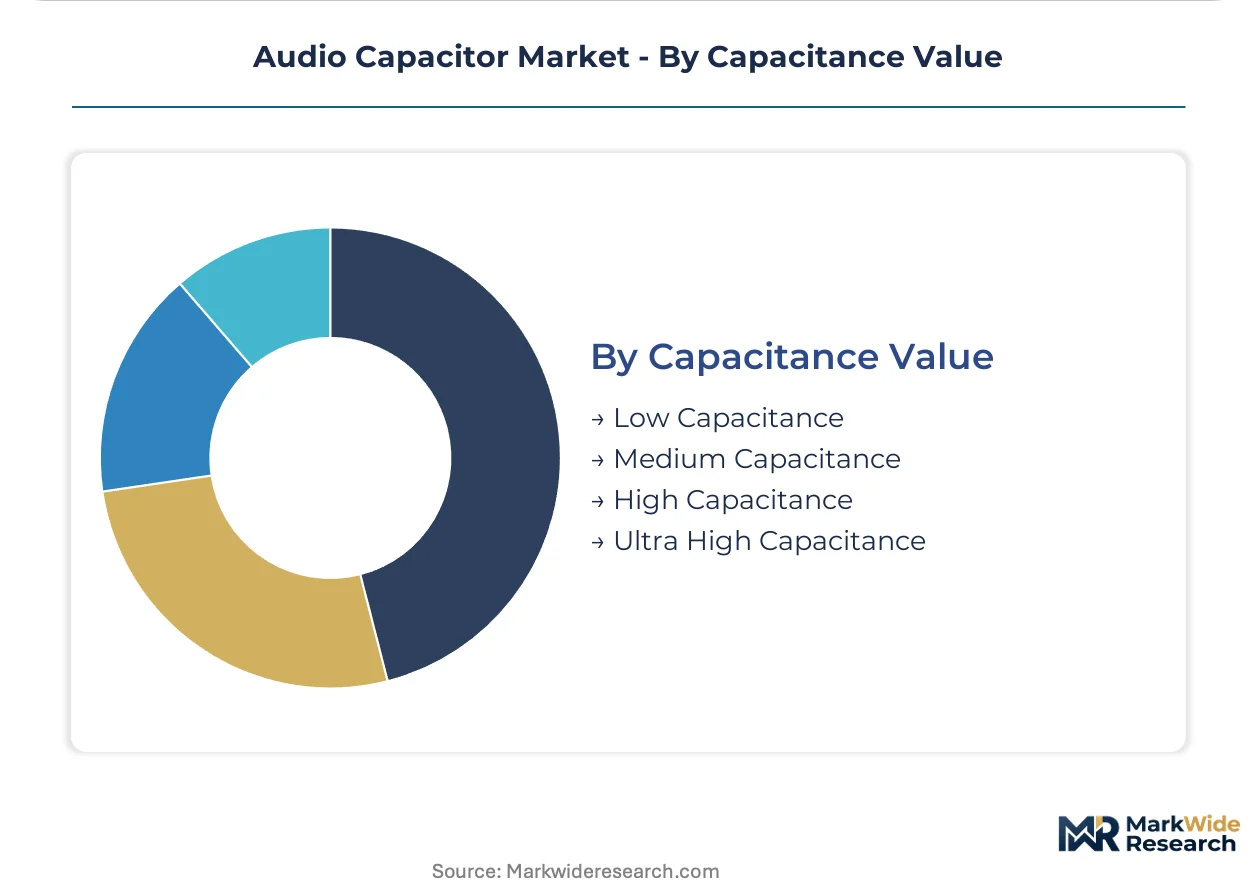
Capacitance Value:
Ultra-high and high capacitance segments face the most severe aluminum foil supply concentration risks, while low capacitance ceramic alternatives escape raw material volatility.
- Ultra High Capacitance:Millifarad-range electrolytic units filter power rails in EV audio systems where bulk energy storage stabilizes amplifier draw during transient peaks.
- High Capacitance:Sub-millifarad aluminum electrolytics serve subwoofer amplifier stages in premium cabin systems requiring sustained current delivery.
- Medium Capacitance:Microfarad-range film and ceramic hybrids balance signal path integrity with board space constraints in mid-tier consumer electronics.
- Low Capacitance:Picofarad to nanofarad ceramics dominate high-frequency decoupling in compact wireless audio devices where GaN amplifier switching speeds demand phase-linear response.
High capacitance anchors revenue concentration, with ultra high capacitance expanding most quickly alongside EV platform proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the densest capacitor production infrastructure globally, while Japan maintains tighter certification standards that shape export qualification requirements for integrated amplifier manufacturers worldwide.
China
Electric vehicle platform expansion at BYD and NIO generates captive demand for thermally ruggedized electrolytic modules in cabin-integrated amplifier systems. SAMR-administered GB standards and dual carbon goals restrict electrolyte formulations while mandating energy-efficient production audits across Guangdong and Jiangsu manufacturing clusters. Shenzhen and Dongguan electronics hubs concentrate surface-mount ceramic assembly lines serving compact consumer device OEMs.
Japan
High-fidelity loudspeaker manufacturers in Tokyo and Osaka pull premium film capacitor procurement toward segmented electrode constructions with self-healing metallized layers. METI enforces JIS reliability standards requiring extended thermal cycling tests that delay new product qualification timelines. Nagoya and Kyoto technical institutes retain scarce expertise in ethylene glycol and boric acid electrolyte blends for high-temperature audio applications.
South Korea
Hyundai and Kia platform consolidation creates dedicated demand streams for radial-form-factor capacitors in premium EV cabin systems. MFDS-aligned component traceability requirements intersect with automotive OEM vibration resistance specifications. Busan-Ulsan manufacturing corridors host assembly lines supplying thermally stable modules for engine-bay amplifier installations.
Germany
ECHA REACH restrictions on halogenated flame retardants in polyester film coatings force reformulation of termination finishes for automotive audio suppliers serving BMW and Mercedes-Benz. EU Green Deal carbon border adjustments add certification friction for electrolytic imports from East Asian smelters. Bavarian industrial clusters concentrate professional audio crossover network manufacturers specifying phase-linear polypropylene dielectrics.
United States
Vintage guitar amplifier restoration channels in Nashville and Los Angeles sustain aftermarket demand for axial-lead electrolytic constructions preserving original footprint specifications. EPA industrial emissions standards shape capacitor encapsulant chemistry decisions for domestic assembly operations. Austin and Boston electronics design hubs prototype GaN amplifier systems requiring low-capacitance ceramic decoupling components.
Audio Capacitor Market Competitive Environment
Top-tier vendors anchor professional audio and automotive OEM supply chains, while mid-tier specialists populate consumer electronics procurement channels with surface-mount ceramic alternatives. The vendor base stratifies across three functional tiers: integrated conglomerates with radial and surface-mount line breadth, dielectric specialists commanding premium positioning in signal-path applications, and scale-driven assemblers serving high-volume consumer device contracts. Competitive maneuvering concentrates on backward integration into aluminum foil supply and JIS certification timeline acceleration.
Within the integrated conglomerate tier, Panasonic and Nichicon occupy positions spanning professional audio OEM and automotive module supply. Nichicon exemplifies the electrolytic specialist archetype anchored in Japanese high-fidelity brand relationships. KEMET (YAGEO) represents ceramic specialization for compact consumer electronics where space constraints dominate design decisions. Cornell Dubilier Electronics sits within the North American fabricator group serving industrial and professional audio crossover applications with film construction expertise.
| Leading Market Players |
|---|
| Nichicon |
| Panasonic |
| ELNA |
| KEMET (YAGEO) |
| Nippon Chemi-Con |
| Cornell Dubilier Electronics |
| TDK Corporation |
| Vishay |
| Rubycon |
| Others |
Value Chain & Pricing Dynamics
Aluminum foil spot indices from Japanese and Chinese smelters cascade through electrolytic capacitor manufacturing into three-tier pricing structures across premium, standard, and economy levels. JIS-certified film constructions for professional audio OEMs capture margin pools that commodity ceramic grades cannot access, while GB standards compliance costs in China compress price floors for regional export-bound inventory.
Pricing Analysis
Capacity additions in India's PLI-supported electronics corridors are reshaping price floors for standard-grade electrolytic assemblies previously concentrated in coastal China. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified segmented electrode film from industrial-grade ceramic and unqualified electrolytic alternatives. Price differentiation hinges on METI certification timelines and aluminum foil purity grades, with cost compression in standard tiers intensifying because of energy price volatility at East Asian smelters. Automotive OEM procurement teams exhibit lowest price sensitivity, while consumer electronics contract manufacturers in Shenzhen electronics clusters prioritize unit cost minimization above thermal performance headroom.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for electrolytic assembly lines migrating from Guangdong province. Aluminum foil supply concentrates in Japanese and Chinese smelters, with ethylene glycol electrolyte blends and polypropylene film dielectrics drawing from specialty chemical producers in Nagoya and Ulsan. Single-source vulnerability runs through Japanese anode foil producers serving high-reliability automotive audio modules. Distribution runs through Tier 1 supplier consolidation at Hyundai and Kia platform integrators in South Korea, with aftermarket channels feeding vintage amplifier restoration demand in Nashville and Los Angeles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between China's dual carbon audit costs and India's PLI incentive structures creates margin capture opportunities for electrolytic assembly relocation. SAMR energy-efficiency mandates raise production costs in Jiangsu clusters while Indian component manufacturing incentives attract capacity migration.
For Market Incumbents: Acquire captive aluminum foil rolling capacity to offset energy price volatility at Japanese and Chinese smelters. Backward integration into anode foil production defends margin position against ceramic substitution in consumer electronics, while accelerated JIS certification investments protect professional audio procurement relationships from South Korean film capacitor specialists. For New Entrants and Emerging Players: Direct-to-technical-director digital channels bypass incumbent distributor relationships in Japanese and South Korean professional audio markets. White-space opportunity concentrates in firmware-upgradable crossover network aftermarket services, with GaN amplifier integration demand creating entry points for phase-linear polypropylene film specialists lacking legacy electrolytic baggage. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier film capacitor fabricators possessing JIS certification capability but lacking automotive OEM scale. Five-to-ten year viability favors dielectric specialists over commodity ceramic assemblers, with acquisition targets clustering around segmented electrode metallization expertise. The inflection signal to watch is Hyundai and Kia platform standardization timelines for EV cabin audio modules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Foil | Captive anode foil supply insulates margin from Japanese smelter energy cost spikes. |
| JIS Certification Acceleration | Compressed METI thermal cycling timelines unlock professional audio OEM procurement access. |
| GaN Amplifier Component Development | Phase-linear polypropylene film positions for next-generation switching speed requirements. |
| India PLI Corridor Manufacturing | Domestic-content compliance captures automotive audio module contracts migrating from China. |
| Firmware-Upgrade Service Bundling | Recurring revenue layers atop hardware sales extend customer lifetime value in professional audio. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with capacitor procurement managers at automotive Tier 1 suppliers, technical directors at Japanese professional audio OEMs, and electrolyte formulation chemists at Nagoya technical institutes. Secondary validation drew from METI JIS standard filings, SAMR GB compliance bulletins, ECHA REACH substance evaluations, and customs trade data for aluminum foil imports. Bottom-up segment sizing and top-down macro anchoring triangulated volume and value estimates.
Historical reference periods anchored the projection horizon through electrolytic and film capacitor shipment tracking across automotive, professional audio, and consumer electronics end-uses. Segmentation dimensions modeled include dielectric material type, form factor compatibility, capacitance value tier, and regional manufacturing cluster. CAGRs derived from segment-level growth rate blending, with forecast inputs incorporating EV platform proliferation timelines and GaN amplifier adoption curves in premium audio systems.
The model assumes a particular technology adoption path; alternative pathways for solid-state capacitor substitution would alter the outlook for aluminum electrolytic demand in engine-bay applications. Forecasts reflect assumptions around JIS certification timeline stability, aluminum foil supply concentration persistence, and REACH substance restriction enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Operational Amplifier Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
Global DC Motor Control Devices Market
Electronic Components
Audio DSP Market
Electronic Components
Data Acquisition Card Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
AC Adapter Market
Electronic Components
Solder Paste for Mini LED Market
Electronic Components
Fixed Capacitor Market
Electronic Components
Global Circuit Protection Market
Electronic Components
Camera Battery Charger Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
Power Resistor Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Global Capacitor Market