
 Bonding Wires and Ribbons Market | 2026-2036
Bonding Wires and Ribbons Market Size, Share, and Industry Trends Forecast 2026-2036
Bonding Wires and Ribbons Market Insights
Copper-to-silicon interconnection migration is reconfiguring bonding wire specifications across power and RF device portfolios. Heraeus sustains technology leadership through precision alloy development for fine-pitch applications. Sumitomo Metal Mining dominates precious metal feedstock integration from mine to drawn wire. Tanaka specializes in ultra-fine diameter gold and copper products for high-reliability semiconductor packages.
Bonding wires and ribbons are metallic conductors, typically 15-50 micrometers in diameter for wires and 0.2-2.0 millimeters in width for ribbons, drawn from high-purity gold, aluminum, copper, or silver and surface-treated for oxidation resistance and bondability, serving as electrical and mechanical interconnections between semiconductor dies and package leads or substrates. Aluminum wire retains cost advantage in legacy automotive and industrial power modules where thermal cycling tolerance outweighs conductivity gains. Copper ribbon captures margin pools in power device and hybrid module segments where current-carrying capacity and thermal performance command premium positioning over gold alternatives.
China's MIIT enforces GB standards on electronic-grade copper purity and wire mechanical properties that constrain import eligibility and shape domestic supplier qualification protocols. The EU REACH regulation and RoHS directive limit cadmium and lead content in surface coatings, compelling wire manufacturers to reformulate plating chemistries and document substance compliance across supply chains. Japan's METI coordinates JIS standards with PMDA quality frameworks for medical device interconnects, creating dual-certification requirements for ribbon suppliers serving diagnostic imaging OEMs. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied carbon tracking reshape smelter energy sourcing and wire carbon footprint disclosures.
Market Dynamics
Copper ribbon migration from gold interconnections is compressing material cost structures while forcing recalibration of wire bonding equipment and process parameters across power semiconductor packaging lines.
Growth Catalysts
- Power Module Assembly Expansion:Electric vehicle traction inverters and renewable energy converters demand copper ribbon's superior current density, pulling wire specifications toward wider gauge and enhanced thermal cycling performance.
- EU RoHS Compliance Deadlines:Hazardous substance restrictions on lead-bearing coatings accelerate reformulation of plating chemistries toward pure tin and silver finishes in automotive-qualified interconnects.
- East Asian Foundry Clustering:Taiwan and South Korea semiconductor packaging capacity additions concentrate procurement volumes, creating dedicated supply agreements for high-purity copper feedstock.
Market Restraints
- Copper Price Volatility:London Metal Exchange copper futures swings compress margin predictability for drawn wire producers holding 60-90 day raw material inventories.
- Smelter Concentration:Chilean and Peruvian mine output disruptions transmit directly to electronic-grade cathode availability, constraining qualified feedstock for ultra-pure ribbon drawing.
- Gold Substitution Ceiling:High-reliability aerospace and medical device segments retain gold wire for corrosion immunity, limiting copper penetration in hermetic package categories.
Strategic Opportunities
- India Semiconductor Mission:Domestic packaging incentives under the PLI scheme create qualification pathways for copper ribbon suppliers establishing local drawing and surface treatment operations.
- Silver-Coated Copper Convergence:Hybrid metallization combines copper conductivity with silver bondability, opening RF device and LED segments previously locked to solid precious metal solutions.
- Carbon Disclosure Mandates:EU CSRD reporting requirements favor wire suppliers with documented smelter renewable energy sourcing, creating differentiation in OEM sustainability scorecards.
Industry Challenges
- Bonding Process Engineering Gap:Copper ribbon implementation demands recalibration of ultrasonic bonding parameters, creating bottlenecks where packaging houses lack in-house metallurgical expertise.
- Dual Certification Timelines:Medical device interconnects require simultaneous JIS standards compliance and PMDA quality framework alignment, extending qualification cycles for diagnostic imaging OEM supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bonding Wires and Ribbons Market |
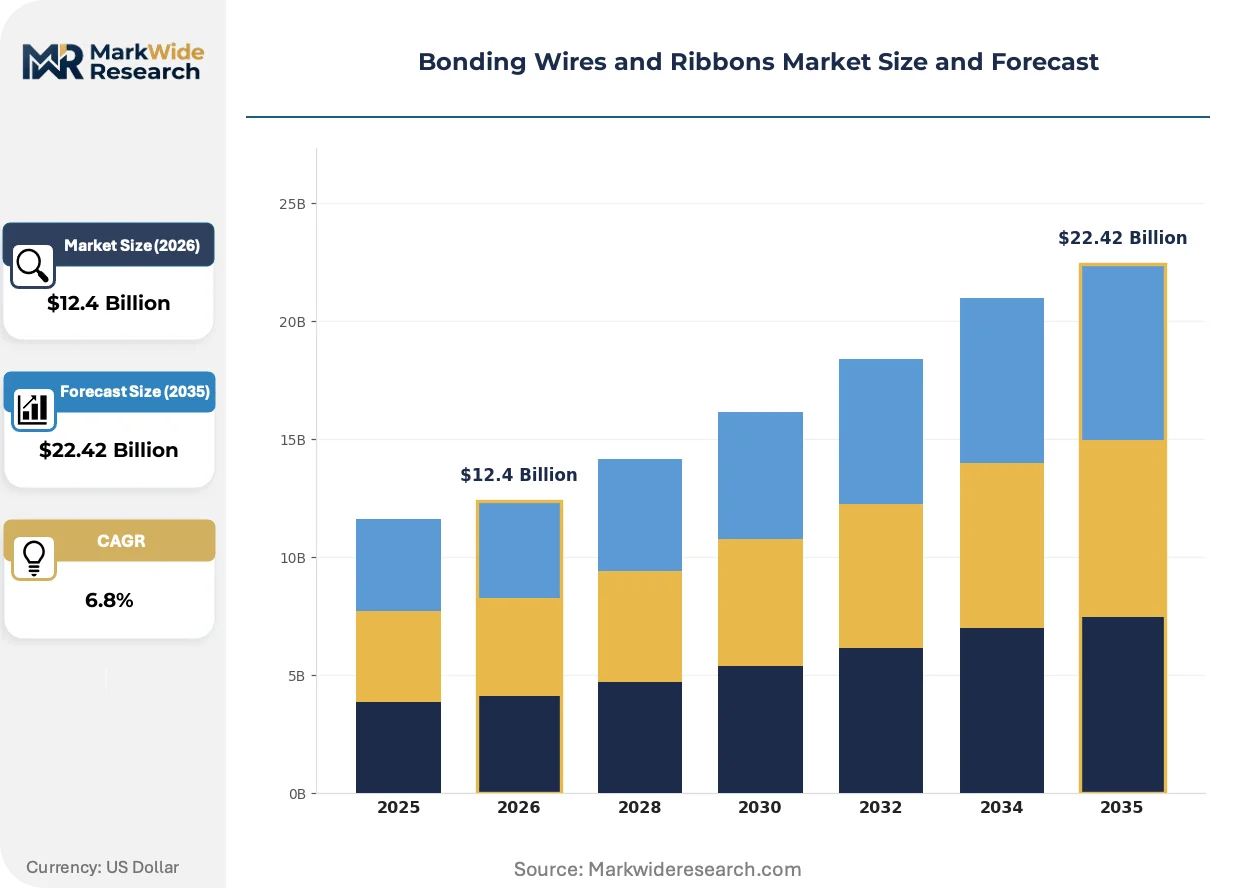
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold Wires, Aluminum Wires, Copper Ribbons, Silver Wires End User: Semiconductors, Electronic Components, Automotive, Telecommunications Application: IC Packaging, Hybrid Modules, Power Devices, Sensor Devices Manufacturing Stage: Raw Material Processing, Wire Drawing, Surface Treatment, Final Assembly |
| Companies Covered | Heraeus, Sumitomo Metal Mining, Tanaka, Tatsuta Electric Wire & Cable, ASMPT, Ametek, Mitsui Mining & Smelting, MK Electron, Palomar Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bonding Wires and Ribbons Market Trends and Innovations
Material science advances and regulatory disclosure requirements are restructuring how bonding wire specifications are validated, procured, and integrated into semiconductor package designs.
Fine-pitch copper wire below 20 micrometer diameter is rendering obsolete traditional gold wire in consumer electronics memory packages where cost-per-interconnect dominates supplier selection. Memory module assemblers in Taiwan and South Korea have transitioned production lines within 18-month equipment refresh cycles. This shift compresses gold wire volume in mainstream packaging while elevating surface oxidation control as a critical process parameter.
China's MIIT enforcement of GB standards on electronic-grade copper purity and mechanical property documentation constrains import eligibility for non-compliant suppliers. Domestic wire manufacturers must certify tensile strength consistency and elongation uniformity to maintain foundry qualification status. Taiwan-based packaging houses serving China-bound product lines now require dual documentation streams to satisfy cross-strait regulatory divergence.
Automotive OEMs now mandate full material substance declarations through IMDS submission before wire supplier approval, shifting procurement evaluation toward supply chain transparency rather than unit pricing alone. Tier-1 module suppliers have disqualified legacy wire sources lacking automated coating chemistry tracking. This behavioral pivot is most pronounced in German and Japanese automotive semiconductor procurement offices managing EV powertrain component qualification.
Bonding Wires and Ribbons Market Segmentation
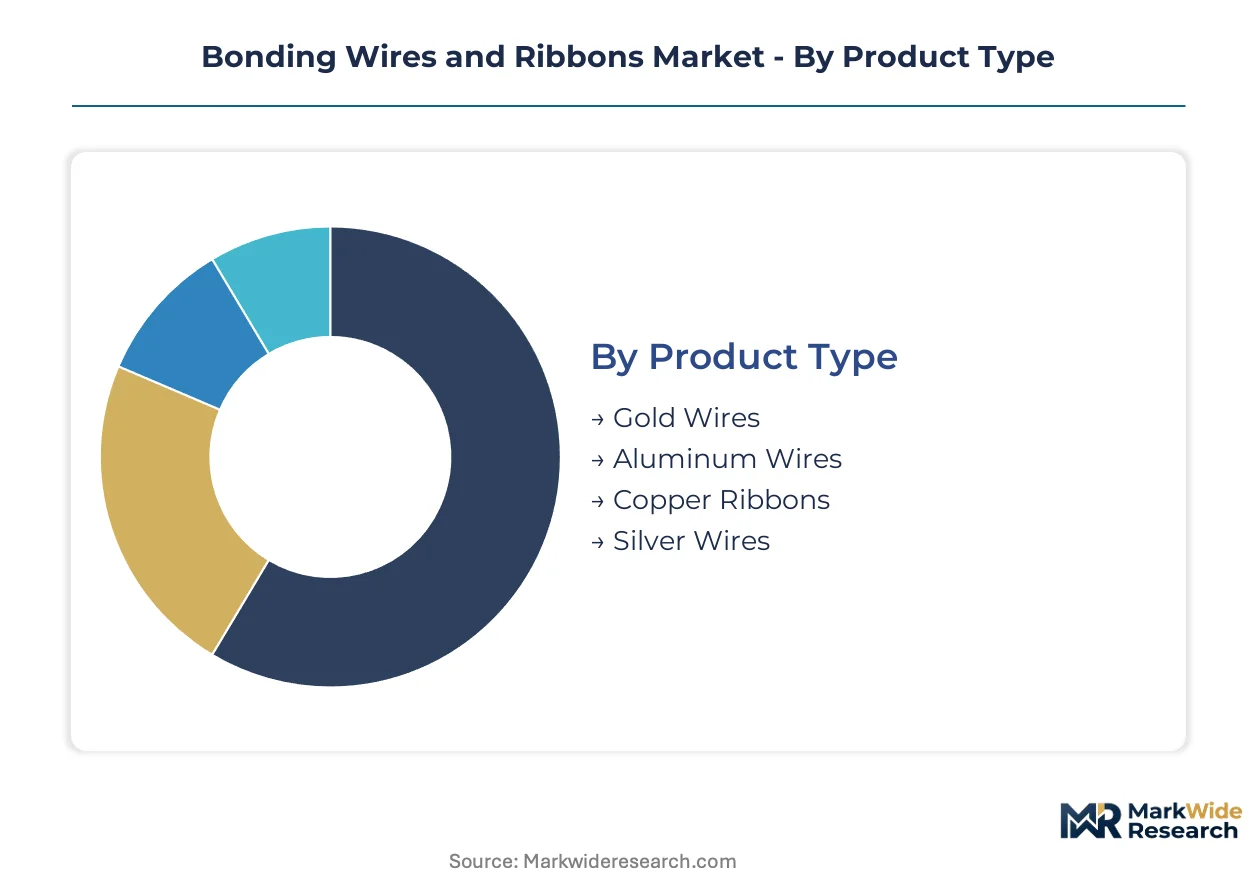
Bonding wire and ribbon specifications diverge sharply across power density, thermal cycling, and corrosion resistance requirements. Semiconductor packaging houses select metallurgies based on current-carrying capacity, bond pad metallization compatibility, and regulatory substance restrictions. Each segmentation axis reveals distinct procurement patterns tied to end-use reliability tiers and geographic regulatory enforcement.
Product Type:
Use-case spectrum spans hermetic aerospace packages through cost-driven consumer memory modules, with metallurgy selection dictated by conductivity requirements and environmental exposure severity.
- Copper Ribbons:Wide-format conductors (0.2-2.0mm width) deliver 25% conductivity advantage over aluminum alternatives. Electric vehicle traction inverters and renewable energy converters in Taiwan and South Korea pull specifications toward enhanced thermal cycling performance. Automotive OEMs mandate IMDS substance declarations before supplier approval.
- Gold Wires:Ultra-fine diameters (15-25 micrometers) provide oxidation immunity for hermetic medical and aerospace packages. High-reliability segments retain gold despite copper substitution pressure. Japan's METI coordinates JIS standards with PMDA quality frameworks for diagnostic imaging interconnects.
- Aluminum Wires:Legacy automotive and industrial power modules favor thermal cycling tolerance over conductivity gains. Cost advantage persists in mature packaging lines.
- Silver Wires:RF device and LED applications leverage silver bondability where solid precious metal solutions previously dominated. Hybrid metallization approaches combine conductivity with surface compatibility.
Established volume favors aluminum wire in legacy automotive modules; emerging adoption favors copper ribbon in EV powertrain assembly.
End User:
Cost tier stratification separates premium-qualified aerospace and medical supply from price-sensitive consumer electronics procurement.
- Semiconductors:Foundry packaging lines in Taiwan and South Korea concentrate wire demand as advanced IC capacity expands. Memory module assemblers transitioned production lines to fine-pitch copper within compressed equipment refresh cycles.
- Automotive:Tier-1 module suppliers disqualify legacy sources lacking automated coating chemistry tracking. EU RoHS compliance deadlines accelerate lead-free plating reformulation.
- Electronic Components:Consumer electronics memory packages drive cost-per-interconnect optimization. Surface oxidation control emerged as critical process parameter.
- Telecommunications:Base station and infrastructure equipment demand balances reliability with volume scale. RF performance requirements sustain specialty metallization demand.
Procurement concentration clusters in semiconductor foundries; regulatory compliance intensity peaks in automotive qualification.
Application:
Volume distribution tracks power density escalation across electrification and renewable energy deployment.
- Power Devices:Current-carrying capacity and thermal performance command premium positioning. Copper ribbon captures margin pools where conductivity specifications are non-negotiable.
- IC Packaging:Fine-pitch wire below 20 micrometer diameter displaced traditional gold in mainstream consumer applications. Taiwan-based houses serving China-bound product lines require dual documentation streams.
- Hybrid Modules:Multi-material integration demands compatible thermal expansion coefficients across dissimilar metallurgies.
- Sensor Devices:Miniaturization trends push wire diameter specifications while maintaining mechanical reliability under vibration exposure.
Power device applications are climbing the fastest; IC packaging retains absolute volume leadership.
Manufacturing Stage:
Supply concentration in upstream smelting and refining shapes downstream qualification timelines and feedstock security.
- Wire Drawing:Precision diameter control and surface finish determine bondability. Chilean and Peruvian mine output disruptions transmit directly to electronic-grade cathode availability.
- Surface Treatment:Plating chemistry reformulation responds to EU REACH and RoHS substance restrictions. Pure tin and silver finishes displace legacy lead-bearing coatings.
- Raw Material Processing:Electronic-grade copper purity certification under China's GB standards constrains import eligibility. Tensile strength consistency and elongation uniformity documentation is mandatory.
- Final Assembly:Spooling and packaging specifications align with automated bonding equipment requirements. Cleanroom compatibility distinguishes semiconductor-grade from industrial-grade supply.
Backward integration into raw material processing offers margin defense; surface treatment specialization enables regulatory compliance differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese copper wire exports flow predominantly to Taiwan and South Korea packaging houses, creating a trade corridor that concentrates procurement volumes and shapes regional supplier qualification protocols.
China
Domestic foundry expansion and EV powertrain assembly drive copper ribbon consumption. MIIT enforces GB standards on electronic-grade purity and mechanical documentation that constrains import eligibility. Yangtze River Delta smelters and wire drawing facilities supply Taiwan-based packaging houses with dual documentation streams for cross-strait compliance.
Taiwan
Advanced IC packaging capacity additions concentrate global wire demand as memory module assemblers transition to fine-pitch copper. The island's semiconductor packaging lines require high-purity copper feedstock with certified tensile consistency. Hsinchu Science Park facilities anchor the regional supply chain for consumer electronics interconnects.
South Korea
Electric vehicle traction inverter production pulls copper ribbon specifications toward wider gauge formats. Samsung and SK hynix packaging operations demand surface oxidation control for automated bonding equipment. Seoul Capital Area foundry clusters negotiate dedicated supply agreements with Japanese and Chinese feedstock suppliers.
Japan
Medical device and aerospace segments retain gold wire demand for hermetic package reliability. METI coordinates JIS standards with PMDA quality frameworks, creating dual-certification requirements for diagnostic imaging OEM supply. Kansai region precision alloy developers serve high-reliability segments resistant to copper substitution.
Germany
Automotive OEMs mandate IMDS substance declarations before wire supplier approval, shifting procurement toward supply chain transparency. EU REACH and RoHS compliance deadlines accelerate lead-free plating reformulation. Bavaria-based Tier-1 module suppliers disqualify legacy sources lacking automated coating chemistry tracking.
Bonding Wires and Ribbons Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated upstream and fragmented downstream structure. Smelter concentration in precious and base metals creates feedstock gatekeepers, while wire drawing and surface treatment operations fragment across regional qualification requirements. Three archetypes dominate: vertically integrated mining-to-wire conglomerates, precision alloy specialists serving hermetic packages, and regional drawing houses competing on logistics proximity. Dominant competitive moves include backward integration into electronic-grade cathode production and strategic partnerships with packaging equipment OEMs for process parameter co-development.
Within the integrated conglomerate tier, Sumitomo Metal Mining and Mitsui Mining & Smelting exemplify upstream control over precious metal feedstock from mine to drawn wire. Tanaka occupies a position among precision alloy specialists developing ultra-fine diameter products for high-reliability semiconductor packages. Heraeus anchors the technology leadership archetype through precision alloy development for fine-pitch applications.
| Leading Market Players |
|---|
| Heraeus |
| Sumitomo Metal Mining |
| Tanaka |
| Tatsuta Electric Wire & Cable |
| ASMPT |
| Ametek |
| Mitsui Mining & Smelting |
| MK Electron |
| Palomar Technologies |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese wire drawing facilities is compressing supplier margins and forcing acceptance of indexed raw material pass-through clauses. Taiwan-based packaging houses exploit this surplus to negotiate quarterly price resets tied to London Metal Exchange copper futures, while Japanese precision alloy specialists resist volume discounting through certification-locked supply agreements.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange copper cathode prices dominate procurement between Taiwanese packaging houses and Yangtze River Delta suppliers. Three-tier pricing structure across high-reliability certified, automotive-qualified, and industrial-grade tiers separates Sumitomo Metal Mining's precious metal products from Chinese copper ribbon commodity supply. Pricing pressure stems from EV inverter assemblers demanding wider gauge formats at legacy wire diameters pricing. Memory module manufacturers exhibit highest price sensitivity, while medical device OEMs prioritize JIS-PMDA dual certification over unit cost.
Supply Chain Analysis
Extended sixty-day payment terms from Seoul Capital Area foundries strain working capital at regional drawing houses, accelerating supply-chain finance facility adoption among Chinese feedstock suppliers. Electronic-grade copper cathode supply concentrates in Chile, Peru, and Chinese smelter complexes. Ultra-pure ribbon drawing rests on Chilean mine concentrate, Japanese precision alloy additives, and Taiwanese surface treatment chemistries. Single-source vulnerability runs through Andean mine disruptions transmitting directly to cathode availability. Distribution runs through bonded warehouse networks serving Hsinchu Science Park and Seoul Capital Area clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment moat, where JIS-PMDA dual certification and automotive IMDS compliance create switching costs that lock qualified suppliers into multi-year foundry agreements.
For Market Incumbents: Harden qualification documentation systems to capture EU CSRD carbon disclosure mandates before competitors achieve renewable energy sourcing verification. Expand captive copper cathode refining in Yangtze River Delta facilities to offset London Metal Exchange volatility exposure. Defensive consolidation through acquisition of Japanese surface treatment specialists protects margin pools in medical device interconnects against silver-coated copper hybrid entrants.
For New Entrants and Emerging Players: Pursue India Semiconductor Mission PLI incentives for domestic packaging qualification, where copper ribbon localization gaps create penetrable white space. Target RF device and LED segments with silver-coated copper hybrid metallization, bypassing entrenched gold wire positions in hermetic packages. Go-to-market leverage through equipment OEM process parameter co-development accelerates bonding line qualification timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward precision alloy specialists with JIS-PMDA dual certification and renewable energy sourcing documentation, positioned for EU CSRD procurement preference. Long-term viability favors suppliers integrating backward into electronic-grade cathode production to capture margin defense against commodity volatility. Watch for inflection where automotive OEMs mandate full smelter renewable energy disclosure as a supplier disqualification threshold.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electronic-Grade Cathode Production | Captures margin defense against London Metal Exchange copper volatility for Taiwanese packaging supply. |
| JIS-PMDA Dual Certification Investment | Locks diagnostic imaging OEM supply agreements against silver-coated copper hybrid substitution threats. |
| Renewable Energy Sourcing Documentation | Meets EU CSRD procurement preferences from German automotive OEM sustainability scorecards. |
| Silver-Coated Copper Hybrid Metallization Launch | Opens RF device and LED segments previously locked to solid precious metal interconnect solutions. |
| India PLI Scheme Localization | Qualifies for domestic packaging incentives as EV traction inverter assembly expands beyond East Asia. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade databases, and semiconductor equipment OEM technical disclosures. Primary interviews engaged wire bonding equipment engineers, foundry procurement managers at Taiwan and South Korea packaging houses, copper cathode traders, and automotive Tier-1 module supplier quality directors. Secondary validation drew from MIIT GB standard enforcement notices, EU REACH substance restriction updates, and IMDS material declaration system protocols. Bottom-up segment sizing triangulated against top-down foundry capacity expansion announcements.
Forecast inputs incorporate wire diameter migration rates, copper-to-gold substitution elasticities across reliability tiers, and regional foundry capacity buildout schedules. Segmentation modeling spans product metallurgy, end-use industry, application power density, and manufacturing stage integration depth. CAGRs derive from elasticity-adjusted volume projections against price normalization assumptions. Industry-specific inputs include ultrasonic bonding equipment refresh cycles and automotive EV powertrain content-per-vehicle trajectories.
Sensitivities concentrate around Chilean mine supply disruptions, EU Green Deal embodied carbon tracking acceleration, and copper ribbon bonding parameter adoption rates at packaging houses lacking in-house metallurgical expertise. Forecasts reflect documented assumptions on raw material availability and regulatory enforcement timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Coin Battery Holder Market
Electronic Components
Passive Attenuator Market
Electronic Components
Braking Resistors Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Handheld Devices Battery Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Global Industrial Media Converters Market
Electronic Components
Astable Multivibrator Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Asia Pacific Safety Relays and Timers Market
Electronic Components
Power Resistor Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Pneumatic Components Market