
 Europe Radiation-Hardened Electronics Market | 2026-2036
Europe Radiation-Hardened Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Radiation-Hardened Electronics Market Intelligence
The EU Green Deal is restructuring capital allocation across Europe's radiation-hardened supply base, raising compliance thresholds for environmental durability and traceability. Infineon Technologies AG anchors German automotive and industrial crossover demand with silicon carbide-adjacent process expertise. BAE Systems dominates UK defense and space procurement through vertically controlled foundry relationships. Honeywell International Inc. positions its European operations around nuclear instrumentation and reactor monitoring systems.
Radiation-hardened electronics are semiconductor devices and discrete components engineered to maintain operational integrity under ionizing radiation doses exceeding 100 krad(Si), achieved through specialized fabrication processes including silicon-on-insulator substrates, triple-module redundancy, and error-correction logic. These components serve mission-critical functions in aerospace, military, and nuclear infrastructure where conventional electronics would experience threshold voltage shifts and single-event upsets. Integrated circuits command the largest product share due to their centrality in flight computers and payload processors, while GaN technology captures the fastest technology growth trajectory owing to its superior power density and radiation tolerance for satellite power systems. Sensors represent a concentrated margin pool as nuclear power operators modernize in-core monitoring networks across France, the UK, and Finland.
EMA's medical device oversight and the EU AI Act create overlapping compliance burdens for autonomous space systems, while REACH restricts certain substrate materials and forces reformulation of packaging compounds. The F-Gas Regulation indirectly shapes thermal management design rules for sealed aerospace enclosures. Stakeholders must monitor how the EU Chips Act's dedicated funding lines for strategic semiconductors redirect national subsidy competition among France, Germany, and Italy.
Market Dynamics
European satellite constellation deployments and nuclear reactor instrumentation upgrades are compressing procurement cycles for radiation-hardened components, forcing suppliers to reconfigure qualification pipelines around dual-use certification standards.
Growth Catalysts
- EU Green Deal nuclear mandates:France, Finland, and the UK are extending reactor lifespans and constructing new units, requiring hardened sensors and control systems for in-core monitoring networks that must survive decades of cumulative radiation exposure.
- Silicon carbide substrate advances:Wide-bandgap semiconductor processes are enabling power converters and motor drives that tolerate higher radiation doses while operating at elevated temperatures, expanding addressable missions beyond traditional silicon limits.
- Low Earth orbit constellations:European space agencies and commercial operators are procuring hardened integrated circuits for satellite buses and payloads in volumes that justify dedicated foundry capacity.
Market Restraints
- Specialized foundry concentration:Qualified fabrication for radiation-hardened designs concentrates among a handful of European and US facilities, creating single-source vulnerabilities for critical process nodes.
- Extended qualification timelines:Total ionizing dose and single-event effect testing protocols add 18-36 months to product development cycles, delaying revenue recognition and locking working capital.
- Alternative platform competition:Commercial off-the-shelf components with radiation-tolerant firmware and triple-module redundancy are capturing missions with moderate reliability requirements at substantially lower unit costs.
Strategic Opportunities
- Finnish nuclear newbuild:The Olkiluoto expansion and planned additional reactors create concentrated demand for first-of-a-kind instrumentation qualified to national regulatory standards.
- GaN-SiC hybrid power modules:Converging gallium nitride switching with silicon carbide substrates enables satellite power conditioning units with superior radiation tolerance and thermal performance.
- EU Chips Act funding lines:Dedicated subsidies for strategic semiconductor manufacturing are redirecting national competition toward radiation-hardened process development in France, Germany, and Italy.
Industry Challenges
- Radiation effects modeling expertise:The specialized knowledge required for single-event upset prediction and hardened cell design concentrates among aging specialists, constraining workforce expansion.
- REACH compliance reformulation:Restrictions on substrate materials and packaging compounds are forcing redesigns of qualified product lines, triggering costly re-qualification cycles.
- Legacy system integration:New hardened components must interface with decades-old reactor control architectures and satellite bus designs, complicating electrical and software compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Radiation-Hardened Electronics Market |
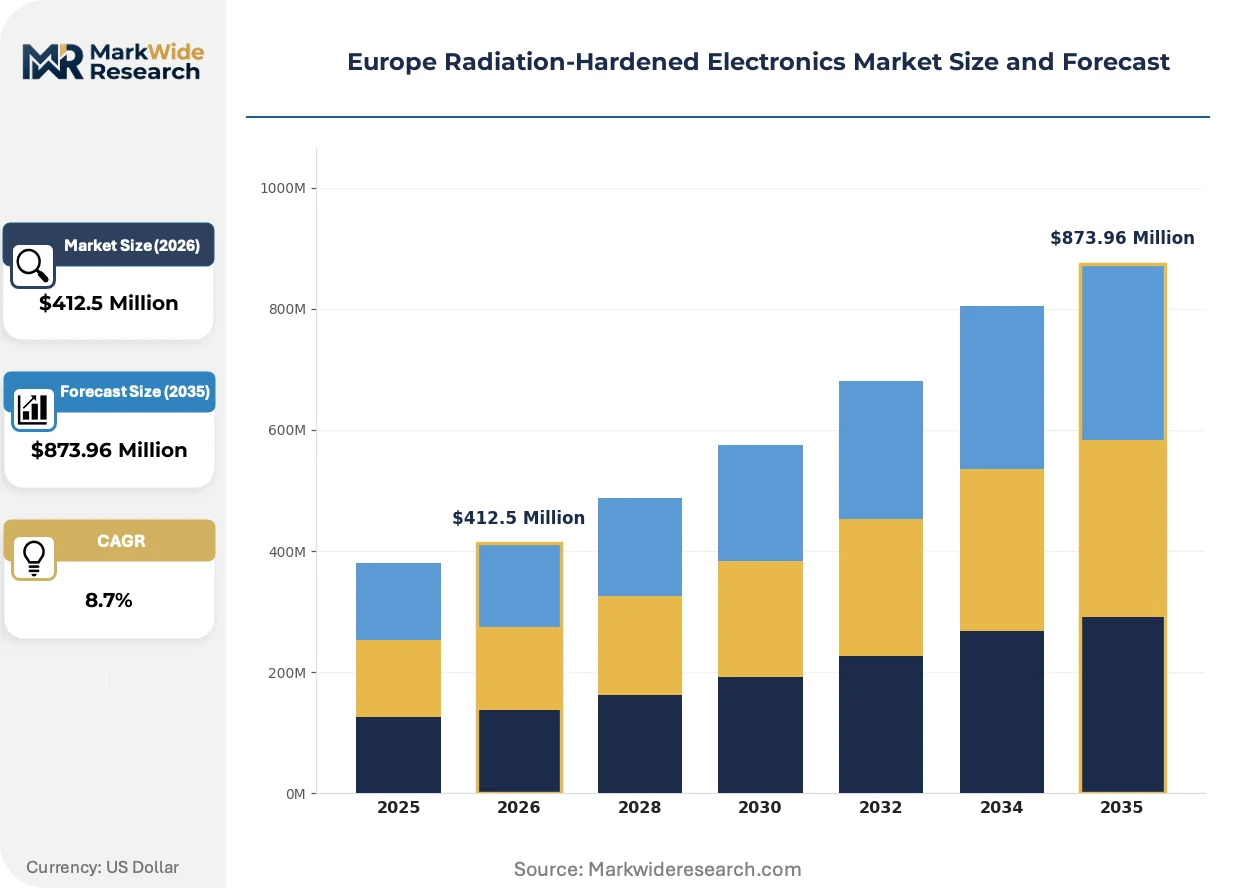
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, Transistors, Diodes, Sensors Application: Aerospace, Military, Nuclear Power, Space Exploration Technology: CMOS, Bipolar, GaN, SiGe End User: Government Agencies, Research Institutions, OEMs, Contractors |
| Companies Covered | Microchip Technology Inc., Honeywell International Inc., Infineon Technologies AG, TTM Technologies, Inc., Renesas Electronics Corp, STMicroelectronics, Texas Instruments Incorporated, Data Devices Corporation, BAE Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Radiation-Hardened Electronics Market Strategic Shifts & Innovations
Radiation-hardened electronics are undergoing process and architectural transformation as satellite power demands intensify and nuclear instrumentation refresh cycles compress. Three developments are restructuring competitive positioning.
Silicon carbide power devices are converging with gallium nitride gate drivers to form integrated power conversion modules for satellite electrical subsystems. European space prime contractors are specifying these hybrid architectures for next-generation Earth observation platforms. This convergence is compressing the performance gap between hardened and commercial power electronics, enabling missions previously reserved for custom designs.
REACH restrictions on lead-based solders and halogenated flame retardants are forcing reformulation of packaging materials for aerospace and nuclear applications. ECHA substance evaluations are disqualifying legacy compound formulations faster than replacement qualifications can complete. Satellite payload suppliers in France and the UK are accelerating material validation programs to maintain export certification timelines.
Long-term service contracts for nuclear instrumentation are unbundling hardware procurement from calibration and replacement scheduling. French and Finnish reactor operators are separating initial sensor purchases from decade-spanning maintenance agreements, shifting supplier revenue toward recurring service streams. This restructuring concentrates purchasing authority with specialized engineering procurement teams rather than capital project managers.
Europe Radiation-Hardened Electronics Market Segmentation
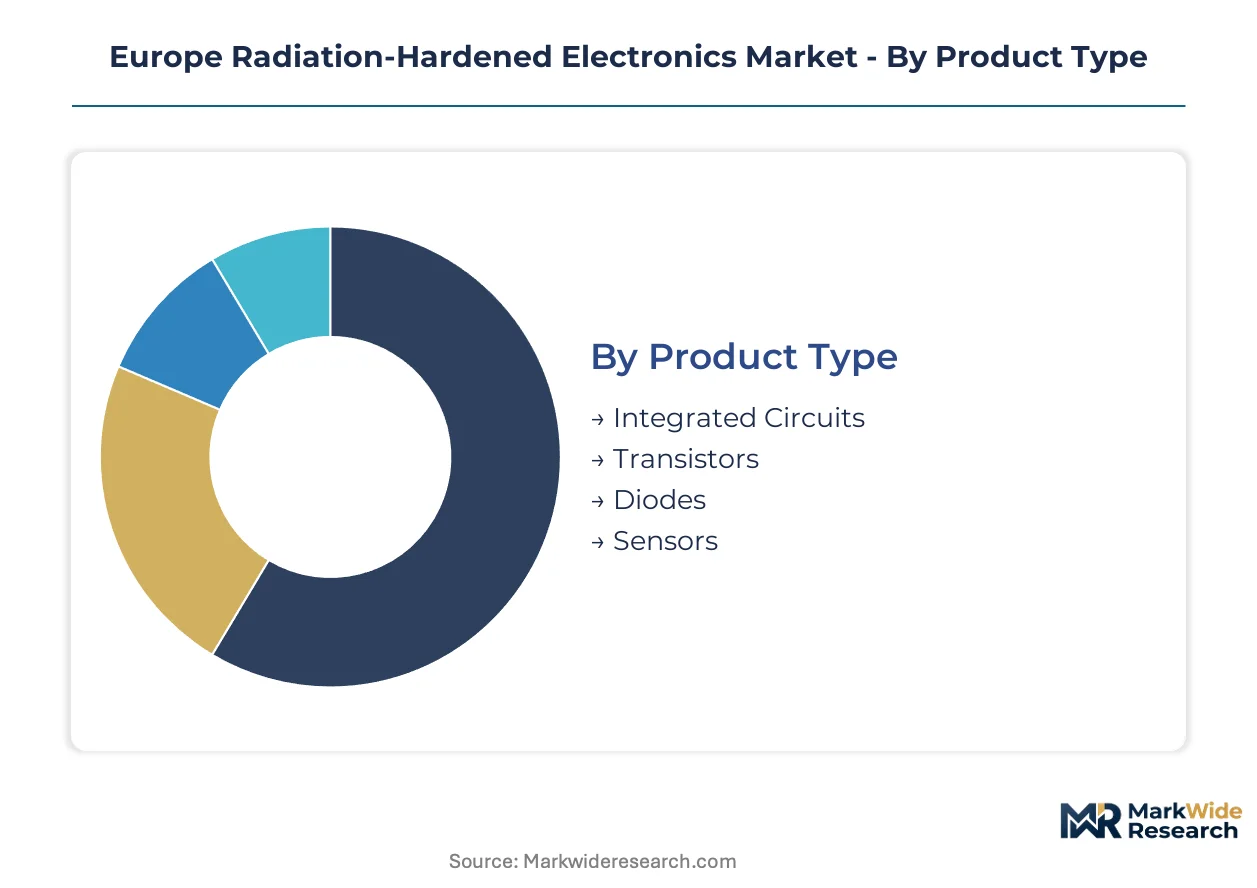
Segmentation reveals how radiation-hardened electronics integrate into mission-critical systems across Europe. Product architecture, application environment, and procurement channel each dictate distinct qualification requirements and margin structures.
Product Type:
Integration depth varies sharply — integrated circuits embed into flight computers as complete subsystems, while discrete components serve as replaceable elements in larger assemblies.
- Integrated Circuits:Complex functional blocks fabricated on silicon-on-insulator or epitaxial substrates with triple-module redundancy and error-correction logic. French satellite prime contractors specify these for payload processors and bus controllers where single-event upsets would corrupt orbital operations. ESA procurement cycles now compress qualification timelines for constellation-scale volumes.
- Sensors:In-core thermocouples, neutron flux detectors, and pressure transducers engineered for cumulative doses exceeding decades of reactor operation. Finnish and French nuclear operators drive replacement demand as aging instrumentation networks reach end-of-design-life, with REACH compliance forcing material reformulation of cable assemblies and housings.
- Transistors:Power switching elements for satellite power distribution and motor drive applications.
- Diodes:Rectification and protection devices in radiation-tolerant power conditioning units.
Integrated circuits lead volumes today; sensors are gaining share fastest.
Application:
Environmental severity dictates component grade — aerospace missions tolerate moderate doses, while in-core nuclear instrumentation faces the harshest cumulative exposure.
- Nuclear Power:In-core monitoring systems, control rod position indicators, and primary circuit instrumentation requiring decades of reliable operation under continuous gamma and neutron flux. French EDF reactor fleet extensions and Finnish Olkiluoto newbuild projects concentrate procurement authority with specialized engineering teams rather than capital project managers.
- Space Exploration:Deep-space probes and planetary missions demanding electronics that survive extreme total ionizing dose and single-event effects beyond Earth's magnetosphere. ESA science missions specify hardened components for JUICE and Hera programs, with GaN power devices displacing silicon for outer-planet solar array conditioning.
- Aerospace:High-altitude platforms and atmospheric re-entry vehicles with moderate radiation exposure profiles.
- Military:Strategic systems and tactical platforms requiring radiation tolerance for nuclear event survivability.
Nuclear power anchors procurement value; space exploration shows the steepest expansion trajectory.
Technology:
Process maturity versus performance frontier defines competitive positioning — established CMOS dominates volume, while wide-bandgap materials capture next-generation specifications.
- GaN:Gallium nitride high-electron-mobility transistors and power switches delivering superior radiation tolerance and power density for satellite electrical subsystems. European space prime contractors specify GaN gate drivers paired with silicon carbide substrates for Earth observation platform power conversion, compressing the performance gap with commercial alternatives.
- CMOS:Complementary metal-oxide-semiconductor logic fabricated on specialized substrates with radiation-hardened cell libraries and guard ring structures. Mature process nodes from European foundries serve flight computer and payload processor demand, with qualification pipelines adapting to dual-use certification standards.
- Bipolar:Junction transistor technology for linear circuits and precision analog functions in legacy nuclear instrumentation.
- SiGe:Silicon-germanium heterojunction bipolar transistors for high-frequency communication and radar applications in spaceborne payloads.
CMOS dominates installed base; GaN is climbing the fastest.
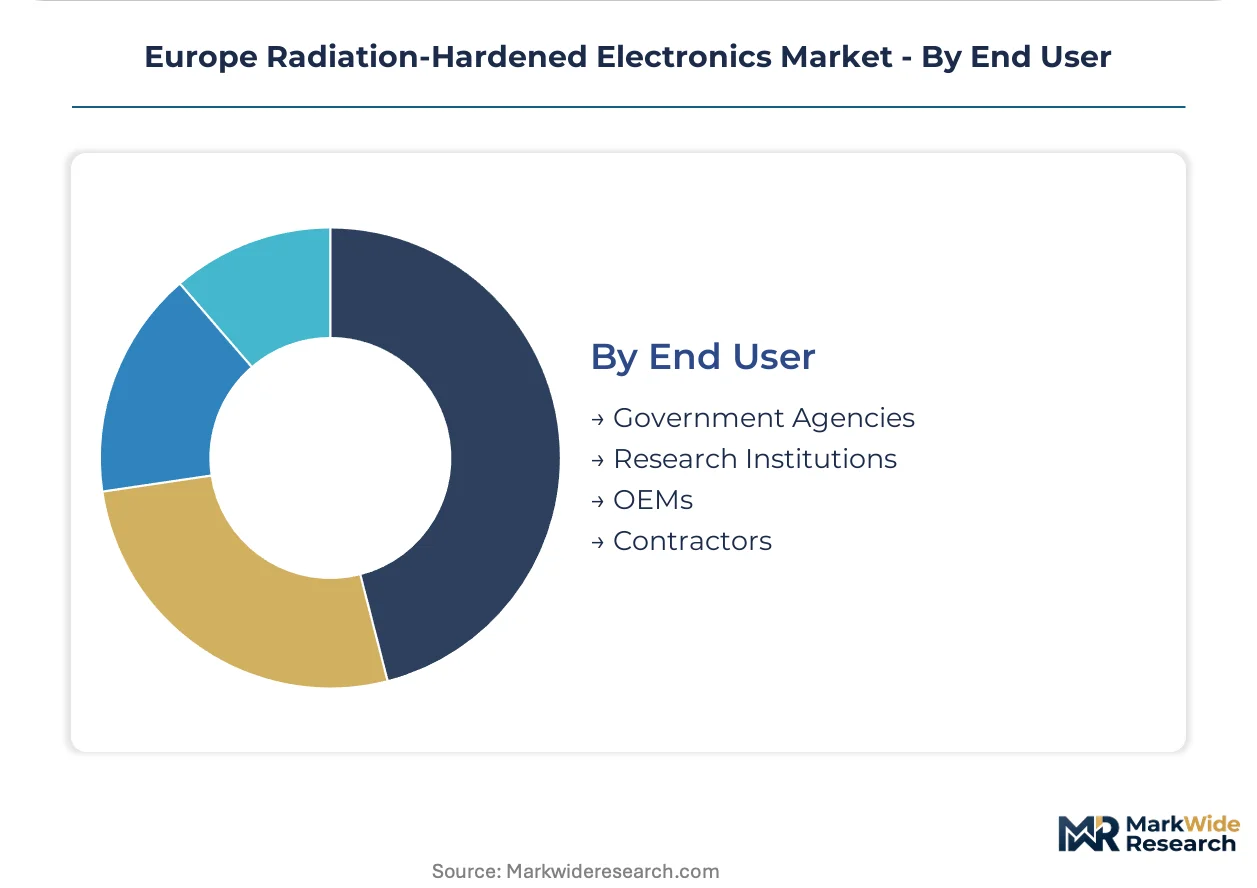
End User:
Procurement authority fragments across institutional buyers with divergent qualification protocols and contract structures.
- Government Agencies:ESA, national space agencies, and defense ministries with sovereign specification authority and long-term program commitments. French CNES and Italian ASI procurement frameworks prioritize European supply chain security, redirecting subsidy competition under EU Chips Act funding lines.
- Contractors:Satellite prime contractors and nuclear engineering procurement consortia unbundling hardware from decade-spanning service agreements. French and Finnish reactor operators now separate initial sensor purchases from calibration and replacement scheduling, shifting supplier revenue toward recurring maintenance streams.
- Research Institutions:CERN and national laboratories with specialized detector instrumentation requirements.
- OEMs:Original equipment manufacturers integrating hardened components into subsystem assemblies for prime contractor supply.
Government agencies command the largest contract values; contractors are expanding procurement autonomy most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized radiation effects modeling expertise concentrates in France, Germany, and the UK, with aging specialists constraining workforce expansion across European foundry networks.
France
EDF's reactor fleet extensions and CNES satellite constellation programs drive concentrated procurement of hardened integrated circuits and in-core sensors. The EU Green Deal nuclear mandates accelerate instrumentation upgrades across 56 operational units. Toulouse hosts dense clusters of space-qualified suppliers serving Ariane and Earth observation platforms.
Germany
Infineon Technologies AG anchors automotive crossover demand with silicon carbide-adjacent process expertise migrating into radiation-hardened applications. The EU Chips Act redirects national subsidy competition toward strategic semiconductor manufacturing in Dresden and Munich. Bavarian engineering consortia coordinate qualification pipelines for dual-use certification standards.
United Kingdom
BAE Systems dominates defense and space procurement through vertically controlled foundry relationships serving sovereign programs. The UK nuclear newbuild at Sizewell C creates demand for first-of-a-kind instrumentation qualified to national regulatory standards. Harwell and Stevenage house satellite payload engineering clusters.
Finland
Olkiluoto nuclear expansion and planned additional reactors generate concentrated demand for hardened sensors and control systems. Finnish Radiation and Nuclear Safety Authority (STUK) standards require decades-proven reliability for in-core monitoring networks. Espoo-based engineering procurement teams unbundle hardware from decade-spanning maintenance agreements.
Italy
ASI procurement frameworks prioritize European supply chain security for satellite bus and payload components. The EU Chips Act funding lines redirect national competition toward radiation-hardened process development in Milan-Turin industrial corridors. Thales Alenia Space manufacturing in Rome anchors GaN power device qualification for Earth observation platforms.
Europe Radiation-Hardened Electronics Market Key Industry Players
The competitive structure tilts toward diversified semiconductor conglomerates with captive radiation-hardened divisions. Market concentration remains moderate, with qualified fabrication capacity limiting new entry despite constellation-scale demand growth. Two strategic archetypes dominate: vertically integrated defense contractors controlling proprietary foundry relationships, and broad-based semiconductor suppliers leveraging silicon carbide process adjacencies. Competitive moves center on dual-use certification streamlining and REACH-compliant material reformulation.
Among diversified semiconductor suppliers, Microchip Technology Inc., Infineon Technologies AG, and STMicroelectronics exemplify scale-driven archetypes with radiation-tolerant product divisions. These companies occupy positions where automotive and industrial process expertise migrates into hardened applications. Defense-centric fabricators including BAE Systems and Honeywell International Inc. anchor the sovereign procurement tier, sitting within vertically integrated structures that control qualification pipelines for national security programs.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Honeywell International Inc. |
| Infineon Technologies AG |
| TTM Technologies, Inc. |
| Renesas Electronics Corp |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Data Devices Corporation |
| BAE Systems |
| Others |
Cost & Logistics Intelligence
EU Green Deal nuclear instrumentation mandates are compressing procurement timelines for hardened sensors and control systems, forcing foundries to accelerate qualification cycles and pass through compliance costs to buyers in France, Finland, and the UK.
Pricing Analysis
Bundled hardware-service contracts are unbundling into separate procurement streams for initial sensor purchases and decade-spanning maintenance agreements. Price differentiation hinges on REACH-compliant material certification and volume scale for constellation-grade integrated circuits. Pricing pressure stems from commercial off-the-shelf alternatives capturing moderate-reliability missions. Nuclear engineering procurement teams show highest price sensitivity; ESA satellite programs demonstrate lowest.
Supply Chain Analysis
Refurbishment flows for end-of-life reactor instrumentation create reverse-logistics complexity as French and Finnish operators require certified remanufacturing to original qualification standards. Qualified fabrication concentrates in France, Germany, and the United States. Supply chains draw from silicon-on-insulator substrates, gallium nitride wafers, and specialized packaging compounds. Single-source vulnerability pervades critical process nodes. Distribution runs through satellite prime contractors and nuclear engineering consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European radiation-hardened electronics function as a geographic-arbitrage play where REACH compliance costs in France and Germany exceed those in Eastern European manufacturing zones, creating cost-differential opportunities for qualified suppliers.
For Market Incumbents: To counter commercial off-the-shelf radiation-tolerant alternatives, BAE Systems and Infineon Technologies AG should deepen captive foundry control over silicon carbide process nodes while accelerating dual-use certification streamlining for ESA and national space agency procurement frameworks.
For New Entrants and Emerging Players: Begin with Finnish nuclear newbuild instrumentation networks, where STUK qualification requirements have created white-space demand for first-of-a-kind sensor suppliers. Target GaN-SiC hybrid power module specifications for Earth observation platforms, leveraging EU Chips Act subsidy lines for strategic semiconductor manufacturing.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized radiation effects modeling consultancies and qualified packaging material suppliers facing REACH-driven reformulation cycles. Five-to-ten-year viability hinges on EU Green Deal nuclear fleet extensions and constellation deployment scale. Monitor ESA procurement volume announcements and Olkiluoto reactor construction milestones as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Use Certification Streamlining | Compresses qualification timelines for ESA and CNES satellite constellation procurement. |
| GaN-SiC Hybrid Power Module Development | Captures next-generation Earth observation platform specifications from Thales Alenia Space. |
| REACH-Compliant Material Reformulation | Maintains export certification for French and UK satellite payload suppliers under ECHA restrictions. |
| Backward Integration into Silicon Carbide Substrates | Secures process control for radiation-tolerant power conversion at Infineon Dresden facilities. |
| Long-Term Service Contract Unbundling | Shifts revenue toward recurring maintenance streams with French and Finnish reactor operators. |
Research Approach
Multiple input streams — primary interviews with satellite procurement officers, nuclear engineering leads, and radiation effects specialists; secondary validation against ESA program disclosures, EDF fleet extension filings, and STUK regulatory databases; plus customs records for semiconductor trade flows — were reconciled through bottom-up and top-down triangulation.
Segmentation-level demand curves across product type, application environment, technology node, and end-user procurement channel were modeled across the analysis window. CAGRs derived from installed base turnover rates, reactor lifespan extension schedules, and constellation deployment trajectories. Forecast inputs incorporated silicon carbide substrate yield improvements and REACH substance restriction timelines.
Several conditions sit outside the modeled scope, including abrupt ESA budget reallocations, rapid commercial off-the-shelf radiation tolerance advances, and unscheduled French reactor shutdowns. Practitioners should monitor EU Chips Act subsidy award announcements and ECHA substance evaluation schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Laser Direct Structuring (LDS) Antenna Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
High Density Interconnect (HDI) PCB Market
Electronic Components
Stretchable and Conformal Electronics Market
Electronic Components
North America MLCC Market
Electronic Components
USB Wall Charger Market
Electronic Components
Special Function Data Convertors Market
Electronic Components
US Frequency Control and Timing Devices Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Conductive Polymer Capacitor Market
Electronic Components
Primary Charge Roller Market
Electronic Components
Global Microfluidic Components Market
Electronic Components
Electronic Shelf Label Market
Electronic Components
Multilayer Transparent Conductors Market
Electronic Components
Graphics Add-In Board (AIB) Market