
 United States Oral Hygiene Market | 2026-2036
United States Oral Hygiene Market Size, Share, and Industry Trends Forecast 2026-2036
United States Oral Hygiene Market Intelligence
Dental clinic procurement is rebalancing toward preventive care bundles as insurers expand coverage for prophylactic treatments. Colgate-Palmolive Company leverages its professional channel relationships to anchor fluoride varnish programs in pediatric dentistry. Procter & Gamble Company sustains R&D intensity around enzymatic whitening systems, while Church & Dwight Co., Inc. competes aggressively in the natural-ingredient segment through baking-soda-based formulations.
Oral hygiene encompasses the practices, products, and professional services used to maintain clean teeth, healthy gums, and fresh breath, typically involving mechanical removal of plaque through brushing and flossing supplemented by chemotherapeutic agents such as fluoride, chlorhexidine, or hydrogen peroxide at specified concentrations. The category serves both consumer self-care routines and clinical preventive protocols, with product efficacy measured against FDA monograph standards for anticaries and antigingivitis claims. Toothpaste occupies the largest revenue pool within product type segmentation, though whitening strips generate disproportionate margin contribution due to higher price positioning and repeat purchase velocity. Online retail channels are expanding fastest among distribution pathways, while the seniors end-user segment deepens as Medicare Advantage plans increasingly embed dental benefits.
FDA monograph compliance governs active ingredient claims for anticaries and antiplaque products, while EPA regulations address triclosan phase-out and antimicrobial rinse environmental discharge. OSHA bloodborne pathogen standards shape infection control protocols in dental settings, indirectly influencing professional product specifications. Stakeholders must monitor how FDA sunscreen-style proposed rulemaking for fluoride dosing could reshape formulation thresholds and label requirements.
Market Dynamics
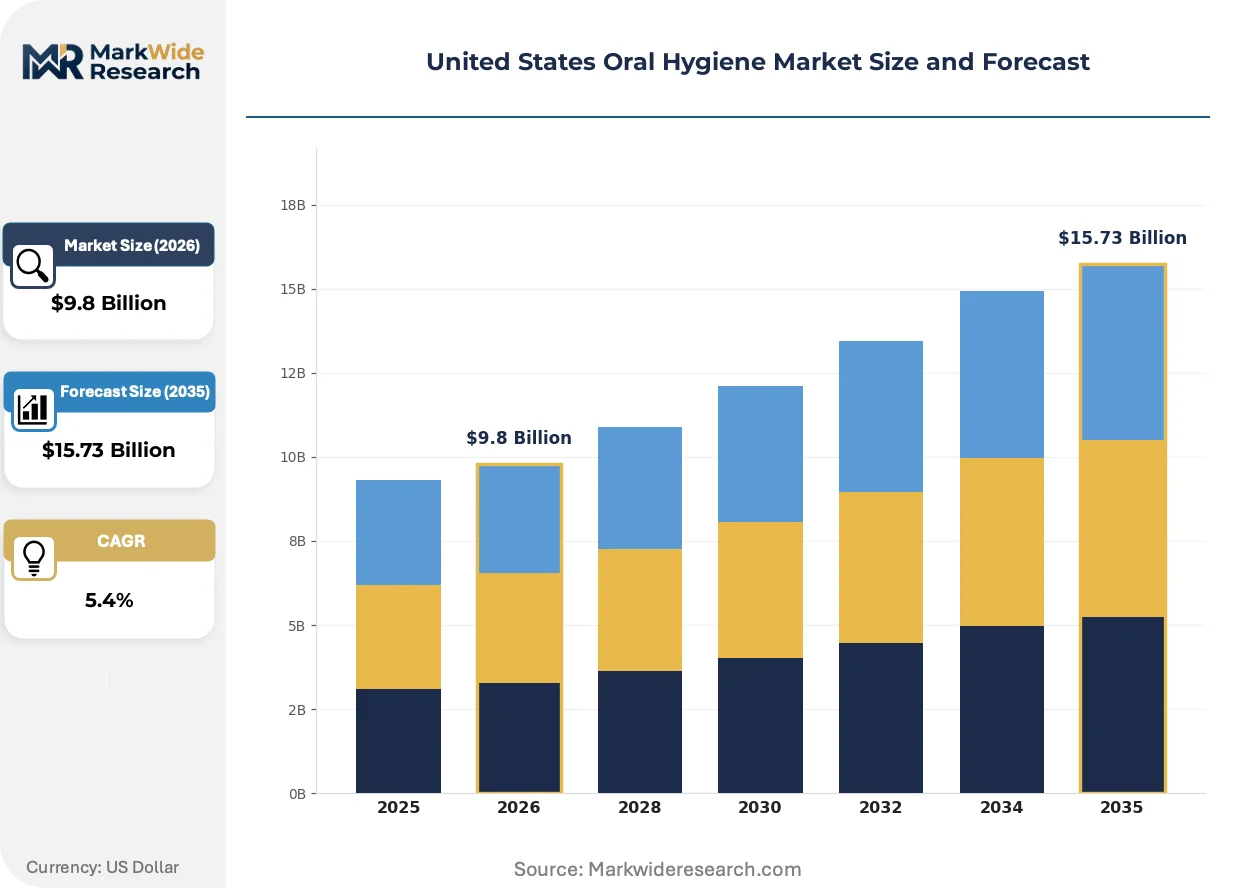
Medicare Advantage dental benefit expansion is restructuring demand composition across the United States Oral Hygiene Market, pulling volume toward senior-specific formulations and institutional procurement channels as payers consolidate preventive coverage.
Growth Catalysts
- OSHA bloodborne pathogen standards:Infection control mandates in dental clinics elevate demand for professional-grade sterilization products and single-use preventive applicators.
- Enzymatic whitening chemistry:Hydrogen peroxide alternatives reduce sensitivity complaints while maintaining efficacy, expanding adoption among adult consumers with compromised enamel.
- Texas and Florida population density:Sunbelt migration concentrates addressable households in markets with above-average dental service penetration and retail channel development.
Market Restraints
- Fluoride raw material concentration:Domestic sourcing constraints for pharmaceutical-grade sodium fluoride create formulation bottlenecks and input cost volatility for anticaries manufacturers.
- FDA monograph revision timelines:Pending sunscreen-style rulemaking for fluoride dosing thresholds extends product reformulation cycles and delays new claim approvals.
- Natural-ingredient substitution:Baking-soda and herbal formulations capture price-sensitive segments, compressing conventional synthetic chemistry volumes in mass retail.
Strategic Opportunities
- Rural Medicare Advantage penetration:Underserved counties in Appalachia and the Mountain West present whitespace for tele-dental bundled product programs.
- Online direct-to-consumer subscriptions:Replenishment automation for whitening strips and specialty rinses bypasses traditional retail slotting fees.
- California pediatric fluoride varnish mandates:School-based prevention programs create institutional procurement channels distinct from consumer retail.
Industry Challenges
- FDA compliance talent scarcity:Regulatory affairs specialists with monograph submission experience command premium compensation, constraining mid-tier manufacturer expansion.
- Legacy ERP integration:Batch manufacturing systems for toothpaste production require costly retrofitting to meet serialized track-and-trace requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Oral Hygiene Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Mouthwash, Dental Floss, Whitening Strips End User: Adults, Children, Seniors, Special Needs Distribution Channel: Online Retail, Supermarkets, Pharmacies, Convenience Stores Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Church & Dwight Co., Inc., Unilever PLC, Johnson & Johnson Services, Inc., Haleon PLC, Perrigo Company plc, Sunstar Suisse S.A., Koninklijke Philips N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Oral Hygiene Market Strategic Shifts & Innovations
Digital diagnostic integration and chemotherapeutic formulation advances are converging to blur the boundary between professional treatment and home-based preventive care across the United States Oral Hygiene Market.
Smart toothbrush sensor arrays paired with pressure-mapping algorithms are automating plaque detection feedback loops, enabling real-time brushing coaching that previously required hygienist intervention. Dental clinic chains in California and Texas are piloting these devices for remote patient monitoring between appointments. The technology is automating compliance documentation for insurers while compressing the traditional six-month recall cycle into continuous engagement models.
FDA proposed rulemaking for fluoride concentration labeling mirrors sunscreen dosing disclosure frameworks, forcing manufacturers to retest efficacy claims against revised exposure metrics. The regulatory shift elevates formulation transparency requirements while extending new product approval timelines. Pediatric dentistry segments are responding fastest, with professional varnish programs preemptively adopting concentration banding to align with anticipated monograph finalization.
Subscription-based replenishment for whitening strips and specialty rinses is displacing impulse-driven pharmacy purchasing, concentrating consumer lifetime value in direct channels. Major retail pharmacy chains are responding with membership programs that bundle oral care with prescription services. This behavioral pivot is most visible in suburban Florida markets where Medicare Advantage dental benefits reduce out-of-pocket sensitivity to premium product pricing.
United States Oral Hygiene Market Segmentation
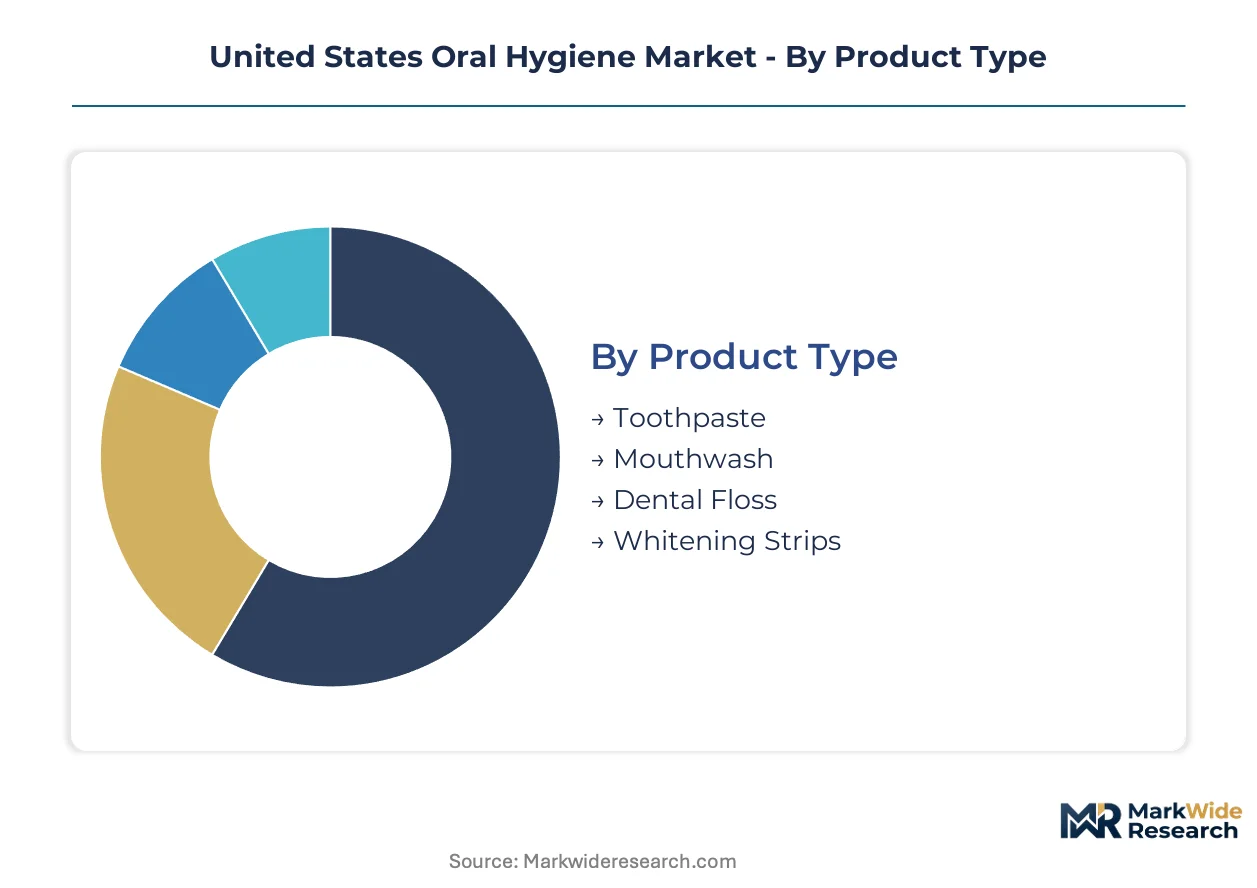
Segmentation in the United States Oral Hygiene Market reveals divergent margin structures across preventive versus cosmetic positioning. Product type splits between high-frequency consumables and discretionary treatments, while demographic targeting increasingly differentiates formulation chemistry and channel strategy.
Product Type:
Toothpaste dominates absolute volume, yet whitening strips command disproportionate margin contribution due to specialized chemistry and repeat purchase velocity.
- Toothpaste:Fluoride-based anticaries formulations constitute the baseline preventive standard, with sodium fluoride and stannous fluoride variants differentiated by sensitivity profiles. Demand concentrates in California, Texas, and Florida retail corridors where dental service penetration drives premium SKU adoption. FDA monograph compliance for anticaries claims elevates formulation costs relative to private-label alternatives.
- Mouthwash:Antiseptic rinses containing chlorhexidine or cetylpyridinium chloride serve both therapeutic and cosmetic endpoints, with alcohol-free variants gaining preference among senior users. Medicare Advantage dental benefit expansion pulls institutional procurement toward clinical-strength formulations in senior care facilities. EPA discharge regulations constrain antimicrobial chemistry options for manufacturers.
- Dental Floss:Waxed and unwaxed nylon or PTFE monofilament products address interdental plaque removal, with tape formats preferred for tight contact points.
- Whitening Strips:Hydrogen peroxide or carbamide peroxide gel delivery systems target enamel discoloration through oxidative chemistry.
Today's leader: Toothpaste. Tomorrow's challenger: Whitening Strips.
End User:
Aging demographics reshape demand composition, with senior-specific formulations requiring altered abrasivity and flavor profiles to accommodate medication interactions and dry mouth conditions.
- Adults:The largest addressable cohort drives whitening and sensitivity management categories, with enzymatic alternatives to peroxide chemistry expanding among compromised enamel cases. Subscription replenishment models concentrate lifetime value in direct channels for this segment.
- Seniors:Dry mouth formulations and reduced-abrasivity pastes address medication-induced xerostomia and gingival recession. Demand concentrates in Medicare Advantage-heavy markets including suburban Florida and Arizona retirement corridors.
- Children:Fluoride varnish programs and flavor-optimized pastes target early childhood caries prevention, with California school-based mandates creating institutional procurement channels distinct from retail.
- Special Needs:Adaptive delivery systems including foam applicators and suction toothbrushes accommodate motor control limitations.
Seniors are climbing the fastest as Medicare Advantage dental benefits restructure category purchasing.
Distribution Channel:
Channel strategy bifurcates between convenience-driven replenishment and clinical-grade procurement, with online platforms capturing subscription economics previously dominated by pharmacy loyalty programs.
- Online Retail:Direct-to-consumer subscriptions for whitening strips and specialty rinses bypass traditional slotting fees, with replenishment automation locking in repeat purchase behavior. Tele-dental bundled programs in rural Appalachia and Mountain West counties leverage this channel for underserved geographies.
- Supermarkets:Mass-market toothpaste and mouthwash volumes concentrate here, with private-label compression strongest in price-sensitive Sunbelt migration corridors.
- Pharmacies:Professional recommendation influence remains highest for therapeutic rinses and sensitivity formulations.
- Convenience Stores:Emergency replenishment and travel-size SKUs dominate, with limited assortment favoring established national brands.
Online Retail is gaining share fastest as subscription models displace impulse purchasing.
Price Tier:
Premium positioning correlates with clinical validation and specialized chemistry, while budget tiers face private-label substitution pressure in consolidated retail environments.
- Premium:Enzymatic whitening systems and prescription-strength fluoride formulations target consumers with dental professional relationships. FDA monograph compliance costs and clinical trial investments create barriers to entry.
- Mid-Range:Mainstream anticaries and cosmetic whitening products balance efficacy claims with mass-market accessibility.
- Budget:Basic fluoride pastes and alcohol-based mouthwashes serve price-sensitive households, with natural-ingredient alternatives from Church & Dwight capturing value-conscious switchers.
- Discount:Private-label and dollar-channel offerings compete on unit economics, with formulation sourcing from contract manufacturers.
Premium commands margin. Budget defends volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between states reshape production geography as manufacturers seek FDA-aligned facilities with lower operational overhead. Texas and Florida attract contract manufacturing investment due to favorable tax treatment and proximity to Medicare Advantage-dense senior populations. California's stringent environmental regulations push formulation R&D toward low-emission chemistry while creating premium pricing corridors.
California
School-based fluoride varnish mandates and pediatric dentistry density drive institutional procurement volume. California Air Resources Board (CARB) volatile organic compound limits constrain antiseptic mouthwash solvent selection. Los Angeles and San Diego corridors concentrate tele-dental pilot programs linking smart toothbrush data to dental clinic chains.
Texas
Sunbelt migration and above-average dental service penetration create mass-market toothpaste demand concentration. Texas Commission on Environmental Quality (TCEQ) industrial discharge rules affect manufacturing facility siting for rinse products. Dallas-Fort Worth and Houston metros anchor distribution hub expansion for online retail fulfillment networks.
Florida
Medicare Advantage dental benefit density and retirement corridor demographics pull senior-specific formulation demand. Florida Department of Health administrative rules govern school-based sealant programs creating procurement channels. Tampa and Orlando clusters host senior care facility supply chain consolidation for dry mouth and reduced-abrasivity products.
New York
Professional dental practice density and premium product adoption sustain midtown Manhattan and Long Island whitening strip volume. New York State Department of Health oversees Medicaid dental benefit administration affecting pediatric fluoride program reach. Buffalo and Rochester manufacturing zones retain legacy toothpaste production capacity serving Northeast retail corridors.
Illinois
Midwest distribution hub positioning and private-label manufacturing concentration support budget-tier toothpaste supply chains. Illinois Environmental Protection Agency wastewater discharge permits shape antimicrobial rinse production economics. Chicago metro logistics networks facilitate cross-border Canadian market access for US-manufactured oral care exports.
United States Oral Hygiene Market Key Industry Players
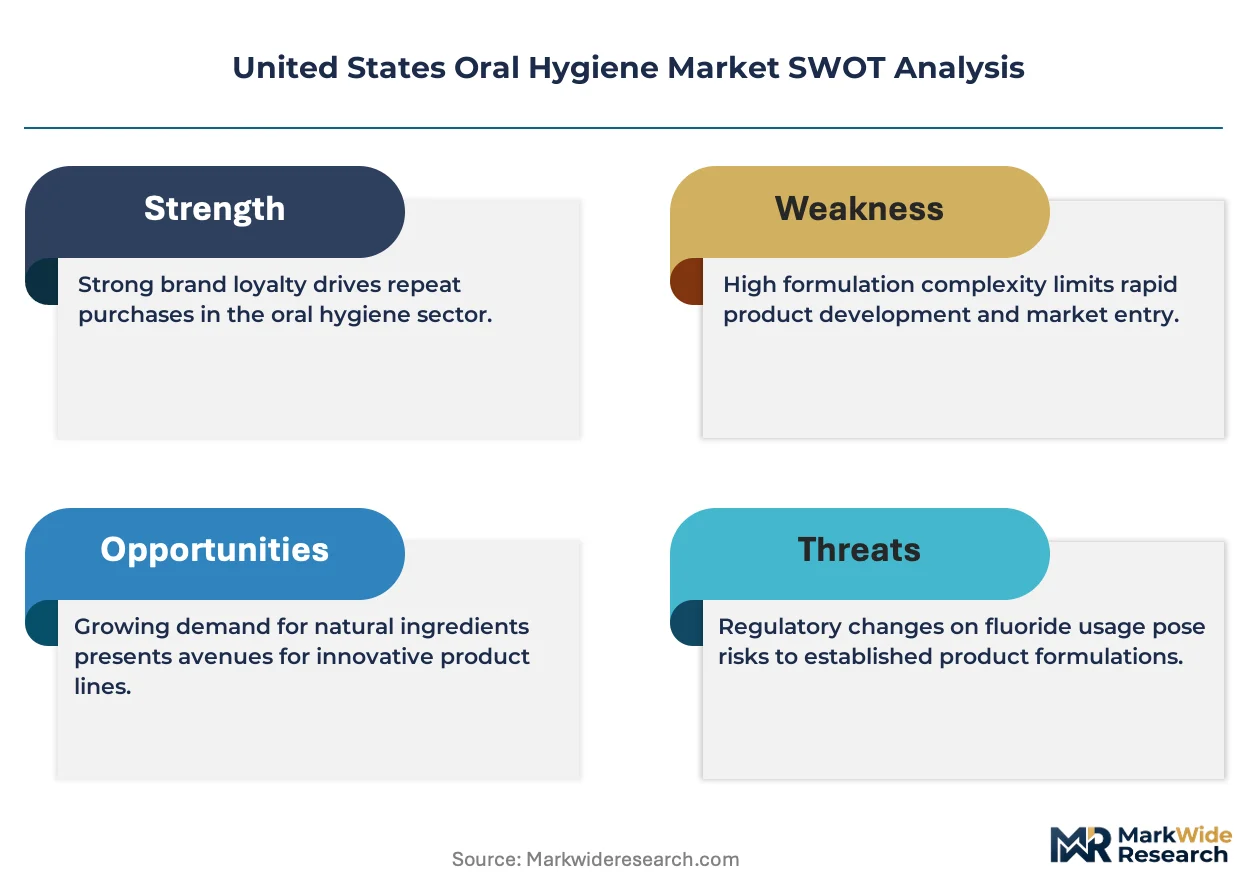
Branded specialists and contract manufacturers split share differently across segments, with consumer-facing portfolios commanding premium shelf positioning while private-label fabricators capture volume in consolidated retail. The structure consolidates around three national brand houses with professional channel anchoring, mid-tier natural-ingredient specialists, and Asian-headquartered device manufacturers. Strategic archetypes include fluoride chemistry patent holders, baking-soda formulation pure-plays, and subscription-direct whitening specialists. Competitive moves center on professional channel exclusivity agreements and direct-to-consumer subscription infrastructure buildout.
Within the branded multinational tier, Colgate-Palmolive Company and Procter & Gamble Company occupy positions defined by professional dental relationships and enzymatic whitening R&D intensity. Church & Dwight Co., Inc. represents the natural-ingredient archetype through baking-soda-based formulation heritage. These three entities exemplify divergent strategic vectors: clinical validation anchoring, chemistry innovation, and value-conscious segment capture respectively.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Church & Dwight Co., Inc. |
| Unilever PLC |
| Johnson & Johnson Services, Inc. |
| Haleon PLC |
| Perrigo Company plc |
| Sunstar Suisse S.A. |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade formulation chemists concentrated in New Jersey and North Carolina drive labor-cost differentials that widen pricing-tier spreads between premium FDA-validated products and mass-market alternatives. These specialized workforce clusters enable premium manufacturers to command sustained margin premiums while budget-tier competitors absorb cost compression through contract manufacturing in lower-overhead geographies.
Pricing Analysis
Distributor margin layers in professional dental channels sustain premium positioning for clinical-grade formulations, while mass retail markups compress mid-tier profitability. Three-tier pricing structure across premium, standard, and economy levels separates prescription-strength fluoride from mainstream anticaries pastes from private-label alternatives. Cost compression in the budget tier is intensifying because Church & Dwight's baking-soda formulations capture price-sensitive switchers. Senior Medicare Advantage enrollees show lowest price sensitivity due to embedded dental benefits, while uninsured adults in Sunbelt migration corridors exhibit highest elasticity.
Supply Chain Analysis
Workforce availability for pharmaceutical-grade sodium fluoride synthesis concentrates manufacturing in the United States, China, and India, with domestic facilities favored for FDA monograph compliance. Active ingredient supply draws from specialty chemical producers in the US Gulf Coast and Zhejiang province, while packaging materials source from domestic converters. Single-source vulnerability in pharmaceutical-grade fluoride creates formulation bottlenecks when purity specifications tighten. Distribution runs through dental supply distributors for professional channels and retail consolidation networks for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Oral Hygiene Market represents a late-cycle quality story where Medicare Advantage dental benefit expansion pulls demand toward premium specifications with clinical validation requirements.
For Market Incumbents: Deepen professional channel exclusivity agreements with dental clinic chains to anchor fluoride varnish programs against emerging natural-ingredient substitutes. Prioritize backward integration into pharmaceutical-grade fluoride sourcing to mitigate raw material concentration risk and secure formulation cost stability. For New Entrants and Emerging Players: Capture rural Medicare Advantage whitespace in Appalachia and Mountain West counties through tele-dental bundled subscription programs. The most penetrable segment is institutional procurement for school-based prevention mandates, with go-to-market execution through state health department contract vehicles. For Investors and Strategic Acquirers: Consumer health conglomerates with dental portfolio gaps are the most active acquirer in this space, targeting subscription-direct whitening specialists with established replenishment automation. The long-term viability window favors assets with FDA monograph submission capabilities and professional channel anchoring. Watch FDA fluoride concentration rulemaking finalization as the inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Replenishment automation locks lifetime value away from retail slotting fees in whitening strips. |
| Professional Channel Exclusivity Agreement | Fluoride varnish program anchoring with pediatric dentistry chains preempts competitor access. |
| Backward Integration into Active Ingredients | In-house sodium fluoride production mitigates pharmaceutical-grade sourcing bottlenecks. |
| Premium Tier Introduction | Enzymatic whitening systems with reduced sensitivity profiles capture compromised enamel segments. |
| Sustainability Repositioning | Low-emission chemistry alignment with California CARB limits opens premium pricing corridors. |
Research Approach
Coverage spans California, Texas, Florida, and New York, with primary inputs from each state combined with secondary validation across regulatory filings and trade databases. Interviews with dental supply distributors, pediatric dentistry practice administrators, Medicare Advantage plan formulary directors, and retail category buyers informed demand-side dynamics. Secondary sources include FDA monograph filings, EPA discharge compliance records, CMS Medicare dental benefit utilization data, and Nielsen retail audit tracking. Bottom-up product-level volume builds triangulate against top-down category spend estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type chemistry, end-user age cohort, distribution channel structure, and regional regulatory intensity. CAGRs derive from historical trajectory analysis adjusted for Medicare Advantage penetration curves and FDA rulemaking timelines. Forecast inputs incorporate smart toothbrush adoption rates and school-based prevention program expansion schedules.
FDA monograph revision timing, Medicare Advantage dental benefit carve-in acceleration, and pharmaceutical-grade fluoride supply disruptions are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about regulatory stability and payer benefit design continuity. Material deviation in named triggers warrants pause and re-evaluation of volume and value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Kids Oral Care Products Market
Oral Care
Oral Rinse Market
Oral Care
China Oral Care Market
Oral Care
Oral Hygiene Products Market
Oral Care
Global Toothbrush and Toothpaste Market
Oral Care
Canker Sores Treatment Market
Oral Care
Us Oral Care Market
Oral Care
Europe Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Manual Toothbrush Market
Oral Care
Oral Irrigator Market
Oral Care
Oral Antiseptics Market
Oral Care
Herbal Toothcare Market