
 Xerostomia Treatment Market | 2026-2036
Xerostomia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Xerostomia Treatment Market Analytics
Biomimetic mucoadhesive polymer science is rewriting formulation standards for xerostomia interventions, shifting development toward sustained-release platforms that mimic natural salivary film dynamics. GlaxoSmithKline plc leverages its consumer health division's channel depth to sustain shelf presence across pharmacy and dental networks. Pfizer Inc. anchors its position through prescription-grade portfolios tied to oncology supportive care protocols. 3M Company differentiates via dental professional channels where clinician recommendation drives patient adherence.
Xerostomia treatment encompasses therapeutic and palliative interventions designed to restore, substitute, or stimulate salivary function in patients with hyposalivation, typically formulated with carboxymethylcellulose, mucin-based compounds, or salivary stimulants such as pilocarpine at specified dosages. These products serve to prevent dental caries, preserve oral mucosal integrity, and improve mastication and speech in medically compromised populations. Artificial saliva and moisturizing gel segments occupy the mature volume core, while lozenge formats represent the fastest-growing administration form due to patient preference for discrete, portable relief. Cancer therapy applications generate concentrated demand tied to radiation protocol adjuvancy, whereas Sjögren's Syndrome represents a specialized but expanding addressable pool with higher willingness to pay for prescription options.
FDA oversight of active pharmaceutical ingredients in salivary stimulants shapes clinical trial requirements and labeling standards for prescription xerostomia products, while the EPA regulates manufacturing discharge for facilities producing polymer-based saliva substitutes. The EU MDR and REACH frameworks impose additional compliance burdens on suppliers seeking European market access, elevating documentation and biocompatibility testing costs. Stakeholders must monitor evolving FDA monograph proceedings for OTC oral demulcents, as reclassification decisions would reshape competitive boundaries between pharmaceutical and consumer health entrants.
Market Dynamics
Biomimetic mucoadhesive polymer science is compressing formulation development cycles while elevating clinical efficacy thresholds for xerostomia interventions. This technological inflection is redistributing competitive advantage toward firms with polymer chemistry capabilities and dental professional channel access.
Growth Catalysts
- FDA Monograph Evolution:The agency's pending reclassification of oral demulcents is expanding OTC eligibility for saliva substitutes, lowering patient access barriers and accelerating pharmacy channel penetration.
- Oncology Protocol Integration:Radiation therapy centers in the United States are embedding xerostomia management into standardized head-and-neck cancer care pathways, creating institutional procurement pull.
- Salivary Stimulant Formulation:Pilocarpine delivery innovations are improving tolerability profiles, expanding addressable populations beyond Sjögren's Syndrome into polypharmacy-induced dry mouth.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Pilocarpine API supply chains concentrate among specialized alkaloid manufacturers, exposing formulators to single-source dependency risks.
- REACH Compliance Burden:ECHA documentation requirements for polymer-based saliva substitutes elevate European market entry costs, compressing margins for mid-tier entrants.
- Generic Substitution Pressure:Patent-expired pilocarpine formulations face commoditization as compounding pharmacies and regional generics erode branded prescription pricing power.
Strategic Opportunities
- Pediatric Oncology Underservice:Formulations optimized for children receiving chemotherapy represent an unaddressed segment with limited competing solutions and higher caregiver willingness to pay.
- Telehealth Integration:Remote oral health screening platforms are creating direct-to-patient distribution channels that bypass traditional dental clinic gatekeepers.
- EU MDR Harmonization:The Medical Device Regulation's consolidated approval pathway offers first-mover advantage to firms achieving CE marking ahead of 2027 enforcement deadlines.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with mucoadhesive film expertise command premium compensation, constraining R&D expansion at emerging competitors.
- Biocompatibility Testing Timelines:ISO 10993 cytotoxicity and sensitization studies for novel polymer platforms extend development cycles by 18-24 months.
- Legacy System Integration:Dental practice management software lacks standardized fields for xerostomia severity tracking, complicating outcomes-based reimbursement pilots.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Xerostomia Treatment Market |
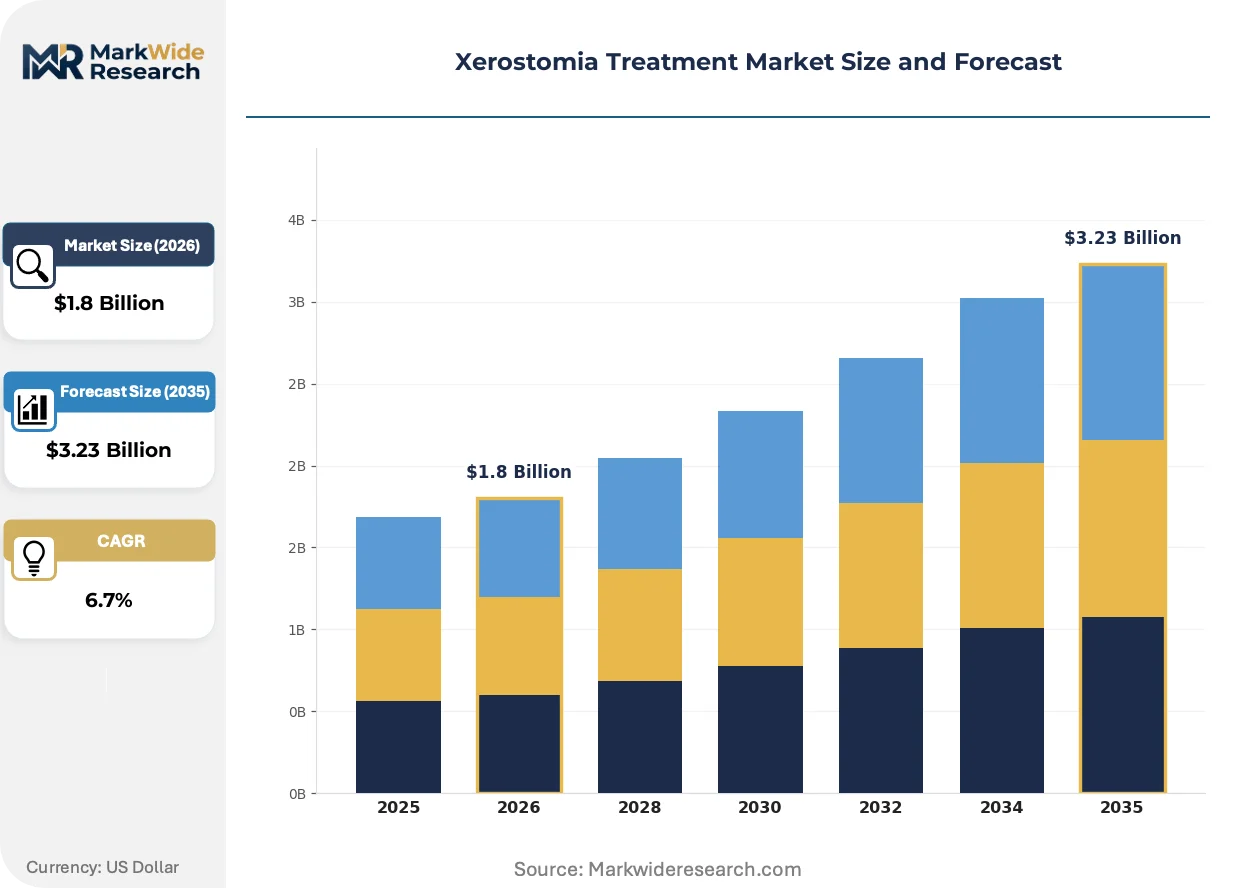
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artificial Saliva, Mouth Rinse, Moisturizing Gel, Lozenge Application: Dental Care, Cancer Therapy, Sjögren's Syndrome, Nerve Damage End User: Hospitals, Dental Clinics, Home Care, Rehabilitation Centers Administration Route: Oral, Topical, Injectable, Inhalation |
| Companies Covered | GlaxoSmithKline plc, Pfizer Inc., 3M Company, Sun Pharmaceutical Industries Ltd., Parnell Pharmaceuticals Inc., Hikma Pharmaceuticals PLC, Colgate-Palmolive Company, Synedgen Inc., Quest Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Xerostomia Treatment Market Evolving Landscape
Formulation science convergence with digital health infrastructure is redefining how xerostomia interventions are developed, regulated, and delivered to patients across care settings.
Electrospun nanofiber membranes functionalized with hyaluronic acid and mucin analogs are enabling sustained-release saliva substitutes that replicate natural film dynamics for 6-8 hours. Academic medical centers in Germany and Japan are piloting these platforms in radiation oncology protocols. Conventional carboxymethylcellulose gels with 30-60 minute efficacy windows are rendering obsolete for severe hyposalivation cases.
REACH authorization requirements for novel polymer chemistries are tightening substance volume thresholds and elevating chronic toxicity data obligations for saliva substitute manufacturers. The European Chemicals Agency's 2024 updated guidance on respiratory sensitization is forcing reformulation of spray-delivery products. Suppliers targeting EU dental clinics are accelerating biopolymer sourcing from pre-registered substance inventories.
Direct procurement by hospital oncology pharmacies is displacing traditional wholesale distribution for prescription salivary stimulants in the United States. Integrated delivery networks are consolidating formulary decisions, compressing vendor counts from 8-12 suppliers to 3-4 preferred partners. This concentration is most visible in National Cancer Institute-designated centers where protocol standardization drives volume commitments.
Xerostomia Treatment Market Segmentation
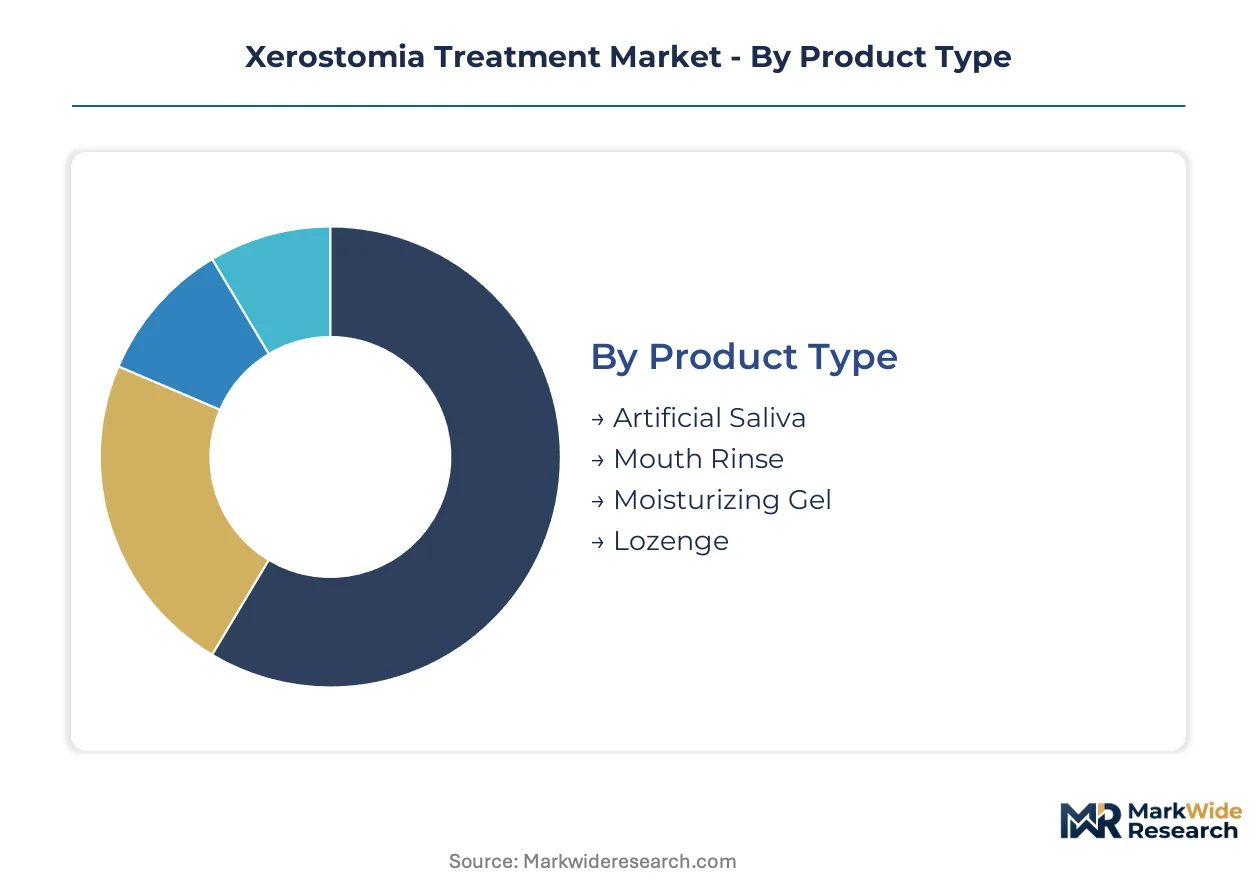
Xerostomia treatment markets fragment across formulation chemistry, clinical setting, and patient severity. Each segmentation axis reveals distinct margin structures and regulatory pathways that shape competitive positioning.
Product Type:
Mature liquid formats dominate current volume, while solid-dose innovations are capturing preference shifts toward portability and discretion.
- Artificial Saliva:Polymer-based solutions using carboxymethylcellulose or mucin analogs replicate salivary film properties for 30-60 minute intervals. Hospital oncology pharmacies in the United States procure these in bulk for radiation protocol adjuvancy, though reimbursement compression limits branded pricing power.
- Lozenge:Sustained-release matrices incorporating hyaluronic acid or electrolyte blends offer 2-4 hour relief without the mess of gels. Dental clinic dispensing of lozenge formats is climbing fastest as clinicians prioritize patient adherence and discrete daytime use.
- Mouth Rinse:Alcohol-free formulations with xylitol and calcium phosphate target caries prevention in hyposalivation patients.
- Moisturizing Gel:High-viscosity polymers adhere to oral mucosa for overnight relief in severe cases.
Artificial Saliva handles the majority of throughput; Lozenge is climbing the fastest on share.
Application:
Demand concentrates where iatrogenic salivary gland damage intersects with institutional care protocols and reimbursement availability.
- Cancer Therapy:Radiation-induced xerostomia in head-and-neck oncology drives prescription-grade stimulant demand and high-efficacy substitute procurement. National Cancer Institute-designated centers in the United States embed pilocarpine protocols into standardized care pathways, creating concentrated volume pull.
- Sjögren's Syndrome:Autoimmune etiology produces chronic, progressive hyposalivation requiring lifelong management. Rheumatology and oral medicine co-management in German university hospitals is expanding addressable prescription volumes for secretagogue therapies.
- Dental Care:Polypharmacy-induced dry mouth in aging populations supports OTC saliva substitute uptake.
- Nerve Damage:Postsurgical and trauma-related salivary dysfunction represents a smaller, reimbursement-challenged segment.
Cancer Therapy anchors institutional procurement volumes; Sjögren's Syndrome shows the steepest expansion trajectory as diagnostic criteria broaden.
End User:
Channel economics diverge sharply between reimbursement-dependent institutional settings and cash-pay retail environments.
- Dental Clinics:Chairside diagnosis and product sampling drive patient trial and adherence. 3M Company's professional channel penetration in United States dental practices demonstrates how clinician recommendation converts to recurring purchase behavior.
- Home Care:Direct-to-consumer e-commerce and retail pharmacy access support OTC maintenance therapy for chronic conditions.
- Hospitals:Oncology pharmacy integration and formulary standardization concentrate procurement decisions.
- Rehabilitation Centers:Stroke and neurodegenerative patient populations generate episodic demand for swallowing-safe formulations.
Dental Clinics capture the highest-margin transactions; Home Care is gaining share fastest as telehealth screening expands direct patient access.
Administration Route:
Patient tolerance and onset speed requirements determine route selection across acute versus chronic management scenarios.
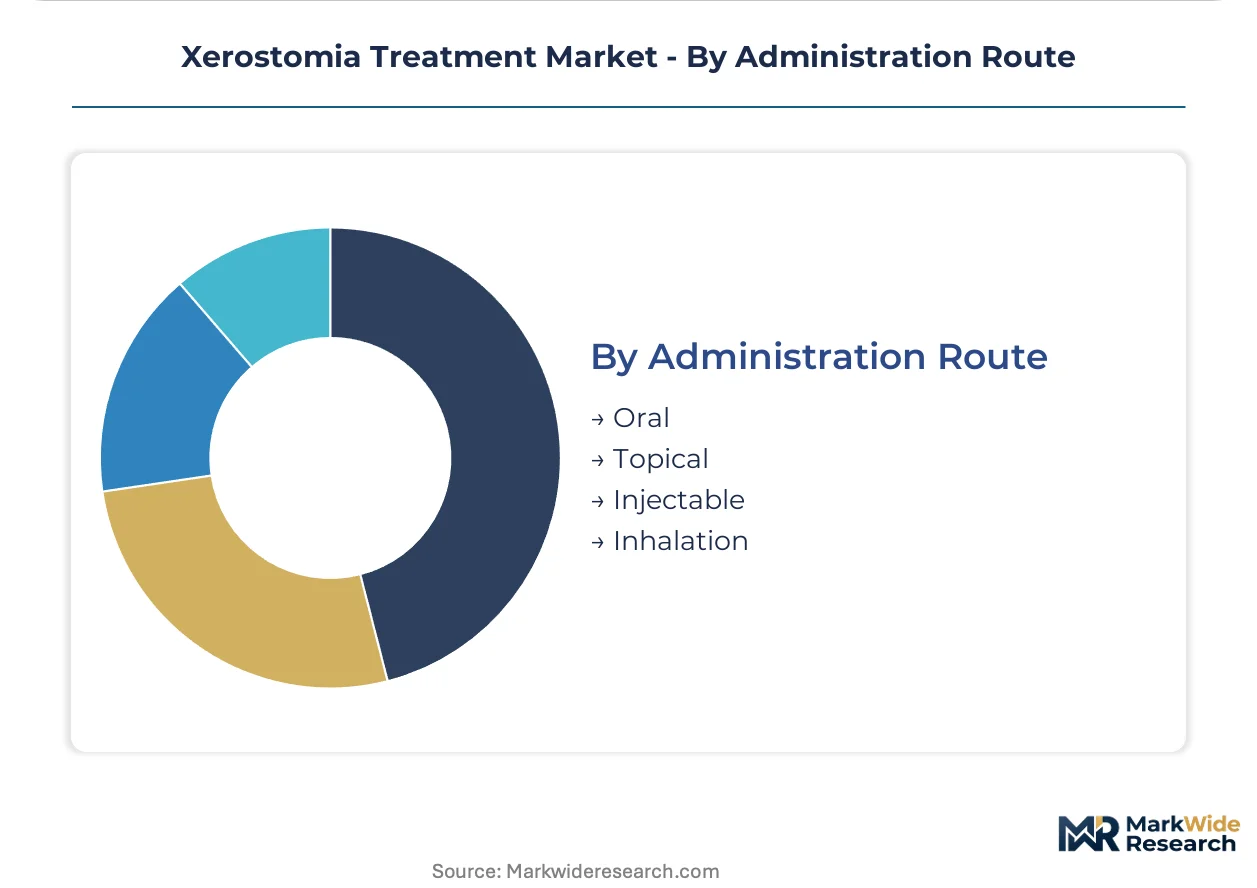
- Oral:Systemic secretagogues like pilocarpine tablets stimulate residual gland function through muscarinic receptor activation. FDA monograph proceedings for OTC oral demulcents are expanding eligibility for non-prescription saliva substitutes, lowering United States patient access barriers.
- Topical:Mucoadhesive gels, sprays, and rinses provide immediate symptomatic relief without systemic side effects.
- Injectable:Botulinum toxin interventions for sialorrhea-excess conditions represent an adjacent therapeutic space with limited xerostomia crossover.
- Inhalation:Nebulized saliva substitutes remain experimental, with pilot studies at Japanese academic medical centers exploring film deposition patterns.
Oral administration commands the dominant volume position; Topical delivery is expanding most quickly as polymer science improves mucoadhesion duration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports polymer-based saliva substitutes to oncology centers across the Netherlands and Scandinavia, establishing a north-south trade corridor in European xerostomia therapeutics. This exchange pattern concentrates formulation expertise in German chemical clusters while distributing finished products through Dutch pharmaceutical wholesalers.
United States
National Cancer Institute-designated centers in Houston and Boston drive prescription-grade pilocarpine procurement for radiation protocol adjuvancy. FDA monograph proceedings for OTC oral demulcents are expanding pharmacy channel eligibility for non-prescription saliva substitutes. The Mayo Clinic in Rochester anchors outcomes research that shapes reimbursement criteria across Midwestern integrated delivery networks.
Germany
University hospitals in Heidelberg and Munich are expanding rheumatology-oral medicine co-management for Sjögren's Syndrome patients requiring lifelong secretagogue therapy. ECHA documentation requirements under REACH elevate biocompatibility testing costs for polymer-based formulations entering the European market. The Frankfurt-Rhine-Main chemical cluster supplies mucoadhesive polymer precursors to dental device manufacturers throughout Baden-Württemberg.
Japan
Academic medical centers in Tokyo and Osaka are piloting electrospun nanofiber membranes in radiation oncology protocols for head-and-neck cancer patients. PMDA oversight of salivary stimulant labeling shapes clinical trial requirements for muscarinic receptor agonists. The Kansai region's biomedical manufacturing corridor concentrates hyaluronic acid sourcing for sustained-release lozenge production.
United Kingdom
NHS England's specialized commissioning frameworks concentrate xerostomia management referrals to teaching hospitals in London and Manchester. MHRA alignment with EU MDR transitional provisions is extending CE marking recognition timelines for dental clinic-dispensed moisturizing gels. The Cambridge-Oxford life sciences arc hosts polymer chemistry startups developing next-generation mucoadhesive platforms.
India
CDSCO regulatory pathways for fixed-dose combinations are attracting contract manufacturing inquiries from European pharmaceutical firms seeking cost-competitive pilocarpine production. Sun Pharmaceutical Industries Ltd. and regional generic houses in Gujarat and Maharashtra supply API to formulators across Southeast Asia and Africa. Hyderabad's bulk drug manufacturing cluster is expanding capacity for alkaloid-derived salivary stimulants.
Xerostomia Treatment Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: multinational consumer health divisions with pharmacy channel dominance, prescription-focused pharmaceutical firms with oncology protocol relationships, and specialized dental professional suppliers with clinician recommendation networks. Strategic moves concentrate on portfolio diversification into pediatric formulations and backward integration into polymer chemistry capabilities. Geographic expansion through distributor partnerships in Asia-Pacific markets and technology licensing for sustained-release platforms represent the dominant competitive vectors.
Within the multinational tier, GlaxoSmithKline plc and Pfizer Inc. occupy positions shaped by consumer health versus prescription-grade portfolio differentiation. 3M Company anchors the dental professional channel archetype, where clinician recommendation drives patient adherence and recurring purchase behavior. These three firms exemplify how channel access—pharmacy shelf presence, oncology formulary inclusion, and dental practice penetration—determines competitive positioning more than formulation chemistry alone.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Pfizer Inc. |
| 3M Company |
| Sun Pharmaceutical Industries Ltd. |
| Parnell Pharmaceuticals Inc. |
| Hikma Pharmaceuticals PLC |
| Colgate-Palmolive Company |
| Synedgen Inc. |
| Quest Products Inc. |
| Others |
Value Network & Pricing Analysis
Pilocarpine API manufacturing concentrates in Indian alkaloid extraction facilities and specialized European chemical processors, anchoring margin capture upstream while downstream formulators face reimbursement compression in United States oncology channels. This concentration pattern elevates input cost volatility for prescription-grade salivary stimulants while polymer-based saliva substitutes compete on formulation differentiation rather than raw material sourcing.
Pricing Analysis
Prior-generation carboxymethylcellulose gels command economy positioning at 30-60 minute efficacy windows, while current-generation hyaluronic acid matrices occupy standard tiers at 2-4 hour release profiles, and next-generation electrospun nanofiber platforms target premium segments with 6-8 hour biomimetic film dynamics. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 biocompatibility certification status and mucoadhesion duration metrics. Cost compression in economy-tier artificial saliva is intensifying because Indian and Chinese generic houses are expanding carboxymethylcellulose bulk production. Hospital oncology pharmacies exhibit lowest price sensitivity due to formulary standardization protocols, while retail pharmacy OTC segments show highest elasticity to co-pay differentials.
Supply Chain Analysis
REACH authorization restrictions on novel polymer chemistries are constraining European-sourced mucoadhesive precursors, limiting cross-border flows of hyaluronic acid derivatives and experimental nanofiber substrates. Active pharmaceutical ingredient production draws from India, Germany, and Japan, while finished formulation manufacturing clusters in the United States, Germany, and Japan. Raw material dependencies include pilocarpine alkaloids from nightshade extraction, synthetic polymer precursors from petrochemical feedstocks, and pharmaceutical-grade hyaluronic acid from bacterial fermentation. Single-source vulnerability permeates specialized alkaloid API channels where European processors dominate high-purity extraction. Distribution runs through hospital oncology pharmacies for prescription stimulants, dental professional channels for clinician-dispensed gels, and retail pharmacy networks for OTC maintenance products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive boundaries as telehealth oral health screening creates direct-to-patient distribution ecosystems that bypass traditional dental clinic gatekeepers, requiring interoperability investments in remote diagnostic data standards.
For Market Incumbents: Entrench formulary position at National Cancer Institute-designated centers through protocol integration and outcomes data partnerships that demonstrate pilocarpine efficacy in radiation adjuvancy. Deepen backward integration into polymer chemistry capabilities via acquisition of German mucoadhesive specialists or captive supply agreements with Frankfurt-Rhine-Main chemical clusters. Generic substitution pressure from Indian compounding pharmacies threatens branded prescription margins; defend through FDA monograph engagement that raises OTC eligibility barriers.
For New Entrants and Emerging Players: Establish a beachhead in pediatric oncology formulations where caregiver willingness to pay exceeds standard adult segments and competing solutions remain sparse. Target telehealth-integrated direct distribution channels that circumvent 3M Company's dental professional network dominance. White-space opportunities concentrate in sustained-release lozenge formats optimized for chemotherapy-induced xerostomia in children, with go-to-market execution through pediatric oncology telehealth platforms.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dental device manufacturers holding clinician recommendation networks but lacking polymer R&D depth. Long-term viability hinges on formulation science capabilities that survive regulatory tightening under EU MDR and REACH substance volume thresholds. Acquisition targets with pre-registered polymer inventories and CE marking pathways ahead of enforcement deadlines offer defensive positioning. Watch FDA monograph reclassification proceedings as the inflection signal that would reshape OTC eligibility boundaries and competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Biomimetic Polymer R&D Partnership | Electrospun nanofiber platforms at Heidelberg and Osaka academic centers accelerate next-generation efficacy windows. |
| Telehealth Platform Integration | Remote oral health screening bypasses dental clinic gatekeepers and captures direct-to-patient subscription revenue. |
| EU MDR Harmonization Sprint | CE marking ahead of enforcement deadlines secures first-mover positioning in German and Scandinavian oncology channels. |
| Pediatric Formulation Development | Chemotherapy-optimized lozenges address underserved children segments with premium pricing tolerance from caregivers. |
| Backward Polymer Integration | Captive supply of mucoadhesive precursors from Frankfurt-Rhine-Main clusters insulates against REACH authorization delays. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with formulation scientists at polymer chemistry firms, regulatory affairs directors navigating FDA monograph proceedings, oncology pharmacy procurement managers at integrated delivery networks, and dental clinic practice owners; alongside secondary validation through FDA 510(k) filings, EMA medical device registrations, ClinicalTrials.gov protocol databases, and REACH substance volume records. Bottom-up demand modeling across patient severity segments and top-down supply validation through manufacturer capacity disclosures were triangulated against reimbursement database benchmarks.
Forecast inputs incorporated patient population epidemiology, radiation therapy protocol penetration rates, and polymer science innovation adoption curves across the projection horizon. Segmentation dimensions modeled include formulation chemistry, clinical application severity, administration route preference, end-user channel economics, and regional regulatory cluster alignment. CAGRs were derived from compound growth trajectory analysis anchored to base-year demand quantification and terminal-year scenario weighting. Industry-specific forecast inputs encompassed oncology patient volume projections and Sjögren's Syndrome diagnostic expansion rates.
Stress conditions across FDA monograph reclassification timing, REACH substance authorization delays, and pilocarpine API supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding reimbursement stability and polymer science talent availability. Material shifts in telehealth regulatory frameworks or EU MDR enforcement timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
GCC Oral Hygiene Market
Oral Care
Adult Oral Care Products Market
Oral Care
Mouthwash Market
Oral Care
China Oral Care Market
Oral Care
Global Halitosis Market
Oral Care
Toothcare Market
Oral Care
Oral Irrigator Market
Oral Care
Europe Oral Care Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Halitosis Treatment Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Kids Oral Care Products Market
Oral Care
Herbal Toothpaste Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
South America Oral Care Market