
 Kids Oral Care Products Market | 2026-2036
Kids Oral Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Oral Care Products Market Analytics
Bundle configurations pairing toothpaste with character-themed toothbrushes is realigning how parents evaluate value at shelf. Colgate-Palmolive Company leverages licensed entertainment partnerships to command premium placement in big-box retail. Procter & Gamble Company sustains formulation credibility through ADA Seal acceptance programs. Church & Dwight Co., Inc. competes on per-unit affordability via high-volume club channel packs.
Kids oral care products encompass age-appropriate dentifrices, brushes, rinses, and interdental cleaners formulated with reduced fluoride concentrations, mild abrasives, and flavor profiles engineered for pediatric compliance. These products serve the primary commercial purpose of establishing preventive hygiene habits before permanent dentition emerges. Toothpaste dominates value contribution due to replenishment frequency, while mouthwash registers faster velocity as rinse protocols expand into early elementary routines. Fluoride formulations anchor professional recommendation channels, whereas herbal alternatives capture parent segments seeking clean-label positioning.
The FDA governs active ingredient concentrations and labeling claims for children's fluoride dentifrices under OTC monograph standards, while the EPA regulates triclosan phase-out in antimicrobial formulations. The American Dental Association's Seal program shapes dentist endorsement patterns that cascade into retail purchasing decisions. Stakeholders must monitor evolving state-level fluoride varnish program expansions and their downstream effects on home-care product recommendation protocols.
Market Dynamics
Licensed entertainment partnerships are restructuring shelf economics in mass retail, as character-themed bundling commands premium placement fees and resets parent value-perception calculations at point-of-sale.
Growth Catalysts
- ADA Seal acceptance programs:Pediatric dentist endorsement cascades into retail purchasing decisions, creating professional credibility loops that sustain formulation premiums.
- State-level fluoride varnish program expansions:Public health protocols in the United States generate downstream demand for complementary home-care products.
- Club channel volume packs:Big-box retail formats in the United States accelerate per-unit affordability positioning and expand household penetration rates.
Market Restraints
- Triclosan phase-out mandates:EPA antimicrobial regulations force reformulation of established rinse protocols, compressing R&D timelines for alternative actives.
- Fluoride concentration ceilings:FDA OTC monograph standards cap active ingredient levels, limiting differentiation space in professional recommendation channels.
- Private-label shelf-space competition:Mass retail channel concentration in the United States erodes branded margin structures through accelerated store-brand placement.
Strategic Opportunities
- Clean-label herbal alternatives:Parent segments seeking ingredient transparency present white space for botanical formulations outside fluoride-centric positioning.
- Early elementary rinse protocols:Mouthwash velocity expansion into younger age brackets creates new application entry points before permanent dentition emergence.
- Pediatric dental clinic preventive care networks:Professional channel integration offers direct-to-parent recommendation pathways bypassing retail margin stacking.
Industry Challenges
- Flavor engineering complexity:Pediatric compliance requirements demand sensory profiles that balance palatability with mild abrasive compatibility, stretching formulation science capabilities.
- Dual regulatory navigation:Simultaneous FDA active ingredient oversight and EPA environmental discharge standards for manufacturing create compliance timeline friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Oral Care Products Market |
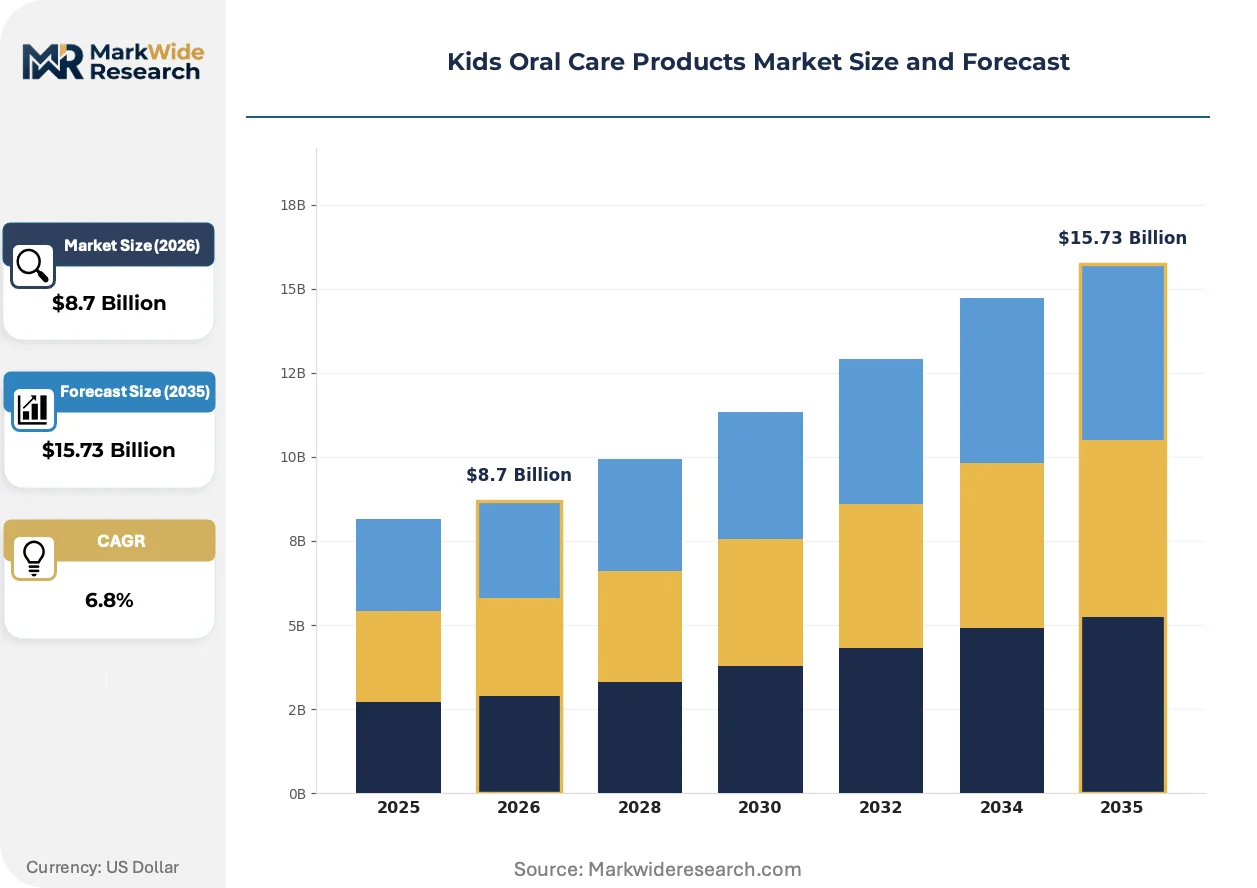
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Toothbrushes, Mouthwash, Dental Floss Formulation: Fluoride, Non-Fluoride, Herbal, Sensitivity Packaging Type: Tubes, Bottles, Jars, Sachets Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Johnson & Johnson Services, Inc., Church & Dwight Co., Inc., Unilever Plc, GlaxoSmithKline PLC, Pigeon Corporation, Lion Corporation, Sunstar Suisse S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Oral Care Products Market Evolving Landscape
Smart packaging and digital engagement layers are embedding habit-formation tools directly into product interfaces, transforming routine compliance from parental enforcement into child-directed interaction.
Enzymatic anti-cavity systems are converging with fluoride-free positioning to serve clean-label demand clusters. Premium parent segments in the United States and Germany are adopting these formulations at accelerated trial rates. This convergence is compressing the traditional fluoride-or-nothing segmentation and forcing portfolio diversification across premium tiers.
REACH chemical safety standards in Europe are tightening preservative allowances in children's rinse formulations. Manufacturers serving EU distribution channels are reformulating to exclude flagged biocides ahead of enforcement deadlines. Pediatric mouthwash SKUs bound for European markets now carry distinct ingredient decks from identical-positioned United States variants.
Subscription replenishment models are displacing episodic retail purchasing among urban United States households. Direct-to-parent delivery services bundle age-progressive product sequences that auto-advance formulations as children age. This channel shift is most visible in coastal metropolitan markets where convenience premiums outweigh mass retail price advantages.
Kids Oral Care Products Market Segmentation
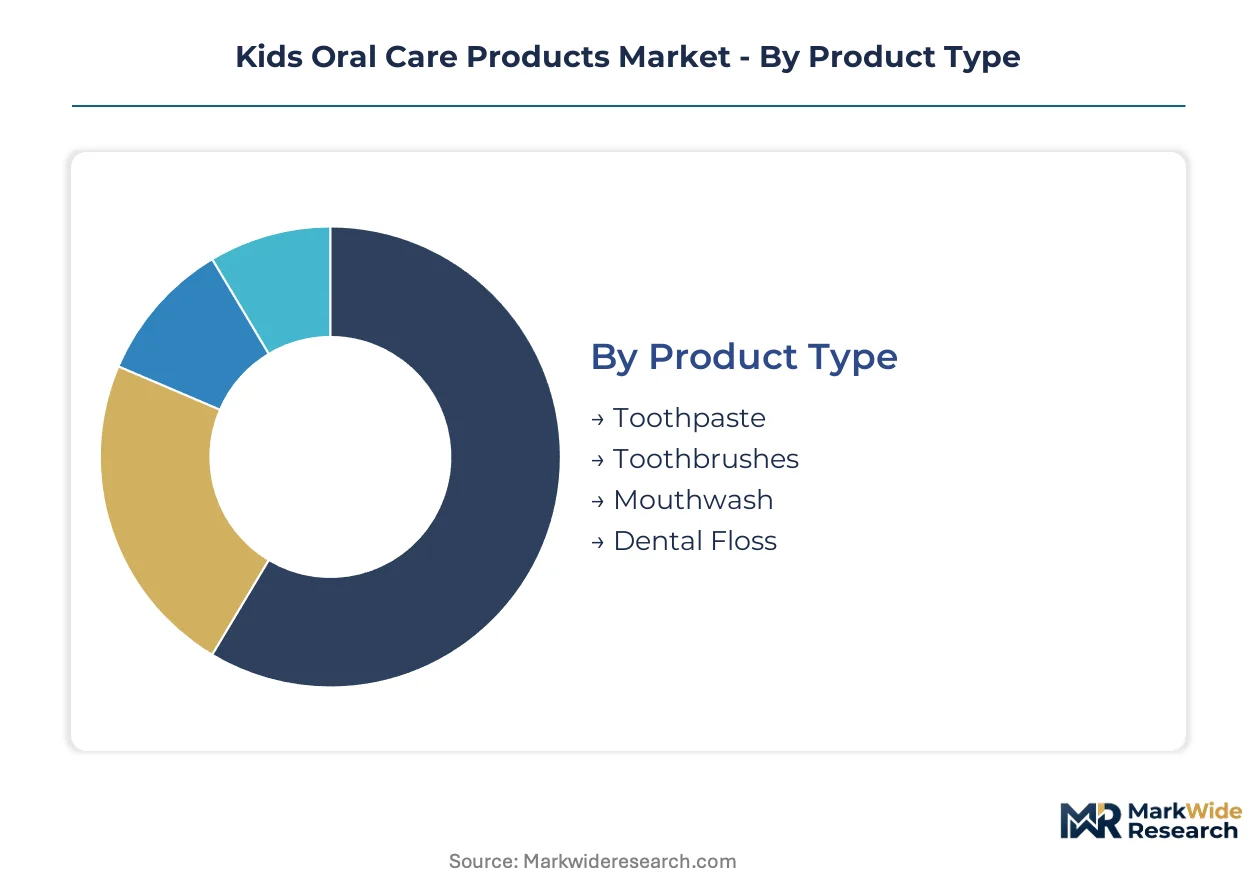
Segmentation in kids oral care products reveals how purchasing decisions bifurcate between clinical credibility and convenience economics. Parents evaluate formulations through dentist recommendation filters while children drive sensory acceptance, creating dual-audience product architecture.
Product Type:
Toothpaste commands the largest wallet share due to replenishment velocity, while mouthwash penetration accelerates as rinse protocols target younger age brackets.
- Toothpaste:Age-graded dentifrices carry reduced fluoride concentrations per FDA OTC monograph standards, with mild abrasives and fruit-forward flavor engineering to sustain pediatric compliance. Replenishment frequency anchors value contribution in United States mass retail and pharmacy channels, where ADA Seal acceptance drives professional endorsement cascades.
- Toothbrushes:Character-themed handles and soft-bristle configurations dominate shelf placement, with licensed entertainment partnerships commanding premium slotting fees in big-box retail. Manual brushes retain volume leadership while electric variants gain traction in urban United States households seeking habit-formation assistance.
- Mouthwash:Alcohol-free formulations with mild flavors serve early elementary routines, expanding application entry points before permanent dentition.
- Dental Floss:Floss picks with ergonomic grips address fine motor skill limitations in younger children, capturing parent preference for interdental compliance tools.
Toothpaste leads on scale; mouthwash leads on momentum.
Formulation:
Regulatory ceilings on active ingredients compress differentiation space, pushing competition toward sensory engineering and clean-label positioning.
- Fluoride:Concentration-capped per FDA monograph standards, these formulations anchor pediatric dentist recommendations and professional channel credibility. ADA Seal programs sustain premium pricing in United States pharmacy and dental clinic networks.
- Non-Fluoride:Enzymatic anti-cavity systems serve parent segments seeking alternatives to fluoride-centric protocols, with trial rates climbing fastest in Germany and coastal United States metropolitan markets.
- Herbal:Botanical extracts and essential oil blends capture clean-label demand, though efficacy claims face stricter scrutiny under EPA antimicrobial discharge standards for manufacturing.
- Sensitivity:Potassium nitrate formulations address pediatric enamel hypersensitivity, typically co-prescribed with professional fluoride varnish programs.
Fluoride formulations dominate recommendation channels; non-fluoride alternatives are climbing the fastest.
Packaging Type:
Unit economics and child-directed engagement features determine format selection across retail and subscription channels.
- Tubes:Squeeze-dispensing formats with flip-top closures dominate toothpaste SKUs, optimized for parental controlled dosing and travel portability.
- Bottles:Pump-dispensing mouthwash containers with measuring caps support independent use by early elementary children, reducing spillage.
- Jars:Wide-mouth containers serve floss pick and brush head storage accessories, extending product lifecycle through organizational utility.
- Sachets:Single-serve packets target travel and trial occasions, with concentrated penetration in airline amenity kits and dental clinic sample programs.
Tubes sustain volume leadership; sachets represent the fastest-growing trajectory for trial conversion.
Distribution Channel:
Channel selection reflects trade-offs between price transparency, professional credibility, and replenishment convenience.
- Online Retail:Subscription auto-replenishment models displace episodic purchasing in United States coastal metropolitan markets, bundling age-progressive product sequences. Direct-to-parent delivery captures convenience premiums but sacrifices immediate gratification.
- Supermarkets:Mass retail concentration in the United States accelerates private-label shelf-space competition, with club channel volume packs driving per-unit affordability positioning.
- Pharmacies:Professional recommendation proximity sustains branded margin structures, with pharmacist counsel reinforcing ADA Seal credibility.
- Specialty Stores:Pediatric dental clinic retail counters and natural product boutiques serve clean-label seekers, bypassing mass retail margin stacking.
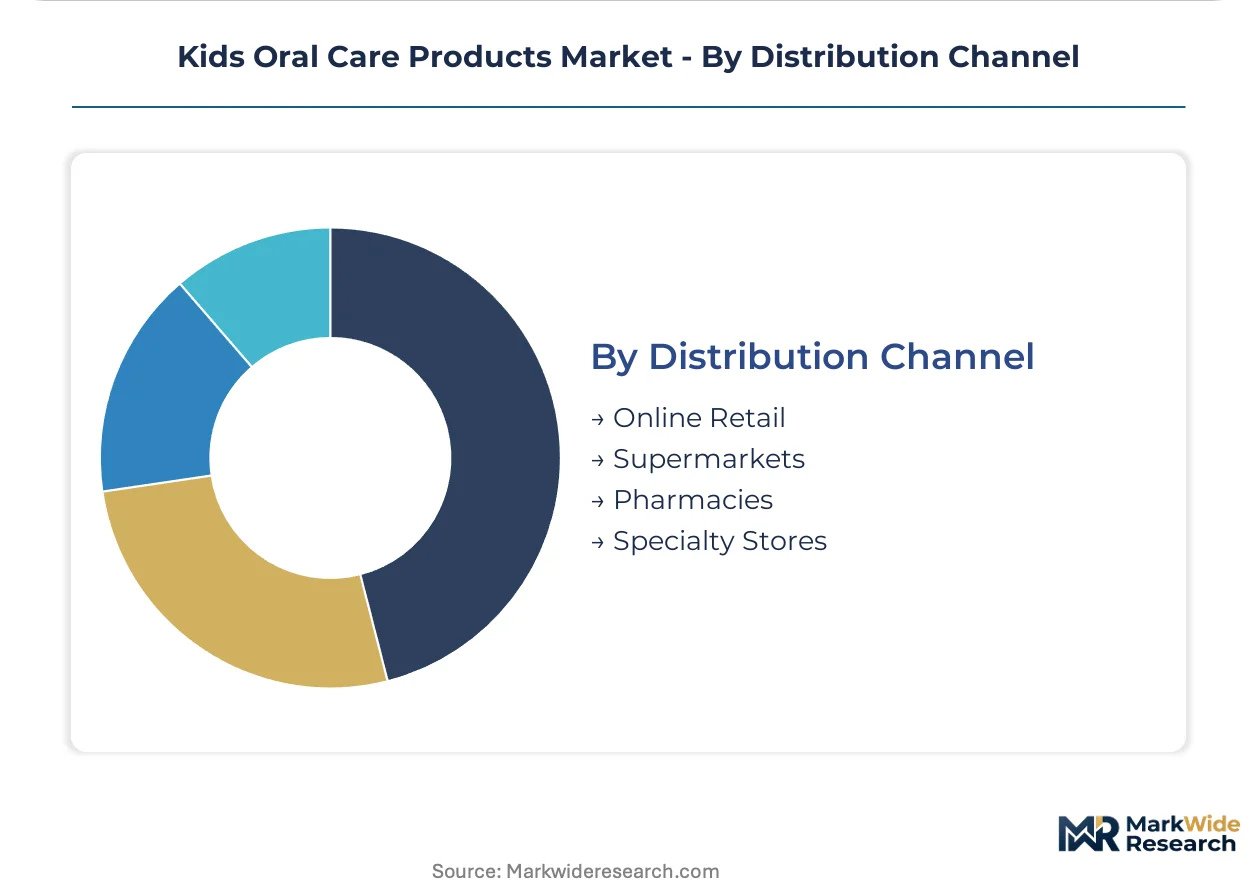
Supermarkets retain volume concentration; online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mass-market oral care originated in the United States during the early twentieth century, with fluoride dentifrice scaling through pharmacy networks before expanding into modern retail formats. Today's geographic distribution reflects this heritage while incorporating distinct regulatory and consumption patterns across major economies.
United States
Club channel volume packs and subscription auto-replenishment models drive per-unit affordability in metropolitan coastal markets. The FDA's OTC monograph system governs children's fluoride concentrations and labeling claims. Cincinnati and New York anchor major brand headquarters, with big-box retail concentration in the Midwest accelerating private-label shelf-space competition.
Germany
Clean-label demand clusters in urban centers favor enzymatic anti-cavity systems over traditional fluoride formulations. REACH chemical safety standards tighten preservative allowances in children's rinse products, forcing distinct EU-bound ingredient decks. The Rhine-Ruhr metropolitan region concentrates pharmacy retail networks where professional recommendation channels sustain premium positioning.
China
Rising middle-class household penetration expands age-graded product adoption beyond tier-one cities. The National Medical Products Administration aligns pediatric dentifrice standards with international concentration benchmarks. The Yangtze River Delta manufacturing corridor supplies both domestic consumption and export production for Asia-Pacific distribution.
Japan
Preventive care protocols embedded in school health programs generate consistent replenishment demand for age-appropriate formulations. The Ministry of Economy, Trade and Industry oversees quality certification systems that influence parent purchasing confidence. The Kanto region around Tokyo concentrates specialty retail and direct-to-consumer subscription services.
Brazil
Community health program expansions in underserved regions create new distribution entry points for basic oral care kits. ANVISA regulates fluoride content and antimicrobial claims in children's products. São Paulo anchors both manufacturing capacity and modern trade retail development, with pharmacy chains extending reach into secondary cities.
Kids Oral Care Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation credibility and licensed entertainment access. The market structures around three tiers: multinational consumer goods conglomerates with pharmacy channel dominance, mid-scale specialists in natural or regional positioning, and private-label manufacturers serving mass retail price compression. Consolidation pressure operates through two dominant vectors: entertainment licensing partnerships that command shelf placement fees, and vertical integration into flavor engineering and packaging design capabilities.
Within the multinational tier, Colgate-Palmolive Company and Procter & Gamble Company exemplify divergent strategic anchors—one leveraging licensed character partnerships for retail visibility, the other sustaining professional credibility through dentist endorsement programs. Church & Dwight Co., Inc. occupies a distinct position on the value-vector, with club channel scale economics representing an alternative to premium-margin competition. These three entities collectively illustrate how shelf-space economics, professional channel access, and per-unit affordability define the competitive topography.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Johnson & Johnson Services, Inc. |
| Church & Dwight Co., Inc. |
| Unilever Plc |
| GlaxoSmithKline PLC |
| Pigeon Corporation |
| Lion Corporation |
| Sunstar Suisse S.A. |
| Others |
Value Network & Pricing Analysis
ADA Seal certification separates premium fluoride formulations from commodity private-label alternatives, with this credential ladder manifesting in both pharmacy channel pricing power and concentrated flavor-engineering supplier relationships in the United States and Germany. Supply chain configurations track this bifurcation: certified manufacturers draw from captive flavor houses and specialized abrasive suppliers, while economy-tier competitors source commoditized inputs through open procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the market, with ADA Seal acceptance and licensed character partnerships driving price differentiation at the top. Cost compression in economy tiers intensifies because club channel volume packs and private-label shelf-space competition erode per-unit margins. Mass retail buyers exhibit highest price sensitivity, whereas dental clinic procurement committees prioritize formulation credibility over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with specialty flavor manufacturers concentrated in the United States and Switzerland. Active ingredient supply draws from fluoride chemical producers in China and Germany, while packaging materials rest on Southeast Asian molded plastics capacity. Tariff exposure on Chinese-sourced fluoride compounds threatens reformulation timelines. Distribution runs through big-box retail consolidation in Midwestern United States markets and pharmacy networks in the Rhine-Ruhr region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the United States, where FDA monograph compliance costs elevate entry barriers, and emerging Asian markets where regulatory alignment with international standards creates faster approval pathways for equivalent formulations.
For Market Incumbents: Deploy entertainment licensing leverage to secure premium shelf placement against private-label encroachment in mass retail channels. Deepen backward integration into flavor engineering capabilities to reduce dependency on Swiss and United States specialty suppliers. Counter enzymatic anti-cavity substitutes by accelerating ADA Seal pipeline investments for next-generation fluoride formulations. For New Entrants and Emerging Players: The premium-to-economy price-point gap in subscription replenishment services offers accessible entry for direct-to-parent digital-native brands. Coastal United States metropolitan markets show lowest penetration resistance for clean-label herbal alternatives. Pursue pediatric dental clinic professional channel partnerships to bypass retail margin stacking and establish credibility loops. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale natural positioning specialists lack scale to survive REACH compliance costs in European distribution. Five-to-ten-year viability favors acquirers of enzymatic formulation platforms with existing German market presence. Monitor state-level fluoride varnish program budget appropriations as inflection signal for home-care product recommendation volume.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Captures convenience premiums in United States coastal metropolitan markets while bypassing retail slotting fees. |
| Enzymatic Formulation Platform Acquisition | Secures clean-label positioning for parent segments seeking fluoride alternatives in Germany and United States. |
| Pediatric Dental Clinic Partnership Network | Establishes professional recommendation pathways that cascade into retail purchasing decisions. |
| REACH-Compliant Manufacturing Footprint | Enables continued European market access as chemical safety standards tighten preservative allowances. |
| Licensed Entertainment Partnership Expansion | Commands premium placement fees in big-box retail through character-themed bundling configurations. |
Research Methodology
Direct dialogue with brand managers, category buyers at mass retailers, pediatric dental clinic procurement officers, and supply planners anchored qualitative findings, cross-referenced with FDA OTC monograph filings, EPA antimicrobial discharge records, Nielsen retail audit data, and customs import manifests. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Bottom-up unit economics segmented by product type, formulation chemistry, packaging format, and distribution channel informed volume projections, while top-down macro indicators calibrated value outputs throughout the forecast period. CAGRs derived from regression analysis of historical replenishment velocity and age-cohort penetration rates, with state-level public health program budgets and entertainment licensing deal flow serving as forward inputs.
The model assumes a particular technology adoption path; alternative pathways for enzymatic anti-cavity systems would alter the outlook if clinical efficacy data shifts pediatric dentist recommendation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Europe Oral Hygiene Market
Oral Care
GCC Oral Hygiene Market
Oral Care
Oral Thrush Market
Oral Care
Oral Rinse Market
Oral Care
Halitosis Treatment Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Mouth Spray Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
BRICS Oral Care Market
Oral Care
Ayurvedic Toothpaste Market
Oral Care
Europe Oral Care Market
Oral Care
Oral Mucositis Market
Oral Care
Children's Oral Care Market
Oral Care
Kids Toothpaste Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Oral Thin Films Market