
 Global Toothbrush and Toothpaste Market | 2026-2036
Global Toothbrush and Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Global Toothbrush and Toothpaste Market Outlook
Aftermarket service revenue from brush-head replacements and subscription refills is narrowing as manufacturers bundle consumables with hardware ecosystems. Colgate-Palmolive Company anchors its position through pharmacy and supermarket shelf-space dominance across Latin America and Southeast Asia. Procter & Gamble leverages direct-to-consumer subscription models to sustain recurring revenue streams for its electric brush platforms. Koninklijke Philips N.V. specializes in sonic technology leadership, differentiating its portfolio through premium positioning in professional dental channels.
Toothbrush and toothpaste products comprise oral hygiene implements and dentifrices engineered to remove dental plaque, prevent caries, and maintain gingival health through mechanical abrasion and chemical active delivery, with formulations typically containing abrasives, humectants, surfactants, and therapeutic agents such as fluoride at concentrations between 1000 and 1500 ppm. Electric toothbrush systems incorporate oscillating-rotating or sonic mechanisms operating at 31,000 to 62,000 brush movements per minute, serving both consumer home use and professional preventive care protocols. Manual toothbrush and fluoride toothpaste categories occupy the largest volume share due to universal accessibility and established clinical endorsement, while electric toothbrush and whitening toothpaste segments capture disproportionate margin pools through technology premiums and aesthetic positioning in developed markets. Natural ingredient formulations represent the fastest-growing ingredient type as clean-label preferences reshape pharmacy and online retail purchasing decisions.
The FDA regulates toothpaste as a drug-cosmetic hybrid in the United States, mandating fluoride labeling and manufacturing compliance under current Good Manufacturing Practices, while the EU Cosmetics Regulation requires safety assessments and nanomaterial disclosure for whitening agents sold across member states. India's CDSCO and BIS frameworks govern active ingredient limits and product quality standards for both domestic consumption and export certification. Stakeholders must monitor evolving extended producer responsibility mandates for plastic toothbrush components as regulatory timelines compress across multiple jurisdictions.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing toothbrush manufacturers to reengineer plastic-intensive supply chains around biodegradable alternatives, compressing formulation timelines and reshaping competitive positioning across retail channels.
Growth Catalysts
- Aging Demographics in Japan and Germany:Senior populations in these markets are expanding the preventive care consumer base, with pharmacy chains reporting concentrated demand for therapeutic toothpaste formulations targeting gingival health.
- REACH Nanomaterial Disclosure Requirements:The EU Cosmetics Regulation's whitening agent standards are accelerating clinical validation investments, filtering out non-compliant suppliers and consolidating shelf access for certified manufacturers.
- Sonic Mechanism Adoption:Oscillating-rotating and sonic brush systems operating at 31,000 to 62,000 movements per minute are displacing manual alternatives in professional dental channels, creating technology premiums that sustain margin pools.
Market Restraints
- Petroleum-Derived Plastic Input Volatility:Polypropylene and nylon bristle feedstock costs fluctuate with crude oil benchmarks, compressing margins for mass-market manual toothbrush producers unable to pass through price adjustments.
- Supply Concentration in Southeast Asian Molding Operations:Injection molding capacity for brush handles clusters in Thailand and Vietnam, exposing brands to port congestion and labor availability disruptions.
- Biodegradable Material Performance Limitations:PLA and bamboo fiber alternatives exhibit tensile strength and moisture resistance deficiencies versus conventional polymers, restricting their application in electric brush heads subject to mechanical stress.
Strategic Opportunities
- Tier-2 Urban India Penetration:Rising disposable incomes in cities such as Jaipur and Indore, combined with Apollo Pharmacy and MedPlus expansion, create whitespace for premium oral care distribution beyond metro saturation.
- Direct-to-Consumer Subscription Channels:Recurring refill models for brush heads and therapeutic pastes bypass traditional retail slotting fees, capturing lifetime value through automated replenishment algorithms.
- PLI Scheme Manufacturing Incentives:India's production-linked incentive framework for personal care goods offers capital expenditure offsets for domestic electric toothbrush assembly, reducing import dependency from Chinese component suppliers.
Industry Challenges
- CDSCO Active Ingredient Compliance Timelines:India's regulator requires 18-to-24-month stability testing for fluoride concentration claims, delaying market entry for reformulated whitening and sensitivity variants.
- Legacy ERP Integration with IoT Brush Systems:Electric toothbrush manufacturers embedding usage-tracking sensors face middleware complexity connecting consumer data streams to existing inventory and warranty management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Toothbrush and Toothpaste Market |
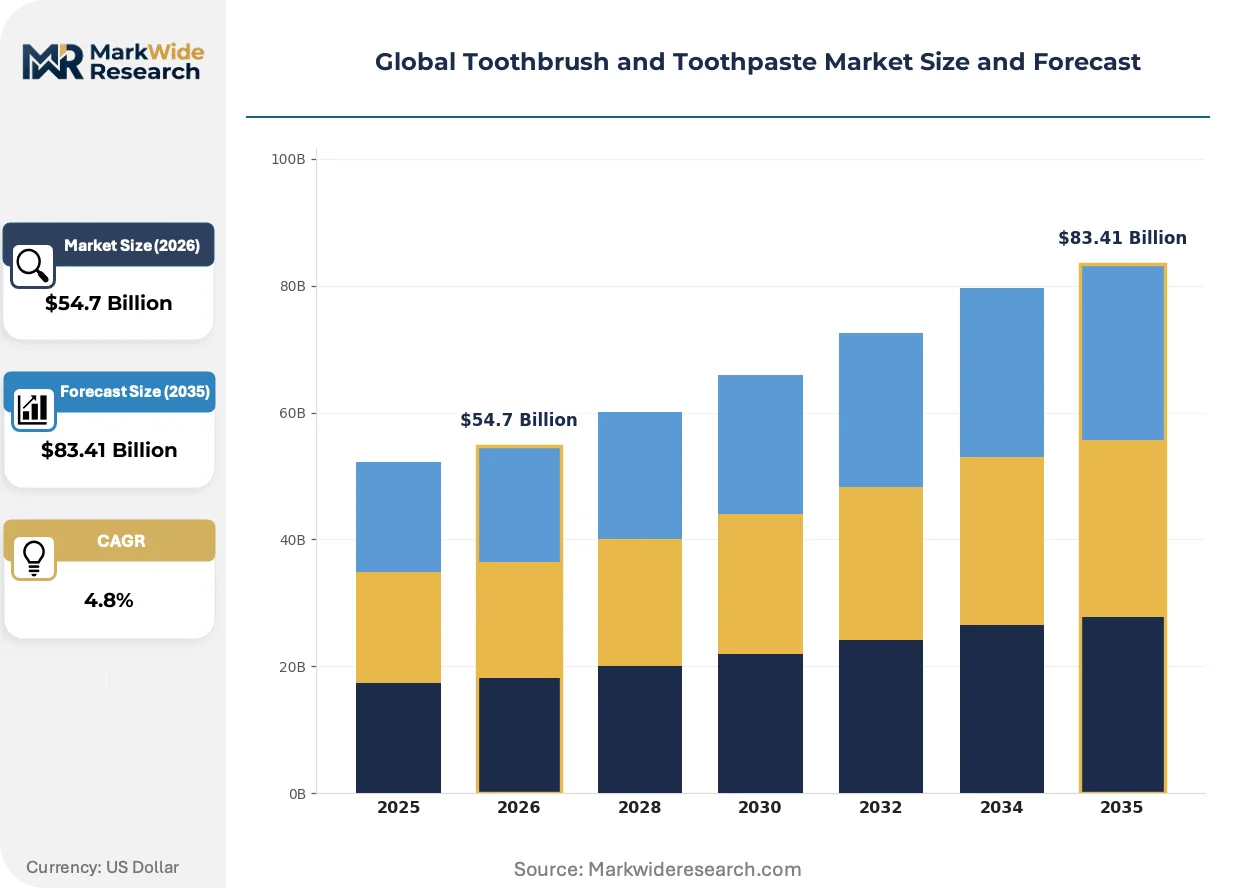
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $83.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Toothbrush, Electric Toothbrush, Whitening Toothpaste, Fluoride Toothpaste End User: Adults, Children, Seniors, Infants Sales Channel: Online Retail, Supermarkets, Drugstores, Pharmacies Ingredient Type: Natural Ingredients, Chemical Ingredients, Organic Products, Sensitive Formula |
| Companies Covered | GlaxoSmithKline PLC, Lion Corporation, Colgate-Palmolive Company, Johnson & Johnson Services Inc., Koninklijke Philips N.V., Procter & Gamble, Church & Dwight Co. Inc., Sunstar Suisse SA, Unilever PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Toothbrush and Toothpaste Market Strategic Shifts
Connected health ecosystems and biomaterial advances are compressing the boundary between consumer oral care and professional preventive dentistry, with data capture and sustainability credentials now determining shelf placement and pricing power.
Smart toothbrush systems incorporating pressure sensors and Bluetooth connectivity are digitizing brushing behavior into actionable oral health metrics. Dental insurance providers in Germany and the Netherlands are subsidizing these devices for policyholders, accelerating household penetration beyond early adopter segments. The resulting data streams enable personalized replacement head scheduling and risk-scored preventive interventions, shifting value capture from hardware margins to subscription analytics.
REACH and the EU Green Deal are mandating recyclability quotas and biodegradable content minimums for plastic-intensive oral care packaging. Manufacturers serving the German and French markets are reformulating around molded fiber and bio-based polymers, accepting 15-to-20% material cost premiums to maintain retail access. The regulatory friction disproportionately affects value-tier private label suppliers lacking R&D scale to engineer compliant alternatives.
Pharmacy-led purchasing is displacing supermarket impulse buying for therapeutic toothpaste categories. Consumers in Japan and South Korea are consulting in-store pharmacists for fluoride concentration and sensitivity agent guidance, consolidating volume behind chains with trained staff and clinical endorsement displays. This channel migration elevates professional recommendation influence over brand equity, compressing marketing efficiency for heritage labels dependent on broadcast advertising.
Global Toothbrush and Toothpaste Market Segmentation
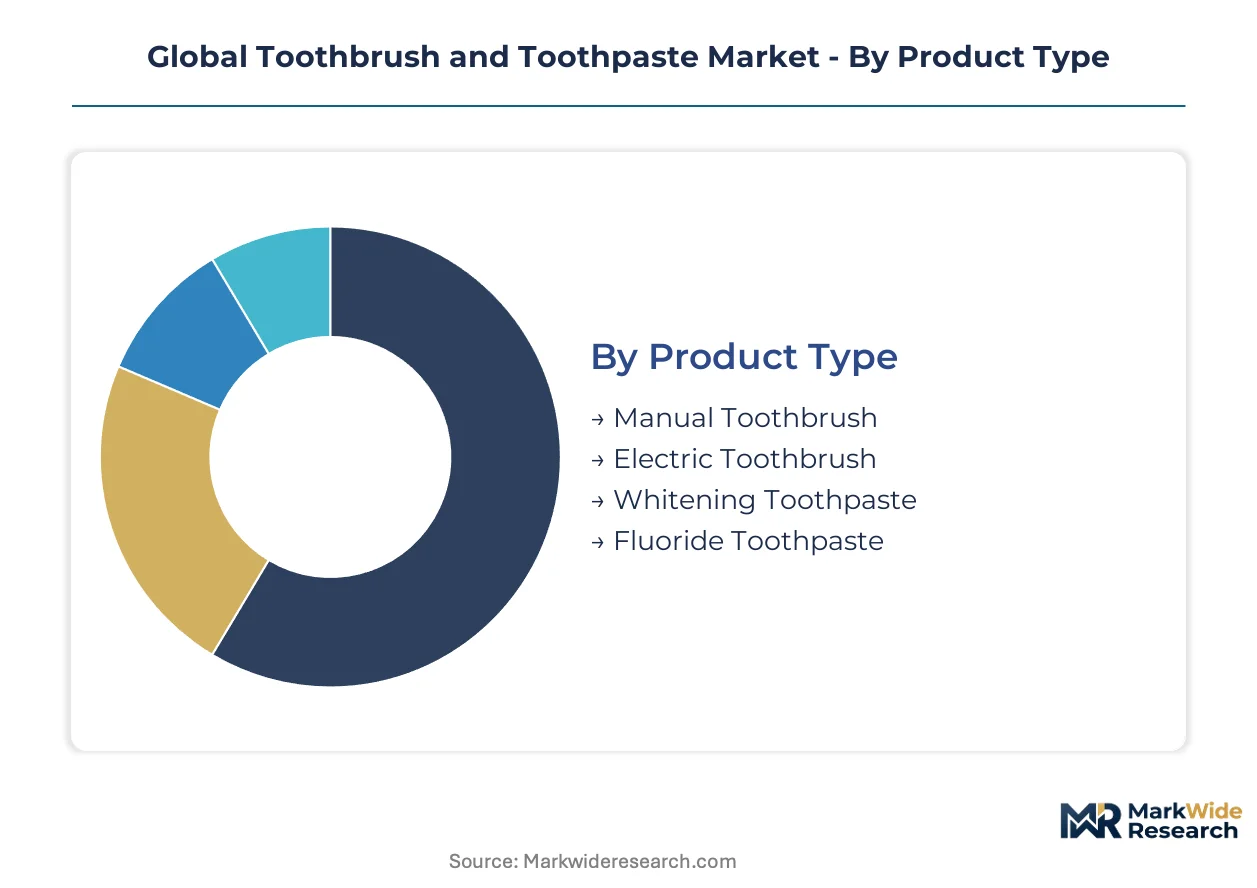
Oral care manufacturers engineer distinct product architectures around brushing mechanism, user physiology, purchase venue, and formulation chemistry. Each segmentation dimension commands separate supply chain configurations, margin structures, and regulatory compliance pathways.
Product Type:
Cost tier stratification separates mass-access manual implements from premium electromechanical systems and specialized therapeutic formulations.
- Manual Toothbrush:Polypropylene handles and nylon bristle arrays dominate unit economics through injection molding scale. Demand concentrates in India's tier-2 cities and Southeast Asian rural markets where pharmacy chains expand distribution reach ahead of electric penetration.
- Electric Toothbrush:Oscillating-rotating and sonic mechanisms operate at 31,000 to 62,000 movements per minute, incorporating lithium-ion power management and pressure sensing. Germany and Japan's aging populations drive replacement head subscription models through dental insurance reimbursement channels.
- Whitening Toothpaste:Peroxide and abrasive formulations target aesthetic positioning in professional dental recommendations.
- Fluoride Toothpaste:Standardized 1000-1500 ppm active concentrations anchor preventive care protocols across pharmacy and supermarket shelves.
Manual Toothbrush holds installed capacity. Electric Toothbrush is rotating up the share rankings.
End User:
Application-specific ergonomics and formulation safety profiles segment demand across developmental stages and physiological conditions.
- Adults:Full-size brush heads and standard fluoride concentrations serve the volume base. Pharmacy-led purchasing in South Korea and Japan concentrates therapeutic variant selection around in-store pharmacist consultation.
- Seniors:Reduced grip strength and gingival recession drive demand for enlarged handles and potassium nitrate formulations. Germany's statutory health insurance subsidizes prescription-strength therapeutic pastes for policyholders over 65.
- Children:Smaller brush heads and flavored formulations accommodate developing dentition and compliance behavior.
- Infants:Silicone finger brushes and fluoride-free training pastes address pre-tooth gum care and early habit formation.
Adults maintains volume dominance. Seniors is expanding most quickly as demographic aging accelerates across developed markets.
Sales Channel:
Customer type and purchase occasion shape channel economics from automated replenishment to impulse-driven supermarket placement.
- Online Retail:Direct-to-consumer subscription algorithms capture lifetime value through automated brush head and therapeutic paste replenishment. India's MedPlus and Apollo Pharmacy digital platforms are consolidating tier-2 city penetration ahead of physical store expansion.
- Pharmacies:Trained staff and clinical endorsement displays drive therapeutic category consolidation. Japanese consumers consult in-store pharmacists for fluoride concentration and sensitivity agent guidance, elevating professional recommendation over brand equity.
- Supermarkets:Impulse placement and promotional pricing dominate mass-market manual brush and standard paste volume.
- Drugstores:Convenience positioning captures emergency replacement purchases and travel-size formats.
Pharmacies holds installed capacity. Online Retail is rotating up the share rankings.
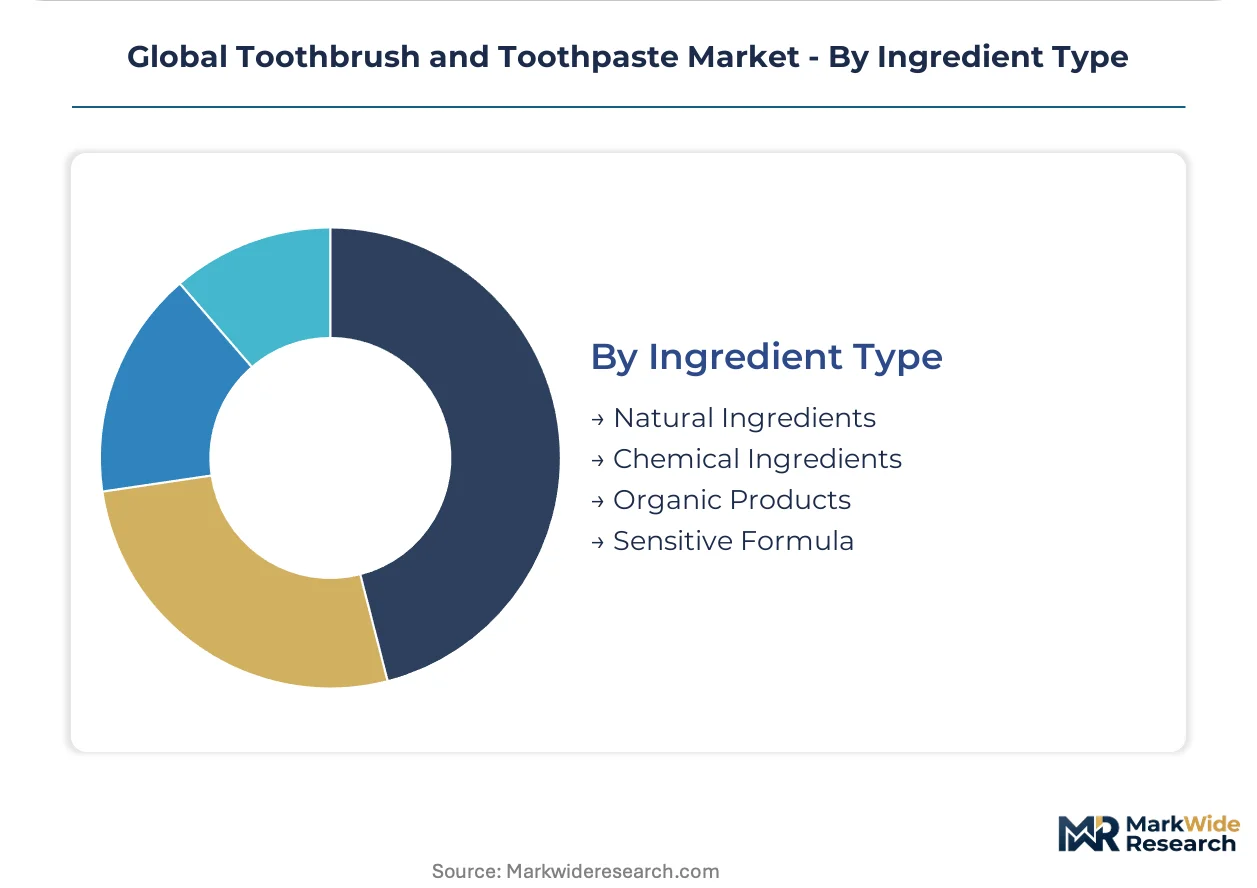
Ingredient Type:
Formulation chemistry and sourcing certification determine margin capture and regulatory compliance intensity across clean-label and clinical positioning.
- Natural Ingredients:Plant-derived abrasives, essential oil antimicrobials, and bio-based surfactants respond to EU Green Deal packaging mandates and REACH nanomaterial disclosure requirements. German and French retailers demand 15-to-20% material cost premiums for molded fiber and bio-based polymer compliance.
- Sensitive Formula:Potassium nitrate and strontium chloride formulations target dentin hypersensitivity through nerve desensitization mechanisms. Pharmacy channel concentration in Japan validates clinical efficacy claims through professional endorsement.
- Chemical Ingredients:Synthetic surfactants and petroleum-derived polymers maintain cost competitiveness in mass-market positioning.
- Organic Products:Third-party certification and supply chain traceability command shelf placement premiums in specialty retail.
Chemical Ingredients holds installed capacity. Natural Ingredients is climbing the fastest as clean-label preferences reshape purchasing decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's aging consumers subsidize electric systems through statutory insurance, while India's tier-2 pharmacy expansion drives manual brush volume—revealing a stark consumption-mix differential between preventive reimbursement markets and accessibility-driven growth corridors.
United States
Direct-to-consumer subscription algorithms capture recurring revenue for brush-head replenishment, bypassing retail slotting fees entirely. The FDA regulates toothpaste as a drug-cosmetic hybrid, mandating fluoride labeling under current Good Manufacturing Practices. Manufacturing clusters in the Northeast and Midwest concentrate on therapeutic formulation packaging for pharmacy distribution.
Germany
Statutory health insurance subsidizes prescription-strength therapeutic pastes for policyholders over 65, expanding the senior preventive care base. The EU Green Deal's extended producer responsibility mandates force reformulation of plastic-intensive toothbrush designs toward biodegradable alternatives. The Rhine-Ruhr industrial corridor hosts molding operations adapting to bio-based polymer compliance requirements.
Japan
Pharmacy-led purchasing concentrates demand for therapeutic formulations targeting gingival health among expanding senior populations. METI guidelines shape domestic quality standards for electric brush systems with pressure-sensing capabilities. The Kanto region around Tokyo anchors professional dental channel distribution for sonic technology platforms.
India
Rising disposable incomes in Jaipur and Indore combine with Apollo Pharmacy and MedPlus expansion to create whitespace for premium oral care beyond metro saturation. The CDSCO requires 18-to-24-month stability testing for fluoride concentration claims, delaying whitening variant entry. The PLI scheme offers capital expenditure offsets for domestic electric toothbrush assembly in Gujarat and Maharashtra manufacturing zones.
South Korea
Consumers consult in-store pharmacists for fluoride concentration and sensitivity agent guidance, elevating professional recommendation over brand equity. The MFDS governs active ingredient limits and nanomaterial disclosure for whitening agents. Seoul's pharmacy chains consolidate volume through clinical endorsement displays and trained staff deployment.
Global Toothbrush and Toothpaste Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where technology specialists capture premium margins while mass-market players defend volume through shelf-space dominance. The vendor base organizes around three strategic archetypes: multinational conglomerates with pharmacy network control, electric system specialists with sonic technology leadership, and diversified consumer goods groups with direct-to-consumer subscription infrastructure. Competitive moves center on M&A for regional distribution access and vertical integration into biodegradable material supply chains.
Among multinational conglomerates, Colgate-Palmolive Company and Procter & Gamble exemplify the scale-driven archetype through pharmacy and supermarket shelf-space dominance across Latin America and Southeast Asia. Koninklijke Philips N.V. occupies a position within the technology specialist tier, representing premium positioning in professional dental channels. GlaxoSmithKline PLC and Johnson & Johnson Services Inc. sit within the therapeutic formulation segment, anchoring clinical endorsement strategies for sensitivity and gingival health variants.
| Leading Market Players |
|---|
| GlaxoSmithKline PLC |
| Lion Corporation |
| Colgate-Palmolive Company |
| Johnson & Johnson Services Inc. |
| Koninklijke Philips N.V. |
| Procter & Gamble |
| Church & Dwight Co. Inc. |
| Sunstar Suisse SA |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Injection molding capacity clustering in Thailand and Vietnam concentrates polypropylene handle production for mass-market manual toothbrushes, anchoring margin capture downstream with brands commanding pharmacy shelf-space in Latin America and Southeast Asia. This upstream concentration amplifies pricing power for integrated manufacturers while exposing value-tier private labels to feedstock volatility and port congestion surcharges.
Pricing Analysis
Long-term offtake agreements between multinational brands and Southeast Asian molding contractors stabilize unit economics for manual toothbrush production, while spot-market procurement dominates specialty bio-based polymer sourcing for EU-compliant variants. Pricing stratifies across premium, standard, and economy tiers based on sonic mechanism inclusion and REACH nanomaterial certification status. Cost compression in the mass-market tier intensifies as petroleum-derived polypropylene and nylon bristle feedstock fluctuate with crude benchmarks. Pharmacy-channel buyers in Germany and Japan exhibit lowest price sensitivity due to insurance reimbursement, while India's tier-2 urban consumers drive hard volume negotiations.
Supply Chain Analysis
Tariff exposure between China and the United States disrupts lithium-ion battery and electronic component flows for electric toothbrush assembly, forcing manufacturers toward India's PLI-subsidized Gujarat and Maharashtra zones. Thailand, Vietnam, and China concentrate injection molding capacity for brush handles and replacement heads. Supply chains draw from petroleum-based polymers, bamboo fiber alternatives, and bio-based PLA resins. Single-source vulnerability concentrates in Southeast Asian port logistics, particularly for brands lacking diversified molding partnerships. Distribution runs through pharmacy chains in developed markets and supermarket impulse placement in mass-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of biodegradable material engineering talent and REACH-compliant formulation expertise concentrates competitive advantage with incumbents who invested early in R&D scale, leaving mid-tier brands exposed to regulatory disqualification.
For Market Incumbents: Insulate margin pools by securing captive supply of bio-based polymers through backward integration into Thai and Vietnamese molding operations, and accelerate CDSCO pre-submission stability testing for fluoride variants to preempt 18-to-24-month entry delays for Indian whitening launches. Threat of private label displacement in EU markets demands certification investment ahead of Green Deal enforcement timelines. For New Entrants and Emerging Players: Tier-2 Indian cities with Apollo Pharmacy and MedPlus expansion represent the most penetrable entry point for premium oral care distribution beyond saturated metro markets. Direct-to-consumer subscription algorithms for brush-head replenishment offer a go-to-market angle bypassing retail slotting fees entirely. Natural ingredient formulations targeting clean-label pharmacy channels in Germany and France provide secondary whitespace with 15-to-20% material cost acceptance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional pharmacy distributors lacking electric toothbrush technology portfolios or IoT connectivity capabilities. Long-term viability over a 5-to-10-year horizon favors targets with established CDSCO filing pathways and biodegradable material supplier relationships. The signal to watch is dental insurance reimbursement expansion for connected brush systems in statutory health markets.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Material Transition | REACH and EU Green Deal compliance secures German and French retail access against regulatory exclusion. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms capture lifetime value while bypassing pharmacy slotting fees. |
| CDSCO Filing Acceleration | Early stability testing initiation compresses 18-to-24-month fluoride variant approval timelines for Indian market entry. |
| Pharmacy Chain Partnership Expansion | Trained staff endorsement displaces brand equity in Japan and South Korea therapeutic categories. |
| Sonic Technology Platform Integration | Pressure-sensing and Bluetooth connectivity enable dental insurance reimbursement in German statutory health markets. |
Study Parameters
Desk research of regulatory filings from FDA, ECHA, CDSCO, and METI preceded structured interviews with brand managers, pharmacy category buyers, supply chain planners, and biomedical engineers at dental device manufacturers. Secondary validation drew from customs trade data, SEC 10-K disclosures, Nielsen retail audit records, and hospital procurement databases. Bottom-up volume modeling across product type, end user, sales channel, and ingredient type segmentation triangulated against top-down macroeconomic indicators.
Assumptions around EU Green Deal enforcement timelines, CDSCO approval velocities, and dental insurance reimbursement expansion were held fixed across baseline scenarios while oil price volatility and port congestion severity were stress-tested. The analytical framework modeled oscillating-rotating versus sonic mechanism adoption, natural ingredient formulation share trajectories, and tier-2 India pharmacy penetration rates. CAGRs were derived from logistic diffusion curves fitted to historical electric toothbrush replacement cycles and whitening toothpaste clinical endorsement velocity.
Macroeconomic conditions sit as an overlay; deviation in crude oil benchmarks, rupee-dollar exchange rates, or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions around aging demographic expansion and clean-label preference persistence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Chemotherapy-Induced Oral Mucositis Market
Oral Care
Kids Toothpaste Market
Oral Care
Manual Toothbrush Market
Oral Care
Global Oral Care/Oral Hygiene Market
Oral Care
Tongue Cleaner Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Oral Rinse Market
Oral Care
Mouth Spray Market
Oral Care
Global Oral Care Products Market
Oral Care
BRICS Oral Care Market
Oral Care
Global Interdental Cleaning Products Market
Oral Care
Europe Oral Care Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Halitosis Treatment Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Kids Oral Care Products Market