
 Tinted Sunscreen Market | 2026-2036
Tinted Sunscreen Market Size, Share, and Industry Trends Forecast 2026-2036
Tinted Sunscreen Market Analysis
Korean cosmetic manufacturers is shifting significant production capacity toward hybrid mineral-chemical tinted sunscreen formats. La Roche-Posay leverages its dermatological heritage to sustain premium positioning across European and North American pharmacy channels. Tower 28 anchors its competitive stance through fragrance-free, sensitive-skin specialization that dominates the clean beauty segment. EltaMD differentiates via physician-dispensed distribution, controlling access through dermatology and plastic surgery practices.
Tinted sunscreen constitutes a topical photoprotective formulation incorporating FDA-recognized active ingredients—zinc oxide, titanium dioxide, or organic UV filters—combined with cosmetic pigments to deliver both solar protection and complexion-evening coverage, manufactured through emulsion stabilization processes requiring particle-size control below 200 nanometers to prevent visible whitening. The mineral formulation segment leads absolute volume due to reef-safe positioning and broad-spectrum efficacy claims, while hybrid mineral-chemical formulations represent the fastest-growing category as brands balance aesthetic elegance with regulatory compliance. Gel textures command premium shelf positioning in Asian markets where lightweight, fast-absorbing aesthetics dominate consumer preference.
FDA sunscreen monograph enforcement determines which active ingredients gain market access in the United States, while the EU's Cosmetics Regulation (EC) No 1223/2009 mandates rigorous safety assessments through the Scientific Committee on Consumer Safety. REACH compliance governs pigment and preservative chemistry across European manufacturing, directly constraining formulation flexibility. Stakeholders must monitor pending FDA decisions on additional sunscreen actives and evolving state-level bans on octinoxate and oxybenzone to anticipate portfolio restructuring requirements.
Market Dynamics
Formulation chemistry is bifurcating as mineral-only and hybrid mineral-chemical architectures compete for shelf space, with particle engineering below 200 nanometers determining whether products achieve aesthetic transparency or suffer from visible whitening that consumers reject.
Growth Catalysts
- Reef-safe mandates:Hawaii and Key West bans on octinoxate and oxybenzone are accelerating mineral formulation adoption across coastal states, forcing incumbent brands to reformulate portfolios.
- Dermatology channel expansion:Physician-dispensed distribution through plastic surgery and dermatology practices is creating premium access points that bypass traditional retail margin compression.
- Hybrid texture innovation:Gel-emulsion stabilization technology is resolving the historical trade-off between mineral UV protection and cosmetic elegance, unlocking Asian market penetration.
Market Restraints
- Pigment supply concentration:Iron oxide and ultramarine pigment production clusters in China, creating single-source dependency for cosmetic-grade mineral colorants.
- FDA monograph uncertainty:Pending decisions on additional sunscreen active ingredients under modernized review processes are freezing R&D investment timelines for novel organic UV filters.
- Cost structure asymmetry:Zinc oxide and titanium dioxide raw material volatility exceeds petrochemical-derived organic filters, compressing gross margins on mineral-dominant SKUs.
Strategic Opportunities
- Men's grooming penetration:Underdeveloped male consumer segments in Germany and the United Kingdom present whitespace for tinted SPF positioned as skincare rather than makeup.
- Post-procedure protocols:Laser and chemical peel aftercare regimens are institutionalizing tinted mineral sunscreen as mandatory recovery step in medi-spa settings.
- REACH pigment pre-registration:Early compliance with ECHA substance dossier requirements is creating first-mover advantage for EU-manufactured color cosmetic hybrids.
Industry Challenges
- Emulsion stability expertise:Formulation chemists capable of maintaining nanoparticle dispersion below 200 nanometers without aggregation or phase separation command scarcity premiums that inflate headcount costs.
- Dual-label compliance:Simultaneous satisfaction of FDA drug monograph and EU Cosmetics Regulation safety assessment timelines stretches regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tinted Sunscreen Market |
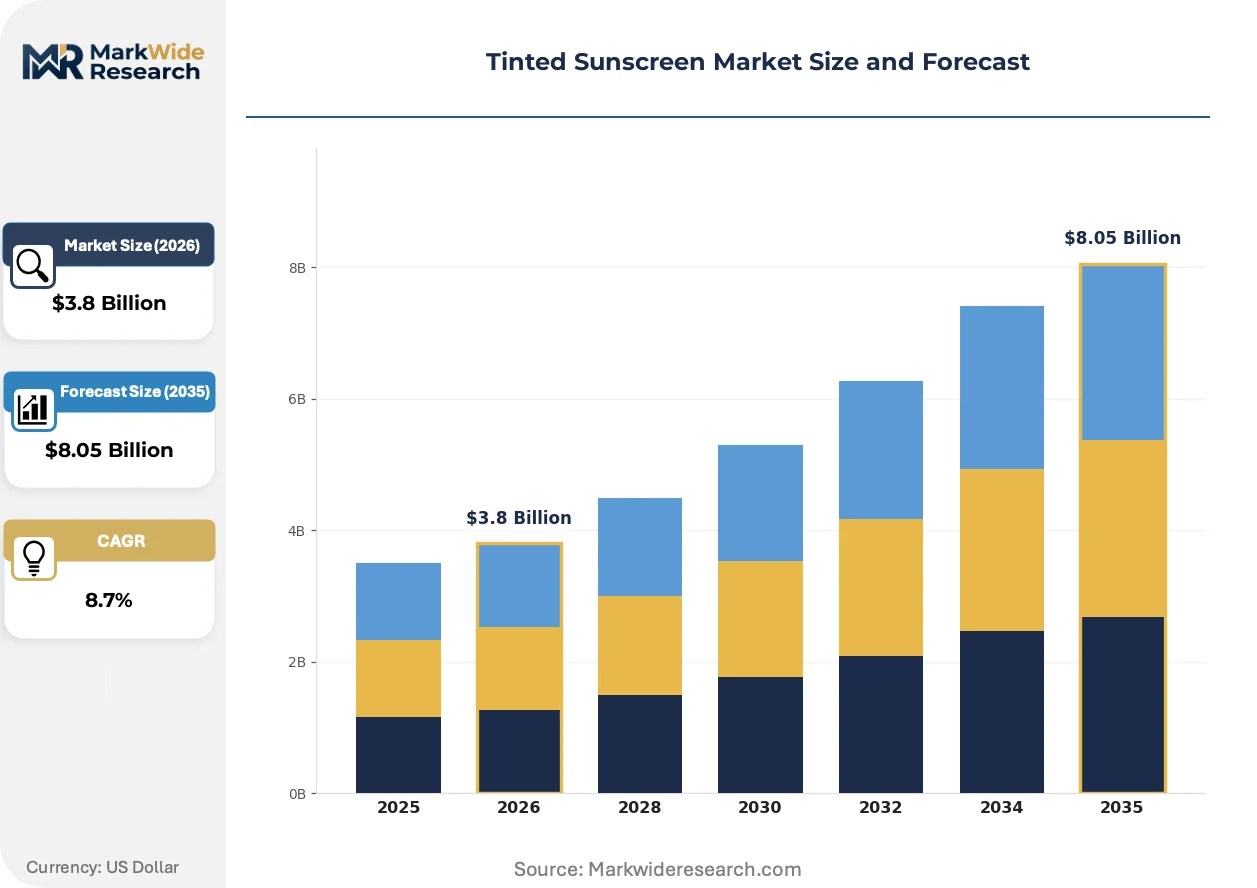
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gel, Lotion, Cream, Stick Formulation: Mineral, Chemical, Hybrid, Organic Skin Type: Dry, Oily, Combination, Sensitive SPF Rating: 30, 50, 70, 100 |
| Companies Covered | MERIT, Dr Sam's, La Roche-Posay, Tower 28, Live Tinted, EltaMD, Colorescience, Bioderma, ILIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tinted Sunscreen Market Emerging Trajectories
Photoprotection is converging with complexion correction as consumers reject multi-step routines, compressing sunscreen and foundation into single-application hybrids that demand unprecedented formulation sophistication.
Encapsulated organic UV filters is overtaking conventional free-film approaches in hybrid formulations. Korean manufacturers are deploying lipid-shell microencapsulation to reconcile chemical UV absorption with mineral aesthetic benefits. This architecture is overtaking legacy formulation methods by enabling higher organic active loads without irritation profiles that previously restricted sensitive-skin positioning.
REACH authorization requirements for titanium dioxide nanoparticles are restructuring European supply chains. ECHA's 2022 carcinogenicity classification triggered mandatory exposure assessment protocols that smaller formulators cannot resource. Professional and pharmacy channels are absorbing compliance costs through premium positioning that distances mass-market competitors.
Subscription replenishment models are displacing intermittent retail purchasing among core users. Direct-to-consumer tint-matching algorithms reduce shade-return friction that previously constrained online penetration. Dermatology practices in California and New York are piloting auto-ship programs integrated with treatment scheduling software.
Tinted Sunscreen Market Segmentation
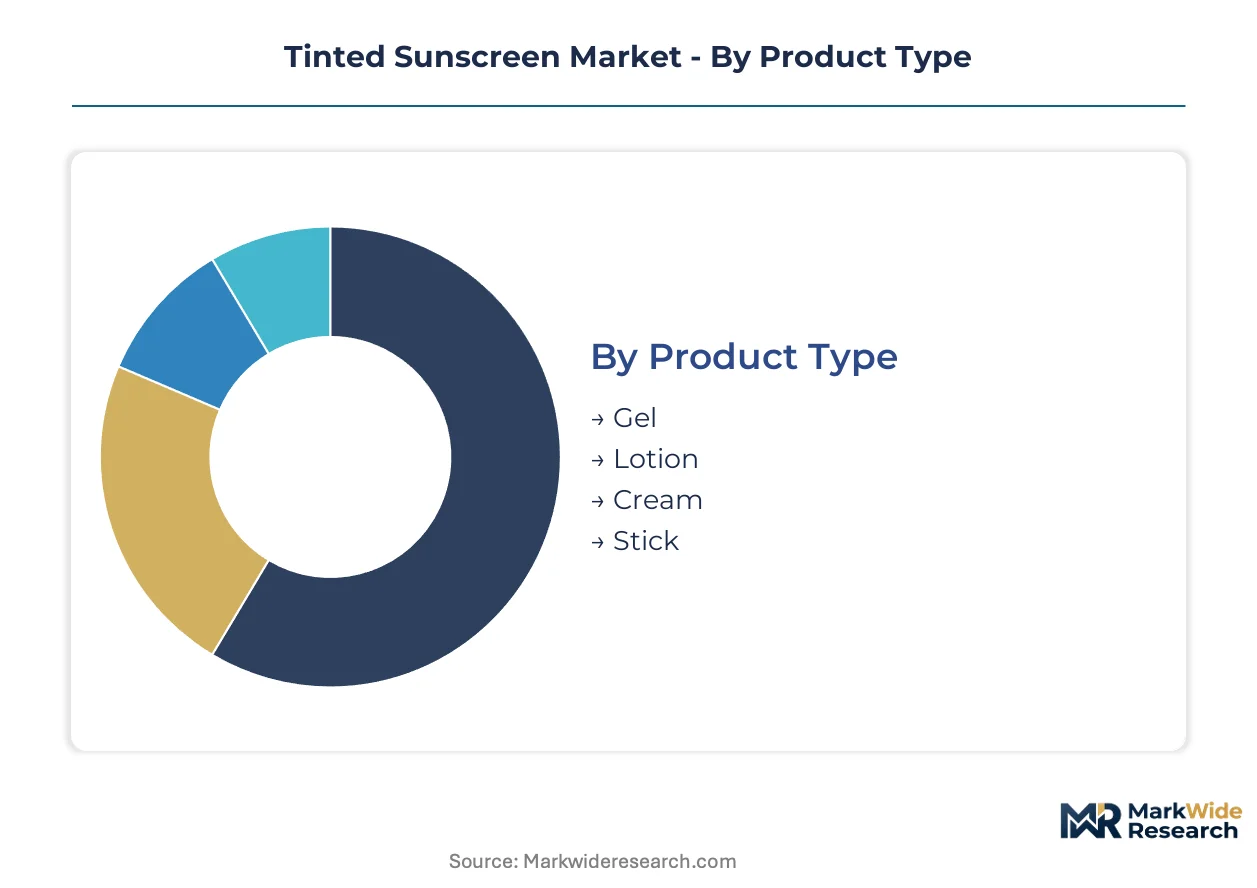
Segmentation in tinted sunscreen reveals how formulation chemistry, texture preferences, and photoprotection intensity fragment demand across distinct user profiles. Each dimension carries specific regulatory, supply chain, and margin implications that shape competitive positioning.
Product Type:
Volume concentrates in mass-market lotions and creams, while gel formats command premium shelf positioning through lightweight aesthetics.
- Gel:Water-based emulsion systems with fast-absorbing, non-greasy finish. Demand clusters in South Korea and Japan where humid climates and multi-step skincare routines favor weightless textures that layer under makeup without pilling.
- Lotion:Fluid oil-in-water or water-in-oil systems offering spreadable coverage for body and face applications. Mass-market penetration runs deepest in United States drugstore channels where consumers prioritize value-per-ounce for daily reapplication.
- Cream:Thicker emulsion with higher oil phase content delivering barrier support for dry climates.
- Stick:Solid anhydrous format enabling precise application and TSA-friendly portability.
Mature deployment sits with Lotion. Newer deployment is concentrated in Gel.
Formulation:
Cost tiering separates mineral-only architectures from hybrid systems that balance efficacy with cosmetic elegance.
- Mineral:Zinc oxide and titanium dioxide as sole active ingredients, requiring nanoparticle engineering below 200 nanometers to prevent whitening. Hawaii's octinoxate and oxybenzone bans are accelerating reef-safe mineral adoption across coastal United States markets.
- Hybrid:Mineral-chemical combinations leveraging organic UV filters for cosmetic transparency with mineral broad-spectrum anchoring. Korean manufacturers are expanding capacity fastest here as encapsulated organic filter technology resolves historical irritation constraints.
- Chemical:Organic UV absorber-only systems, now contracting in reef-sensitive jurisdictions.
- Organic:Plant-derived antioxidant boosters positioned as companion ingredients rather than standalone UV protection.
Volume leadership rests with Mineral. Steepest expansion trajectory belongs to Hybrid.
Skin Type:
Application focus shifts from universal claims toward condition-specific positioning that commands dermatology channel premiums.
- Sensitive:Fragrance-free, minimal-ingredient architectures with barrier-supportive ceramides or niacinamide. Tower 28 and similar clean beauty specialists dominate here through allergen-exclusion protocols that satisfy post-procedure protocols in California medi-spas.
- Oily:Mattifying, non-comedogenic formulations with sebum-absorbing silica or clay. Demand concentrates among younger demographics in urban United States markets where shine control doubles as cosmetic primer function.
- Dry:Emollient-rich bases with humectant glycerin or hyaluronic acid integration.
- Combination:Zone-adaptive textures balancing T-zone oil control with cheek hydration.
Established positioning sits with Oily. Emerging positioning concentrates in Sensitive.
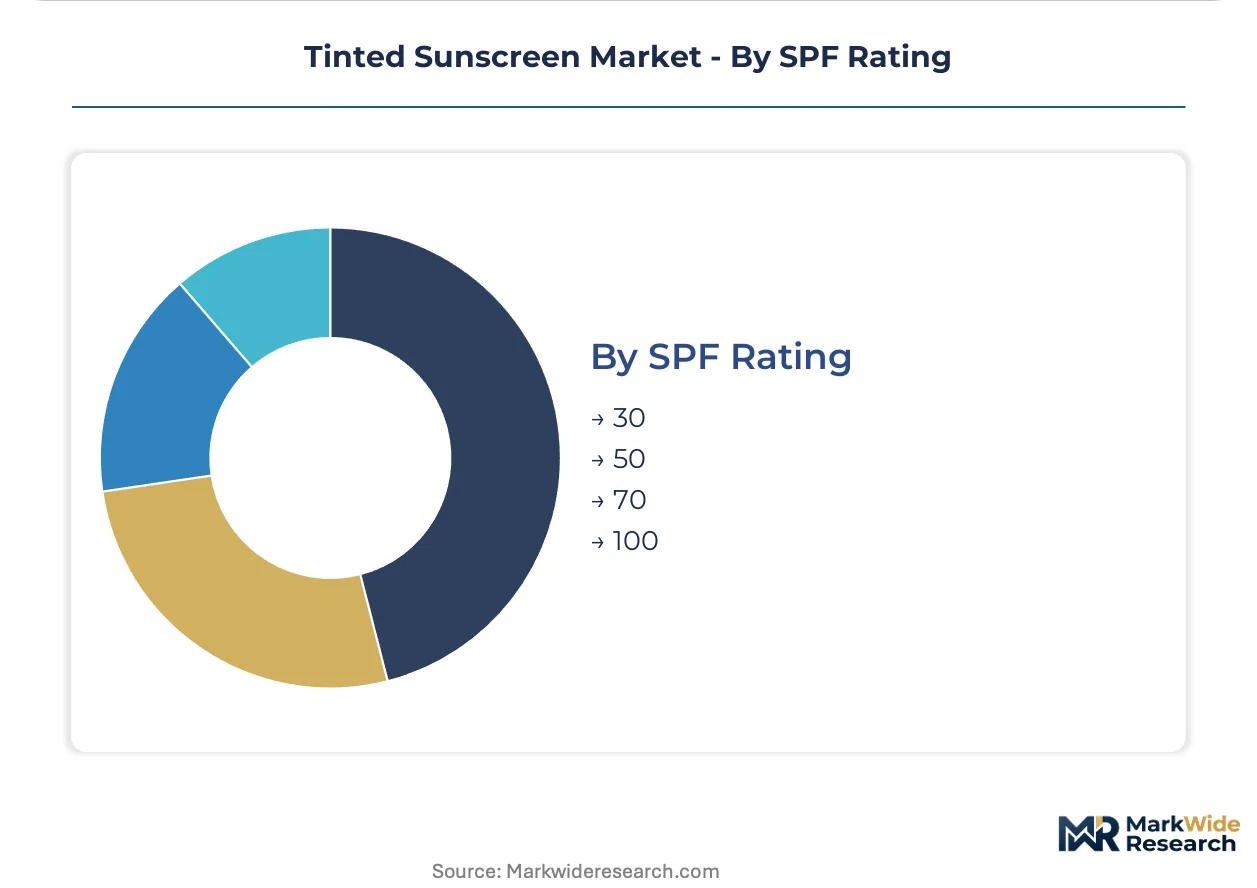
SPF Rating:
Customer type stratification separates daily-wear minimalists from outdoor activity enthusiasts requiring sustained protection.
- SPF 50:The dermatologist-recommended standard balancing photoprotection with formulation wearability. EltaMD and La Roche-Posay anchor pharmacy channel dominance here through clinical validation that supports premium pricing against mass-market SPF 30 alternatives.
- SPF 30:Regulatory minimum for broad-spectrum claims, dominant in cosmetic-tint hybrids where aesthetic elegance trumps maximum protection.
- SPF 70:High-protection tier for extended outdoor exposure and photosensitive conditions.
- SPF 100:Maximum labeled protection, niche positioning for extreme environments and post-procedure sensitivity.
Mainstream adoption sits with SPF 50. Niche expansion is concentrated in SPF 100.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron oxide pigment clusters in China's Jiangsu and Zhejiang provinces anchor global supply chains for tinted sunscreen colorants. Coastal manufacturing hubs in South Korea and Japan process these raw materials into hybrid gel-emulsion formats. Distribution networks radiate from these clusters into pharmacy, medi-spa, and direct-to-consumer channels across four demand-intensive markets.
United States
California and New York dermatology practices drive physician-dispensed premium volume through post-procedure protocol integration. FDA's modernized sunscreen monograph review process is reshaping which active ingredients gain market access, freezing some R&D pipelines. Miami and Honolulu retail channels accelerate mineral-only adoption in response to Hawaii's octinoxate and oxybenzone bans.
South Korea
Seoul-based formulators dominate gel-texture innovation for humid-climate wearability, exporting lightweight emulsion technology globally. MFDS cosmetic safety assessments mandate rigorous nanoparticle exposure documentation for titanium dioxide. Busan-Ulsan manufacturing corridors concentrate encapsulated organic UV filter production capacity expansion.
Germany
Pharmacy-channel loyalty in Bavaria and North Rhine-Westphalia sustains premium pricing for dermatological heritage brands. REACH authorization requirements for titanium dioxide nanoparticles triggered mandatory exposure assessment protocols that smaller formulators cannot resource. Frankfurt and Düsseldorf serve as EU regulatory compliance coordination hubs for multinational portfolios.
France
Île-de-France medi-spa density supports professional-channel penetration for post-laser recovery protocols. ANSM enforces rigorous safety assessments for cosmetic-drug hybrid classifications. Lyon and Marseille manufacturing clusters specialize in iron oxide dispersion technologies for complexion-matching tint ranges.
Japan
Tokyo-Osaka urban corridors demand SPF-plus-makeup hybrids that compress multi-step routines into single applications. METI standards govern nanoparticle labeling transparency for consumer communication. Kansai-region formulators lead particle-engineering capabilities below 200 nanometers for aesthetic transparency.
Tinted Sunscreen Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue clean-beauty and sensitive-skin specializations that command pharmacy and medi-spa premiums. The market structures around three tiers: dermatology-dispensed clinical brands, pharmacy-channel heritage players, and direct-to-consumer digital natives. Two strategic archetypes dominate competitive positioning—mineral-only reef-safe specialists and hybrid texture innovators. Capacity expansion and encapsulated filter technology licensing represent the dominant competitive moves across Korean and European manufacturing bases.
Within the dermatology-dispensed tier, EltaMD exemplifies physician-channel control through plastic surgery and dermatology practice access. La Roche-Posay anchors pharmacy-channel heritage positioning across European and North American markets. Tower 28 occupies the clean-beauty specialization vector through fragrance-free, sensitive-skin formulation protocols that dominate California medi-spa procurement.
| Leading Market Players |
|---|
| MERIT |
| Dr Sam's |
| La Roche-Posay |
| Tower 28 |
| Live Tinted |
| EltaMD |
| Colorescience |
| Bioderma |
| ILIA |
| Others |
Supply Flow & Price Mechanics
Mineral-only reef-safe certification separates dermatology-dispensed premiums from mass-market commodity tiers, with zinc oxide nanoparticle engineering costs and iron oxide pigment sourcing constraints simultaneously shaping both price floors and supply chain geography across United States, South Korean, and German manufacturing corridors.
Pricing Analysis
Service-bundling through physician-dispensed distribution includes post-procedure protocol consultation and auto-replenishment scheduling that mass retail channels unbundle entirely. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity tiering from hybrid gel-emulsion systems to basic lotion formats. Pricing pressure stems from zinc oxide raw material volatility exceeding organic filter costs, compressing margins on mineral-dominant portfolios. Dermatology practices demonstrate least price sensitivity; drugstore mass-market consumers exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Busan-Ulsan, Lyon-Marseille, and New Jersey-Philadelphia radiate finished goods through pharmacy, medi-spa, and direct-to-consumer channels. Manufacturing concentrates in South Korea, China, and France with iron oxide pigment clusters in Jiangsu-Zhejiang provinces feeding global colorant demand. Raw material dependencies center on cosmetic-grade zinc oxide, titanium dioxide nanoparticles, and encapsulated organic UV filters. Single-source vulnerability runs through Chinese pigment concentration. Distribution runs through hub-and-spoke pharmacy networks in Germany and physician-dispensed direct fulfillment in California and New York.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH titanium dioxide authorization costs and FDA monograph uncertainty are forcing portfolio consolidation as smaller formulators exit, leaving acquisition opportunities for scaled players with regulatory affairs capacity.
For Market Incumbents: To counter Korean hybrid-format encroachment, anchor mineral-only positioning through Hawaii and Key West reef-safe mandate compliance while deepening backward integration into iron oxide pigment dispersion capabilities in Lyon and Marseille manufacturing clusters. For New Entrants and Emerging Players: Begin with underpenetrated male grooming segments in Germany and the United Kingdom, positioning tinted SPF as skincare rather than makeup through fragrance-free, minimal-ingredient architectures distributed via pharmacy and barbershop channels. For Investors and Strategic Acquirers: Re-rating potential sits with EU-manufactured color cosmetic hybrids given REACH pre-registration first-mover advantage and titanium dioxide exposure assessment protocols that smaller competitors cannot resource. Long-term viability favors scaled formulators with nanoparticle dispersion expertise below 200 nanometers and dermatology channel control. Signal to monitor: FDA monograph decisions on additional sunscreen actives triggering portfolio restructuring waves.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulated Filter Technology Licensing | Korean lipid-shell microencapsulation resolves irritation constraints while enabling higher organic active loads. |
| Dermatology Channel Expansion | California and New York physician-dispensed distribution creates premium access points bypassing retail margin compression. |
| REACH Pigment Pre-Registration | Early ECHA substance dossier compliance creates defensible positioning against mass-market competitors. |
| Direct-to-Consumer Tint-Matching Algorithms | Shade-return friction reduction unlocks subscription replenishment models displacing intermittent retail purchasing. |
| Post-Procedure Protocol Integration | Laser and chemical peel aftercare regimens institutionalize tinted mineral sunscreen as mandatory recovery step. |
Methodological Framework
Independent corroboration across formulation chemists at Korean and French manufacturing facilities, regulatory affairs directors navigating FDA and ECHA processes, and pharmacy channel procurement managers underwrites the qualitative findings. Primary interviews with dermatology practice administrators, medi-spa operations heads, and iron oxide pigment suppliers combined with secondary validation from FDA sunscreen monograph filings, ECHA substance dossier databases, and MFDS cosmetic safety assessments. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates.
Rate-of-change decomposition across the analysis window segments demand by formulation architecture, texture preference, SPF rating tier, and distribution channel intensity. CAGRs derive from patient visit volume trends in dermatology practices, pharmacy channel inventory turns, and direct-to-consumer subscription cohort retention. Industry-specific inputs include nanoparticle dispersion yield rates, iron oxide pigment cost curves, and reef-safe mandate adoption velocity across coastal United States jurisdictions.
Underlying measurement precision varies by segment; physician-dispensed and pharmacy channel volumes carry tighter precision than emerging direct-to-consumer subscription models. Forecasts reflect documented assumptions regarding FDA monograph timeline resolution, REACH authorization cost pass-through rates, and Korean manufacturing capacity expansion schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Skincare
Europe Functional Cosmetics Market
Skincare
Natural Skin Care Products Market
Skincare
Global Cosmetic Skin Care Market
Skincare
Skin Care Supplements Market
Skincare
Professional Skin Care Market
Skincare
India Skin Care Products Market
Skincare
CBD Skincare Products Market
Skincare
Skin Bioactive Market
Skincare
Ampoule Cream Market
Skincare
Peel Off Face Mask Market
Skincare
Revitalizing Skin Wands Market
Skincare
Skin Grafting System Market
Skincare
Vitamin C Serum Market
Skincare
Skincare Serums Market
Skincare
ASEAN Sensitive Skin Care Market
Skincare
Asia-Pacific Cosmeceutical Market