
 China Oral Care Market | 2026-2036
China Oral Care Market Size, Share, and Industry Trends Forecast 2026-2036
China Oral Care Market Outlook
Buyer concentration among young urban professionals is hardening as dental aesthetics clinics and premium e-commerce platforms consolidate procurement volumes. Procter & Gamble leverages its multinational R&D infrastructure to sustain formulation leadership across whitening and enamel-repair lines. Yunnan Baiyao Group anchors its position through traditional Chinese medicine-infused toothpaste variants that dominate southwestern pharmacy channels. Guangzhou Weimeizi Industrial specializes in private-label manufacturing for domestic supermarket chains, competing on cost-adjusted flexibility.
Oral care encompasses products and appliances designed to maintain dental hygiene, prevent caries and periodontal disease, and cosmetically enhance tooth appearance through abrasive cleaning, antimicrobial action, or chemical bleaching; formulations typically incorporate fluoride compounds, hydrated silica abrasives, and surfactant systems with pH ranges calibrated between 4.5 and 10.5 depending on therapeutic intent. Toothpaste commands the largest revenue pool among product types due to replacement frequency and premiumization of functional variants, while mouthwash records the fastest growth trajectory driven by professional endorsement and expanded pharmacy distribution. Online retail channels are capturing incremental margin pools as live-stream commerce platforms enable direct-to-consumer education and trial-size conversion.
NMPA cosmetic registration requirements and GB standards administered by SAMR mandate pre-market safety assessments and ingredient disclosure for oral care products marketed with therapeutic claims. The dual carbon goals framework pressures manufacturers to reformulate packaging materials and reduce water intensity in production processes. Stakeholders must monitor evolving MEE environmental compliance deadlines and shifting consumer preference toward clean-label formulations to calibrate R&D allocation and channel investment decisions.
Market Dynamics
Live-stream commerce platforms are compressing brand-to-consumer distance in China's oral care sector, collapsing traditional distributor margins while accelerating trial-size conversion rates among tier-one city millennials.
Growth Catalysts
- Dual carbon goals framework:MEE compliance deadlines pressure manufacturers toward biodegradable packaging and water-efficient production, opening premium positioning for early adopters.
- Professional dental aesthetics demand:Shanghai and Beijing clinics now bundle take-home maintenance kits with whitening procedures, embedding oral care into medical-adjacent consumption.
- NMPA cosmetic registration pathways:Streamlined safety assessment protocols for enamel-repair claims reduce time-to-market for functional toothpaste variants.
Market Restraints
- Fluoride compound cost volatility:Sodium fluoride and stannous fluoride feedstock prices fluctuate with phosphate mining output, squeezing margin on therapeutic formulations.
- Southwestern pharmacy channel concentration:Yunnan Baiyao's traditional Chinese medicine-infused variants lock shelf space in Sichuan and Yunnan provinces, limiting new entrant access.
- GB standard testing duration:SAMR-mandated antimicrobial efficacy protocols extend product launch timelines by 8-14 months for novel active ingredients.
Strategic Opportunities
- Lower-tier city penetration:Chongqing and Chengdu per-capita oral care spending remains 40-60% below Shanghai levels, creating volume expansion headroom for mass-market entrants.
- Clean-label formulation convergence:Combination of prebiotic oral microbiome science with SLS-free surfactant systems addresses ingredient-conscious millennials.
- Cross-border e-commerce channels:Tmall Global and JD Worldwide enable foreign niche brands to bypass domestic manufacturing licensing for initial market testing.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging traditional Chinese medicine extraction with modern fluoride stabilization commands premium compensation in Guangzhou and Shenzhen.
- Legacy ERP integration friction:Domestic manufacturers replacing batch production systems with continuous manufacturing face data migration complexity with existing SAMR traceability databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Oral Care Market |
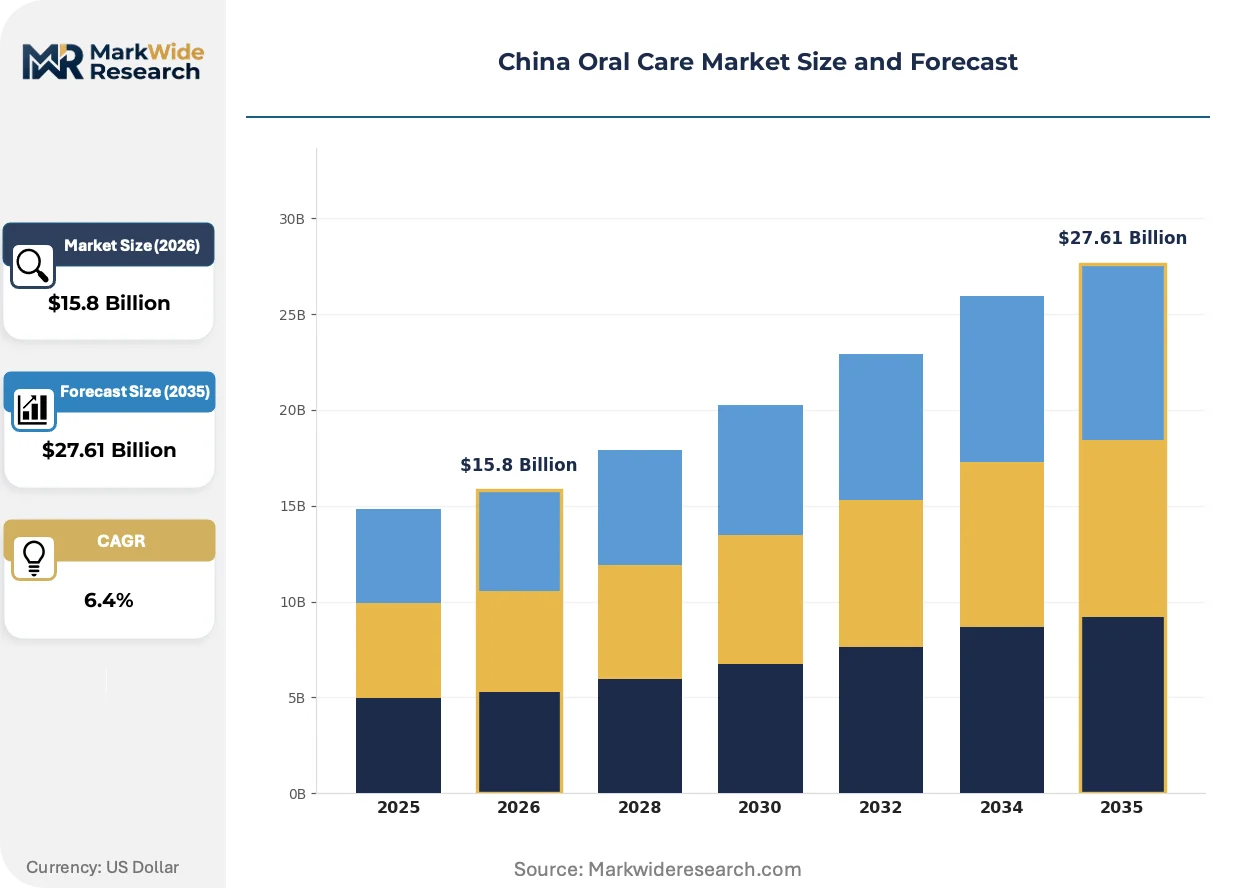
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $27.61 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toothpaste, Toothbrush, Mouthwash, Dental Floss End User: Adults, Children, Seniors, Professionals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Specialty Stores Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Unilever, Lion Corporation, Procter & Gamble, Guangzhou Weimeizi Industrial, Hawley & Hazel, Colgate-Palmolive, GlaxoSmithKline, Johnson & Johnson, Yunnan Baiyao Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Oral Care Market Strategic Shifts
Ingredient transparency demands and channel digitization are simultaneously elevating formulation complexity and collapsing go-to-market timelines across China's oral care landscape.
Hydroxyapatite remineralization technology is overtaking conventional fluoride-only approaches in sensitivity-focused segments. Young urban professionals in Beijing and Shenzhen clinics now request hydroxyapatite-post-treatment maintenance protocols. This shift is compressing R&D investment returns for brands anchored to single-actif fluoride positioning.
SAMR's tightened GB standard disclosure requirements for oral hygiene products now mandate full ingredient listing on outer packaging including flavoring compound concentrations. Manufacturers reformulating to exclude triclosan and certain parabens face accelerated retesting costs. Premium whitening lines targeting pharmacy channels absorb the largest compliance burden as therapeutic claim substantiation intensifies.
Subscription-based replenishment models through Douyin and Xiaohongshu storefronts are displacing supermarket aisle discovery for core toothpaste purchases. Tier-one city consumers now expect personalized brushing data integration with product delivery cycles. This behavioral pivot concentrates customer lifetime value capture among platforms owning both content and fulfillment infrastructure.
China Oral Care Market Segmentation
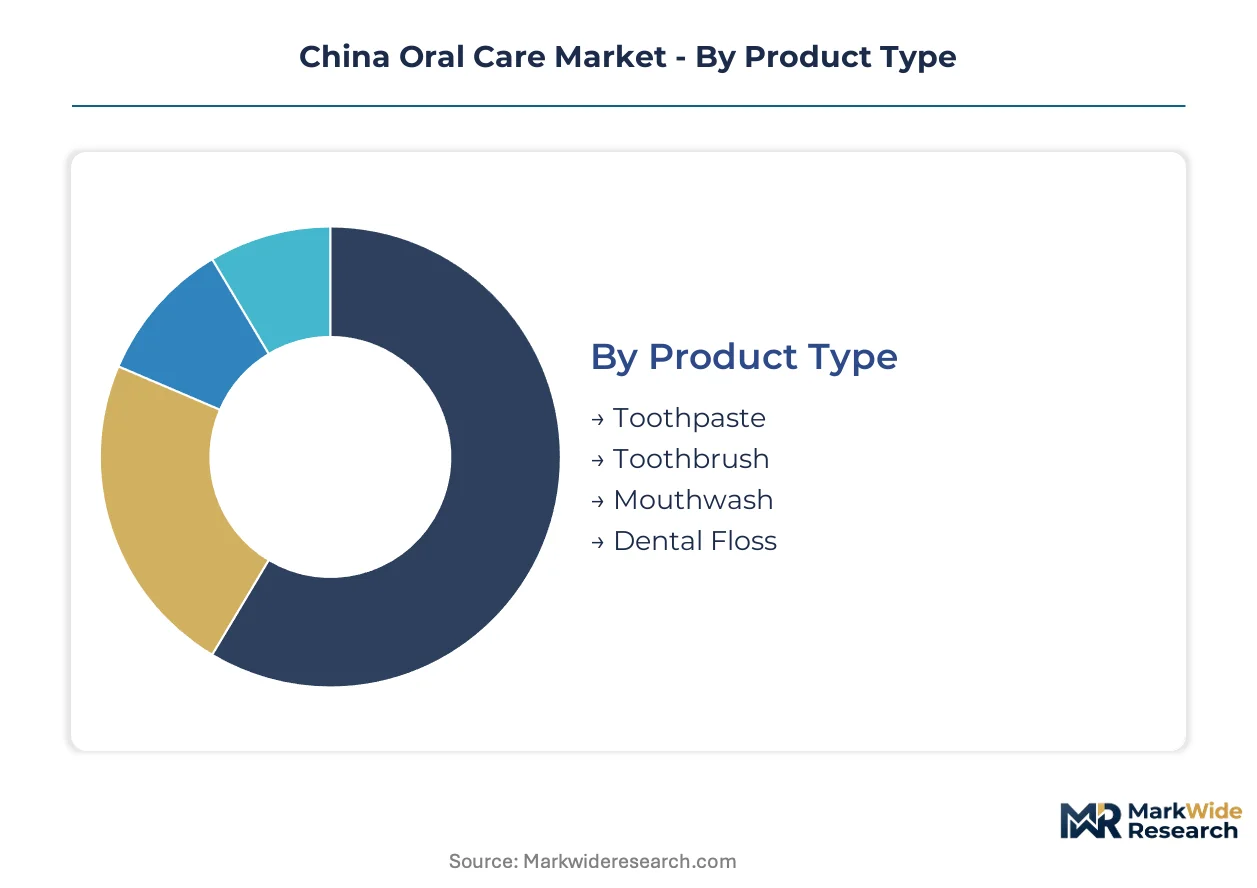
Segmentation in China's oral care market exposes divergent margin structures and channel strategies. Product formulations and distribution access determine competitive positioning more than brand equity alone. Understanding these fault lines clarifies where R&D investment and regulatory compliance resources generate returns.
Product Type:
Manufacturing capacity clusters around high-frequency replacement items with established GB standard compliance pathways, while novel formats face extended SAMR testing timelines.
- Toothpaste:Formulations incorporate fluoride compounds, hydrated silica abrasives, and surfactant systems calibrated between pH 4.5 and 10.5. Demand concentrates in Shanghai and Beijing where premium whitening and enamel-repair variants command pharmacy shelf space. NMPA cosmetic registration requirements for therapeutic claims intensify documentation burdens for functional variants.
- Mouthwash:Antimicrobial efficacy protocols under GB standards mandate 8-14 month testing cycles for novel active ingredients. Live-stream commerce platforms in tier-one cities accelerate trial-size conversion, embedding this format into daily oral care routines among young urban professionals.
- Toothbrush:Manual and powered variants compete on bristle density and ergonomic design specifications. E-commerce bundling with toothpaste subscriptions consolidates procurement volumes.
- Dental Floss:Waxed and unwaxed nylon or PTFE filament formats serve interdental cleaning niches. Pharmacy channel penetration remains limited outside premium urban clusters.
Toothpaste absorbs the bulk of installed capacity; mouthwash is expanding most quickly.
End User:
Demographic targeting in China maps directly onto per-capita spending differentials across city tiers and professional dental aesthetics adoption rates.
- Adults:Young urban professionals in tier-one cities drive demand for premium whitening and sensitivity formulations. Dental aesthetics clinics in Shanghai and Beijing now bundle take-home maintenance kits with whitening procedures.
- Children:Fluoride concentration limits and flavor masking requirements shape formulation constraints. Parental purchasing decisions prioritize safety certification visibility over price differentiation.
- Seniors:Gum recession and denture compatibility specifications concentrate demand in pharmacy channels with pharmacist consultation access.
- Professionals:Medical-adjacent consumption patterns link cosmetic dental procedures with prescribed maintenance protocols. Hydroxyapatite remineralization technology adoption clusters in Beijing and Shenzhen clinic networks.
Adult segments anchor revenue concentration; professional end users are gaining share fastest through medical channel integration.
Distribution Channel:
Channel selection determines margin capture and consumer education intensity, with digitization collapsing traditional distributor hierarchies.
- Online Retail:Douyin and Xiaohongshu storefronts displace supermarket aisle discovery through subscription-based replenishment models. Personalized brushing data integration with product delivery cycles concentrates customer lifetime value.
- Supermarkets:Guangzhou Weimeizi Industrial and comparable private-label manufacturers compete on cost-adjusted flexibility for domestic chain procurement. Shelf space allocation favors high-velocity SKUs with established brand recognition.
- Pharmacies:Yunnan Baiyao Group's traditional Chinese medicine-infused variants dominate southwestern channels in Sichuan and Yunnan provinces. SAMR-mandated ingredient disclosure requirements elevate compliance costs for therapeutic claim substantiation.
- Specialty Stores:Professional dental aesthetics clinics and premium e-commerce platforms consolidate procurement volumes for post-treatment maintenance kits.
Online retail absorbs the bulk of growth investment; specialty stores are climbing the fastest through medical-adjacent positioning.
Price Tier:
Pricing stratification reflects formulation complexity, packaging sustainability credentials, and channel margin requirements rather than pure ingredient cost structures.
- Premium:Hydroxyapatite and prebiotic oral microbiome formulations target ingredient-conscious millennials. Dual carbon goals framework pressures biodegradable packaging adoption.
- Mid-Range:Functional variants with enamel-repair or sensitivity claims balance NMPA registration costs against volume scalability. Chongqing and Chengdu per-capita spending gaps create expansion headroom.
- Budget:Mass-market fluoride formulations compete on replacement frequency and family pack sizing. Water intensity reduction in production processes becomes cost-critical.
- Luxury:Limited-edition packaging and cross-border e-commerce exclusivity via Tmall Global and JD Worldwide enable foreign niche brand positioning.
Mid-range tiers absorb the bulk of manufacturing volume; luxury segments are expanding most quickly through cross-border channel experimentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosphate mining corridors in Yunnan and Guizhou provinces anchor feedstock supply for sodium fluoride production, concentrating formulation expertise in southwestern China while coastal megacities drive premium consumption.
Shanghai
Dental aesthetics clinics in Shanghai's Jing'an and Pudong districts bundle take-home maintenance kits with whitening procedures, embedding oral care into medical-adjacent consumption. SAMR's NMPA cosmetic registration requirements mandate pre-market safety assessments for therapeutic claims. The Yangtze River Delta manufacturing cluster supplies hydroxyapatite remineralization formulations to clinic networks.
Beijing
Young urban professionals in Beijing's Chaoyang and Haidian districts request hydroxyapatite post-treatment maintenance protocols from aesthetic dental providers. Dual carbon goals framework pressures manufacturers toward biodegradable packaging adoption. Zhongguancun biotech corridors host formulation R&D bridging traditional Chinese medicine extraction with modern fluoride stabilization.
Guangzhou
Private-label manufacturers in Guangzhou's Baiyun and Panyu districts compete on cost-adjusted flexibility for domestic supermarket chain procurement. GB standard testing duration extends product launch timelines by 8-14 months for novel active ingredients. The Pearl River Delta packaging hub supplies sustainable materials to oral care brands targeting premium tier positioning.
Chengdu
Per-capita oral care spending in Chengdu remains 40-60% below Shanghai levels, creating volume expansion headroom for mass-market entrants. MEE environmental compliance deadlines pressure water intensity reduction in production processes. The Sichuan-Chongqing economic circle anchors southwestern pharmacy distribution for traditional Chinese medicine-infused variants.
Shenzhen
Cross-border e-commerce platforms in Shenzhen's Nanshan and Longgang districts enable foreign niche brands to bypass domestic manufacturing licensing for initial market testing. Live-stream commerce infrastructure compresses brand-to-consumer distance while accelerating trial-size conversion. Qianhai free trade zone hosts logistics operations for Tmall Global and JD Worldwide oral care fulfillment.
China Oral Care Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue clean-label microbiome positioning and subscription-based replenishment models. Market structure consolidates around multinational R&D infrastructure and domestic private-label manufacturing capabilities. Three archetypes dominate: multinational formulation leaders leveraging global R&D networks, traditional Chinese medicine specialists commanding regional pharmacy channels, and flexible contract manufacturers serving cost-sensitive retail chains. Competitive moves concentrate on portfolio diversification into sensitivity and whitening variants, plus channel expansion through live-stream commerce integration.
Within the multinational tier, Procter & Gamble and Colgate-Palmolive exemplify formulation leadership across therapeutic and cosmetic claim categories. Among domestic specialists, Yunnan Baiyao Group anchors traditional Chinese medicine-infused positioning in southwestern pharmacy channels. Guangzhou Weimeizi Industrial occupies the private-label manufacturing archetype, supplying cost-adjusted flexibility to domestic supermarket chains. These three represent distinct competitive vectors: global R&D scale, regional cultural heritage, and operational adaptability.
| Leading Market Players |
|---|
| Unilever |
| Lion Corporation |
| Procter & Gamble |
| Guangzhou Weimeizi Industrial |
| Hawley & Hazel |
| Colgate-Palmolive |
| GlaxoSmithKline |
| Johnson & Johnson |
| Yunnan Baiyao Group |
| Others |
Value Chain & Pricing Dynamics
Cosmetic chemist talent scarcity in Guangzhou and Shenzhen feeds labor-cost differentials that widen spreads between premium hydroxyapatite formulations and mass-market fluoride variants. Tier-one city manufacturers absorb premium compensation for formulation expertise bridging traditional Chinese medicine extraction with modern stabilization protocols.
Pricing Analysis
Volume concentrates in budget-tier family-pack fluoride toothpaste sold through supermarket chains, while margin pools in premium hydroxyapatite and prebiotic microbiome variants targeting pharmacy and specialty clinic channels. Price differentiation rests on therapeutic claim certification under NMPA cosmetic registration pathways and biodegradable packaging credentials aligned with dual carbon goals. Pricing pressure stems from sodium fluoride and stannous fluoride feedstock volatility tied to phosphate mining output. Mass-market buyers in lower-tier cities exhibit highest price sensitivity; professional dental aesthetics patients in Shanghai and Beijing demonstrate lowest sensitivity to per-unit cost.
Supply Chain Analysis
Direct-to-clinic channels handle professional-grade maintenance kit demand from Beijing and Shenzhen aesthetic dental networks, while e-commerce platforms consolidate tier-one consumer replenishment volumes. Manufacturing draws from phosphate mining corridors in Yunnan and Guizhou provinces for fluoride feedstock, with hydroxyapatite sourcing from Yangtze River Delta biotech clusters. Supply chain risk centers on single-source dependency for traditional Chinese medicine extract suppliers serving Yunnan Baiyao's southwestern pharmacy dominance. Distribution runs through live-stream commerce infrastructure owned by Douyin and Xiaohongshu, compressing legacy distributor hierarchies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's oral care sector is becoming a vertical-integration race as manufacturers pursue captive control over hydroxyapatite synthesis and sustainable packaging supply to defend margin pools against feedstock volatility and compliance cost escalation.
For Market Incumbents: Hedge fluoride cost exposure through backward integration into phosphate processing partnerships in Yunnan mining corridors. Secure shelf space in Chongqing and Chengdu pharmacy channels before regional traditional Chinese medicine specialists consolidate lower-tier penetration. Dual carbon goals compliance deadlines threaten laggards with production suspension risks. For New Entrants and Emerging Players: Begin with cross-border e-commerce testing through Shenzhen's Qianhai free trade zone logistics infrastructure to validate clean-label prebiotic formulations before committing to domestic NMPA registration timelines. Subscription-based replenishment models on Xiaohongshu offer the most penetrable go-to-market angle for millennial trial conversion. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with continuous production systems and SAMR traceability database integration capabilities. Acquisition targets should demonstrate water-intensity reduction credentials aligned with MEE environmental compliance trajectories. Monitor hydroxyapatite patent filing velocity as inflection signal for formulation leadership shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Processing | Captive sodium fluoride supply hedges feedstock volatility from Yunnan mining corridors. |
| Clean-Label Formulation Launch | SLS-free prebiotic variants capture ingredient-conscious millennial demand in tier-one cities. |
| Live-Stream Commerce Platform Partnership | Douyin storefront integration collapses trial-size conversion friction for novel formats. |
| NMPA Cosmetic Registration Investment | Streamlined enamel-repair claim pathways reduce time-to-market for functional variants. |
| Sustainable Packaging Transition | Biodegradable materials adoption aligns with dual carbon goals premium positioning. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with brand managers, category buyers at domestic supermarket chains, pharmaceutical procurement leads, and formulation R&D directors in Guangzhou and Shanghai were cross-referenced against SAMR GB standard documentation and NMPA registration databases. Bottom-up volume triangulation across product type, end user, and channel segments was reconciled with top-down spending pattern analysis from tier-one city household consumption surveys.
Granularity-level modeling disaggregated revenue and volume across toothpaste, mouthwash, toothbrush, and dental floss formats; adult, children, senior, and professional end-user categories; online retail, supermarket, pharmacy, and specialty store channels; and premium, mid-range, budget, and luxury price tiers. CAGRs were derived from trend extrapolation of per-capita spending differentials across Shanghai, Beijing, Guangzhou, Chengdu, and Shenzhen metropolitan clusters, with sensitivity testing for MEE compliance deadline acceleration and hydroxyapatite technology adoption curves.
Underlying measurement precision varies by segment; online retail and pharmacy channel data carry tighter precision than specialty clinic direct sales. Forecasts reflect assumptions regarding NMPA registration pathway efficiency, phosphate mining output stability, and live-stream commerce platform policy continuity. Periodic stress-testing of base assumptions against SAMR regulatory update cycles and dual carbon goals implementation timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Us Oral Care Market
Oral Care
Global Halitosis Market
Oral Care
Europe Oral Hygiene Market
Oral Care
Middle East and Africa Oral Care Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Oral Hygiene Products Market
Oral Care
Kids Oral Care Products Market
Oral Care
United States Oral Hygiene Market
Oral Care
Oral Thrush Treatment Market
Oral Care
Children's Oral Care Market
Oral Care
Kids Toothpaste Market
Oral Care
Oral Antiseptics Market
Oral Care
Europe Oral Care Market
Oral Care
Baby Oral Care Market
Oral Care
Toothcare Market
Oral Care
Tongue Cleaner Market