
 Ayurvedic Toothpaste Market | 2026-2036
Ayurvedic Toothpaste Market Size, Share, and Industry Trends Forecast 2026-2036
Ayurvedic Toothpaste Market Outlook
Modern retail shelf space allocation is tilting toward Ayurvedic oral care as mass-market brands cede position to heritage-positioned alternatives. Patanjali Ayurved Limited leverages its vertically integrated herb sourcing to sustain price competitiveness across North Indian kirana networks. Dabur India Limited anchors the premium medicinal segment through its Red franchise, while Himalaya Wellness Company differentiates via pharmacy-first distribution in metro clusters.
Ayurvedic toothpaste denotes a dentifrice formulated with botanical extracts, minerals, and resin-based actives following classical Ayurvedic compendia, typically containing neem, clove oil, or meswak with abrasive indices below conventional silica pastes. The formulation serves consumers seeking prophylactic gum care and halitosis management through plant-derived antimicrobials rather than synthetic chemistry. Herbal product type commands the widest retail footprint, though whitening variants are gaining fastest as younger buyers seek dual-function claims. Neem ingredient type dominates volume due to established consumer trust, while turmeric-infused lines occupy emerging premium positioning in direct-to-consumer channels.
India's FSSAI regulates Ayurvedic toothpaste under functional food-cosmetic overlap categories, creating compliance complexity for cross-border entrants. The BIS certification mandate for herbal cosmetics and India's PLI scheme for Ayurvedic manufacturing are reshaping domestic production economics. Stakeholders must monitor how regulatory divergence between India's traditional medicine frameworks and Western cosmetic directives affects export eligibility for Ayurvedic oral care brands.
Market Dynamics
FSSAI's evolving standards for Ayurvedic formulations are compressing formulation timelines while India's PLI scheme for herbal products accelerates domestic manufacturing consolidation. Urban millennial households in tier-two Indian cities are pulling demand toward dual-function whitening-herbal hybrids, forcing supply chain recalibration.
Growth Catalysts
- India's PLI scheme for herbal products:Production-linked incentives are luring contract manufacturers into Maharashtra-Gujarat corridors, expanding capacity for neem-based formulations.
- Urban millennial households:This segment's preference for prophylactic gum care over reactive treatment is expanding pharmacy-first distribution in metro clusters.
- BIS certification mandate:Standardized quality benchmarks for herbal cosmetics are legitimizing Ayurvedic toothpaste in modern retail, displacing unorganized sector alternatives.
Market Restraints
- Herb supply concentration:Neem and meswak sourcing clusters in Rajasthan and Gujarat create monsoon-dependent input volatility for formulators.
- FSSAI functional food-cosmetic overlap:Regulatory ambiguity between cosmetic and traditional medicine frameworks delays product registration for cross-border entrants.
- Synthetic chemistry substitution:Fluoride-based pastes retain dentist endorsement in premium urban channels, limiting Ayurvedic penetration in clinical recommendation networks.
Strategic Opportunities
- Turmeric-infused direct-to-consumer channels:Premium positioning through subscription models bypasses kirana network margin compression.
- Tier-two city pharmacy networks:Underpenetrated distribution in Indore, Lucknow, and Coimbatore offers first-mover shelf space allocation.
- CE marking convergence:Aligning BIS herbal standards with EU cosmetic directives opens export eligibility for compliant domestic manufacturers.
Industry Challenges
- Ayurvedic pharmacognosy expertise scarcity:Formulators struggle to recruit chemists versed in classical compendia standardization alongside modern GMP protocols.
- Dual certification timelines:Parallel FSSAI and BIS approvals extend product launch cycles, freezing working capital in regulatory limbo.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ayurvedic Toothpaste Market |
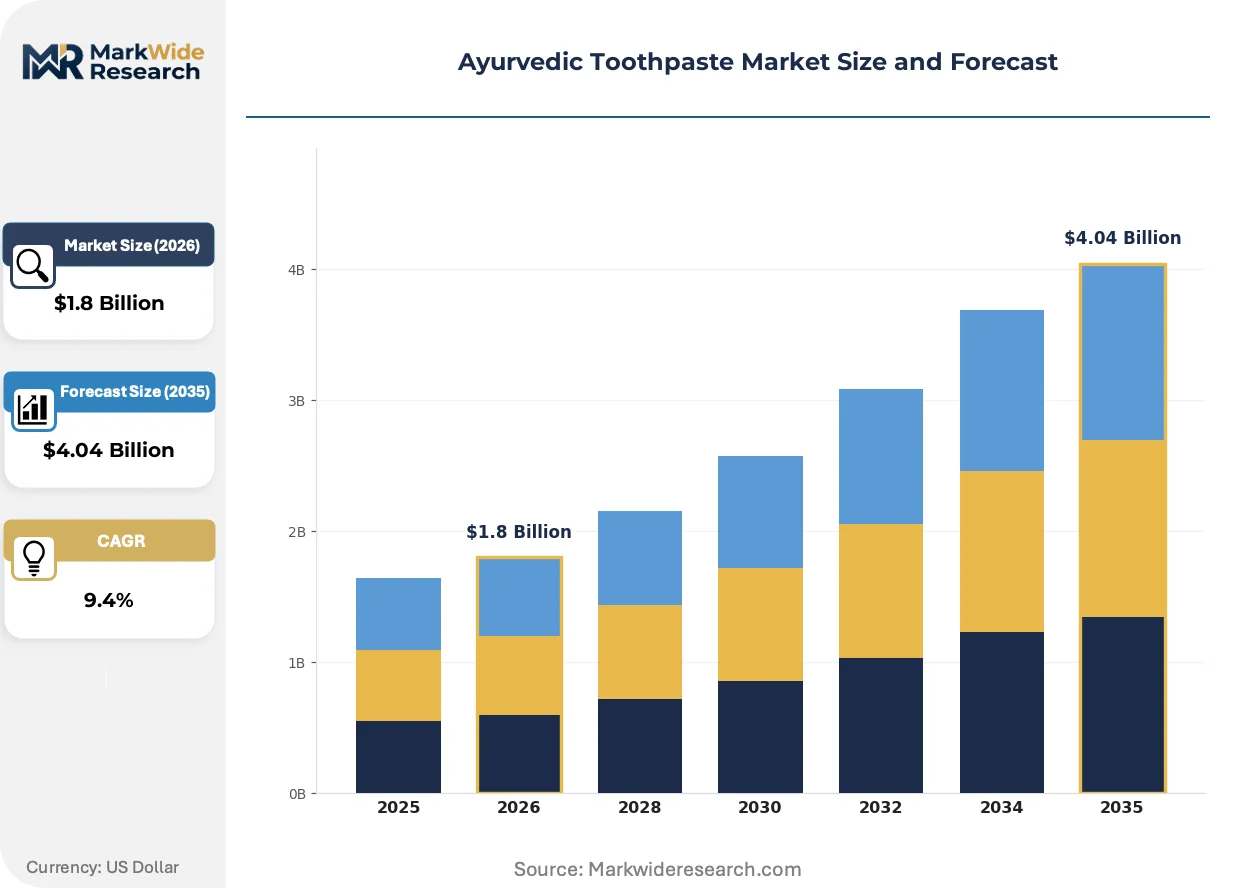
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal, Whitening, Natural, Medicinal Ingredient Type: Aloe Vera, Neem, Clove, Turmeric Packaging Type: Tube, Jar, Sachet, Bottle Sales Channel: Online, Supermarket, Health Stores, Pharmacies |
| Companies Covered | Colgate-Palmolive Company, Hindustan Unilever Limited, Patanjali Ayurved Limited, Zenes Biotech, Arogya Formulation Pvt Ltd, Dabur India Limited, Viccolabs, Lezaa Ayurveda, Himalaya Wellness Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ayurvedic Toothpaste Market Strategic Shifts
Formulation science is converging with classical Ayurvedic texts to create clinically substantiated botanical actives. Three distinct vectors are compressing competitive timelines and reshaping how heritage-positioned brands defend shelf space.
Encapsulation technology for volatile essential oils is collapsing stability limitations that previously constrained clove and eucalyptus concentrations in tube formats. Metro pharmacy chains are fast-tracking SKU approvals for these extended-shelf-life variants. The technology is collapsing the historical trade-off between antimicrobial potency and manufacturing yield loss.
FSSAI's draft guidelines on Ayurvedic oral care claims are forcing reformulation of halitosis management language toward microbiome-balance positioning. Domestic brands are responding by commissioning clinical studies at Indian Council of Medical Research affiliate labs. The regulatory pressure is most acute for whitening-variant launches targeting younger demographics.
Subscription-based replenishment models are displacing traditional kirana replenishment cycles among urban millennial households. Direct-to-consumer platforms are capturing recurring revenue through quarterly herb-sampler bundles paired with toothpaste auto-delivery. This behavioral shift is most visible in Bangalore and Hyderabad's tech-employed consumer base.
Ayurvedic Toothpaste Market Segmentation
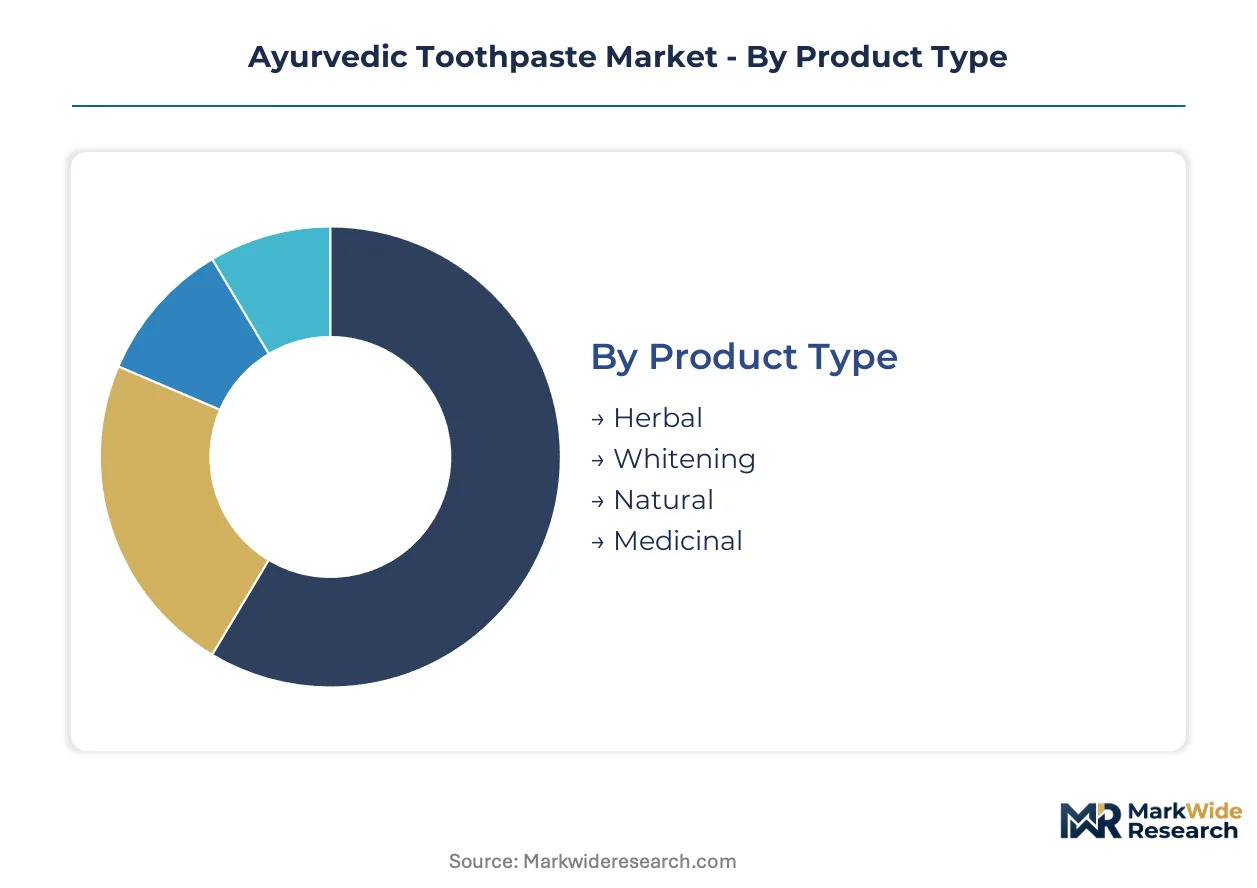
Ayurvedic toothpaste manufacturers navigate four distinct segmentation axes that determine pricing power, distribution access, and regulatory pathway. Each category reflects divergent consumer priorities across India's tier-two cities and metro clusters, with product type and ingredient type commanding the greatest strategic attention from formulators.
Product Type:
Consumer priorities span from heritage botanical claims to dual-function cosmetic benefits, creating distinct margin profiles across the use-case spectrum.
- Herbal:Formulations rely on classical Ayurvedic compendia with neem, meswak, and clove oil as primary actives, maintaining abrasive indices below conventional silica pastes. Demand concentrates in North Indian kirana networks where heritage positioning sustains price competitiveness against mass-market synthetics.
- Whitening:Dual-function variants combine botanical antimicrobials with mild polishing agents for surface stain removal, targeting urban millennial households seeking prophylactic gum care plus cosmetic enhancement. Metro pharmacy chains are fast-tracking SKU approvals for these lines as younger buyers displace single-function heritage alternatives.
- Natural:Minimal-processing claims emphasize resin-based actives and cold-pressed herb extracts without synthetic preservatives, appealing to subscription-model direct-to-consumer platforms in Bangalore and Hyderabad.
- Medicinal:Clinical positioning focuses on halitosis management and gingival health through microbiome-balance language, navigating FSSAI's evolving standards for Ayurvedic oral care claims.
The dominant share belongs to Herbal, while Whitening is closing the gap fastest.
Ingredient Type:
Raw material sourcing geography and monsoon dependency create tiered supply security profiles that cascade into formulation economics.
- Neem:Azadirachta indica extracts dominate volume due to established consumer trust across three generations, with sourcing clusters concentrated in Rajasthan and Gujarat creating input volatility during deficient monsoons. Maharashtra-Gujarat manufacturing corridors have built buffer inventory systems to stabilize neem-based production cycles.
- Turmeric:Curcuma longa formulations occupy emerging premium positioning through direct-to-consumer channels, with subscription models bypassing kirana network margin compression. Clinical substantiation studies at Indian Council of Medical Research affiliate labs are accelerating regulatory clearance for microbiome-balance claims.
- Aloe Vera:Aloe barbadensis gel bases provide soothing properties for sensitive gum segments, concentrated in pharmacy-first distribution targeting reactive treatment consumers.
- Clove:Syzygium aromaticum oil delivers eugenol-based antimicrobial action with established efficacy in classical texts, though encapsulation technology requirements elevate formulation costs.
Neem retains volume leadership, though Turmeric exhibits the steepest expansion trajectory.
Packaging Type:
Format selection tracks distribution channel economics and urban-rural consumption patterns across India's retail landscape.
- Tube:Laminated barrier structures dominate modern retail shelf space with extended shelf-life compatibility for volatile essential oil formulations.
- Jar:Wide-mouth containers serve family-size purchasing in tier-two city traditional trade, though hygiene concerns limit pharmacy channel placement.
- Sachet:Single-use sachets penetrate price-sensitive rural markets and travel retail, with minimal working capital requirements for kirana stockists.
- Bottle:Pump-dispense bottles target premium direct-to-consumer subscriptions with quarterly herb-sampler bundle pairings.
Tube formats command modern retail priority, while Sachet volumes expand most quickly in underpenetrated rural corridors.
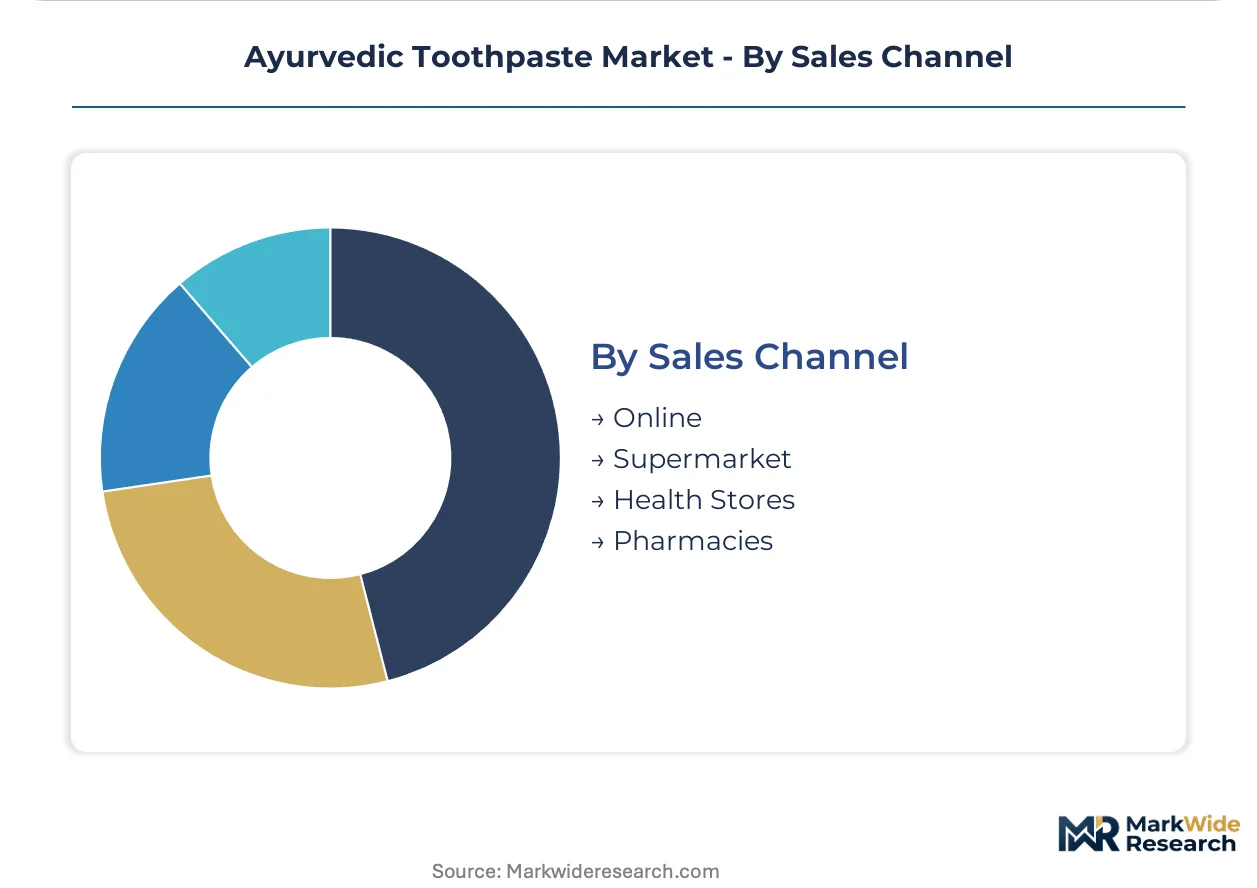
Sales Channel:
Channel mix reflects divergent consumer behaviors between replenishment-driven traditional trade and discovery-oriented digital platforms.
- Supermarket:Modern trade chains allocate expanding shelf space to Ayurvedic oral care as mass-market brands cede position, with standardized quality benchmarks legitimizing heritage alternatives.
- Pharmacies:Pharmacy-first distribution in metro clusters anchors premium medicinal positioning, leveraging clinician endorsement networks that fluoride-based pastes currently dominate.
- Online:Direct-to-consumer platforms capture recurring revenue through auto-delivery models, displacing traditional replenishment cycles among tech-employed urban consumers.
- Health Stores:Specialty wellness retailers emphasize natural and minimal-processing claims, serving subscription-based discovery behavior.
Supermarkets retain the broadest footprint, though Online channels are gaining share fastest among millennial households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for herbal products is accelerating manufacturing consolidation across Maharashtra-Gujarat corridors while urban millennial households in tier-two cities pull demand toward dual-function formulations. The regulatory divergence between India's traditional medicine frameworks and Western cosmetic directives is reshaping export eligibility calculus for domestic formulators.
India
Urban millennial households in Indore, Lucknow, and Coimbatore are expanding pharmacy-first distribution for whitening-herbal hybrids. FSSAI's evolving standards for Ayurvedic oral care claims are compressing product registration timelines for heritage-positioned brands. The Maharashtra-Gujarat manufacturing corridor is absorbing contract manufacturer migration incentivized by production-linked incentives.
United States
Heritage-positioned Ayurvedic brands are penetrating natural products retailers as consumers seek prophylactic gum care alternatives to fluoride-based pastes. FDA cosmetic regulations create compliance friction for botanical actives making microbiome-balance claims. California's wellness retail clusters are anchoring direct-to-consumer subscription growth for turmeric-infused formulations.
United Kingdom
South Asian diaspora communities are sustaining demand for neem-based heritage formulations through ethnic retail channels. MHRA guidance on traditional herbal medicinal products creates registration pathway complexity for classical compendia formulations. Greater London's pharmacy networks are trialing Ayurvedic oral care SKUs alongside mainstream synthetic alternatives.
Germany
Natural cosmetics certification demand is elevating BDIH and Natrue-compliant Ayurvedic toothpaste positioning in organic retail. BfArM's traditional use registration requirements for herbal medicinal products limit clinical claim expansion. Bavaria's wellness tourism corridors are integrating Ayurvedic oral care into hospitality amenity procurement.
United Arab Emirates
Expatriate South Asian populations are driving neem and meswak volume through hypermarket ethnic sections. MOHAP's cosmetic product registration requirements are harmonizing with GCC standardization initiatives. Dubai's duty-free retail channels are testing premium Ayurvedic oral care SKUs for transit passenger segments.
Ayurvedic Toothpaste Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated herb sourcing capabilities and pharmacy-first distribution networks. Three strategic archetypes dominate: heritage Ayurvedic houses with classical compendia expertise, FMCG majors leveraging mass-market scale, and direct-to-consumer specialists capturing subscription revenue. Competitive moves concentrate on backward integration into Rajasthan-Gujarat herb clusters and encapsulation technology licensing for volatile essential oil stability.
Within the heritage-positioned tier, Patanjali Ayurved Limited and Dabur India Limited exemplify divergent scale strategies, while Himalaya Wellness Company occupies the pharmacy-channel specialist position. Colgate-Palmolive Company and Hindustan Unilever Limited represent FMCG majors adapting synthetic chemistry portfolios toward botanical actives. Among emerging direct-to-consumer platforms, Zenes Biotech and Lezaa Ayurveda anchor subscription-model experimentation.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Hindustan Unilever Limited |
| Patanjali Ayurved Limited |
| Zenes Biotech |
| Arogya Formulation Pvt Ltd |
| Dabur India Limited |
| Viccolabs |
| Lezaa Ayurveda |
| Himalaya Wellness Company |
| Others |
Value Chain & Pricing Dynamics
Rajasthan-Gujarat neem and meswak sourcing clusters concentrate upstream herb supply, anchoring margin pools with formulators who have secured captive cultivation contracts or buffer inventory systems. Maharashtra-Gujarat manufacturing corridors absorb production-linked incentive benefits that compress contract manufacturing costs, while tier-two city pharmacy networks extract distribution premiums for whitening-herbal hybrid SKUs.
Pricing Analysis
Volume-discount tiering structures separate premium medicinal positioning from standard herbal and economy sachet formats. Price differentiation rests on BIS certification grade and pharmacy channel endorsement depth, with metro clinicians commanding brand premiums for microbiome-balance claims. Cost compression in the standard tier intensifies as unorganized sector alternatives cede shelf space to compliant domestic manufacturers. Kirana network buyers exhibit highest price sensitivity, while subscription-model urban millennials tolerate premium positioning for turmeric-infused direct-to-consumer lines.
Supply Chain Analysis
Contract manufacturing concentration sits with Maharashtra-Gujarat corridor facilities absorbing PLI scheme incentives for herbal product capacity expansion. Raw material dependencies draw from Rajasthan neem clusters, Gujarat meswak cultivation belts, and Kerala clove oil processing units. Single-source vulnerability in monsoon-dependent herb harvesting creates input volatility that propagates through quarterly production cycles. Distribution runs through pharmacy-first metro networks, kirana traditional trade, and direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
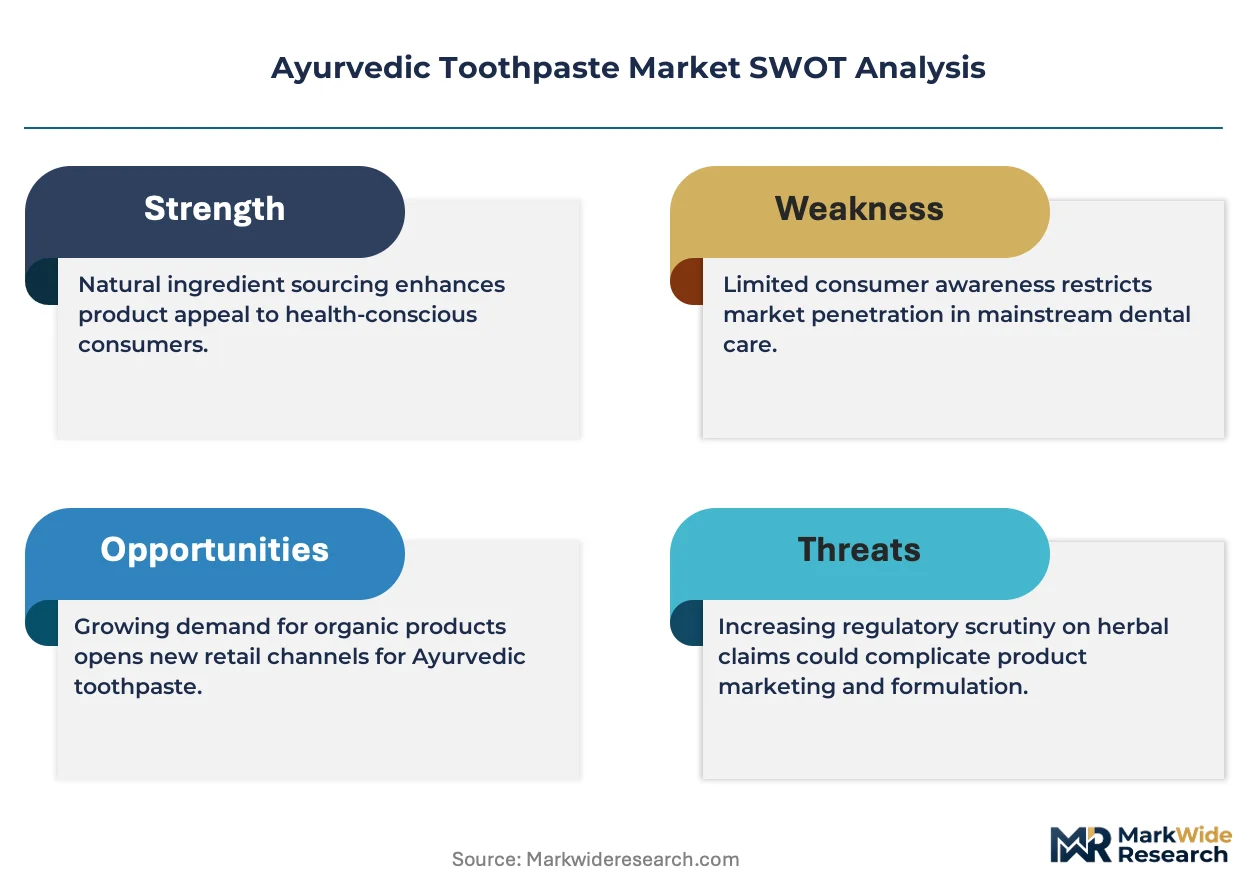
Fluoride-based synthetic pastes retain dentist endorsement networks that threaten Ayurvedic penetration in premium urban channels, forcing incumbents to defend substitution vulnerability through clinical substantiation investments.
For Market Incumbents: Harden pharmacy-first distribution control in metro clusters where clinician recommendation networks remain contested by synthetic chemistry alternatives. Deepen backward integration into Rajasthan-Gujarat herb clusters to stabilize input costs against monsoon volatility. Commission Indian Council of Medical Research affiliate studies to substantiate microbiome-balance claims that satisfy FSSAI evolving standards. For New Entrants and Emerging Players: Pursue tier-two city pharmacy networks in Indore, Lucknow, and Coimbatore where whitening-herbal hybrid SKUs face underpenetrated shelf space allocation. Target subscription-model direct-to-consumer channels in Bangalore and Hyderabad's tech-employed consumer base with quarterly herb-sampler bundle pairings. Anchor go-to-market positioning through turmeric-infused premium lines that bypass kirana network margin compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer specialists possessing encapsulation technology licenses for volatile essential oil stability. Long-term viability across the analysis window hinges on regulatory convergence between BIS herbal standards and EU cosmetic directives that would unlock export eligibility. Watch FSSAI draft guideline finalization as the inflection signal for claim substantiation cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Cultivation | Captive neem and meswak supply from Rajasthan-Gujarat clusters stabilizes monsoon-dependent input volatility. |
| Encapsulation Technology Licensing | Extended shelf-life compatibility for clove and eucalyptus oils collapses historical potency-yield trade-offs. |
| Pharmacy-First Distribution Expansion | Metro clinician endorsement networks displace fluoride-based paste dominance in premium channels. |
| Direct-to-Consumer Subscription Launch | Auto-delivery models capture recurring revenue from Bangalore and Hyderabad tech-employed households. |
| Dual Certification Investment | Parallel BIS and CE marking alignment opens EU export eligibility for compliant domestic manufacturers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with brand managers at heritage Ayurvedic houses, category buyers at modern retail chains, procurement leads at contract manufacturers, and regulatory affairs specialists navigating FSSAI-BIS overlap frameworks. Secondary validation drew from FSSAI draft guideline publications, BIS herbal cosmetics standards, PLI scheme administrative filings, and retail audit data tracking shelf space allocation shifts. Bottom-up SKU-level volume builds were triangulated against top-down category value estimates.
Calibration approaches anchored volume and value outputs to historical registration timelines, regulatory approval cycles, and channel penetration benchmarks across the projection horizon. Segmentation dimensions modeled include product type, ingredient type, packaging format, and sales channel with geographic clustering at state and city levels. CAGRs were derived from growth rate convergence analysis applied to tier-two city demand expansion, PLI capacity absorption curves, and subscription-model adoption patterns in tech corridor households.
Macroeconomic conditions sit as an overlay; deviation in monsoon rainfall indices, rural disposable income trajectories, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect assumptions on FSSAI guideline finalization timing and BIS certification mandate expansion scope. Quarterly review of herb input price indices, pharmacy chain SKU approval velocities, and direct-to-consumer platform subscriber retention is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Mouthwash Market
Oral Care
Oral Antiseptics Market
Oral Care
LED Oral Care Kits Market
Oral Care
Xerostomia Treatment Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Oral Hygiene Products Market
Oral Care
Japan Oral Hygiene Market
Oral Care
Europe Oral Care Market
Oral Care
Toothcare Market
Oral Care
Herbal Toothpaste Market
Oral Care
Oral Health Ingredient Market
Oral Care
Halitosis Treatment Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Us Oral Care Market
Oral Care
Tongue Cleaner Market
Oral Care
Oral Irrigator Market