
 Oral Rinse Market | 2026-2036
Oral Rinse Market Size, Share, and Industry Trends Forecast 2026-2036
Oral Rinse Market Intelligence
Market Dynamics
Pharmaceutical formulation talent is collapsing across consumer health divisions, forcing incumbents to automate batch testing and outsource flavor-chemistry functions. Colgate-Palmolive Company leverages captive manufacturing in Latin America to offset this labor pinch. Procter & Gamble Company sustains North American shelf dominance through pharmacy-exclusive distribution agreements. Johnson & Johnson anchors its position in clinical channels via hospital formulary relationships that competitors struggle to replicate.
Product Landscape
Oral rinse denotes a liquid solution containing antimicrobial, fluoride, or botanical actives designed for gingival irrigation, caries prevention, or breath freshening, typically dosed at 10-20 mL per use and swished for 30-60 seconds before expectoration. The category serves both consumer self-care routines and professional pre-procedural protocols in dental settings. Antiseptic formulations lead volume due to chlorhexidine and essential oil acceptance in peri-implantitis management, while natural segments capture margin expansion as clean-label positioning commands shelf price premiums. E-commerce channels represent the fastest-growing distribution vector, bypassing traditional pharmacy gatekeepers for subscription-driven replenishment models.
Regulatory Environment
The FDA oversees over-the-counter oral rinse safety through monograph compliance for antimicrobial actives, while the EPA regulates triclosan and other environmental discharge concerns from manufacturing facilities. EMA's Medical Device Regulation increasingly classifies prescription-grade rinses intended for surgical site preparation, altering conformity assessment pathways for European entrants. Stakeholders must monitor evolving classification boundaries between cosmetic and therapeutic claims, as regulatory reclassification would force clinical trial investments or channel restrictions.
Market Dynamics
Antimicrobial ingredient restrictions from the FDA and EMA are forcing rapid formulation pivots, compressing R&D timelines while elevating compliance costs across all market tiers.
Growth Catalysts
- Peri-implantitis protocols:Dental specialists in Germany and Switzerland now mandate pre-procedural rinses for implant maintenance, expanding clinic-grade volume.
- REACH substance restrictions:The European Chemicals Agency's tightening limits on residual alcohols in consumer products are accelerating botanical extract adoption.
- Subscription commerce infrastructure:Direct-to-consumer platforms in the United States bypass pharmacy intermediaries, capturing recurring revenue streams.
Market Restraints
- Chlorhexidine supply concentration:Active pharmaceutical ingredient production clusters in India create single-source vulnerability for antiseptic formulations.
- Clean-label cost premiums:Organic certification requirements for botanical actives inflate raw material spend versus synthetic alternatives.
- Triclosan manufacturing discharge:EPA effluent standards for antimicrobial waste elevate environmental compliance overhead at production facilities.
Strategic Opportunities
- Pediatric formulation gap:Alcohol-free, flavor-masked products for children remain underdeveloped in France and Italy.
- Hospital formulary expansion:Post-surgical oral care protocols in Japan's aging care facilities present untapped institutional demand.
- CE-MDR surgical classification:The EU Medical Device Regulation creates a premium tier for prescription-grade rinses with higher margin capture.
Industry Challenges
- Flavor-chemist scarcity:Consumer health divisions struggle to recruit formulation specialists capable of masking bitter actives without sugar alcohols.
- Batch testing automation:Microbial validation equipment requires capital deployment that mid-tier manufacturers cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oral Rinse Market |
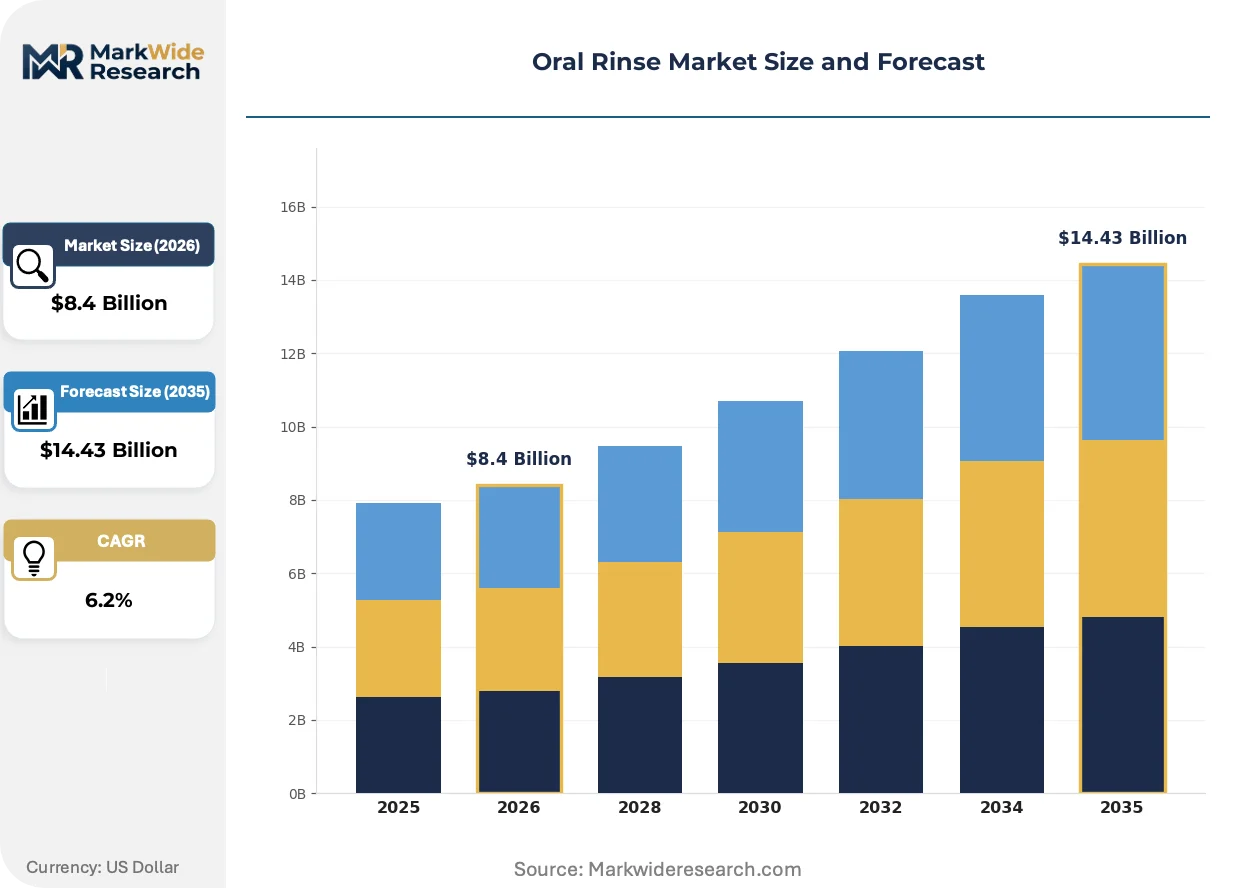
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiseptic, Fluoride, Natural, Cosmetic Ingredient Type: Alcohol-based, Chlorhexidine, Essential Oils, Herbal Distribution Channel: Pharmacies, Supermarkets, E-commerce, Health Stores End User: Adults, Children, Seniors, Dental Clinics |
| Companies Covered | GlaxoSmithKline plc, Church & Dwight Co., Colgate-Palmolive Company, Lion Corporation, Unilever plc, Kenvue Inc., Johnson & Johnson, Sunstar, Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oral Rinse Market Strategic Shifts & Innovations
Connected dispensing hardware and AI-driven personalization engines are redefining how oral rinse reaches end users, collapsing traditional channel hierarchies.
Nano-encapsulation technology for essential oil delivery is miniaturizing active particle size to enhance mucosal penetration. Specialty dental clinics in South Korea and Australia are piloting these formulations for peri-implantitis protocols. The technology is miniaturizing delivery systems from bulk bottles to single-dose pods, enabling point-of-care dispensing.
REACH authorization requirements for biocidal products are forcing reformulation of cetylpyridinium chloride variants across the European Union. Manufacturers must submit full toxicological dossiers that extend time-to-market by 18-24 months. Prescription-grade chlorhexidine rinses face reclassification scrutiny, prompting clinical trial investments from German and Dutch suppliers.
Subscription-driven replenishment is displacing pharmacy impulse purchases among urban professionals in the United States and United Kingdom. Direct-to-consumer platforms bundle diagnostic tools with personalized rinse formulations, capturing behavioral data that retail channels cannot access. This shift concentrates brand loyalty with early movers who own the customer relationship.
Oral Rinse Market Segmentation
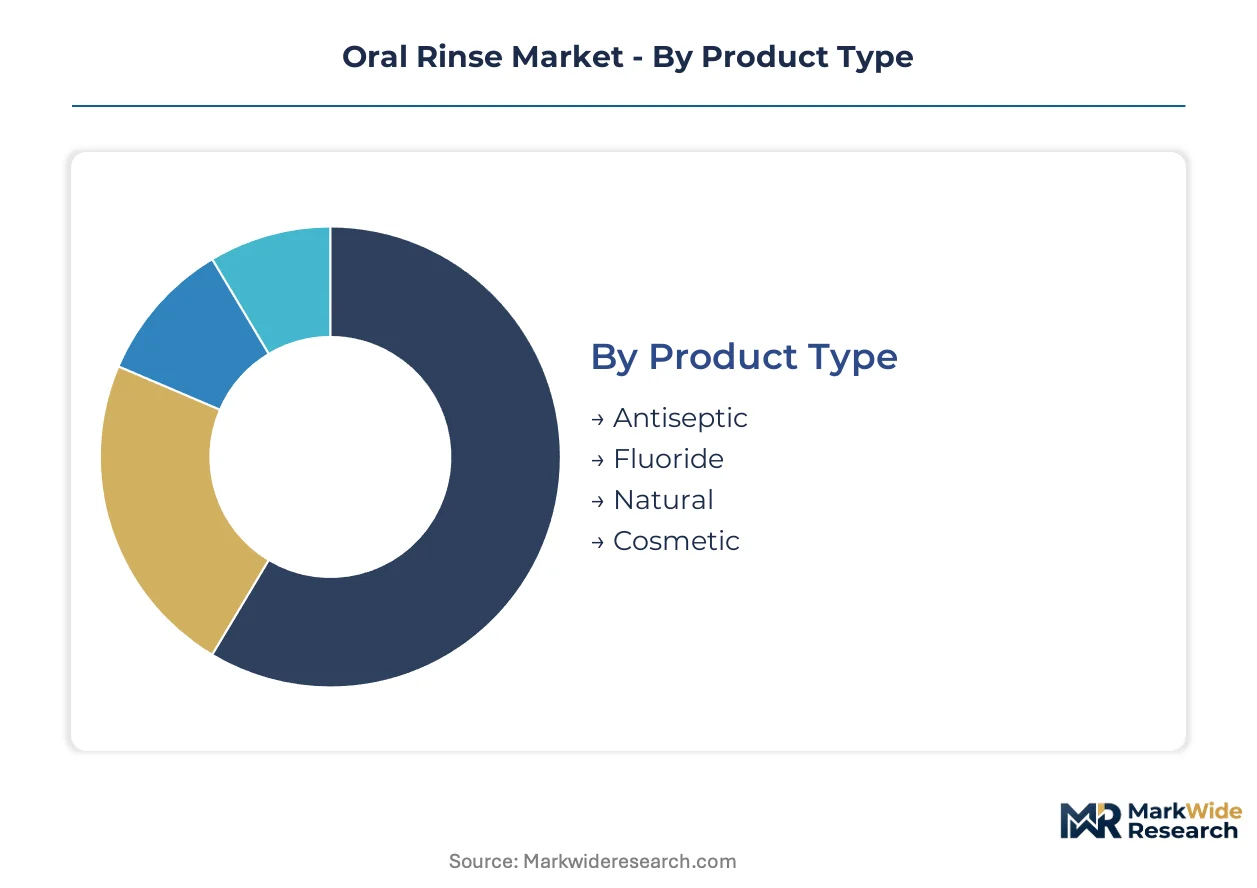
Oral rinse segmentation reveals divergent substitution threats across therapeutic and cosmetic positioning, with professional-grade formulations resisting displacement while breath-freshening variants face pressure from alternative hygiene formats. Understanding these fault lines enables targeted resource allocation across R&D and channel investments.
Product Type:
Antiseptic formulations confront the stiffest substitution pressure from prescription alternatives and procedural protocols, while natural segments compete against oil pulling and traditional remedies.
- Antiseptic:Chlorhexidine and essential oil formulations targeting gingivitis and peri-implantitis management command premium positioning in dental clinic protocols. Demand concentrates in Germany and Switzerland where specialists mandate pre-procedural rinses, though FDA antimicrobial restrictions compress formulation flexibility.
- Fluoride:Caries-prevention solutions with sodium fluoride or stannous fluoride actives dominate pediatric and high-cavity-risk adult segments. School-based programs in Japan and community health initiatives in Brazil sustain institutional procurement volumes despite home-care substitution.
- Natural:Botanical extracts and clean-label positioning capture margin premiums through e-commerce channels in the United States and United Kingdom.
- Cosmetic:Breath-freshening variants without therapeutic claims face intense pressure from gums, mints, and portable spray formats in convenience retail.
Antiseptic anchors the volume base while natural gains share at the steepest rate.
Ingredient Type:
Alcohol-based formulations face margin compression from REACH substance restrictions and consumer preference shifts, reshaping procurement priorities across manufacturing networks.
- Alcohol-based:Ethanol carriers delivering rapid antimicrobial action encounter regulatory headwinds from ECHA residual limits and dry-mouth concerns among aging populations. Reformulation investments in France and Italy target alcohol-free alternatives without efficacy sacrifice.
- Chlorhexidine:Prescription-grade digluconate salts maintain surgical site preparation standards in hospital formularies. Supply concentration in Indian API production creates vulnerability for European and North American finished goods manufacturers.
- Essential Oils:Thymol, eucalyptol, and menthol blends offer OTC accessibility with established peri-implantitis efficacy.
- Herbal:Aloe vera, green tea extract, and chamomile formulations target clean-label positioning in health stores and subscription platforms.
Chlorhexidine maintains institutional anchoring while herbal climbs fastest among direct-to-consumer channels.
Distribution Channel:
Pharmacy intermediaries face disintermediation pressure from platform economics and replenishment automation, altering margin capture across the value chain.
- Pharmacies:Brick-and-mortar drugstores retain formulary influence for prescription-grade chlorhexidine and fluoride rinses. Colgate-Palmolive and Procter & Gamble sustain shelf dominance through exclusive distribution agreements with United States pharmacy chains.
- E-commerce:Subscription-driven platforms bypass traditional gatekeepers, capturing behavioral data and recurring revenue from urban professionals. Direct-to-consumer bundling with diagnostic tools concentrates brand loyalty among early movers.
- Supermarkets:Mass-market cosmetic rinses compete for impulse placement in high-traffic retail.
- Health Stores:Natural and organic variants command price premiums through specialized retail in Germany and the United Kingdom.
Pharmacies anchor volume through clinical credibility while e-commerce expands most quickly via subscription infrastructure.
End User:
Dental clinics demonstrate the strongest resistance to substitution through protocol integration and insurance reimbursement, while consumer segments fragment across age-specific needs.
- Dental Clinics:Professional pre-procedural and post-surgical protocols mandate antiseptic rinses with documented peri-implantitis efficacy. Johnson & Johnson anchors this channel through hospital formulary relationships that competitors struggle to replicate.
- Seniors:Dry-mouth formulations and alcohol-free options align with medication-induced xerostomia and aging mucosal sensitivity. Japan's elder care facilities present untapped institutional demand for post-surgical oral care protocols.
- Adults:General preventive care and breath-freshening routines drive the broadest segment volume.
- Children:Alcohol-free, flavor-masked products remain underdeveloped in France and Italy, presenting formulation gaps for pediatric specialists.
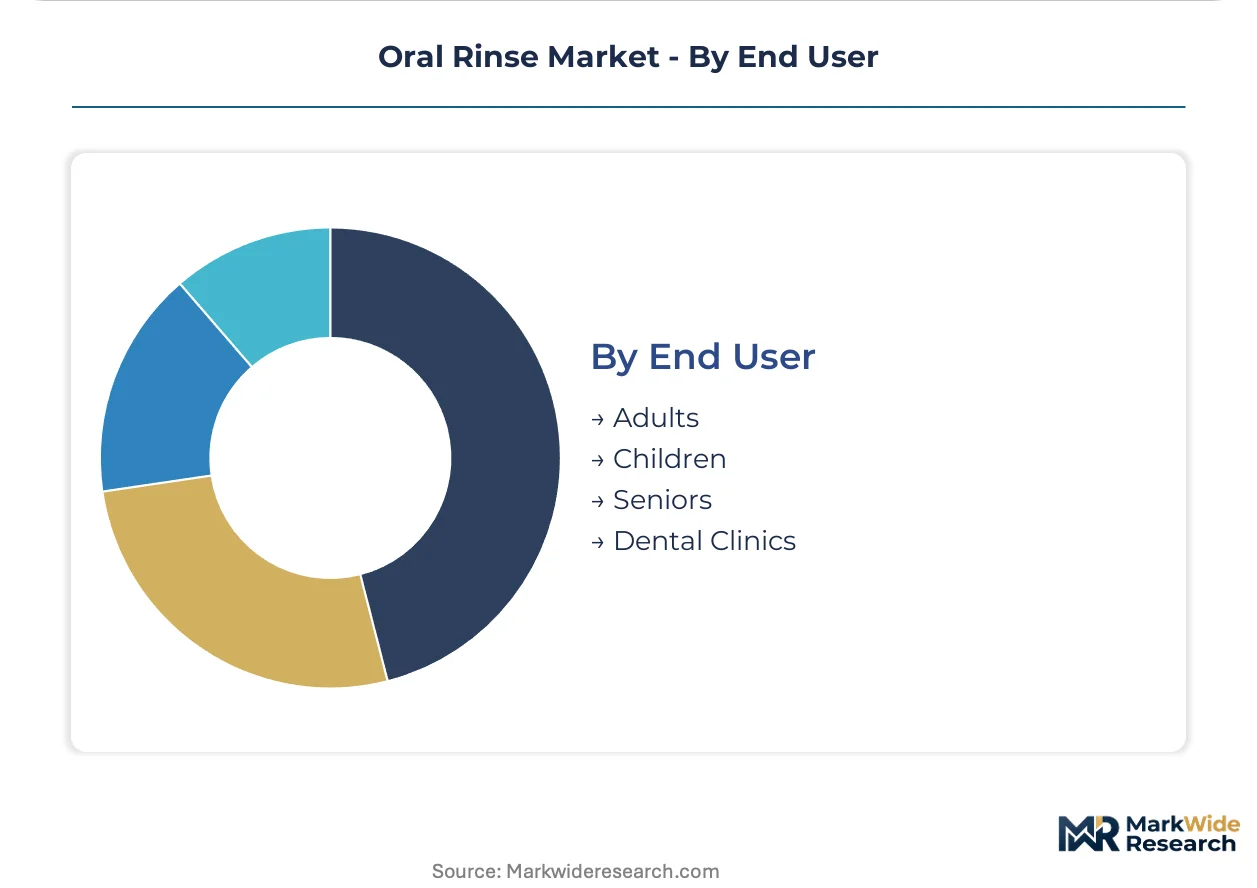
Adults sustain the broadest volume base while dental clinics capture share fastest through protocol standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between clinical-protocol markets and self-care economies. Germany and Switzerland integrate oral rinse into implant maintenance protocols, while the United States drives volume through aging demographics and private insurance reimbursement structures.
United States
Aging populations and employer-sponsored dental benefits sustain clinic-grade purchases through pharmacy and hospital formulary channels. FDA antimicrobial monograph compliance shapes OTC formulation standards, compressing R&D flexibility for alcohol-based variants. Manufacturing clusters in New Jersey and North Carolina host captive production facilities serving North American distribution networks.
Germany
Dental specialists mandate pre-procedural antiseptic rinses for peri-implantitis protocols, anchoring prescription-grade volume. EMA Medical Device Regulation reclassification pressures drive clinical trial investments from Dutch and German suppliers. The Rhine-Ruhr industrial corridor concentrates formulation and packaging operations for European market supply.
Japan
Elder care facilities present untapped institutional demand for post-surgical oral care protocols in aging care infrastructure. PMDA oversight of quasi-drug classifications creates regulatory friction for antimicrobial actives entering consumer channels. The Kanto region around Tokyo hosts headquarters operations for Lion Corporation and Sunstar, anchoring domestic brand equity.
United Kingdom
Subscription commerce penetration among urban professionals displaces traditional pharmacy impulse purchases through direct-to-consumer platforms. MHRA alignment with EMA biocidal product standards extends REACH authorization timelines for cetylpyridinium chloride formulations. The Southeast England logistics corridor supports e-commerce fulfillment infrastructure serving European markets.
India
Active pharmaceutical ingredient production for chlorhexidine digluconate concentrates in Gujarat and Maharashtra, creating supply vulnerability for finished goods manufacturers elsewhere. CDSCO oversight of cosmetic versus drug classifications determines import pathway complexity for international brands. The Mumbai-Pune pharmaceutical belt dominates API synthesis and contract manufacturing for antiseptic formulations.
Oral Rinse Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with multinational consumer health divisions controlling pharmacy formulary access and hospital procurement channels. Mid-tier manufacturers compete on flavor-chemistry differentiation and clean-label positioning through health store and e-commerce vectors. Two strategic archetypes dominate: captive manufacturing networks with Latin American cost bases, and clinical-channel specialists leveraging surgical-site preparation certifications. Competitive moves concentrate on pharmacy-exclusive distribution agreements and subscription platform acquisitions that collapse traditional retail gatekeepers.
Within the integrated multinational tier, Colgate-Palmolive Company and Procter & Gamble Company exemplify scale-driven positioning through North American shelf dominance and pharmacy chain relationships. Johnson & Johnson occupies a distinct clinical-channel position through hospital formulary anchoring that competitors struggle to replicate. Kenvue Inc. represents the consumer health spinoff archetype navigating portfolio rationalization post-demerger. Among Asia-Pacific headquartered players, Lion Corporation and Sunstar exemplify regional brand equity built through decades of domestic market penetration.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Church & Dwight Co. |
| Colgate-Palmolive Company |
| Lion Corporation |
| Unilever plc |
| Kenvue Inc. |
| Johnson & Johnson |
| Sunstar |
| Procter & Gamble Company |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between chlorhexidine API suppliers and European finished goods manufacturers lock in supply access while constraining price volatility exposure for antiseptic formulations. These contracts tether formulation costs to Indian production benchmarks and REACH compliance investments, compressing margin flexibility for mid-tier competitors.
Pricing Analysis
Project-based procurement for clinic-grade chlorhexidine formulations dominates institutional channels, with subscription-driven models displacing transactional purchases in direct-to-consumer segments. Price differentiation separates prescription-grade surgical rinses from over-the-counter cosmetic variants based on FDA monograph compliance tiers and EMA Medical Device Regulation certification levels. Cost compression in alcohol-based formulations is intensifying because REACH residual limits force reformulation investments. Pediatric specialists in France and Italy exhibit highest price sensitivity due to underdeveloped alcohol-free alternatives, while dental clinics in Germany and Switzerland demonstrate lowest sensitivity through insurance reimbursement anchoring.
Supply Chain Analysis
Strategic stockpiling of essential oil actives dominates procurement strategies as manufacturers buffer against harvest volatility and botanical certification delays. Active pharmaceutical ingredient production for chlorhexidine digluconate concentrates in India, with formulation and packaging operations clustering in Germany and the United States. Raw material dependencies include ethanol carriers, thymol extracts, and fluoride compounds. Single-source vulnerability from Indian API concentration creates supply disruption exposure. Distribution runs through pharmacy chain formularies for prescription grades and e-commerce fulfillment centers for subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral rinse market is experiencing high-growth disruption as nano-encapsulation technology and AI-driven personalization engines collapse traditional channel hierarchies and redefine product delivery formats.
For Market Incumbents: Shield formulary relationships in dental clinics by accelerating clinical trial investments for CE-MDR surgical classification compliance before reclassification deadlines tighten. Deepen backward integration into Latin American manufacturing to offset flavor-chemist scarcity and automate batch testing capabilities that mid-tier competitors cannot replicate. For New Entrants and Emerging Players: Anchor in the pediatric formulation gap across France and Italy, where alcohol-free, flavor-masked products remain underdeveloped and regulatory barriers deter established players. Target subscription commerce infrastructure in the United Kingdom and United States with diagnostic tool bundling to capture behavioral data and recurring revenue streams. For Investors and Strategic Acquirers: Clinical-channel specialists with hospital formulary anchoring and surgical-site preparation certifications represent the highest-conviction acquisition archetype for long-term viability across the next decade. Watch for FDA antimicrobial monograph revision timelines as the critical inflection signal that would force clinical trial investments and channel restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Surgical Classification | EMA reclassification creates premium tier with higher margin capture for prescription-grade rinses. |
| Direct-to-Consumer Launch | Subscription platforms bypass pharmacy gatekeepers and concentrate brand loyalty through data ownership. |
| Backward Integration | Captive manufacturing in Latin America offsets flavor-chemist scarcity and labor cost inflation. |
| Botanical Extract Adoption | REACH substance restrictions accelerate clean-label positioning with organic certification premiums. |
| Hospital Formulary Partnership | Johnson & Johnson's clinical-channel anchoring demonstrates defensible positioning against retail competitors. |
Research Approach
A standing panel of dental clinic procurement managers, pharmaceutical formulation directors, regulatory affairs specialists, and e-commerce platform operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA monograph filings, EMA Medical Device Regulation submissions, REACH authorization databases, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, ingredient classification, distribution channel, and end-user archetype. CAGRs were derived from trend extrapolation of clinic-grade protocol adoption and subscription commerce penetration rates, with inputs from chlorhexidine supply concentration indices and antimicrobial regulatory restriction timelines.
Material uncertainties — FDA antimicrobial monograph revisions, EMA reclassification enforcement, and Indian API supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and supply chain continuity. Revision becomes warranted when chlorhexidine supply concentration or REACH authorization timelines cross thresholds that alter competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Japan Oral Hygiene Market
Oral Care
Baby Teeth Care Products Market
Oral Care
Oral Hygiene Products Market
Oral Care
Mouth Spray Market
Oral Care
Mouthwash Market
Oral Care
Mouth Sore Medicine Market
Oral Care
Halitosis Treatment Market
Oral Care
Antiseptic Mouthwash Market
Oral Care
Canker Sores Treatment Market
Oral Care
Adult Oral Care Products Market
Oral Care
Oral Health Ingredient Market
Oral Care
Tongue Cleaner Market
Oral Care
Dry Mouth Relief Market
Oral Care
Toothcare Market
Oral Care
Oral Care Market
Oral Care
Oral Irrigator Market