
 United States Non-Ferrous Scrap Recycling Market | 2026-2036
United States Non-Ferrous Scrap Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
United States Non-Ferrous Scrap Recycling Market Analytics
Modular sorting and processing service bundling is broadening buyer choice among mid-sized foundries and fabricators. David J. Joseph Company leverages its river terminal network to dominate barge-fed supply chains into Ohio Valley smelters. Sims Metal sustains coast-to-coast collection density through its port-adjacent shredding footprint. OmniSource Corporation anchors Midwest industrial demand with integrated scrap-to-semifinished logistics.
United States non-ferrous scrap recycling encompasses the collection, processing, and re-melting of base metals excluding iron and steel, typically achieving purity thresholds of 95-99.5% through eddy-current separation and optical sorting before furnace reintroduction. The practice displaces energy-intensive primary extraction, with recycled aluminum requiring roughly 5% of the electricity needed for virgin production. Aluminum scrap holds the largest volume share among material types, though copper commands the deepest margin pool due to electrification-driven purity premiums. Pyrometallurgical processing remains the workhorse method, yet hydrometallurgical lines are gaining traction for complex multi-metal recovery from e-waste and EV battery packs.
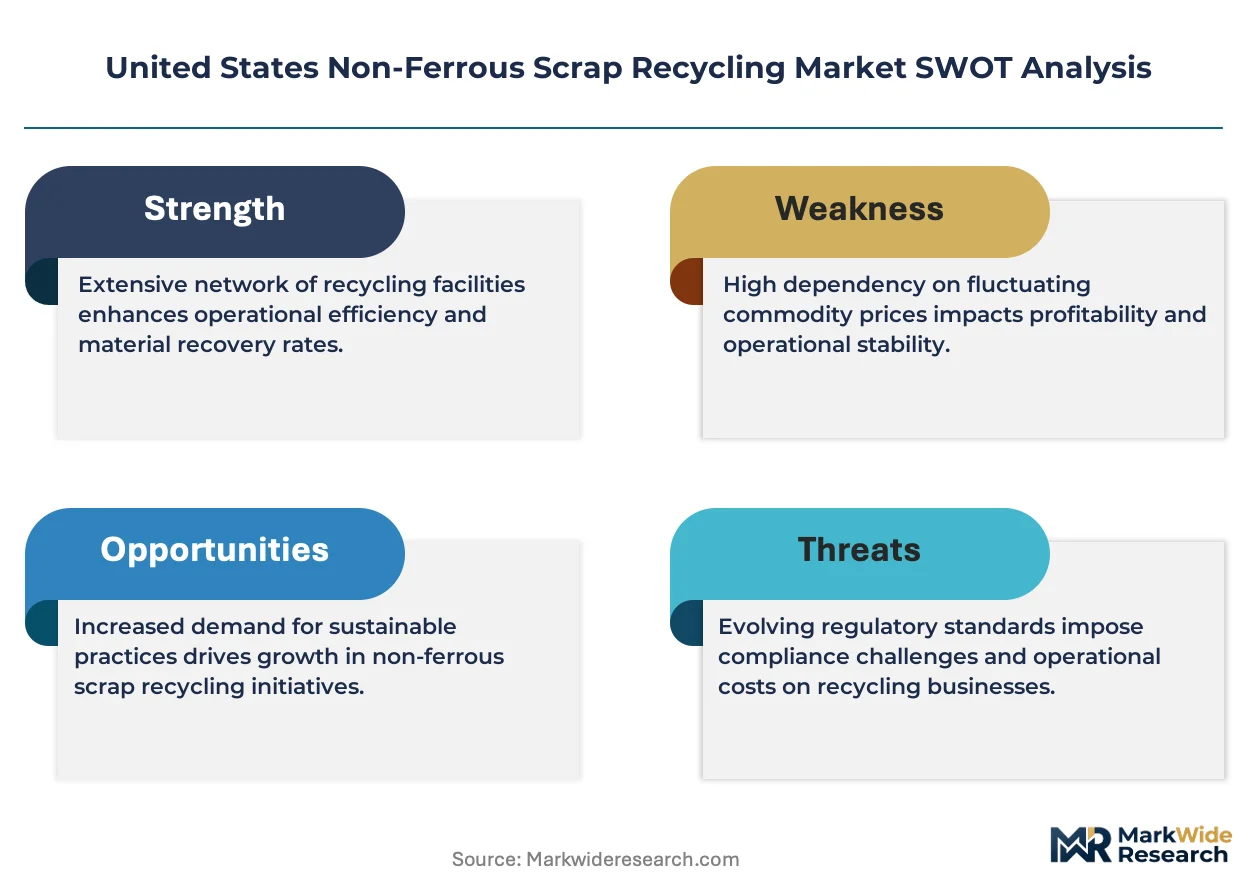
EPA hazardous waste classifications under RCRA, OSHA workplace exposure limits for metal dust, and state-level scrap metal theft reporting laws collectively shape operational compliance costs and facility siting decisions. The SEC climate disclosure rules are pushing OEM customers to document recycled content percentages, tightening chain-of-custody requirements across supplier networks. Stakeholders must monitor how EPA air quality standards for secondary smelters and evolving state extended producer responsibility frameworks reshape feedstock economics and processing technology choices.
Market Dynamics
Electric vehicle battery manufacturers are locking in long-term offtake agreements for aluminum and copper scrap, tightening feedstock availability for traditional foundry buyers across the Great Lakes industrial corridor.
Growth Catalysts
- EPA emissions rules:Secondary smelters face tightening air quality standards that favor recycled feedstock over energy-intensive primary metal production. Facilities investing in emission controls gain preferential permitting.
- State landfill diversion mandates:Michigan, Ohio, and Indiana enforce aggressive metal recovery targets that guarantee minimum scrap collection volumes. These policies secure feedstock pipelines for regional processors.
- EV battery pack dismantling:Hydrometallurgical recovery lines extract cobalt, nickel, and lithium from end-of-life batteries. This emerging waste stream commands premium pricing over traditional scrap grades.
Market Restraints
- Natural gas price volatility:Pyrometallurgical re-melting operations consume substantial fossil fuel inputs. Energy cost spikes compress operating margins for secondary aluminum smelters.
- Barge terminal concentration:Ohio Valley supply chains depend on riverine logistics controlled by a handful of terminal operators. Disruption at key Mississippi River junctions propagates downstream.
- Optical sorting throughput limits:Current near-infrared and X-ray fluorescence systems struggle with mixed-alloy feedstocks containing more than 5% contamination. Manual intervention adds labor cost.
Strategic Opportunities
- Texas Gulf Coast smelter corridor:Underdeveloped secondary non-ferrous capacity along the Houston Ship Channel offers greenfield site potential. Port access enables direct import of international scrap grades.
- SEC climate disclosure rules:OEM customers must document recycled content percentages in supply chain filings. Verified chain-of-custody systems command supplier preference premiums.
- Robotic dismantling convergence:Machine vision paired with adaptive gripping technology enables automated EV battery pack teardown. This pairing reduces hazardous material exposure while accelerating throughput.
Industry Challenges
- Smelter operator certification backlog:OSHA metal dust exposure compliance and RCRA hazardous waste handler permits face 18-24 month approval timelines in EPA Region 5.
- Legacy furnace refractory incompatibility:Hydrometallurgical lines require acid-resistant vessel linings that degrade conventional pyrometallurgical furnace infrastructure. Dual-process facilities face capital duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Non-Ferrous Scrap Recycling Market |
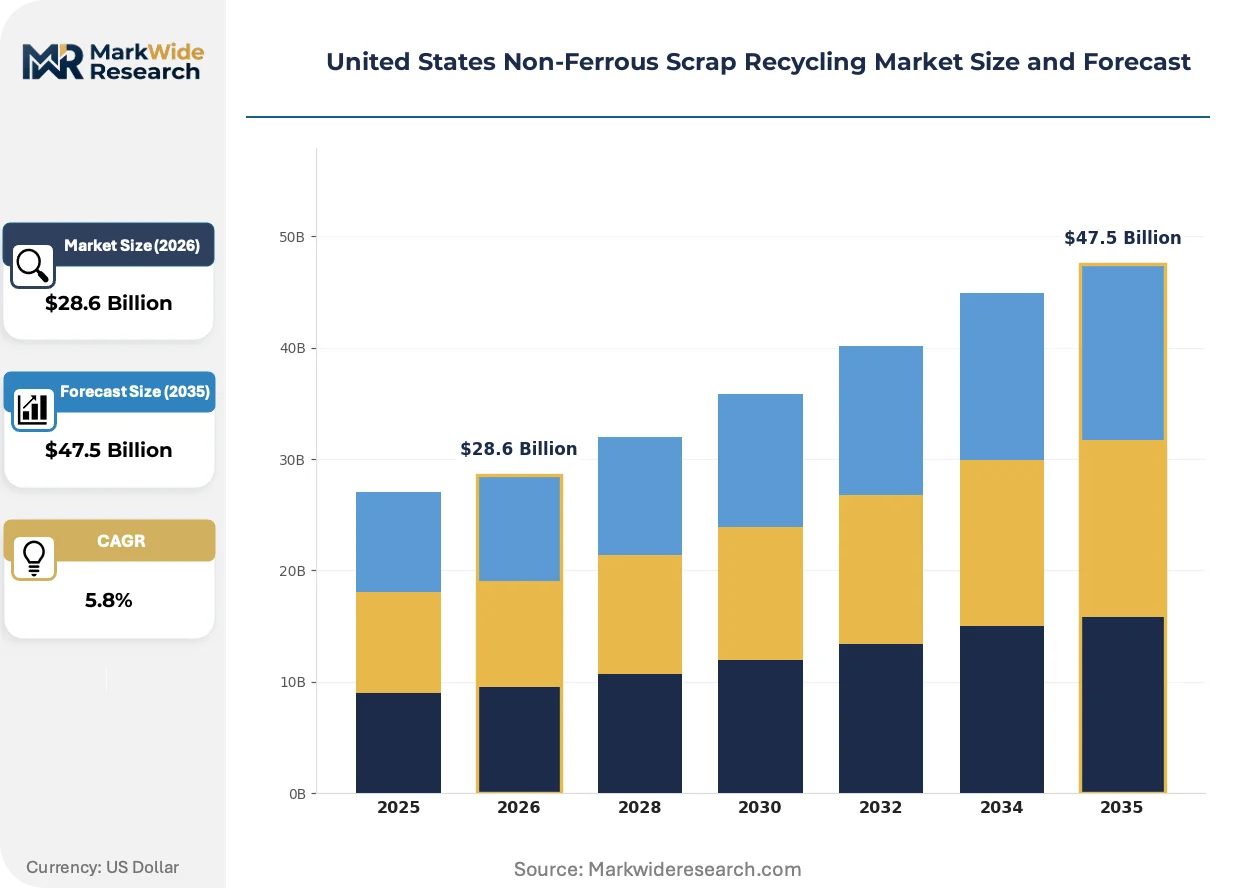
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Copper, Lead, Zinc Processing Method: Shredding, Melting, Sorting, Bailing End User: Manufacturers, Fabricators, Foundries, Exporters Recycling Technology: Hydrometallurgical, Pyrometallurgical, Electrometallurgical, Mechanical |
| Companies Covered | David J. Joseph Company, Sims Metal, OmniSource Corporation, United Scrap Metal, EMR, SA Recycling, Triple M Metal, GLE Scrap Metal, Radius Recycling, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Non-Ferrous Scrap Recycling Market Evolving Landscape
Digital traceability platforms and advanced separation technologies are compressing purity verification cycles while regulatory pressure on carbon intensity accelerates process innovation across secondary smelting operations.
Sensor-based sorting systems integrating laser-induced breakdown spectroscopy with artificial intelligence classification is automating real-time alloy identification at conveyor speeds exceeding 3 meters per second. Mid-sized foundries in Indiana and Ohio are retrofitting existing eddy-current lines with these modules to reduce laboratory assay delays. The technology is automating acceptance decisions that previously required human metallurgist intervention, shrinking feedstock intake bottlenecks.
OSHA's pending crystalline silica exposure standard for secondary smelters will mandate enhanced ventilation and personal protective equipment protocols across Michigan, Ohio, and Indiana facilities. Compliance investments of $2-4 million per plant are redirecting capital from capacity expansion toward environmental health and safety infrastructure. Smaller independent yards without captive industrial customers face consolidation pressure from larger integrated processors.
Automotive OEMs are unbundling scrap management from traditional tolling arrangements, preferring direct spot-market purchases with certified recycled content documentation. Tier-1 suppliers in Detroit and Toledo are establishing dedicated procurement teams for scrap specification compliance. This behavioral shift is most pronounced among battery enclosure manufacturers supplying Ford and GM electrification programs.
United States Non-Ferrous Scrap Recycling Market Segmentation
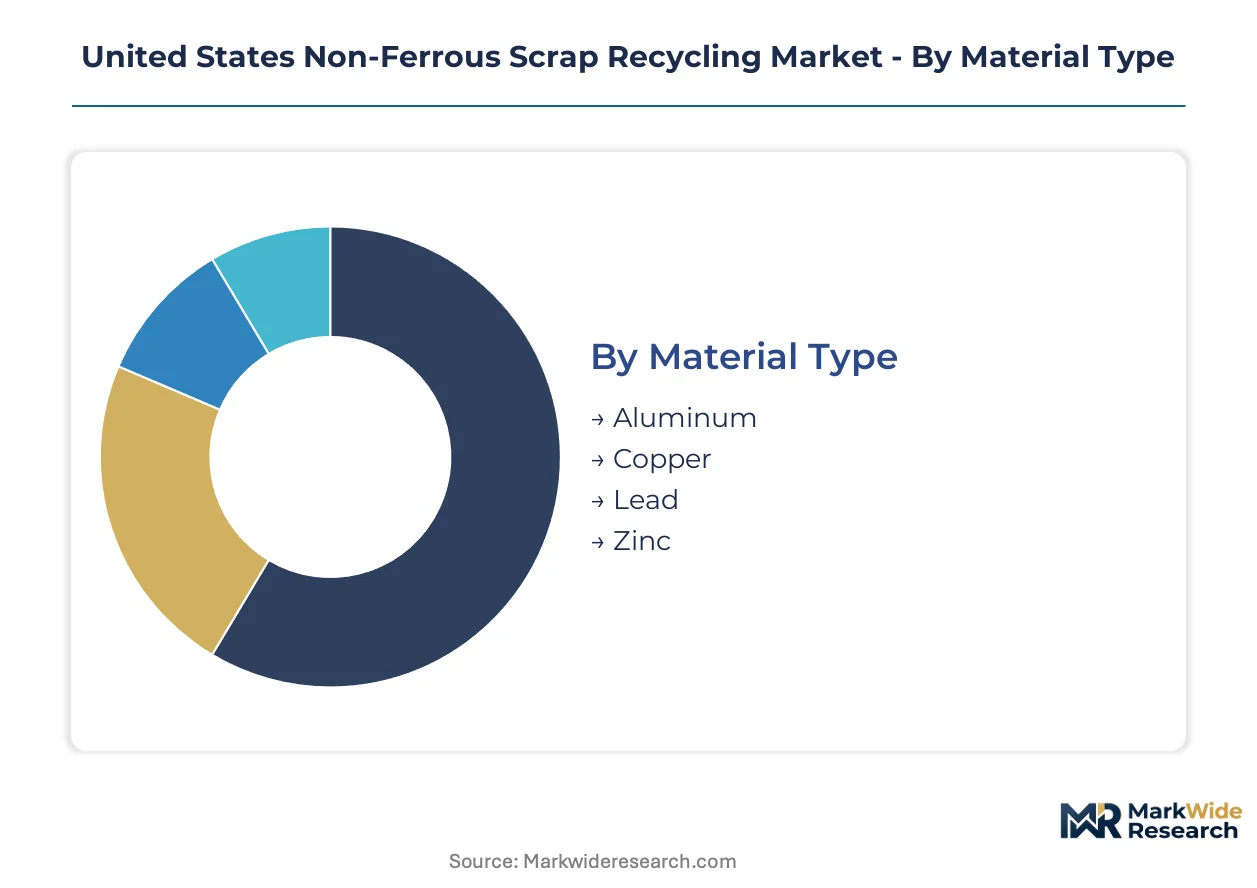
Non-ferrous scrap recycling in the United States fragments across material chemistry, processing intensity, and customer metallurgical requirements. Each segmentation axis reveals distinct margin profiles and capital deployment patterns that shape processor strategy across the Great Lakes corridor and Gulf Coast.
Material Type:
Aluminum commands volume dominance while copper captures premium pricing power in electrification-driven markets.
- Aluminum:Post-consumer and industrial scrap streams achieve 95-99.5% purity through eddy-current separation before furnace reintroduction. Demand concentrates in Ohio and Indiana automotive casting facilities where Ford and GM electrification programs specify certified recycled content for battery enclosures. EPA emissions rules favor this feedstock over primary smelting.
- Copper:Wire, tubing, and busbar scrap commands the deepest margin pool due to electrification-driven purity premiums. Michigan and Ohio wire rod mills and EV battery manufacturers are locking in long-term offtake agreements, tightening availability for traditional brass foundry buyers.
- Lead:Battery scrap recovery dominates this segment with established collection infrastructure through automotive retail channels. Secondary smelters in EPA Region 5 face 18-24 month permit backlogs for capacity expansion.
- Zinc:Die-cast scrap and galvanizing residue supply brass alloying and galvanizing flux markets. Processing concentrates in Illinois and Wisconsin facilities serving construction hardware manufacturers.
Mature deployment sits with aluminum. Newer deployment is concentrated in copper as EV battery pack dismantling accelerates.
Processing Method:
Capital intensity and energy exposure separate commoditized preprocessing from value-added re-melting operations.
- Shredding:High-volume size reduction at port-adjacent facilities enables downstream separation efficiency. Sims Metal sustains coast-to-coast collection density through this footprint, feeding both domestic smelters and export markets.
- Melting:Pyrometallurgical re-melting consumes substantial natural gas inputs, exposing margins to fossil fuel price volatility. Secondary aluminum smelters in Ohio Valley barge corridors depend on David J. Joseph Company terminal networks for feedstock security.
- Sorting:Sensor-based systems integrating laser-induced breakdown spectroscopy with artificial intelligence automate real-time alloy identification. Indiana and Ohio mid-sized foundries retrofit existing eddy-current lines to shrink laboratory assay delays.
- Bailing:Densification for efficient long-haul transport serves export corridors and domestic mill customers with strict density specifications. Gulf Coast processors leverage this step for containerized Asian shipments.
Processing gravity centers on shredding for volume throughput. Melting commands the steepest expansion trajectory as SEC climate disclosure rules push OEMs toward verified recycled content.
End User:
Customer sophistication spans tolling arrangements to spot-market procurement with chain-of-custody documentation.
- Manufacturers:Automotive OEMs are unbundling scrap management from traditional tolling arrangements, preferring direct spot-market purchases with certified recycled content documentation. Tier-1 suppliers in Detroit establish dedicated procurement teams for specification compliance.
- Fabricators:Custom alloy blending requirements drive long-term processor relationships with guaranteed chemistry windows. Ohio and Indiana job shops prioritize feedstock consistency over spot price minimization.
- Foundries:Secondary ingot demand from sand and investment casting facilities tracks construction and agricultural equipment cycles. Michigan foundries face consolidation pressure from integrated processors with captive scrap supply.
- Exporters:Containerized shipments of sorted zorba and twitch grades serve Asian secondary smelters. Houston Ship Channel terminals enable direct international scrap grade imports alongside domestic export flows.
Established relationships dominate fabricator procurement. Manufacturer direct sourcing represents the fastest share gain as Ford and GM electrification programs tighten supplier qualification.
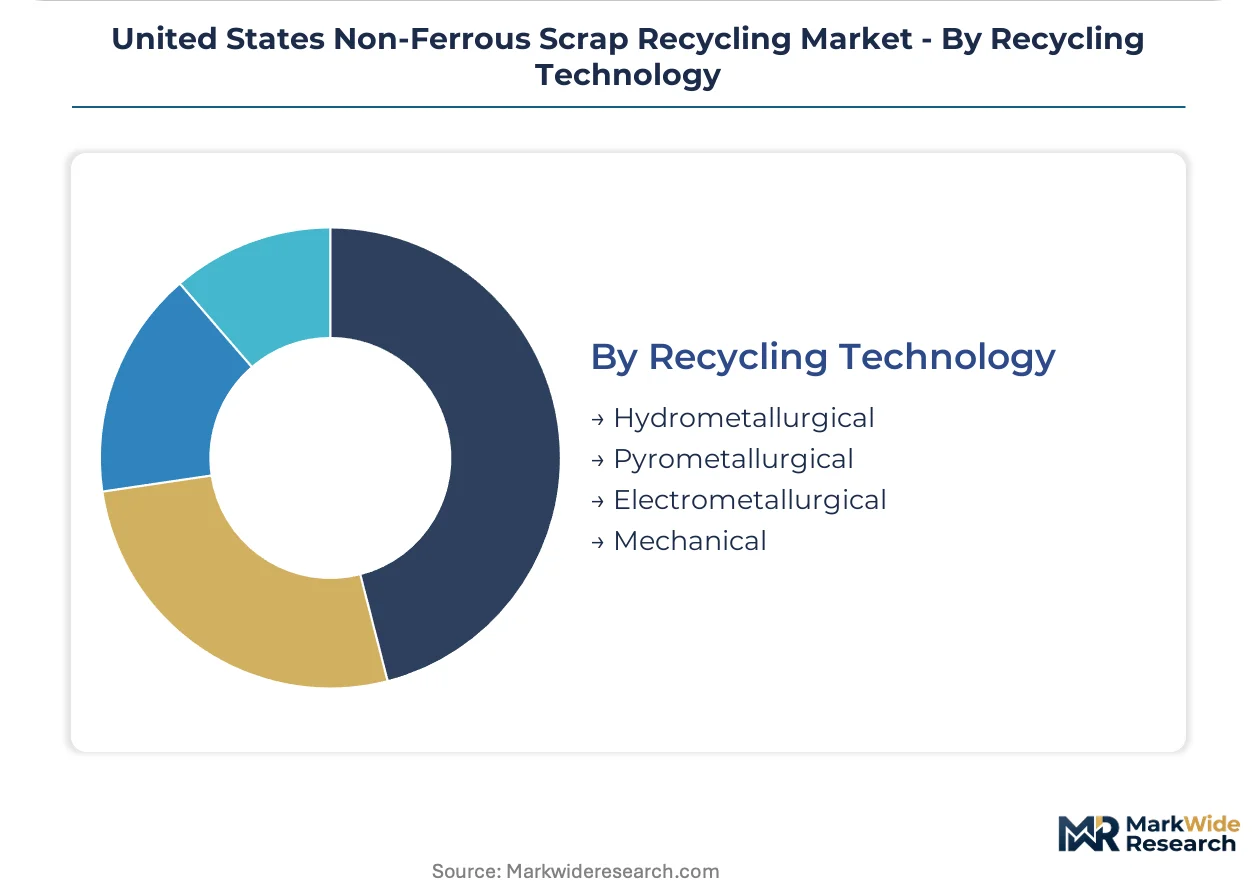
Recycling Technology:
Thermal versus chemical recovery paths diverge sharply in capital requirements and feedstock flexibility.
- Pyrometallurgical:High-temperature furnace re-melting remains the workhorse method for aluminum and copper scrap. OSHA's pending crystalline silica exposure standard will mandate enhanced ventilation investments redirecting capital from capacity expansion.
- Hydrometallurgical:Acid-based recovery lines extract cobalt, nickel, and lithium from end-of-life EV batteries. This emerging waste stream commands premium pricing over traditional scrap grades, though legacy furnace refractory incompatibility forces dual-process facilities into capital duplication.
- Electrometallurgical:Electrolytic refining achieves ultra-high purity for specialized conductor and semiconductor applications. Limited domestic capacity concentrates in Arizona and Texas border facilities.
- Mechanical:Physical separation without chemical transformation serves preprocessing stages and lower-grade mixed metal recovery. Optical sorting throughput limits at 5% contamination thresholds require manual intervention adding labor cost.
Pyrometallurgical deployment is mature across EPA Region 5. Hydrometallurgical lines are expanding most quickly for complex multi-metal recovery from e-waste and EV battery packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic secondary smelting capacity concentrates along inland waterways while coastal processors serve export corridors. The Great Lakes industrial corridor generates the deepest demand pool for certified recycled aluminum and copper feedstock. State-level landfill diversion mandates and EPA air quality standards reshape facility economics across the Midwest and Gulf Coast.
Great Lakes Industrial Corridor
Michigan, Ohio, and Indiana anchor North American non-ferrous scrap demand through Ford and GM electrification programs. EPA Region 5 enforces 18-24 month permit backlogs for secondary smelter expansions under RCRA hazardous waste classifications. Detroit and Toledo Tier-1 suppliers establish dedicated procurement teams for scrap specification compliance with SEC climate disclosure rules.
Ohio Valley Barge Corridor
Riverine logistics dominate feedstock movement into secondary aluminum smelters along the Mississippi River system. OSHA workplace exposure limits for metal dust shape facility siting decisions and compliance investment levels. Cincinnati and Louisville terminal operators control critical junctions where disruption propagates downstream to re-melting operations.
Texas Gulf Coast
Underdeveloped secondary non-ferrous capacity along the Houston Ship Channel offers greenfield site potential with deepwater port access. The state's lighter regulatory burden attracts processors seeking alternatives to EPA Region 5 permitting delays. Houston terminals enable direct import of international scrap grades alongside domestic export flows to Asian secondary smelters.
Southeast Manufacturing Belt
Georgia and Tennessee automotive casting facilities drive aluminum scrap demand outside traditional Midwest supply chains. State scrap metal theft reporting laws tighten chain-of-custody requirements across supplier networks. Atlanta and Chattanooga fabricators prioritize feedstock consistency over spot price minimization for custom alloy blending.
Pacific Coast Export Gateway
California and Washington port-adjacent shredding facilities serve containerized Asian shipments of sorted zorba and twitch grades. The state's aggressive extended producer responsibility frameworks reshape feedstock economics for e-waste and EV battery recovery. Los Angeles and Oakland processors balance export volumes against domestic smelter commitments.
United States Non-Ferrous Scrap Recycling Market Competitive Landscape
The competitive structure tilts toward integrated processors with captive terminal networks and long-term industrial offtake agreements. Three distinct archetypes occupy the landscape: river-terminal operators controlling barge-fed supply chains, coast-to-coast collection networks with port-adjacent shredding footprints, and Midwest-anchored specialists with scrap-to-semifinished logistics integration. Dominant competitive moves include strategic partnerships with automotive OEMs for certified recycled content supply and capacity expansion into hydrometallurgical recovery lines for EV battery dismantling.
Among river-terminal operators, David J. Joseph Company exemplifies the barge-fed supply chain archetype through its Ohio Valley network dominance. Sims Metal occupies a position within coast-to-coast collection density, sustaining shredding footprint scale across port-adjacent locations. OmniSource Corporation anchors the integrated Midwest processor tier with scrap-to-semifinished logistics serving regional industrial demand.
| Leading Market Players |
|---|
| David J. Joseph Company |
| Sims Metal |
| OmniSource Corporation |
| United Scrap Metal |
| EMR |
| SA Recycling |
| Triple M Metal |
| GLE Scrap Metal |
| Radius Recycling |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement teams in Detroit and Toledo now mandate certified recycled content documentation for battery enclosure suppliers, forcing secondary smelters to absorb chain-of-custody verification costs that compress margins across the Great Lakes corridor.
Pricing Analysis
Margin tightening in premium-grade aluminum scrap reflects EV battery manufacturer offtake agreements locking in long-term copper and aluminum supply at fixed premiums. Three-tier pricing structure across certified battery-grade, industrial foundry, and export twitch grades separates Ford-GM qualified suppliers from commodity exporters. Cost-down pressure on standard-grade scrap accelerates because optical sorting throughput limits at 5% contamination thresholds require manual intervention. Export buyers show highest price sensitivity versus automotive Tier-1 suppliers prioritizing specification compliance over spot minimization.
Supply Chain Analysis
Riverine barge freight from Mississippi River terminals to Ohio Valley smelters anchors feedstock economics, with David J. Joseph Company controlling critical junctions at Cincinnati and Louisville. Domestic supply draws from Michigan automotive stamping plants, Ohio wire rod mills, and Indiana die-cast facilities alongside containerized imports through Houston Ship Channel. Single-source vulnerability concentrates at Mississippi River flood-control infrastructure where disruption propagates downstream. Distribution runs through integrated processor networks with captive terminal access rather than spot-market broker channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Secondary non-ferrous scrap recycling has become a vertical-integration race where control over barge-terminal networks and hydrometallurgical recovery lines determines who captures EV battery dismantling premiums.
For Market Incumbents: To counter hydrometallurgical specialist entrants from the battery recycling sector, established pyrometallurgical operators should secure Ohio Valley barge terminal capacity additions before permitting backlogs extend further. Backward integration into EV battery pack collection through automotive retail partnerships locks in cobalt-nickel-lithium feedstock streams that command premium pricing over traditional scrap grades. For New Entrants and Emerging Players: Machine vision-enabled robotic dismantling technology offers a technology-first wedge into EV battery pack teardown where incumbent smelters lack acid-resistant vessel infrastructure. Texas Gulf Coast greenfield sites near Houston Ship Channel terminals represent the most penetrable geography given EPA Region 5 permitting delays and lighter state regulatory burden. A go-to-market angle anchored in verified chain-of-custody platforms for SEC climate disclosure compliance attracts OEM procurement teams establishing direct spot-market relationships. For Investors and Strategic Acquirers: The window for entry favors mid-sized processors with existing hydrometallurgical pilot lines or secured terminal leases in underdeveloped corridors. Acquisition targets should display dual-process capability spanning pyrometallurgical aluminum re-melting and acid-based critical mineral recovery. Watch for OSHA crystalline silica standard implementation as an inflection indicator that redirects capital from capacity expansion toward compliance infrastructure, pressuring independent yard valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Network Expansion | David J. Joseph Company's riverine logistics dominance locks in Ohio Valley feedstock security against barge disruption. |
| Hydrometallurgical Line Deployment | Acid-based recovery from EV batteries extracts cobalt, nickel, and lithium at premiums above traditional scrap grades. |
| Chain-of-Custody Certification | Verified recycled content documentation satisfies SEC climate disclosure rules for Ford and GM electrification programs. |
| Robotic Dismantling Integration | Machine vision with adaptive gripping reduces hazardous material exposure while accelerating EV pack teardown throughput. |
| Gulf Coast Greenfield Development | Houston Ship Channel port access enables direct international scrap import alongside domestic export flows to Asian smelters. |
Research Methodology
Trade databases, EPA enforcement records, and SEC climate disclosure filings formed the secondary backbone, cross-referenced with primary interviews spanning secondary smelter operators, automotive Tier-1 procurement directors, and barge terminal logistics managers. Bottom-up scrap flow modeling from collection through re-melting triangulated against top-down market sizing from customs data and industry association reports.
Historical trendline analysis across material type, processing method, and end-user segments informed the projection framework over the analysis window. Segmentation dimensions modeled include aluminum-copper-lead-zinc chemistry tiers, pyrometallurgical versus hydrometallurgical recovery technology, and manufacturer-fabricator-foundry-exporter customer archetypes. CAGRs derived from feedstock availability constraints, regulatory permitting timelines, and electrification-driven demand elasticity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under natural gas price spikes or Mississippi River logistics disruption. Forecasts reflect assumptions about EPA air quality standard enforcement consistency and state landfill diversion mandate durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
India Plastic Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
China Plastics Market
Recycled Plastics
US Plastics Market
Recycled Plastics
Modified Polypropylene Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Circular Plastic Feedstock Traceability Market