
 Vietnam Plastics Market | 2026-2036
Vietnam Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Plastics Market Analytics
ISO 9001:2015 certification is rotating as the baseline qualification for export-oriented molders serving Japanese and South Korean buyers. Haplast Group leverages integrated film extrusion and printing to sustain margin control across agricultural and industrial packaging grades. An Phat Bioplastics anchors its position through proprietary starch-blend formulations and PBAT compounding capacity. EuroPlas competes on color masterbatch specialization, supplying compounders throughout northern Vietnam's processing cluster.
Vietnam plastics encompass thermoplastic and thermoset polymers formulated with additives for processability, durability, and end-use performance, typically processed via injection molding, extrusion, or blow molding at melt temperatures between 160°C and 320°C depending on resin chemistry. These materials serve as lightweight, cost-efficient substitutes for metal, glass, and wood across industrial and consumer applications. Packaging dominates volume throughput, with food-grade polyethylene films capturing the largest share of export-oriented production. Polypropylene compounds for automotive components represent the fastest-expanding material category as VinFast's supplier localization program deepens. PVC for construction materials maintains mature, price-sensitive demand tied to residential and infrastructure development cycles.
Vietnam's Ministry of Natural Resources and Environment enforces Decree 08/2022/ND-CP plastic waste management rules, while the General Department of Vietnam Customs applies import tariff schedules that shape resin sourcing economics for domestic compounders. The national technical regulation QCVN 07:2009/BTNMT on hazardous substance limits in packaging directly affects formulation choices for food-contact applications. Stakeholders must monitor how draft extended producer responsibility legislation alters cost structures for single-use packaging categories before committing to capacity expansion.
Market Dynamics
Decree 08/2022/ND-CP is forcing resin compounders and converters to reengineer formulations toward biodegradable feedstocks while maintaining cost parity with conventional polymers, compressing margin structures across the Red River Delta processing cluster.
Growth Catalysts
- VinFast supplier localization:Automotive OEMs are qualifying Vietnamese molders for interior and under-hood polypropylene components, pulling capital into compounding capacity near Hai Phong port facilities.
- QCVN 07:2009/BTNMT compliance:Food-contact packaging exporters are upgrading to migration-tested polyethylene grades to access Japanese and South Korean retail channels.
- Cold-chain infrastructure buildout:Temperature-sensitive agricultural exporters are consuming multi-layer barrier films for seafood and tropical fruit shipments through modernized logistics corridors.
Market Restraints
- Feedstock import dependency:Domestic compounders source naphtha-derived resins through Singapore and South Korean traders, exposing margins to freight rate volatility and currency fluctuation.
- PBAT resin supply concentration:Biodegradable polyester feedstocks concentrate among Chinese petrochemical complexes, creating single-source risk for Vietnamese bioplastic converters.
- Starch-blend performance ceiling:Mechanical property limitations of agricultural-waste fillers restrict load-bearing applications, capping addressable market scope for domestic bioplastic producers.
Strategic Opportunities
- Mekong Delta underpenetration:Can Tho and surrounding provinces lack integrated resin-to-product infrastructure, offering first-mover positioning for film extrusion investments serving rice and aquaculture packaging.
- Extended producer responsibility prelude:Draft legislation mandating post-consumer collection systems creates service-revenue potential for compounders with reverse-logistics capabilities.
- Masterbatch-3D printing convergence:Color and additive concentrate producers can formulate filament-grade compounds for emerging industrial prototyping services in Ho Chi Minh City manufacturing parks.
Industry Challenges
- ISO 17025 laboratory scarcity:Migration testing and biodegradability certification for food-contact claims require offshore validation, extending product launch timelines by four to six months.
- Compounding equipment lead times:Twin-screw extruders for PBAT-starch alloying face eighteen-month delivery schedules from European and Japanese machinery builders, throttling capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Plastics Market |
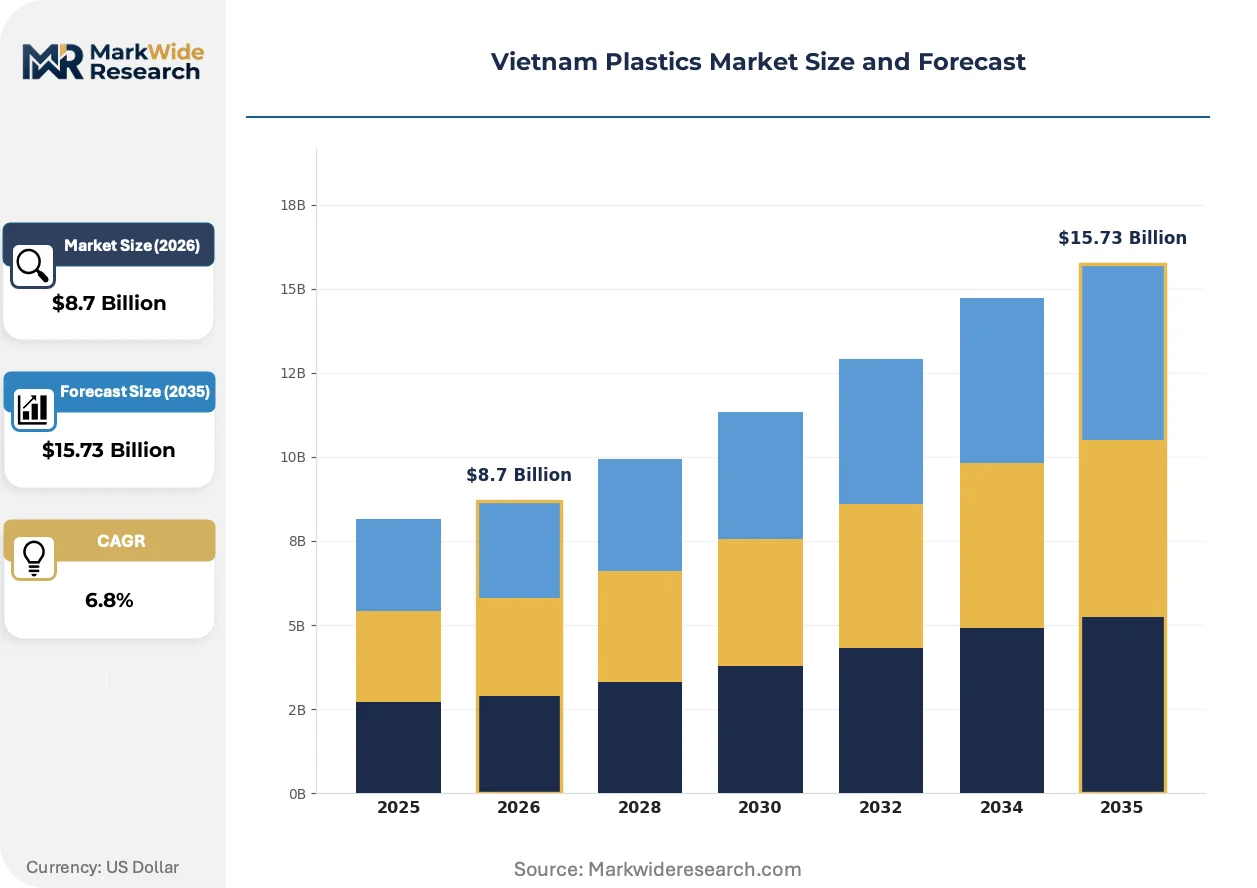
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Packaging, Consumer Goods, Automotive Components, Construction Materials Application: Food Packaging, Medical Supplies, Household Items, Electronic Components Material: Polyethylene, Polypropylene, PVC, Polystyrene End User: Manufacturers, Retailers, Wholesalers, Exporters |
| Companies Covered | Haplast Group, Polifilm Vietnam Co. Ltd, An Phat Bioplastics, Duy Tân Plastics, EuroPlas, Rang Dong Long An Plastic JSC, IFC Plastic Co. Ltd, Hanpak Vietnam, K-Packings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Plastics Market Evolving Landscape
Biodegradable formulation science is advancing faster than waste-collection infrastructure, creating formulation-deployment mismatches that favor flexible packaging over rigid applications in near-term investment planning.
Starch-PBAT alloy technology is bifurcating the flexible packaging supply base. An Phat Bioplastics and similar compounders are scaling proprietary twin-screw compounding lines to serve agricultural mulch film and carrier bag segments. The technology is compressing conventional polyethylene volumes in export-oriented production while domestic retail channels lag in price acceptance.
Vietnam's Ministry of Natural Resources and Environment is tightening enforcement of Decree 08/2022/ND-CP plastic waste classification rules. Provincial environmental departments are mandating industrial-zone processors to segregate multi-material scrap streams. Food-contact film extruders in Bac Ninh and Hung Yen provinces are investing in closed-loop grinding systems to maintain operating permits.
Japanese trading houses are consolidating procurement authority for Vietnamese-sourced packaging films. Mitsui and Sojitz representatives now specify migration-tested grades and certificate-of-analysis documentation at contract negotiation, displacing spot-market purchasing through Ho Chi Minh City distributors. This concentration is most visible in seafood export supply chains serving Tokyo and Osaka retail networks.
Vietnam Plastics Market Segmentation
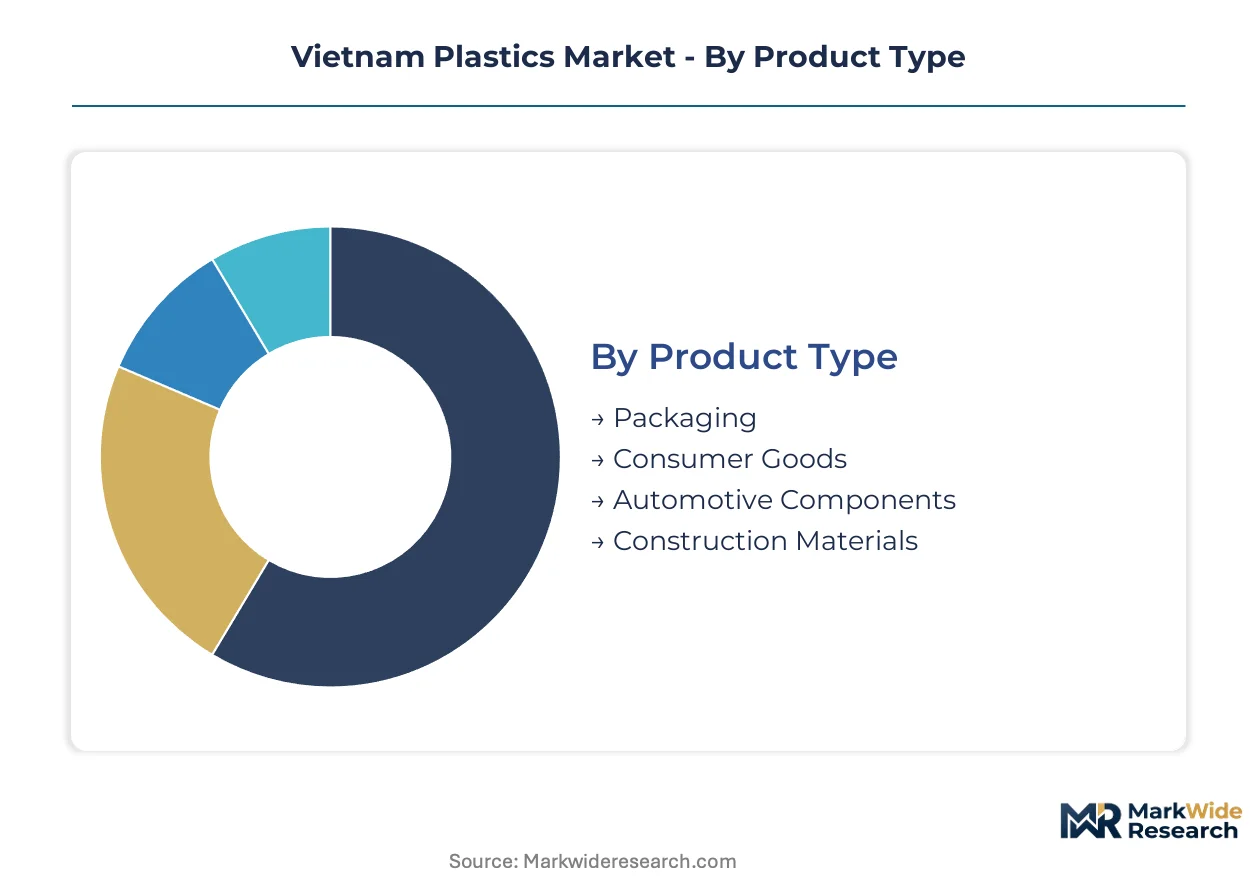
Segmentation in Vietnam's plastics market reveals how resin formulations and processing technologies align with distinct procurement channels. Understanding these flows exposes where margin compression concentrates and where bioplastic substitution offers escape velocity from commodity pricing.
Product Type:
Channel-mix dynamics show packaging flowing predominantly through export-oriented converters near Hai Phong, while construction materials serve domestic distributors in Ho Chi Minh City and Hanoi.
- Packaging:Multi-layer barrier films and thermoformed containers dominate resin throughput. Cold-chain modernization for seafood and tropical fruit exports is pulling investment into high-clarity polyethylene grades across the Red River Delta processing cluster.
- Automotive Components:Polypropylene compounds for interior panels and under-hood applications are gaining share fastest. VinFast's supplier localization program is qualifying Vietnamese molders for direct OEM supply contracts.
- Consumer Goods:Injection-molded household articles serve mass retail channels with price-sensitive specifications. Domestic distributors in urban centers drive volume through high-turnover SKUs.
- Construction Materials:PVC profiles and piping maintain mature demand tied to residential development cycles. Infrastructure project timelines create lumpy procurement patterns for extrusion-grade compounds.
By volume, Packaging leads. By growth pace, Automotive Components is climbing the fastest.
Application:
Application segments stratify by regulatory intensity, with food-contact and medical grades commanding certification premiums over industrial and household specifications.
- Food Packaging:Migration-tested polyethylene films capture the largest export revenue pool. QCVN 07:2009/BTNMT compliance is now mandatory for Japanese and South Korean retail channel access.
- Electronic Components:Flame-retardant ABS and polycarbonate blends serve assembly operations for consumer electronics. Precision molding tolerances favor compounders with ISO 9001:2015 certification.
- Medical Supplies:Sterile barrier films and disposable device housings require cleanroom extrusion capabilities. Domestic hospital procurement is expanding as healthcare infrastructure modernizes.
- Household Items:Commodity polypropylene for storage containers and kitchenware faces intense price competition from Thai and Chinese imports.
Food Packaging generates the highest unit margins. Electronic Components shows the steepest expansion trajectory as manufacturing parks diversify beyond textiles.
Material:
Material selection maps directly to end-use performance requirements, with polyolefins capturing flexible packaging and PVC defending construction applications against metal substitution.
- Polyethylene:Linear low-density and high-density grades form the backbone of export film production. Biodegradable alloy development is compressing conventional volumes in agricultural mulch segments.
- Polypropylene:Homopolymer and copolymer compounds are displacing ABS in automotive interior applications. Compounding capacity near Hai Phong is expanding to serve VinFast localization.
- PVC:Rigid and plasticized formulations maintain entrenched positions in window profiles and cable insulation. Decree 08/2022/ND-CP waste classification rules are pressuring processors to invest in closed-loop recycling.
- Polystyrene:Expandable grades for protective packaging face substitution pressure from molded pulp alternatives. General-purpose crystal grades serve disposable cutlery and retail display applications.
Polyethylene dominates tonnage. Polypropylene is gaining share fastest through automotive qualification programs.
End User:
End-user concentration determines payment terms and technical service intensity, with exporters demanding certificate-of-analysis documentation and domestic retailers prioritizing inventory flexibility.
- Exporters:Seafood and agricultural product packagers specify migration-tested grades with full traceability documentation. Japanese trading houses now consolidate procurement authority through direct mill relationships.
- Manufacturers:Tier-one automotive suppliers and appliance assemblers drive compound customization requirements. Technical collaboration with resin producers shapes formulation development roadmaps.
- Retailers:Modern trade chains and e-commerce platforms source private-label packaging through Ho Chi Minh City distributors. Volume commitments negotiate preferential pricing tiers.
- Wholesalers:Traditional trade channels in provincial markets distribute commodity grades with minimal technical support. Price transparency from Chinese import competition compresses trading margins.
Exporters command the most demanding specifications. Retailers are expanding volume fastest as organized retail penetration deepens in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented compounders cluster near deepwater ports where Japanese and South Korean buyers consolidate procurement. Domestic distributors serve construction and household segments through Ho Chi Minh City and Hanoi trading networks.
Red River Delta
Hai Phong port facilities anchor integrated resin-to-product operations serving seafood and agricultural exporters. Vietnam's Ministry of Natural Resources and Environment enforces Decree 08/2022/ND-CP waste classification rules across Bac Ninh and Hung Yen industrial zones. Compounding capacity for automotive-grade polypropylene is expanding near VinFast supplier qualification programs.
Southeast Region
Ho Chi Minh City manufacturing parks concentrate injection molders for consumer electronics and household goods. The General Department of Vietnam Customs applies import tariff schedules shaping resin sourcing economics for domestic compounders. Bien Hoa and Dong Nai provinces host film extrusion investments targeting retail packaging for modern trade chains.
Mekong Delta
Rice and aquaculture exporters drive demand for flexible packaging in Can Tho and surrounding provinces. Provincial environmental departments mandate industrial-zone processors to segregate multi-material scrap streams under tightening circular economy enforcement. First-mover positioning opportunities exist for integrated film extrusion investments lacking established resin-to-product infrastructure.
Central Coast
Da Nang and Quang Nam provinces process seafood exports through modernized cold-chain logistics corridors. QCVN 07:2009/BTNMT compliance requirements for food-contact applications shape formulation choices among coastal film extruders. Japanese trading houses now specify migration-tested grades with certificate-of-analysis documentation at contract negotiation.
Vietnam Plastics Market Competitive Landscape
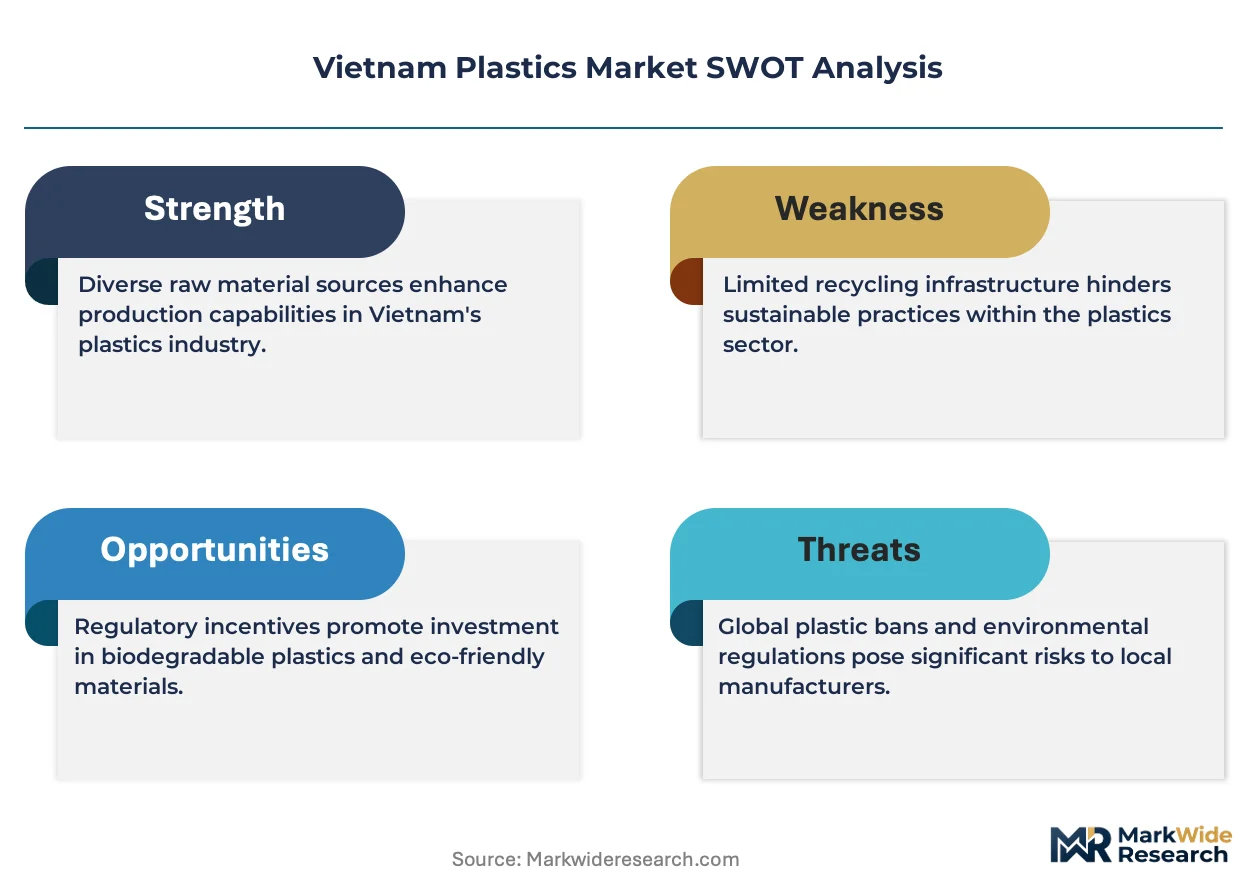
Player mix skews toward integrated compounders with captive resin conversion and export certification capabilities. Tiered specialization separates masterbatch formulators from film extruders and automotive-grade molders. Strategic archetypes include port-proximate exporters serving Japanese procurement networks, bioplastic specialists with proprietary starch-alloy formulations, and color concentrate producers supplying northern processing clusters. Dominant competitive moves center on compounding capacity expansion near Hai Phong and formulation licensing for biodegradable feedstock transitions.
Among Vietnamese-based compounders, Haplast Group and An Phat Bioplastics occupy positions reflecting divergent specialization vectors. Haplast Group exemplifies integrated film extrusion and printing operations sustaining margin control across agricultural and industrial packaging grades. An Phat Bioplastics anchors the bioplastic archetype through proprietary starch-blend formulation capabilities and PBAT compounding capacity. EuroPlas represents the masterbatch specialization tier, supplying color and additive concentrates throughout northern Vietnam's processing cluster without captive film or molding operations.
| Leading Market Players |
|---|
| Haplast Group |
| Polifilm Vietnam Co. Ltd |
| An Phat Bioplastics |
| Duy Tân Plastics |
| EuroPlas |
| Rang Dong Long An Plastic JSC |
| IFC Plastic Co. Ltd |
| Hanpak Vietnam |
| K-Packings |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates at Hai Phong port-proximate compounders establish price floors that smaller Mekong Delta converters cannot match, concentrating margin pressure on inland processors while export-oriented molders defend premium tiers through ISO 9001:2015 certification.
Pricing Analysis
Cost-plus contracts with naphtha indexation dominate resin procurement for Vietnamese compounders, with price differentiation resting on migration-testing certification for food-contact grades and volume scale in masterbatch supply. Pricing pressure intensifies in commodity polyethylene film segments as Thai and Chinese imports compress trading margins. Domestic retailers exhibit highest price sensitivity, while Japanese trading houses prioritize certificate-of-analysis documentation over unit cost.
Supply Chain Analysis
Singapore and South Korea supply naphtha-derived base resins to Vietnamese compounders, who draw from Chinese petrochemical complexes for PBAT biodegradable feedstocks. Single-source vulnerability concentrates in PBAT resin supply, with distribution running through Ho Chi Minh City distributors for domestic retail channels and direct mill relationships for export-oriented buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 laboratory scarcity and eighteen-month compounding equipment lead times create structural bottlenecks that advantage early movers in certification investment and capacity planning.
For Market Incumbents: Secure backward integration into PBAT-starch compounding capacity before equipment lead times extend further, and anchor port-proximate positions near Hai Phong against Mekong Delta challengers. VinFast supplier localization programs threaten margin capture by automotive-grade specialists, making ISO 9001:2015 certification maintenance essential for Japanese and South Korean buyer retention. For New Entrants and Emerging Players: Reverse-logistics service gaps in post-consumer collection systems offer white-space positioning ahead of extended producer responsibility legislation. Target Can Tho and surrounding Mekong Delta provinces for film extrusion investments serving rice and aquaculture packaging, leveraging first-mover absence of integrated resin-to-product infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with proprietary starch-alloy formulation capabilities and captive PBAT compounding capacity. Long-term viability hinges on bioplastic substitution momentum against conventional polyethylene volumes. Watch draft extended producer responsibility legislation passage as inflection indicator for reverse-logistics service revenue potential.| Strategic Initiative | Industry Significance |
|---|---|
| PBAT-Starch Compounding Capacity Expansion | Proprietary twin-screw lines serve agricultural mulch film demand under Decree 08/2022/ND-CP compliance pressure. |
| ISO 17025 Laboratory Investment | In-house migration testing and biodegradability certification compress four-to-six month product launch timelines. |
| Port-Proximate Resin-to-Product Integration | Hai Phong facilities reduce freight exposure and qualify for direct Japanese trading house procurement relationships. |
| Reverse-Logistics Capability Buildout | Post-consumer collection systems position compounders for extended producer responsibility service revenue streams. |
| Masterbatch-3D Printing Convergence | Filament-grade compound formulation captures emerging industrial prototyping demand in Ho Chi Minh City manufacturing parks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured interviews with resin compounders, film extrusion plant managers, Japanese trading house procurement leads, and Vietnam's Ministry of Natural Resources and Environment enforcement officers. Secondary validation drew from customs import records, Decree 08/2022/ND-CP regulatory filings, QCVN 07:2009/BTNMT technical standards, and SEC disclosures from multinational resin producers. Bottom-up capacity assessments and top-down demand modeling were triangulated.
Across the analysis window, forecasts reflect segmentation by product type, application, material chemistry, and end-user procurement channel, with CAGRs derived from regression analysis against automotive production volumes, cold-chain infrastructure investment, and bioplastic substitution elasticities. Key inputs include VinFast supplier localization timelines and Hai Phong port throughput capacity expansion.
Forecasts assume regulatory continuity in Vietnam's Ministry of Natural Resources and Environment enforcement and General Department of Vietnam Customs tariff schedules; material policy shifts in extended producer responsibility legislation or naphtha import duties would require re-modeling. Recalibration cycles align with material shifts in biodegradable formulation adoption rates and Japanese trading house procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Recycled Polyethylene Terephthalate (Rpet) Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Engineering Plastic Recycling Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Industrial Plastic Market
Recycled Plastics
Graphite Recycling Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Global Post-Consumer Recycled Plastics Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
North America Plastic Recycling Market
Recycled Plastics
Europe Recycled Plastics Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
USA Plastic-To-Fuel Market