
 Microplastic Recycling Market | 2026-2036
Microplastic Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Microplastic Recycling Market Analytics
REACH compliance is expanding the cost-of-entry calculus for microplastic recyclers entering European value chains. Carbios leverages enzymatic depolymerization R&D to anchor its position in polyester microplastic recovery. PureCycle Technologies dominates solvent-based purification for polypropylene streams. Ioniqa Technologies specializes in magnetic catalyst separation for colored microplastic feedstocks.
Microplastic recycling encompasses the collection, sorting, and reprocessing of synthetic polymer fragments under five millimeters recovered from industrial effluent, wastewater treatment sludge, and environmental remediation sites. Thermal and chemical processes restore these degraded polymers to virgin-equivalent molecular weight for reintegration into durable goods manufacturing. Mechanical processing leads the recycling method segment due to lower capital intensity, though pyrolysis commands margin pools where mixed-waste streams defy conventional sorting. Polyethylene dominates material type volumes given its prevalence in packaging microplastics, while upcycling into construction aggregates represents the fastest-expanding application area by value capture.
EMA guidelines on medical device plastics traceability, EPA microbead prohibitions under the Microbead-Free Waters Act, and EU Green Deal circular economy action plan enforcement collectively reshape product standards and market access protocols. ECHA restriction proposals on intentionally added microplastics further tighten compliance timelines for consumer goods and cosmetics feedstock suppliers. Stakeholders must monitor regulatory divergence between European hazard-classification frameworks and North American polymer-exemption thresholds when configuring cross-border recycling investments.
Market Dynamics
EU Green Deal circularity mandates are compressing compliance timelines while enzymatic depolymerization R&D rewrites cost structures for polyester microplastic recovery. Mechanical recycling clusters around Cologne and Rotterdam's chemical processing hubs concentrate supply-side capacity.
Growth Catalysts
- REACH compliance expansion:ECHA restriction proposals on intentionally added microplastics tighten feedstock sourcing protocols for cosmetics and consumer goods suppliers.
- Construction aggregate upcycling:Polyethylene microplastics diverted from packaging waste streams now supply durable infrastructure materials with virgin-equivalent performance specifications.
- Rotterdam port complex proximity:Chemical processing hubs co-located with Europe's largest seaport reduce feedstock logistics costs for imported mixed-polymer streams.
Market Restraints
- Feedstock heterogeneity:Mixed-waste streams containing polypropylene, polyethylene, and polystyrene fragments defy conventional density-based sorting without solvent-based purification.
- Capital intensity threshold:Pyrolysis units for thermal depolymerization require front-loaded capex commitments that exclude sub-scale operators from margin pools.
- Regulatory divergence friction:EPA polymer-exemption thresholds under the Microbead-Free Waters Act create classification mismatches with EU hazard frameworks.
Strategic Opportunities
- Germany mechanical recycling clusters:Cologne-centered infrastructure offers co-location synergies for post-industrial microplastic collection and reprocessing.
- Medical device traceability mandates:EMA guidelines on plastics provenance create premium pricing tiers for certified-recycled feedstocks in healthcare applications.
- Magnetic catalyst separation:Ioniqa Technologies' colored microplastic processing methods converge with AI-driven optical sorting to unlock previously unrecoverable pigment-contaminated volumes.
Industry Challenges
- Polymer chemist talent scarcity:Molecular weight restoration expertise for degraded microplastics remains concentrated among legacy petrochemical engineering programs.
- ISO 15270 certification timelines:Third-party validation for plastics recycling quality management extends market entry cycles by twelve to eighteen months.
- Wastewater treatment sludge integration:Legacy municipal infrastructure lacks feedstock pre-processing capacity for microplastic extraction at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microplastic Recycling Market |
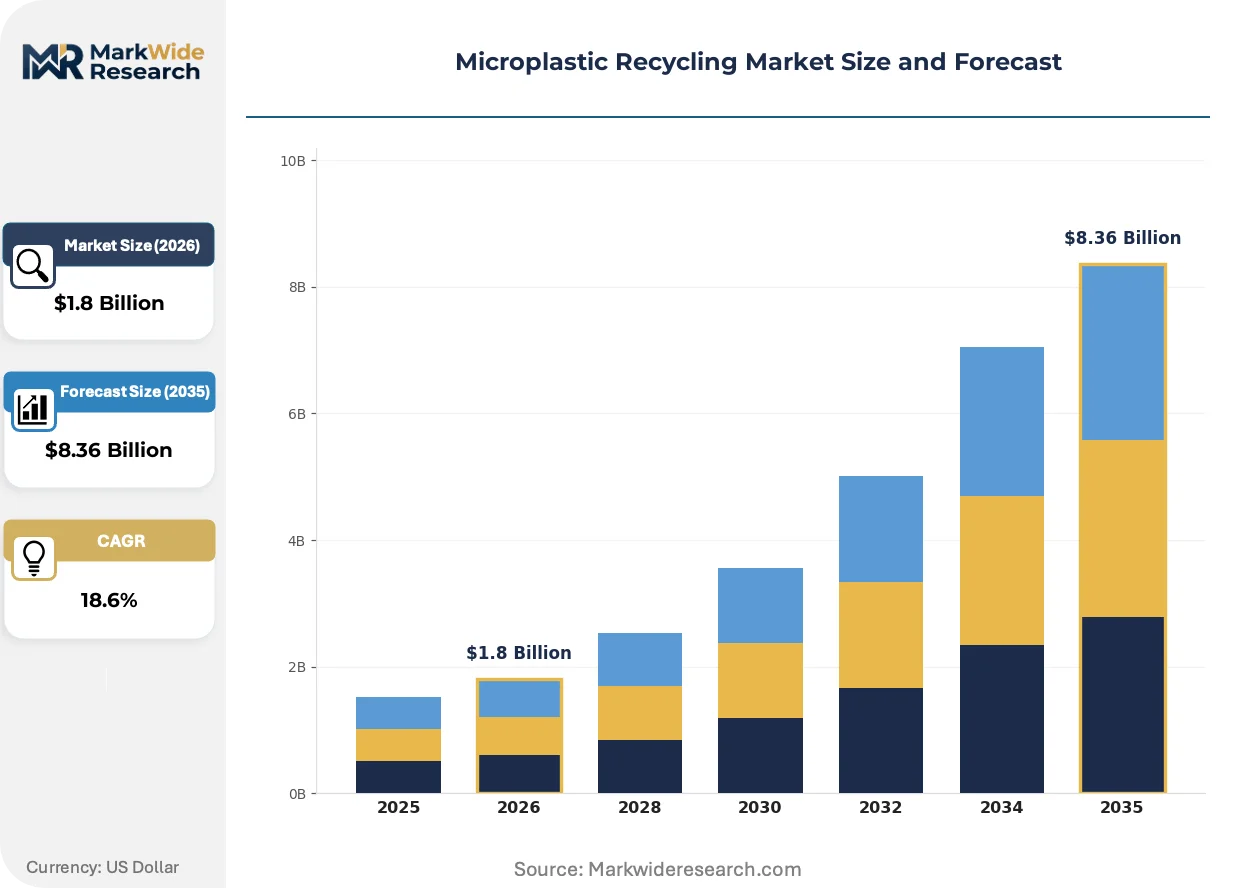
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Recycling Method: Mechanical Processing, Chemical Processing, Pyrolysis, Upcycling Application Area: Textiles, Packaging, Construction, Automotive End User Industry: Consumer Goods, Electronics, Food & Beverage, Pharmaceuticals |
| Companies Covered | Carbios, PureCycle Technologies, Ioniqa Technologies, Calyxia, Polygonesystems, PlanetCare, ECOFARIO, Ocean Diagnostics, OceanWorks International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microplastic Recycling Market Evolving Landscape
Enzymatic and solvent-based purification technologies are compressing the cost gap between virgin and recycled polymer feedstocks. Regulatory frameworks on both sides of the Atlantic are hardening traceability requirements.
Depolymerization catalysts are rewriting the economics of colored and contaminated microplastic streams that mechanical processes cannot valorize. Packaging manufacturers in Germany and the Netherlands are piloting these technologies at demonstration scale. The technology is rewriting competitive positioning by enabling margin capture from previously landfilled mixed-polymer fractions.
REACH restriction proposals on intentionally added microplastics are forcing reformulation across cosmetics, detergents, and agricultural coatings. Industrial consequence includes mandatory supply chain documentation for polymer provenance. Consumer goods manufacturers operating across EU member states are consolidating procurement around pre-certified recycled feedstock suppliers to preempt enforcement gaps.
Certification-driven procurement preferences now separate premium-tier suppliers from commodity recyclers in buyer evaluations. Brand owners in personal care and food packaging are mandating third-party verified recycled content percentages in supplier contracts. This shift concentrates contract volumes with German and Dutch operators holding EMAS registration and ISO 14001 environmental management certification.
Microplastic Recycling Market Segmentation
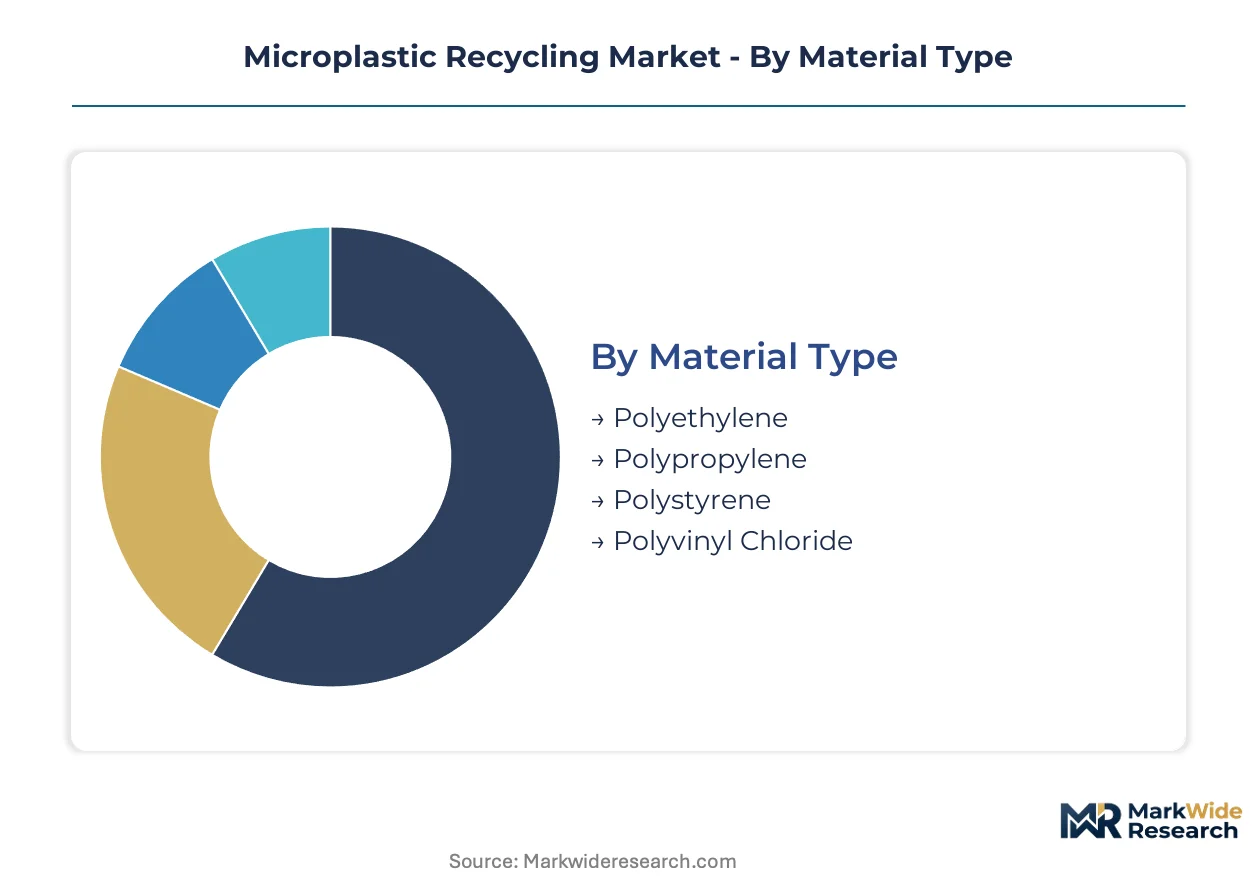
Segmentation in microplastic recycling reveals how feedstock chemistry, processing economics, and end-use specifications intersect to determine value capture. Material type and recycling method together dictate capital deployment patterns across European supply chains. Application-driven demand fragmentation creates distinct procurement tiers for certified versus commodity-grade output.
Material Type:
Polyethylene concentrates feedstock flows through Cologne mechanical recycling clusters and Rotterdam chemical processing corridors.
- Polyethylene:Dominant packaging-derived microplastic stream with established density-based sorting infrastructure. Demand concentrates in German construction aggregate applications where REACH-compliant provenance commands premium contract terms.
- Polypropylene:Higher melting point enables thermal reprocessing with virgin-equivalent molecular weight restoration. Solvent-based purification demand clusters around PureCycle Technologies' Dutch operations serving automotive interior specifications.
- Polystyrene:Brittle fragmentation from consumer electronics casing requires specialized depolymerization catalysts. Food & Beverage packaging bans under EU Single-Use Plastics Directive constrain feedstock availability.
- Polyvinyl Chloride:Chlorine content demands thermal processing with acid gas scrubbing systems. Pharmaceutical blister pack recovery remains nascent due to EMA traceability documentation gaps.
Today's leader: Polyethylene. Tomorrow's challenger: Polypropylene.
Recycling Method:
Capital intensity tiers separate incumbent mechanical operators from emerging chemical technology platforms.
- Mechanical Processing:Lower capex threshold enables mid-scale entry with shredding, washing, and extrusion sequences. Cologne-centered clusters exploit post-industrial film scrap proximity for margin defense.
- Chemical Processing:Solvent purification and enzymatic depolymerization restore degraded polymers to monomer purity. Carbios anchors polyester recovery R&D with demonstration-scale units near Toulouse.
- Pyrolysis:Thermal cracking of mixed-polymer streams yields synthetic fuel intermediates. Front-loaded reactor investments exclude sub-scale participants from margin pools.
- Upcycling:Diverts microplastics into construction aggregates and composite materials with performance specifications exceeding virgin alternatives. German infrastructure projects drive specification-grade procurement.
Mechanical processing retains volume dominance. Chemical platforms gain share fastest.
Application Area:
End-use performance requirements stratify procurement into specification-grade and commodity tiers.
- Textiles:Fiber-grade recycled microplastics require controlled viscosity for spinning consistency. Dutch technical textile manufacturers pilot enzymatic polyester recovery for workwear applications.
- Packaging:Food-contact compliance demands EFSA migration testing for recycled content thresholds. Brand owners consolidate procurement around EMAS-registered German suppliers.
- Construction:Infrastructure aggregate specifications now incorporate polyethylene microplastic binders. German federal procurement guidelines favor certified-recycled content in public works.
- Automotive:Interior trim specifications drive polypropylene purity requirements. OEMs mandate ISO 15270-certified recycling quality management for tier-one suppliers.
Packaging commands current procurement volumes. Construction aggregates show steepest expansion trajectory.
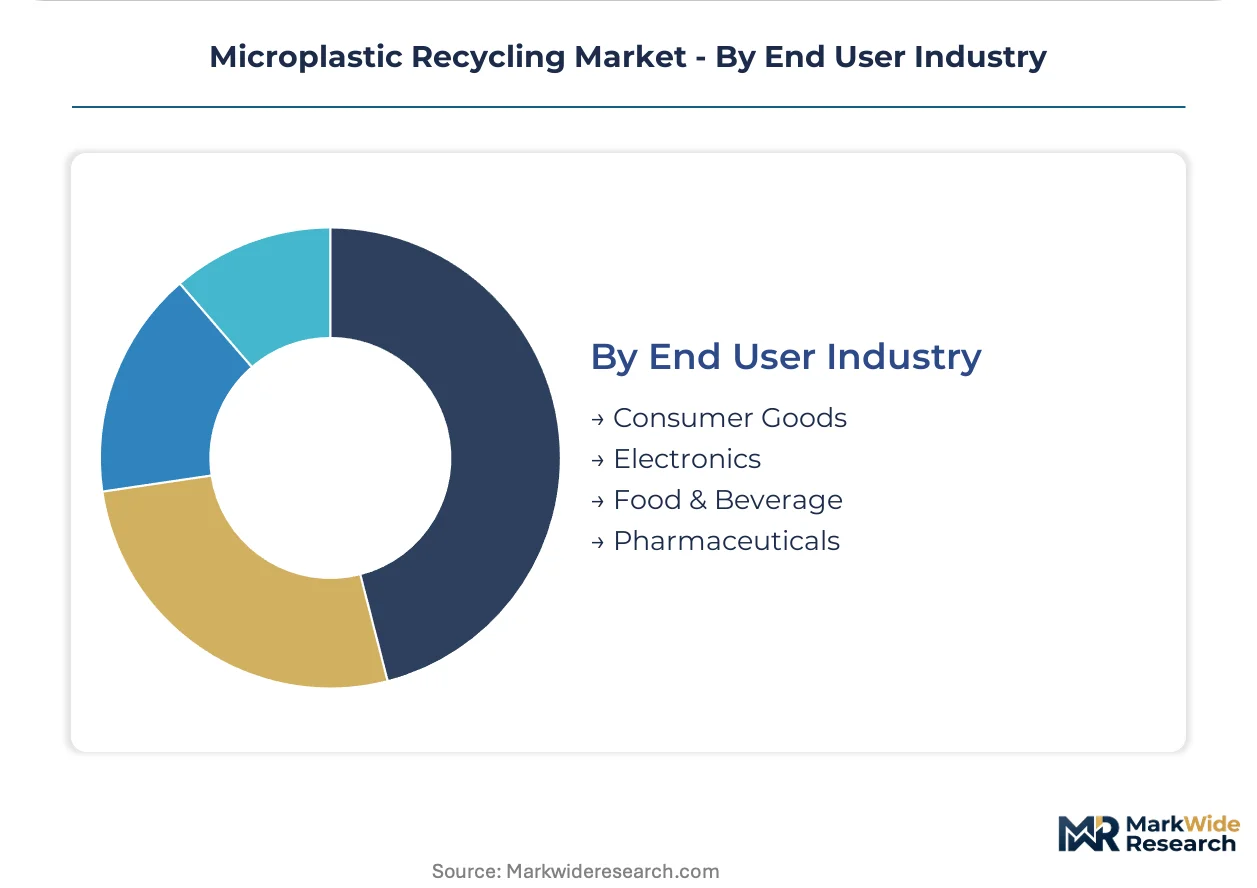
End User Industry:
Regulatory compliance intensity varies sharply across sectoral procurement mandates.
- Consumer Goods:Cosmetics reformulation under ECHA restriction proposals eliminates intentionally added microplastics. Detergent manufacturers pivot to biodegradable alternatives.
- Electronics:WEEE directive enforcement expands post-consumer plastic recovery obligations. Polystyrene housing fragmentation from e-waste streams supplies specialized recyclers.
- Food & Beverage:Single-use plastics bans constrain feedstock availability while creating demand for certified-recycled alternatives. EFSA safety assessments extend qualification timelines.
- Pharmaceuticals:EMA medical device plastics traceability guidelines create premium tiers for documented provenance. Blister pack PVC recovery remains underdeveloped.
Consumer Goods leads regulatory-driven procurement. Pharmaceuticals offers untapped premium pricing potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer chemist talent pools concentrate in Germany's Rhine-Ruhr corridor and the Netherlands' Randstad region, anchoring Europe's microplastic recycling infrastructure development. These workforce clusters support enzymatic depolymerization R&D and solvent-based purification scale-up.
Germany
Mechanical recycling clusters around Cologne exploit post-industrial film scrap proximity for margin defense. EU Green Deal circularity mandates compress compliance timelines for packaging manufacturers. North Rhine-Westphalia's chemical processing infrastructure integrates with Rotterdam port logistics for imported mixed-polymer feedstock handling.
Netherlands
Rotterdam's port complex reduces logistics costs for chemical processing hubs importing contaminated microplastic streams. ECHA restriction proposals on intentionally added microplastics tighten sourcing protocols for cosmetics suppliers. Eindhoven-region technical textile manufacturers pilot enzymatic polyester recovery for workwear applications.
France
Toulouse anchors enzymatic depolymerization R&D demonstration units for polyester microplastic recovery. REACH compliance expansion raises cost-of-entry barriers for recyclers entering European value chains. Auvergne-Rhône-Alpes specialty chemical infrastructure supports catalyst development for colored feedstock processing.
United Kingdom
Post-Brexit regulatory divergence creates classification friction with EU hazard frameworks for cross-border recycling investments. Environment Agency enforcement of microplastic discharge limits drives industrial effluent collection infrastructure. Midlands-based automotive suppliers demand ISO 15270-certified recycled polypropylene for interior trim specifications.
Belgium
Antwerp's petrochemical corridor offers feedstock integration synergies for pyrolysis operators processing mixed-waste streams. EFSA migration testing requirements extend food-contact recycled content qualification timelines. Flanders-based packaging converters consolidate procurement around EMAS-registered suppliers with documented polymer provenance.
Microplastic Recycling Market Competitive Landscape
The competitive structure tilts toward technology-differentiated specialists rather than scale-driven commodity processors. Capital intensity thresholds exclude sub-scale operators from pyrolysis margin pools, concentrating thermal processing among well-capitalized entrants. Three archetypes dominate: enzymatic depolymerization R&D anchors, solvent-based purification platforms, and mechanical recycling cluster operators. Capacity expansion and strategic technology licensing represent the dominant competitive moves as players position for EU Green Deal enforcement timelines.
Within the enzymatic technology tier, Carbios exemplifies R&D-anchored competitive positioning through its Toulouse demonstration infrastructure. PureCycle Technologies and Ioniqa Technologies occupy complementary positions in solvent-based and magnetic catalyst separation domains respectively. These three entities represent the technology-forward archetype that is compressing the cost gap between virgin and recycled polymer feedstocks across European supply chains.
| Leading Market Players |
|---|
| Carbios |
| PureCycle Technologies |
| Ioniqa Technologies |
| Calyxia |
| Polygonesystems |
| PlanetCare |
| ECOFARIO |
| Ocean Diagnostics |
| OceanWorks International |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EMAS-registered German operators and commodity recyclers manifests in both contract premiums and feedstock sourcing configurations. Buyers consolidate procurement around documented polymer provenance while suppliers absorb REACH compliance costs through selective geographic clustering.
Pricing Analysis
Bundled certification-plus-feedstock contracts command premiums over unbundled commodity spot transactions. Three-tier pricing structure across EMAS-certified, ISO 14001-compliant, and uncertified grades reflects buyer procurement consolidation. Price differentiation hinges on REACH documentation completeness and EFSA migration testing status. Cost compression in mechanical processing tiers is intensifying because Cologne-centered clusters defend margin position through post-industrial scrap proximity.
Supply Chain Analysis
Polymer chemist scarcity in Germany's Rhine-Ruhr corridor and the Netherlands' Randstad region constrains chemical processing scale-up. Feedstock flows concentrate in Germany, the Netherlands, and Belgium through Rotterdam port integration. Raw material dependencies include post-industrial film scrap, wastewater treatment sludge, and imported mixed-polymer streams. Single-source vulnerability runs through enzymatic catalyst supply chains anchored in French R&D corridors. Distribution runs through EMAS-registered converter networks serving automotive and packaging OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory enforcement cascades. EU Green Deal circularity mandates compress compliance timelines and consolidate procurement around pre-certified suppliers.
For Market Incumbents: Lock in feedstock agreements with Cologne mechanical recycling clusters before capacity constraints harden. Deepen backward integration into wastewater treatment sludge pre-processing to defend margin position against pyrolysis entrants. Prioritize EMAS registration maintenance as brand owners mandate third-party verified recycled content percentages.
For New Entrants and Emerging Players: Begin with pharmaceutical blister pack PVC recovery where EMA traceability documentation gaps leave supply underserved. Target construction aggregate upcycling in German federal procurement corridors where certified-recycled content mandates create specification-grade demand. Pursue technology licensing partnerships with enzymatic depolymerization R&D anchors rather than greenfield reactor investments.
For Investors and Strategic Acquirers: Consolidation pressure builds where solvent-based purification platforms lack feedstock integration with Rotterdam port logistics. Five-to-ten-year viability favors technology-differentiated specialists over scale-driven commodity processors. Watch for ECHA restriction proposal enforcement gaps as the inflection signal triggering accelerated M&A in cosmetics feedstock reformulation.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Depolymerization Scale-Up | Carbios anchors polyester recovery R&D through Toulouse demonstration infrastructure. |
| Solvent-Based Purification Expansion | PureCycle Technologies concentrates polypropylene purity capacity near Rotterdam port complex. |
| Magnetic Catalyst Separation Deployment | Ioniqa Technologies unlocks pigment-contaminated volumes through AI-driven optical sorting convergence. |
| EMAS Registration Consolidation | German packaging converters defend contract volumes through documented environmental management certification. |
| Wastewater Sludge Pre-Processing Integration | Municipal infrastructure partnerships enable microplastic extraction at environmental remediation scale. |
Research Methodology
Multiple input streams — primary interviews with polymer chemists and procurement leads, secondary validation through ECHA regulatory filings and EU customs data, and technical R&D disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder roles included mechanical recycling plant managers, chemical processing hub operators, cosmetics formulation scientists, automotive tier-one procurement directors, and municipal wastewater treatment engineers. Secondary sources encompassed REACH restriction proposal documentation, EMAS registration databases, ISO 15270 certification records, and European plastics trade flow statistics.
Historical capacity deployment patterns were cross-referenced against expert panel assessments of enzymatic technology cost curves across the analysis window. Segmentation dimensions modeled include material type chemistry, recycling method capital intensity tiers, application area performance specifications, and end-use industry regulatory compliance intensity. CAGRs were derived through iterative convergence of feedstock availability projections and end-demand elasticity estimates. Industry-specific inputs incorporated ECHA enforcement timeline probabilities and EFSA migration testing backlog assumptions.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments, breakthrough catalyst discoveries, and macroeconomic disruptions to construction sector demand. Forecasts reflect documented assumptions about REACH implementation pacing and EU Green Deal funding allocation. Material deviation in ECHA restriction enforcement or enzymatic depolymerization cost breakthroughs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Recycled PET Flakes Market
Recycled Plastics
Malaysia Plastics Market
Recycled Plastics
Americas Plastic Sheets Market
Recycled Plastics
Vietnam Plastics Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Plastic Ignition Holders Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Recycled Polypropylene Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Vietnam Recycling Market
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Recycled Leather Market