
 Recycled Polyethylene Terephthalate (Rpet) Market | 2026-2036
Recycled Polyethylene Terephthalate (Rpet) Market Size, Share, and Industry Trends Forecast 2026-2036
Recycled Polyethylene Terephthalate (Rpet) Market Intelligence
Consolidation among major consumer packaged goods companies is decoupling R-PET procurement from volatile spot market pricing. This shift favors large-scale producers with consistent, high-quality output capable of fulfilling long-term offtake agreements. Indorama Ventures Public Ltd. leverages its global manufacturing footprint to secure these large contracts. Alpek competes on integrated feedstock supply, while Clear Path Recycling LLC specializes in high-purity grades for specific food-contact packaging applications.
Recycled polyethylene terephthalate is a polymer produced by mechanically or chemically processing post-consumer PET waste, primarily from beverage bottles. Its quality is often defined by Intrinsic Viscosity (IV) and color, which determine its suitability for reuse in demanding applications. The material serves as a substitute for virgin resin in manufacturing, reducing fossil fuel dependency. Bottle-grade R-PET for packaging applications commands premium pricing due to stringent purity requirements, while the fiber segment for textiles represents a high-volume but more commoditized outlet.
Regulatory frameworks are a primary market catalyst, with the EU's Green Deal mandating recycled content in plastic bottles. In the United States, the FDA sets strict guidelines for food-contact grade R-PET, influencing processing technology choices. Concurrently, China's MEE policies on solid waste management and recycling promotion shape regional supply-demand dynamics. Securing consistent, high-quality feedstock remains the central strategic challenge for producers aiming for growth in high-value segments.
Market Dynamics
The central structural force shaping the market is the codification of circular economy principles into binding regulations. Mandates for minimum recycled content in packaging are creating non-negotiable, structural demand that decouples a significant portion of R-PET value from virgin resin price fluctuations.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and similar state-level legislation in the United States create compulsory demand for R-PET by setting recycled content targets for beverage bottles and other packaging.
- Brand Owner Commitments:Major consumer packaged goods companies are publicly pledging to increase recycled material use in their packaging to meet corporate sustainability goals and appeal to environmentally conscious consumers.
- Collection Infrastructure:Advanced waste collection and sorting systems in countries like Germany and Japan provide a consistent and relatively clean stream of post-consumer PET, enabling higher-quality R-PET production.
Market Restraints
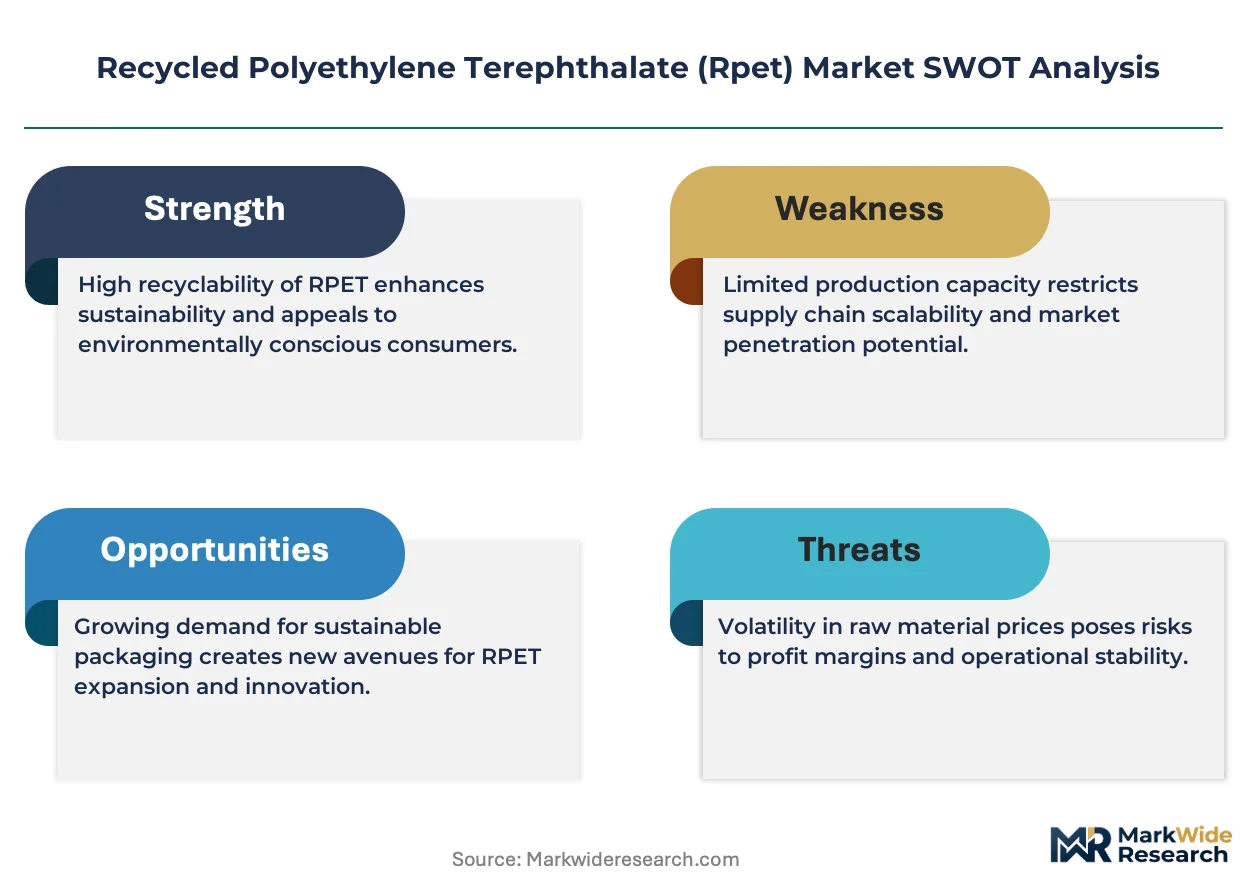
- Feedstock Quality and Cost:The supply of post-consumer PET bales is often contaminated with other plastics, colors, and residues, which increases processing costs and limits the yield of high-quality, food-grade R-PET.
- Polymer Degradation:Mechanical recycling causes thermal and hydrolytic degradation, reducing the intrinsic viscosity (IV) of the PET polymer with each cycle, which can make it unsuitable for demanding applications like carbonated beverage bottles. *
- Substitution by Virgin PET:When crude oil prices are low, the cost of virgin PET can fall below that of high-quality R-PET, creating economic pressure on recyclers and incentivizing brand owners to switch back to virgin material.
Strategic Opportunities
- Chemical Recycling Technologies:Advanced recycling processes like glycolysis and methanolysis can break down PET waste into its constituent monomers, allowing for the creation of virgin-quality polymer from low-quality or difficult-to-recycle feedstock.
- High-Value Non-Packaging Applications:Expanding use in durable goods such as automotive interiors, industrial strapping, and construction materials offers new, high-performance outlets beyond the traditional bottle and fiber segments.
- Infrastructure Development in Emerging Economies:Investing in collection and sorting infrastructure in regions like Southeast Asia and Latin America can unlock vast, untapped sources of post-consumer PET feedstock for the market.
Industry Challenges
- Capital Investment Hurdles:The construction of food-grade mechanical recycling plants and advanced chemical recycling facilities requires significant upfront capital expenditure, posing a barrier to entry for smaller operators.
- Lack of Bale Standardization:Inconsistent quality and sorting standards for post-consumer PET bales across different regions and municipalities create operational inefficiencies and yield variability for recycling processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recycled Polyethylene Terephthalate (Rpet) Market |
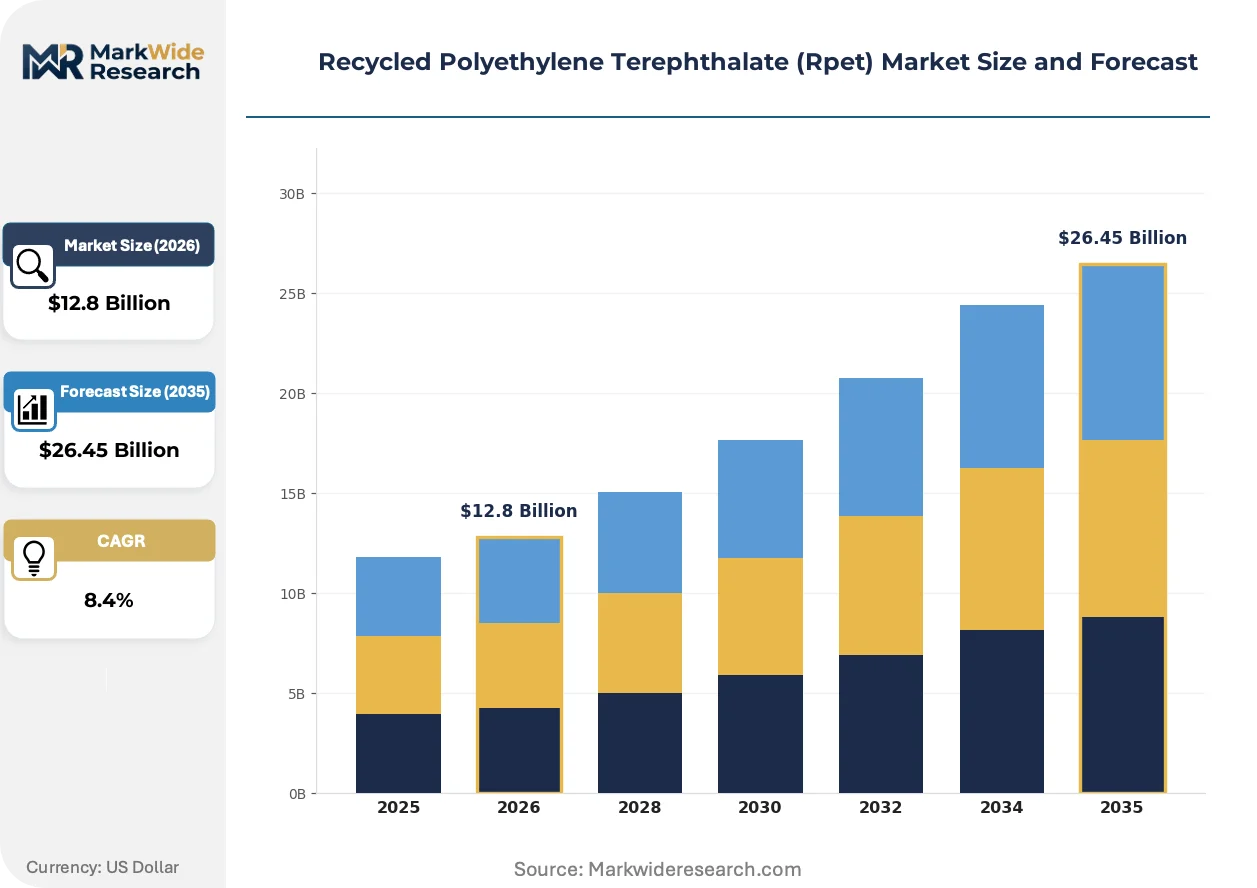
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Film, Fiber, Bottles Application: Packing, Textiles, Consumer Goods, Automotive End User: Manufacturers, Retailers, Distributors, OEMs Distribution Channel: Online, Retail, Direct Sales, Wholesalers |
| Companies Covered | Indorama Ventures Public Ltd., Placon, Clear Path Recycling LLC, Verdeco Recycling, Inc., Alpek, Evergreen Plastics, Inc., Phoenix Technologies, PolyQuest, Zhejiang Anshun Pettechs Fibre Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recycled Polyethylene Terephthalate (Rpet) Market Strategic Shifts & Innovations
Technological advancements in sorting and purification are unlocking new feedstock streams, while procurement models are evolving to secure supply. The market is shifting from a focus on simple waste diversion to creating a resilient, quality-driven supply chain for circular polymers.
Advanced sorting systems using artificial intelligence and robotics are a key product evolution. These technologies identify and separate PET bottles by polymer type, color, and even original brand with high speed and accuracy. Food and beverage packagers are specifying R-PET processed with these systems to ensure purity. This technology is decentralizing feedstock qualification from manual labor to automated, data-driven nodes within the recycling facility.
China's MEE policies on solid waste management are fundamentally altering regional R-PET supply dynamics. The country's strict import bans on plastic waste have forced the development of a sophisticated domestic collection and recycling industry. This shift directly impacts the textile sector, which must now compete with the higher-value bottle-to-bottle segment for a finite pool of locally sourced feedstock.
A notable behavioral shift is the move toward long-term offtake agreements between large CPG companies and R-PET producers. This model replaces volatile spot-market transactions with predictable, multi-year contracts that guarantee supply for the buyer and revenue for the producer. This trend is most visible in North America and Europe, where brands require consistent, food-grade material to meet public sustainability pledges and regulatory mandates.
Recycled Polyethylene Terephthalate (Rpet) Market Segmentation
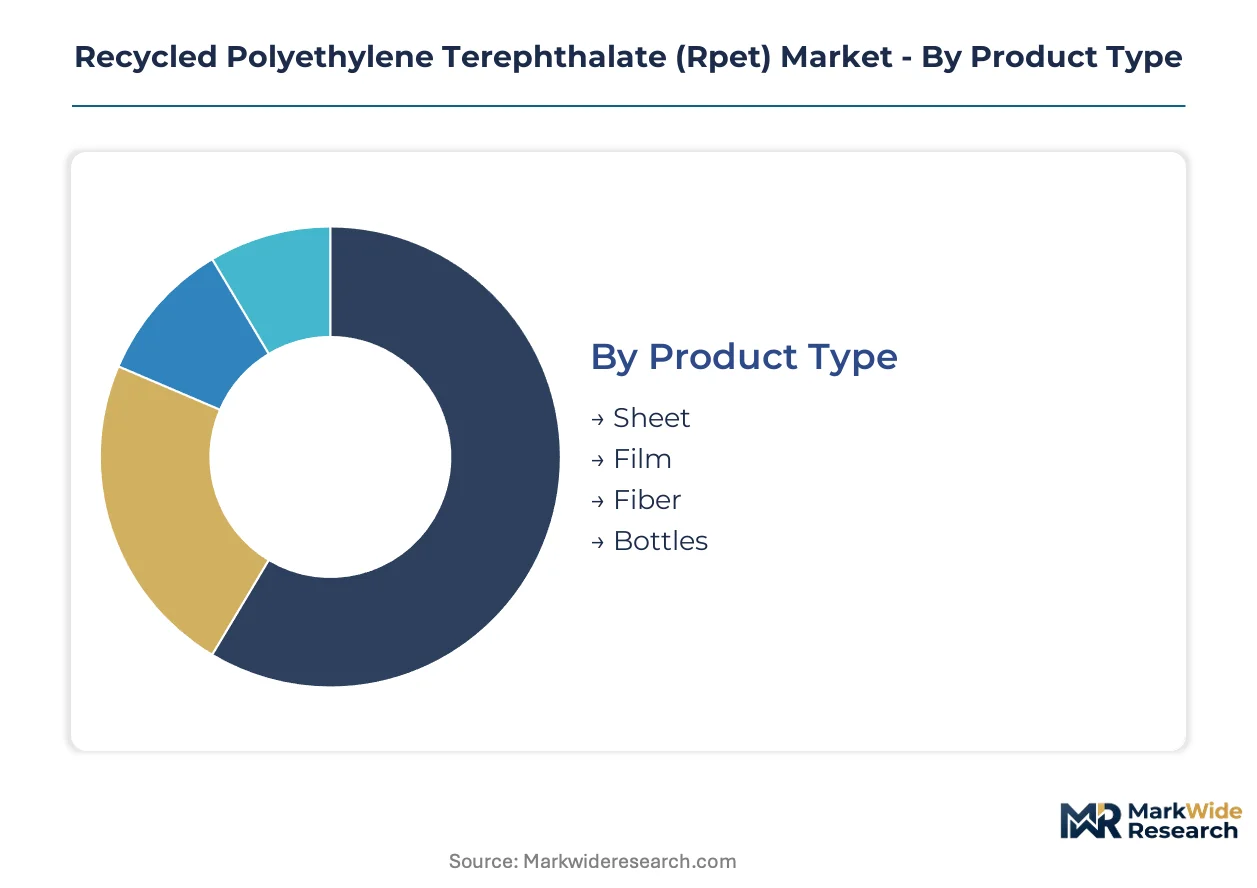
The Recycled Polyethylene Terephthalate (Rpet) market segmentation reflects the diverse forms, applications, and value chain participants driving its expansion. Understanding these distinct segments is crucial for producers to align output with specific market requirements and for buyers to source appropriate material grades.
Product Type:
Buyers prioritize product type based on the specific material properties required for their final applications.
- Bottles:Recycled PET bottles are mechanically or chemically processed to meet stringent purity and intrinsic viscosity (IV) standards. Demand concentrates in the food and beverage packaging sector, driven by regulatory mandates like the EU Green Deal's recycled content targets.
- Fiber:R-PET fiber is produced by extruding recycled PET flakes into filaments for textile and non-woven applications. The textile industry represents a high-volume outlet, though it faces competition from higher-value bottle-to-bottle applications for feedstock.
- Sheet:R-PET sheet is thermoformed into trays and containers for various consumer goods and fresh food packaging.
- Film:R-PET film finds use in flexible packaging, labels, and industrial applications requiring transparency and barrier properties.
Volume sits with Fiber; growth tilts toward Bottles.
Application:
Application segmentation reflects the diverse end-use requirements for R-PET properties.
- Packing:This segment encompasses food and beverage containers, blister packs, and other rigid and flexible packaging solutions. Demand is heavily influenced by brand owner commitments and regulatory pressures for circular packaging in Germany and Japan.
- Textiles:R-PET is processed into polyester fibers for apparel, carpets, and industrial textiles, offering a sustainable alternative to virgin polyester. This application faces feedstock competition from bottle-to-bottle recycling, impacting supply dynamics for manufacturers.
- Consumer Goods:R-PET integrates into various consumer products, including household items, sports equipment, and durable goods.
- Automotive:The automotive sector utilizes R-PET for interior components, floor mats, and non-structural parts, supporting vehicle lightweighting and sustainability goals.
The largest share belongs to Packing; Automotive applications are expanding most quickly.
End User:
End-user categories delineate the primary purchasers and transformers of R-PET materials.
- Manufacturers:These include packaging producers, textile mills, and component fabricators who process R-PET into finished or semi-finished goods. Their procurement is increasingly characterized by long-term offtake agreements to secure consistent supply for their production lines.
- OEMs (Original Equipment Manufacturers):OEMs integrate R-PET components directly into their final products, particularly in the automotive and electronics sectors. They prioritize material specifications and certifications, often requiring high-purity grades for performance and compliance.
- Retailers:Retailers indirectly drive R-PET demand through their private label packaging and sustainability initiatives for store brands.
- Distributors:Distributors act as intermediaries, supplying R-PET resin and flakes to smaller manufacturers and specialized processors.
Manufacturers account for the bulk of consumption; OEMs exhibit a steep expansion trajectory.
Distribution Channel:
Distribution channels reflect the various pathways through which R-PET products reach end-users.
- Direct Sales:Large-scale R-PET producers engage in direct sales to major consumer packaged goods companies and industrial manufacturers. This channel facilitates long-term offtake agreements and customized supply chains for high-volume, consistent material delivery.
- Wholesalers:Wholesalers purchase R-PET in bulk from processors and distribute it to smaller manufacturers, specialized converters, and regional markets. They often manage logistics and inventory for a diverse client base, offering flexibility in procurement.
- Online:Online platforms are emerging for spot market transactions and specialized R-PET grades, connecting buyers and sellers globally.
- Retail:The retail channel is less direct for raw R-PET but influences demand through the sale of products containing recycled content.
Direct Sales captures significant transactional value; Online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's robust waste collection infrastructure anchors the European market for recycled polyethylene terephthalate. This system provides a consistent, high-quality feedstock stream essential for producing bottle-grade R-PET. Similar advancements in other developed economies drive regional market dynamics.
Germany
Germany's packaging sector exhibits strong demand for R-PET, driven by consumer preference for sustainable products. The EU Green Deal mandates specific recycled content targets for plastic bottles, compelling manufacturers to integrate R-PET. The Rhine-Ruhr region, with its established chemical and plastics industry, concentrates significant R-PET processing capacity.
Japanese
Japanese brand owners actively commit to using recycled content, influencing market demand for R-PET. The Ministry of Economy, Trade and Industry (METI) promotes circular economy initiatives, supporting advanced recycling technologies. Major packaging and textile manufacturers in the Tokyo Bay area drive innovation in R-PET applications.
The United States
The United States market for R-PET is increasingly shaped by state-level legislation mandating recycled content in packaging. The FDA sets strict guidelines for food-contact grade R-PET, impacting processing technology choices for producers. The Northeast Corridor and California represent key regions with growing R-PET processing and consumption due to concentrated brand owner activity.
China
China's R-PET market is heavily influenced by the Ministry of Ecology and Environment (MEE) policies on solid waste management and recycling promotion. Strict import bans on plastic waste have fostered a sophisticated domestic collection and recycling industry. The Yangtze River Delta, a major industrial hub, sees significant investment in R-PET production facilities to meet local demand.
Recycled Polyethylene Terephthalate (Rpet) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-purity, food-grade R-PET applications. The market structure favors large-scale producers capable of fulfilling consistent supply agreements. Key strategic archetypes include globally integrated material suppliers, specialized high-purity R-PET manufacturers, and regional processors. Dominant competitive moves involve securing long-term offtake agreements and expanding processing capacity.
Among the large-scale, integrated producers, Indorama Ventures Public Ltd. leverages its global manufacturing footprint to secure significant contracts. Alpek exemplifies a company with integrated feedstock supply, enhancing cost control and material consistency. Clear Path Recycling LLC sits within the specialized segment, focusing on high-purity grades for demanding food-contact packaging applications.
| Leading Market Players |
|---|
| Indorama Ventures Public Ltd. |
| Placon |
| Clear Path Recycling LLC |
| Verdeco Recycling, Inc. |
| Alpek |
| Evergreen Plastics, Inc. |
| Phoenix Technologies |
| PolyQuest |
| Zhejiang Anshun Pettechs Fibre Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Bottle-grade versus fiber-grade R-PET represents a fundamental tier divergence, manifesting in premium pricing for high-purity applications and distinct supply chain requirements. This bifurcation necessitates advanced collection and processing infrastructure for bottle-grade material, while fiber-grade R-PET can utilize a broader range of feedstock quality.
Pricing Analysis
Consistency of supply and quality guarantees are implicitly bundled into the pricing of high-purity R-PET, particularly for food-contact applications. Contract-based long-term offtake agreements dominate for bottle-grade material, ensuring stable pricing for both buyers and producers. Price differentiation stems from intrinsic viscosity (IV) levels and FDA certification for food-contact, rewarding specialized processors. Pricing pressure stems from virgin PET when crude oil prices are low, though regulatory mandates create a demand floor for R-PET. Textile manufacturers buying fiber-grade R-PET exhibit higher price sensitivity compared to food and beverage packagers.
Supply Chain Analysis
The availability of skilled labor for advanced sorting and processing facilities significantly influences R-PET supply chain efficiency in key manufacturing geographies. Supply concentration is evident in Germany and Japan, which possess robust collection and sorting systems, facilitating high-quality feedstock. China's domestic collection and recycling industry has expanded due to import bans, shifting regional supply dynamics. The supply chain relies heavily on consistent post-consumer PET bale feedstock. Feedstock quality and contamination present a structural supply chain risk. Distribution runs through direct sales channels for large-volume contracts and wholesalers for smaller, specialized converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Recycled Polyethylene Terephthalate market is evolving into a consolidation play, with significant capital investment hurdles for advanced recycling facilities forcing smaller, less efficient players out.
For Market Incumbents: To counter substitution by virgin PET when crude oil prices are low, incumbents must secure long-term offtake agreements with major consumer packaged goods companies. Investing in advanced chemical recycling technologies allows for processing lower-quality feedstock into virgin-equivalent material. Leveraging a global manufacturing footprint further strengthens market position and cost control. Prioritizing FDA certification for new R-PET grades ensures access to high-value food-contact segments.
For New Entrants and Emerging Players: Capture white-space opportunities by specializing in high-purity grades for niche food-contact applications or high-performance non-packaging segments like automotive interiors. Emerging economies in Southeast Asia and Latin America represent penetrable geographies with vast, untapped sources of post-consumer PET feedstock. A focused go-to-market angle involves deploying advanced AI-driven sorting technologies to ensure consistent quality from diverse feedstock streams.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized high-purity R-PET manufacturers given binding regulatory mandates for recycled content. The long-term viability of the R-PET market is underpinned by structural demand for circular polymers and corporate sustainability pledges. Acquisition targets should include companies with patented chemical recycling technologies or those controlling significant collection infrastructure in regions with growing demand. The expansion of advanced sorting and chemical recycling capacity serves as a key inflection indicator to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Building new food-grade mechanical recycling plants addresses rising demand for high-purity R-PET. |
| Backward Integration | Securing long-term feedstock supply through collection partnerships reduces raw material volatility. |
| Green Manufacturing Transition | Investing in chemical recycling allows processing of diverse waste streams into virgin-quality polymer. |
| Long-term Supply Agreement | Locking in consistent R-PET demand with major consumer packaged goods companies ensures revenue stability. |
| Certification Investment | Achieving FDA food-contact approval for new R-PET grades unlocks premium market segments. |
Research Approach
Independent corroboration across industry association reports, government environmental agency data, and corporate sustainability disclosures underwrites the qualitative findings. Primary interviews involved R-PET producers, CPG sustainability directors, recycling infrastructure developers, and polymer scientists. Secondary data sources included EU Green Deal documentation, FDA guidelines for food-contact plastics, and China's MEE policies, triangulated with bottom-up and top-down market sizing approaches.
The rate-of-change decomposition framing informed the quantitative analysis across the analysis window. The model segmented the market by product type (bottles, fiber, sheet, film), application (packaging, textiles, automotive), end-user (manufacturers, OEMs), and distribution channel, including intrinsic viscosity (IV) grades. Compound annual growth rates were derived from historical trends, regulatory impact assessments, and projected technology adoption rates, with recycled content mandates and virgin PET price forecasts as key inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to shifts in crude oil prices, advancements in chemical recycling, and changes in regulatory enforcement. Forecasts reflect assumptions regarding economic stability and technological progression. Material deviation in significant changes to virgin resin pricing, new breakthrough recycling technologies, or major shifts in environmental policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Plastic Recycling Market
Recycled Plastics
Plastic Pellets Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
Waste Plastic Bricks Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Germany Plastics Market
Recycled Plastics
North America BPA Free Plastic Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
North America Recycled Plastics Market
Recycled Plastics
Environmentally Friendly RPET Webbing Market
Recycled Plastics
Global Recycled PET (R-PET) Bottles Market
Recycled Plastics
Global Recycled Plastics Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Plastic Drums Market
Recycled Plastics
Recycled PET Flakes Market