
 Global Houseboats Market | 2026-2036
Global Houseboats Market Size, Share, and Industry Trends Forecast 2026-2036
Global Houseboats Market Analysis
European hull fabrication capacity is hardening as Dutch shipyards and Italian coastal builders absorb rising orders for floating residences. Brunswick Corporation leverages its marine propulsion portfolio to supply integrated power systems across multiple houseboat manufacturers. Luxe Motor sustains handcrafted wooden vessel production for heritage canal markets in Belgium and France. Arkup competes through self-elevating, hurricane-resistant platforms targeting Florida and Caribbean mooring sites.
A houseboat constitutes a flat-bottomed or semi-displacement hull vessel designed for extended residential or commercial occupancy, typically incorporating sleeping quarters, galley facilities, and marine sanitation systems compliant with IMO MARPOL discharge standards. These vessels serve recreational mooring, floating hospitality, and waterfront real estate functions across protected inland and coastal waterways. Luxury houseboats command the highest margin pools through bespoke interior fit-out and smart-home integration, while fishing houseboats anchor volume demand among North American Great Lakes users. Fiberglass hull construction dominates new builds for its corrosion resistance and molded complex geometry, though steel retains preference for permanent mooring structures in northern European climates.
FAA and USCG regulations govern mast height and navigation lighting for houseboats operating in federally managed waterways, while the EU Green Deal and F-Gas Regulation constrain refrigerant choices in onboard climate systems. The EPA enforces Clean Water Act discharge standards that shape marine sanitation device specifications across US lakes and rivers. Stakeholders must monitor evolving electrical grid connection standards for shore-powered floating residences as municipalities revise marina infrastructure codes.
Market Dynamics
Electric propulsion retrofits and solar-hybrid marine architectures are forcing hull redesigns across European canal networks, compressing traditional diesel-engine supply chains while opening new vendor categories in battery management and photovoltaic integration.
Growth Catalysts
- EU Green Deal vessel standards:MARPOL Annex VI amendments on nitrogen oxide emissions are accelerating engine replacement cycles in Dutch and German inland fleets. Shipyards report order backlogs for compliant propulsion packages.
- Floating hospitality expansion:Boutique hotel operators in France, Belgium, and the Netherlands are commissioning purpose-built houseboat suites for canal-adjacent real estate where conventional construction faces height restrictions.
- Lithium-iron-phosphate battery density improvements:Pack-level energy density gains above 160 Wh/kg are enabling overnight electric cruising ranges that satisfy weekend leisure users without auxiliary generators.
Market Restraints
- Marine-grade aluminum sheet volatility:Hull fabricators in Italy and Croatia face input cost swings of 20-30% on 5083-H321 alloy, compressing quoted margins on fixed-price contracts.
- Dutch shipyard capacity concentration:Three facilities in Friesland and Groningen provinces handle 60% of premium fiberglass hull production for northwest Europe, creating bottleneck risk during peak spring commissioning seasons.
- Shore power infrastructure gaps:Municipal marina codes in Germany and Austria lag IEC 80005-3 standards for high-voltage connection, limiting overnight electric vessel adoption outside Amsterdam and Utrecht.
Strategic Opportunities
- Poland and Czech Republic canal systems:Elbląg Canal and Vltava River networks remain underpenetrated by floating hospitality operators despite rising Warsaw and Prague leisure demand.
- US Inflation Reduction Act marine electrification credits:Section 45W commercial clean vehicle provisions extend to commercial tour operators, creating subsidy pools for electric houseboat fleet conversions on Lake Powell and Lake Cumberland.
- Smart-home integration with vessel monitoring:Convergence of IoT sensor networks and predictive maintenance platforms enables subscription-based remote diagnostics for absentee owners of Caribbean and Florida Keys mooring properties.
Industry Challenges
- Marine electrical certification timelines:ABYC and NMMA compliance testing for lithium battery installations adds 8-14 weeks to new build delivery schedules, frustrating seasonal buyers.
- Skilled aluminum welder scarcity:TIG certification holders capable of 5083 alloy hull fabrication command 40% wage premiums in Adriatic coastal yards, constraining Italian and Croatian production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Houseboats Market |
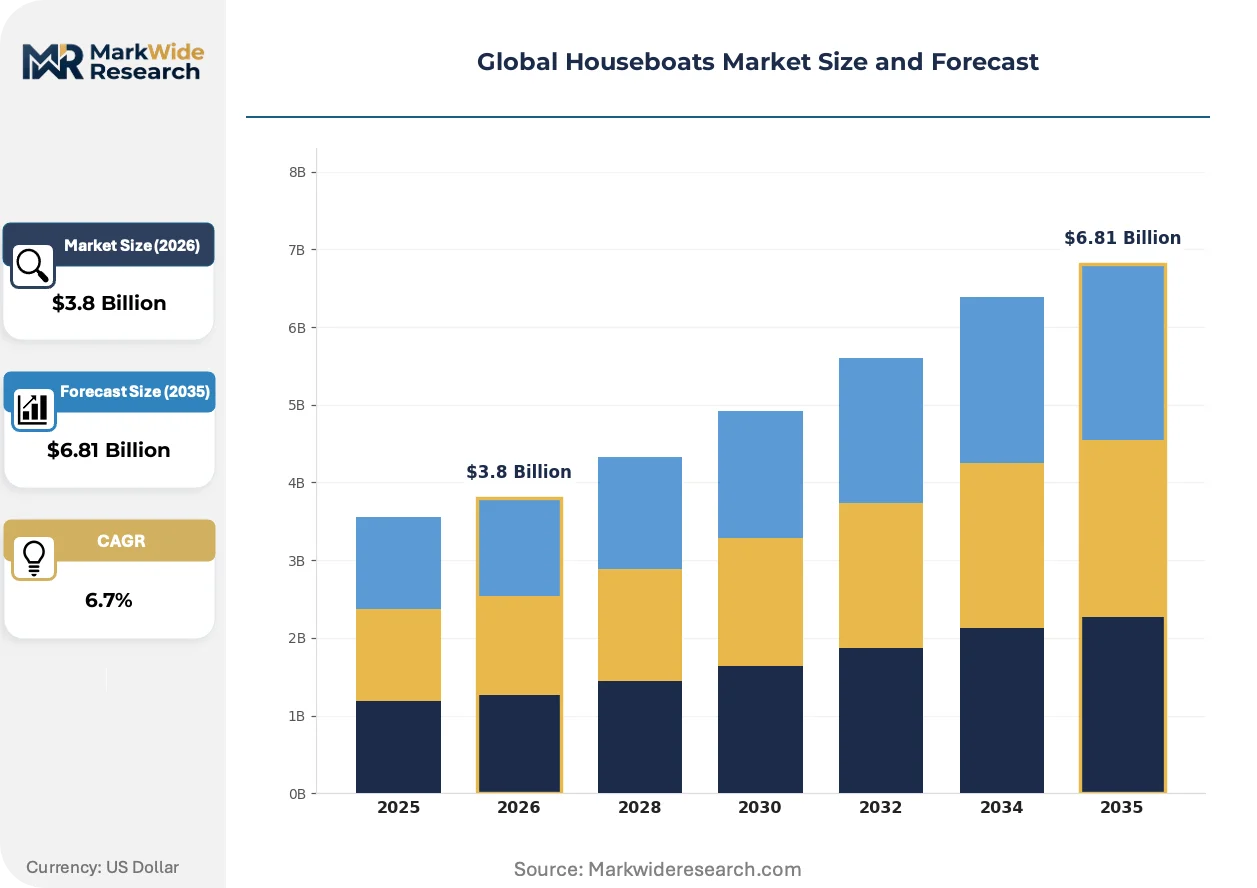
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Houseboats, Fishing Houseboats, Sailboats, Cabin Cruisers Material: Steel, Fiberglass, Wood, Aluminum End User: Recreational Users, Tour Operators, Real Estate Developers, Rental Services Geographical Orientation: Inland Waterways, Coastal Areas, Marina Locations, Resort Destinations |
| Companies Covered | Gibson Boats, Arkup, Brunswick Corporation, Dutch Craft, Catalina Yachts, MasterCraft Boat Company, Marine Group Boat Works, Luxe Motor, Sunseeker International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Houseboats Market Emerging Trajectories
Propulsion electrification, regulatory tightening on refrigerants and discharge, and the unbundling of vessel ownership from usage rights are restructuring how houseboats are specified, financed, and operated across protected waterways.
Solid-state lithium-metal battery architectures are absorbing engineering attention from cobalt-dependent NMC chemistries. Premium houseboat builders in the Netherlands and Pacific Northwest are piloting 400 Wh/kg prototype packs for extended off-grid anchoring. This chemistry shift is absorbing R&D budgets previously allocated to hydrogen fuel cell auxiliary systems, consolidating vendor roadmaps around direct electrification.
The EU F-Gas Regulation phasedown on hydrofluorocarbon refrigerants is mandating CO2 transcritical heat pumps for onboard climate systems. German and Austrian hull outfitters face retrofit obligations on existing fleets by 2030. Mediterranean operators are responding fastest, with Italian yards specifying propane-based alternatives for smaller vessel footprints where CO2 system costs prove prohibitive.
Fractional ownership platforms and vessel-sharing cooperatives are displacing traditional sole-ownership models among urban professionals in Amsterdam, Berlin, and Copenhagen. These arrangements pool maintenance, mooring fees, and insurance across 6-12 members. The shift is most visible in the Netherlands, where waterway access permits carry decade-long waiting lists that cooperative structures navigate more efficiently than individual applicants.
Global Houseboats Market Segmentation
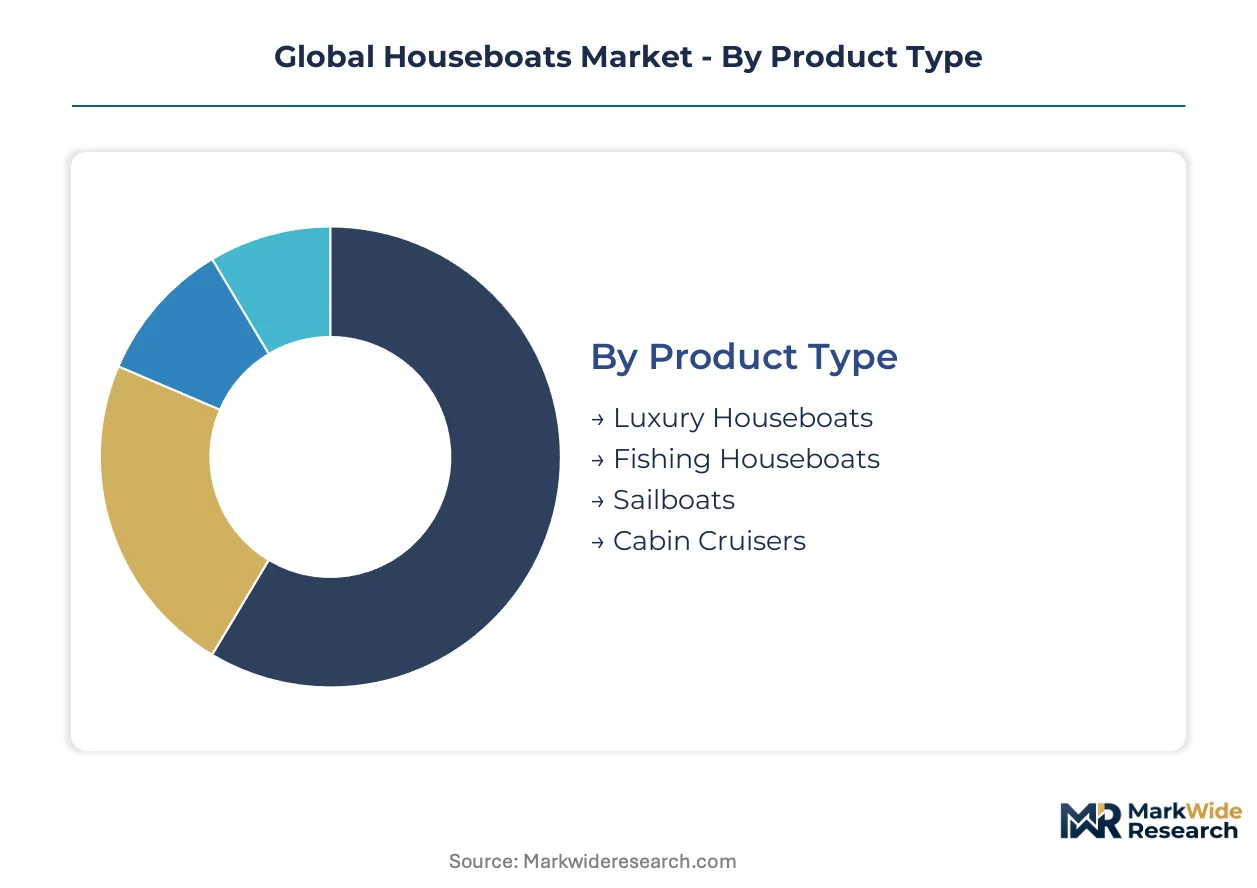
Houseboat specification varies sharply by intended function and mooring environment. Builders must reconcile hull material durability against propulsion architecture and regulatory discharge requirements across distinct operational profiles.
Product Type:
Standalone leisure vessels dominate order books, while embedded hospitality platforms integrate permanently with waterfront real estate developments.
- Luxury Houseboats:Bespoke interior fit-out with smart-home integration and premium marine sanitation systems command highest margins. Demand concentrates in Amsterdam and Utrecht floating real estate developments, constrained by EU Green Deal vessel standards mandating electric propulsion retrofits.
- Fishing Houseboats:Flat-bottomed hulls optimized for stability in freshwater lakes with integrated rod storage and livewell systems. North American Great Lakes users anchor volume demand, though EPA Clean Water Act discharge specifications shape marine sanitation device selection.
- Sailboats:Auxiliary sail-equipped houseboats reduce fuel dependence for extended coastal cruising.
- Cabin Cruisers:Semi-displacement hulls with enclosed helm stations serve weekend leisure markets requiring weather protection.
Luxury houseboats lead volumes today; electric-ready platforms are gaining share fastest.
Material:
Cost tier stratification separates premium custom builds from production volume hulls, with climate exposure dictating regional material preference.
- Fiberglass:Molded complex geometry enables corrosion-resistant new builds with reduced maintenance schedules. Dutch and Italian coastal builders absorb rising orders, though 5083-H321 aluminum price volatility compresses quoted margins on competing metal hulls.
- Steel:Permanent mooring structures in northern European climates favor welded steel for ice-load resistance and structural longevity.
- Wood:Handcrafted heritage vessels sustain niche demand in Belgium and France canal markets.
- Aluminum:Marine-grade 5083 alloy serves Adriatic coastal yards facing skilled TIG welder scarcity and 40% wage premiums for certified fabricators.
Fiberglass dominates new construction today; aluminum faces supply-side headwinds despite weight advantages.
End User:
Customer type determines financing structure and regulatory compliance burden, from individual recreational buyers to institutional fleet operators.
- Recreational Users:Individual owners seeking weekend leisure mooring face ABYC and NMMA certification timelines adding 8-14 weeks to lithium battery installation deliveries.
- Tour Operators:Commercial fleets on Lake Powell and Lake Cumberland access US Inflation Reduction Act Section 45W credits for electric conversion subsidies.
- Real Estate Developers:Floating hospitality suites in France, Belgium, and Netherlands canal-adjacent zones bypass conventional construction height restrictions.
- Rental Services:Fractional ownership platforms and vessel-sharing cooperatives pool maintenance and insurance across 6-12 members in Amsterdam, Berlin, and Copenhagen.
Recreational users anchor absolute volumes today; tour operators are expanding most quickly through electrification subsidies.
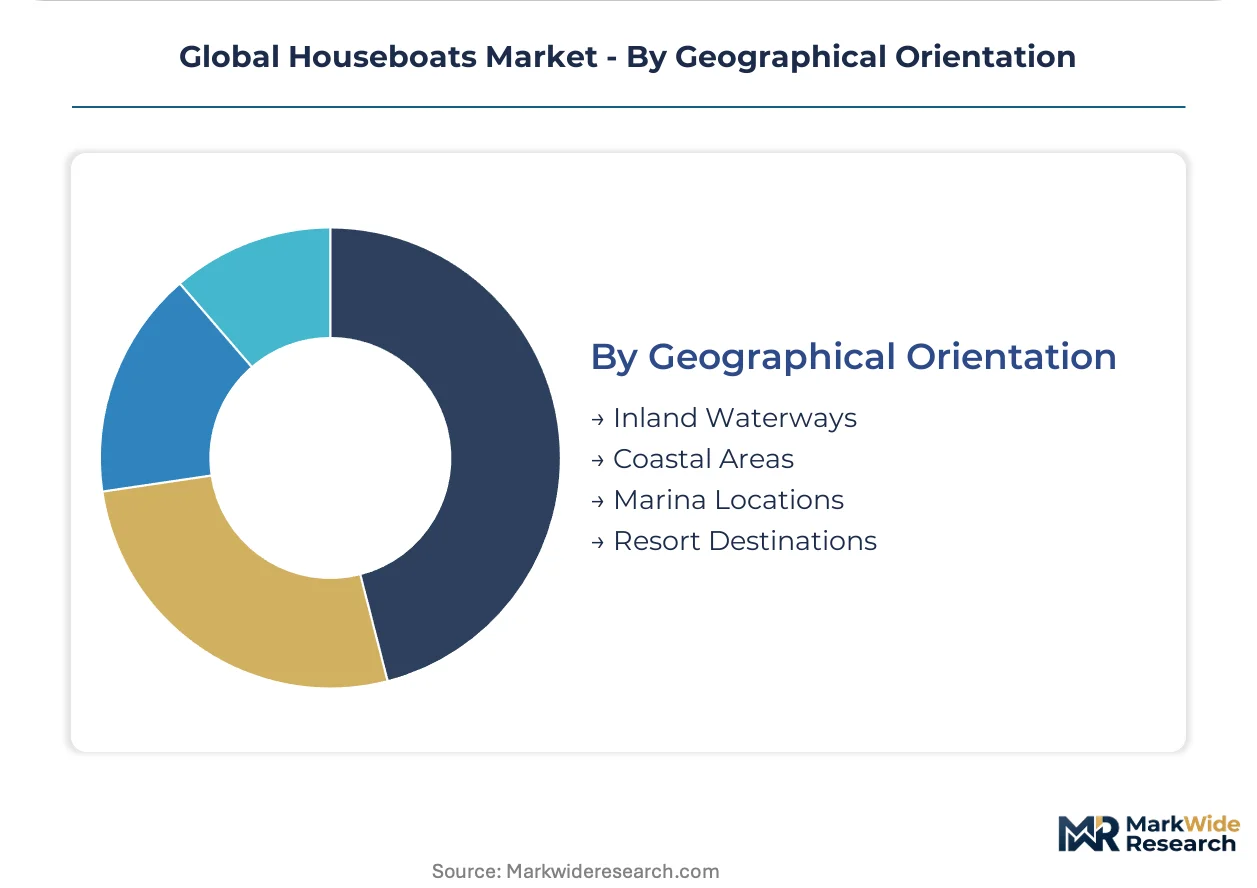
Geographical Orientation:
Application setting dictates hull form, regulatory jurisdiction, and shore power infrastructure availability.
- Inland Waterways:Protected canal networks in Netherlands, Germany, and Austria face shore power infrastructure gaps outside Amsterdam and Utrecht, limiting overnight electric vessel adoption.
- Coastal Areas:Hurricane-resistant self-elevating platforms target Florida and Caribbean mooring sites with enhanced storm survivability requirements.
- Marina Locations:Federally managed US waterways require FAA and USCG compliance on mast height and navigation lighting specifications.
- Resort Destinations:Boutique hotel operators commission purpose-built suites where conventional waterfront construction faces environmental permitting barriers.
Inland waterways sustain established demand today; coastal hurricane-resistant platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between European emission standards and US federal waterways governance are redirecting production investment toward Dutch and German shipyards, where EU Green Deal vessel standards concentrate fabrication expertise but extend delivery timelines.
Netherlands
Amsterdam and Utrecht floating real estate developments drive premium hull demand for canal-adjacent hospitality suites. EU Green Deal MARPOL Annex VI amendments on nitrogen oxide emissions accelerate engine replacement cycles across Dutch inland fleets. Friesland and Groningen provinces host three facilities handling sixty percent of premium fiberglass hull production for northwest Europe.
Germany
Elbe and Rhine river tour operators expand electric fleet commitments under federal maritime decarbonization incentives. The country's national environmental regulator enforces discharge standards that shape marine sanitation device specifications for commercial vessels. Bavaria and Baden-Württemberg shipyards specialize in steel-hulled permanent mooring structures for ice-load resistance.
United States
Lake Powell and Lake Cumberland commercial operators access Inflation Reduction Act Section 45W credits for electric houseboat fleet conversions. FAA and USCG regulations govern mast height and navigation lighting for vessels operating in federally managed waterways. Florida Keys and Caribbean mooring sites attract hurricane-resistant platform development from specialized fabricators.
Italy
Adriatic coastal builders absorb rising orders for Mediterranean floating hospitality concepts. The EU F-Gas Regulation phasedown on hydrofluorocarbon refrigerants mandates CO2 transcritical heat pumps for onboard climate systems in new builds. Veneto and Emilia-Romagna yards face skilled TIG welder scarcity and forty percent wage premiums for 5083 alloy hull certification.
France
Boutique hotel operators in Paris and Lyon canal zones commission purpose-built houseboat suites where conventional construction faces height restrictions. The country's national environmental authority aligns with EU Green Deal vessel standards for inland waterway emissions. Île-de-France and Provence-Alpes-Côte d'Azur clusters sustain handcrafted wooden vessel demand for heritage canal markets.
Global Houseboats Market Vendor Landscape
Dutch producers anchor the premium-tier fabrication segment; US and Italian specialists hold volume and coastal-resilience positions respectively. The vendor base stratifies across three tiers: integrated marine propulsion suppliers, heritage craftsmanship ateliers, and self-elevating platform innovators. Consolidation pressure concentrates in fiberglass hull supply chains, while aluminum fabrication remains fragmented across Adriatic yards. Dominant competitive moves include capacity expansion in Friesland shipyards and strategic partnerships between battery management system vendors and hull outfitters.
Within the integrated propulsion tier, Brunswick Corporation exemplifies supply chain breadth across multiple vessel categories. Dutch Craft and Luxe Motor occupy distinct positioning as heritage-oriented fabricators serving canal network preservation demands. Arkup represents the coastal-resilience archetype through self-elevating platform engineering targeting storm-exposed mooring environments. These three company types collectively illustrate how geographic specialization and regulatory adaptation shape competitive differentiation across protected inland and coastal waterway markets.
| Leading Market Players |
|---|
| Gibson Boats |
| Arkup |
| Brunswick Corporation |
| Dutch Craft |
| Catalina Yachts |
| MasterCraft Boat Company |
| Marine Group Boat Works |
| Luxe Motor |
| Sunseeker International |
| Others |
Supply Flow & Price Mechanics
Electric propulsion retrofits and solar-hybrid marine architectures are compressing traditional diesel-engine supply chains while opening new vendor categories in battery management and photovoltaic integration. This technology shift concentrates pricing power among Dutch and German shipyards that have absorbed EU Green Deal compliance expertise, forcing buyers to accept extended delivery timelines for certified hulls.
Pricing Analysis
Distributor margins on marine propulsion systems range from fifteen to twenty-five percent depending on integration complexity, while direct-to-shipyard procurement of lithium-iron-phosphate battery packs commands volume discounts above fifty-unit orders. Three-tier pricing structure across premium, standard, and economy levels separates bespoke heritage craftsmanship from production fiberglass hulls and entry-level rental fleet vessels. Pricing pressure stems from marine-grade aluminum sheet volatility on 5083-H321 alloy, which compresses quoted margins for Adriatic builders. Tour operators accessing US Inflation Reduction Act credits exhibit lowest price sensitivity; individual recreational buyers in North American Great Lakes markets face highest budget constraints.
Supply Chain Analysis
Marine-grade aluminum sheet supply rests on Norwegian and Chinese primary smelters, with Italian and Croatian hull fabricators drawing from German and Austrian rolling mills for 5083-H321 alloy certification. Lithium-iron-phosphate cathode material sources from Chinese and South Korean chemical producers, while photovoltaic marine panels concentrate in Taiwanese and Malaysian manufacturing hubs. Single-source vulnerability runs through Dutch fiberglass hull production, where three Friesland and Groningen facilities handle sixty percent of northwest European premium vessel output. Distribution runs through direct shipyard contracts for custom builds and regional marine distributors for standardized leisure craft.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Houseboats Market functions as a regulatory compounder where EU Green Deal MARPOL Annex VI amendments on nitrogen oxide emissions are accelerating engine replacement cycles and concentrating fabrication expertise in compliant Dutch and German shipyards.
For Market Incumbents: Cement defensive positioning through captive supply of lithium battery management systems and shore power integration hardware, locking out emerging Asian electronics vendors. Expand fiberglass hull capacity in Friesland province ahead of peak spring commissioning seasons, preempting bottleneck risk that could displace orders to Italian competitors. The priority lever sits with vertical integration into electric propulsion retrofit services, capturing recurring revenue from existing diesel fleet owners facing regulatory deadlines. For New Entrants and Emerging Players: Solid-state lithium-metal battery pilot programs offer technology-first wedge into premium off-grid anchoring segments where energy density above four hundred watt-hours per kilogram commands design partnerships. Target Poland and Czech Republic canal systems for floating hospitality concepts, where Elbląg Canal and Vltava River networks remain underpenetrated despite rising Warsaw and Prague leisure demand. The most penetrable entry angle pairs vessel-sharing cooperative structures with municipal waterway access permit aggregation, navigating decade-long waiting lists that frustrate individual applicants. For Investors and Strategic Acquirers: Roll-up economics work for regional marine electrical installers because ABYC and NMMA certification timelines create eight-to-fourteen-week delivery backlogs that fragment service capacity and sustain pricing premiums. Long-term viability centers on five-to-ten-year electrification conversion cycles across European inland fleets and US commercial tour operators. Acquisition targets should exhibit captive relationships with lithium battery distributors and shore power infrastructure contractors. The signal to watch is municipal marina code adoption of IEC 80005-3 high-voltage connection standards, which would unlock overnight electric vessel adoption outside Amsterdam and Utrecht core markets.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Retrofit Partnership | Brunswick Corporation's marine propulsion portfolio enables integrated power system supply across multiple Dutch and German hull manufacturers. |
| Fractional Ownership Platform Launch | Vessel-sharing cooperatives in Amsterdam, Berlin, and Copenhagen pool maintenance and insurance across six-to-twelve members, displacing traditional sole-ownership models. |
| Hurricane-Resistant Platform Engineering | Self-elevating platform development targets Florida Keys and Caribbean mooring sites with enhanced storm survivability requirements. |
| CO2 Transcritical Heat Pump Specification | EU F-Gas Regulation mandates onboard climate system retrofits by 2030, creating retrofit obligations for German and Austrian hull outfitters. |
| Poland Canal Network Hospitality Expansion | Elbląg Canal floating suites address rising Warsaw leisure demand in underpenetrated waterways outside Netherlands core markets. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with shipyard operations directors, marine propulsion procurement leads at Brunswick Corporation and Dutch Craft, canal network regulatory affairs officers, and fractional ownership platform founders with secondary validation. Secondary sources included EU MARPOL Annex VI amendment filings, US Inflation Reduction Act Section 45W guidance documents, Netherlands environmental regulator discharge permits, and SEC 10-K marine equipment disclosures. Bottom-up hull production tallies from Friesland, Groningen, Veneto, and Emilia-Romagna provinces were triangulated against top-down leisure tourism expenditure estimates.
Segment-weighting approaches modeled product type splits across luxury houseboats, fishing houseboats, sailboats, and cabin cruisers; material categories spanning fiberglass, steel, wood, and aluminum; and end-user distinctions among recreational users, tour operators, real estate developers, and rental services across the projection horizon. CAGRs were derived from regression analysis of historical hull commissioning data against regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated lithium-iron-phosphate battery density improvement curves and municipal marina shore power infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal vessel standard enforcement timing and US Inflation Reduction Act credit extension decisions. Forecasts reflect documented assumptions regarding aluminum alloy price stabilization and skilled TIG welder availability in Adriatic coastal yards. Material deviation in battery chemistry transition timelines or hurricane-resistant platform certification pathways warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recreational Vehicles
Self Balancing Scooter Market
Recreational Vehicles
Snowmobile Trailer Axle Market
Recreational Vehicles
Recreational Boating Market
Recreational Vehicles
Automotive Trailer Market
Recreational Vehicles
Kick Scooter Market
Recreational Vehicles
Hovercraft Market
Recreational Vehicles
Recreational Vehicle Parks and Campgrounds Market
Recreational Vehicles
US Recreational Boating Market
Recreational Vehicles
Global Truck Camper Market
Recreational Vehicles
Light Car Trailer Market
Recreational Vehicles
Water Scooter Market
Recreational Vehicles
Luxury Van Market
Recreational Vehicles
Segway Market
Recreational Vehicles
Low Speed Vehicle (LSV) Market
Recreational Vehicles
Motorized Quadricycle Market
Recreational Vehicles
Caravan and Motorhome Market