
 Japan Marine Composites Market | 2026-2036
Japan Marine Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Marine Composites Market Intelligence
Japanese carbon fiber producers is pivoting toward maritime-grade prepreg capacity as domestic yards seek lighter hull solutions. Toray Industries leverages its aerospace-derived resin transfer expertise to supply high-modulus fiber systems for naval patrol craft. Mitsubishi Chemical Carbon Fiber and Composites anchors its position through captive precursor production and integrated autoclave facilities in Otake. Teijin competes via aramid-hybrid laminates targeting impact-resistant applications in fast-attack craft.
Japan marine composites encompass fiber-reinforced polymer systems, vinylester and epoxy matrices, and phenolic formulations engineered for saltwater corrosion resistance, fire retardancy, and specific strength exceeding steel by fivefold. These materials serve shipbuilding, yacht construction, and naval platforms where weight reduction directly improves fuel efficiency and payload capacity. Fiber Reinforced Polymer dominates value capture due to carbon fiber's performance premium in defense and superyacht segments, while phenolic resins gain share in engine-room and bulkhead applications driven by stricter fire-safety mandates. Epoxy systems sustain the broadest application base across commercial shipbuilding, though vinylester competes aggressively in fishing vessels where cost and blister resistance matter more than modulus.
METI's vessel efficiency standards and JIS class rules for fiber-reinforced plastic construction shape product certification requirements and yard procurement patterns. PMDA oversight of chemical substance release governs resin formulation changes, while ISO 12215 structural scantling rules influence laminate specification for export-bound craft. Stakeholders must monitor evolving defense procurement timelines and the pace of hydrogen-fuel-cell vessel trials, as both will redirect composite specification toward cryogenic-compatible systems and pressure-vessel architectures.
Market Dynamics
METI's fuel-efficiency mandates for domestic vessels are compressing procurement cycles as yards accelerate composite hull adoption to meet 2027 compliance deadlines. This regulatory pressure concentrates demand among Setouchi-region builders with autoclave capacity.
Growth Catalysts
- Naval modernization programs:Defense procurement for patrol craft and fast-attack vessels specifies carbon-fiber composite superstructures to extend operational range.
- JIS FRP construction standards:Updated class rules streamline certification for fiber-reinforced plastic hulls, reducing yard approval timelines.
- Hydrogen vessel trials:METI-funded demonstration projects for fuel-cell ferries create specification pull for cryogenic-compatible pressure vessels.
Market Restraints
- Acrylonitrile precursor concentration:Domestic carbon fiber supply depends on petrochemical feedstock imports subject to naphtha price volatility.
- Autoclave capacity scarcity:Large-diameter pressure chambers for naval hull sections concentrate at three Otake-area facilities.
- Steel hull substitution inertia:Commercial fishing fleet operators resist FRP adoption due to repair network gaps in remote Hokkaido ports.
Strategic Opportunities
- Kyushu offshore wind support vessels:Unpenetrated demand exists for composite crew-transfer boats serving turbine maintenance contracts.
- Aramid-epoxy hybrid systems:Impact-resistant laminates for fast-attack craft represent white space between carbon fiber and glass fiber performance tiers.
- Direct yard contracting:Bypassing trading houses to supply prepreg directly to Setouchi builders captures margin and specification control.
Industry Challenges
- Laminate technician certification:JIS-qualified adhesive bonding specialists remain scarce relative to yard expansion timelines.
- Resin formulation re-registration:PMDA chemical substance release reviews delay new fire-retardant epoxy introductions by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Marine Composites Market |
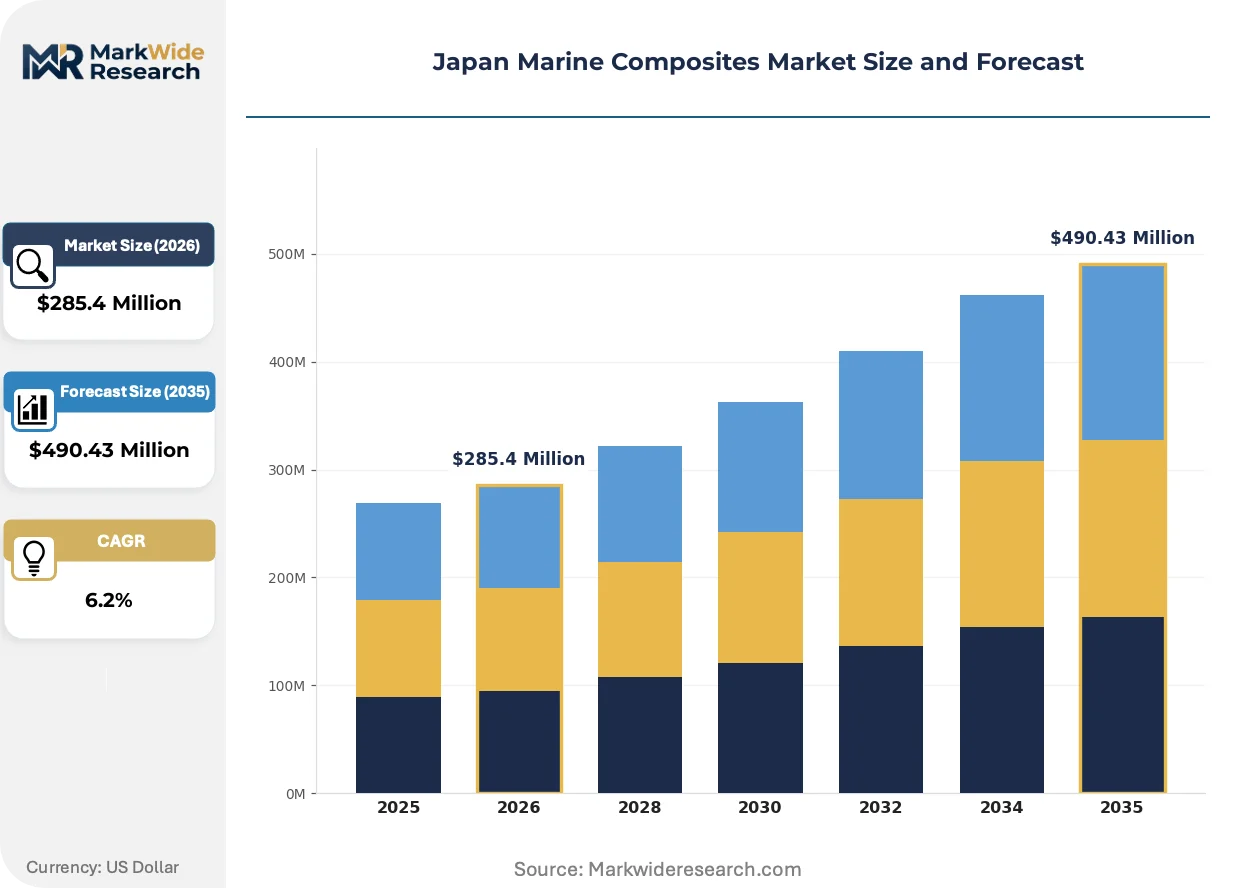
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Reinforced Polymer, Vinylester, Epoxy, Phenolic Application: Shipbuilding, Yachts, Fishing Vessels, Naval Applications End User: OEMs, Repair Services, Maritime Academies, Defense Contractors Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Toray Industries, Mitsubishi Chemical Carbon Fiber and Composites, SGL Carbon, Hexcel Corporation, Gurit Services, Teijin, Toho Tenax, Mitsubishi Chemical Holdings, Toray Advanced Composites, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Marine Composites Market Strategic Shifts & Innovations
Out-of-autoclave curing systems are disrupting traditional manufacturing economics as yards seek to decouple hull production from chamber bottlenecks. These process innovations compress capital requirements while expanding feasible component sizes.
Infusion-molded epoxy prepregs is absorbing production volume previously captured by autoclave-cured systems. Regional builders in Hiroshima Prefecture are adopting resin transfer molding for patrol craft hull sections up to 40 meters. This diffusion is compressing the premium commanded by aerospace-grade autoclave capacity.
REACH-aligned substance restrictions on styrene emissions are forcing reformulation of vinylester resin systems used in commercial fishing vessels. European export compliance now requires alternative monomer architectures. Japanese formulators are responding with low-styrene hybrid chemistries certified for Baltic Sea passenger ferry contracts.
Yard procurement teams are consolidating supplier rosters around vertically integrated fiber-precursor-to-prepreg manufacturers. Direct technical service agreements replace distributor-mediated relationships for critical naval contracts. This concentration is most visible in Nagasaki Prefecture, where Mitsubishi Heavy Industries structures specify single-source carbon fiber qualification.
Japan Marine Composites Market Segmentation
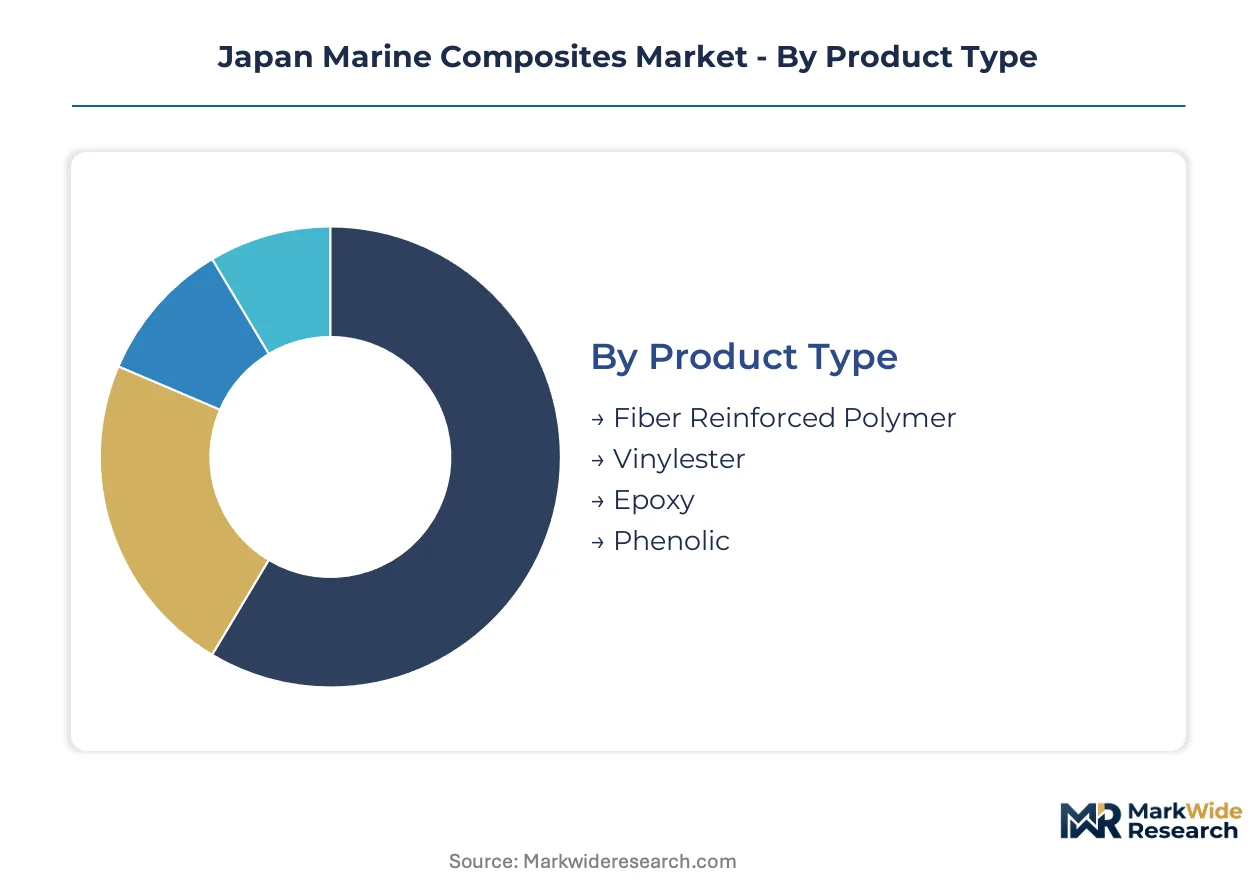
Segmentation in the Japan marine composites market reveals how capital deployment, regulatory pressure, and end-use specifications fragment procurement patterns across domestic yards. Understanding these divisions clarifies where specification control concentrates and where margin compression threatens.
Product Type:
Carbon fiber prepreg systems demand the heaviest capital commitment, requiring autoclave infrastructure and climate-controlled storage that locks smaller formulators out of defense-tier supply.
- Fiber Reinforced Polymer:Carbon and glass fiber laminates deliver specific strength five times that of steel. METI's fuel-efficiency mandates for domestic vessels pull demand toward Setouchi-region builders with autoclave capacity for naval superstructures.
- Epoxy:Marine-grade formulations dominate commercial shipbuilding through superior adhesion and fatigue resistance. Hiroshima Prefecture yards specify infusion-molded epoxy prepregs for patrol craft hull sections up to 40 meters, displacing some autoclave-cured volume.
- Vinylester:Cost-optimized resins serve fishing fleets where blister resistance outweighs modulus requirements. REACH-aligned styrene restrictions are forcing reformulation for Baltic Sea export compliance.
- Phenolic:Fire-retardant systems penetrate engine-room and bulkhead applications as JIS safety standards tighten. PMDA chemical substance reviews delay new formulation introductions by 18-24 months.
Most installed capacity flows through Fiber Reinforced Polymer. Expansion is steepest in Phenolic as fire-safety mandates broaden.
Application:
Defense procurement cycles stretch 7-10 years, locking specification relationships early, while commercial shipbuilding operates on compressed tender timelines.
- Naval Applications:Patrol craft and fast-attack vessel programs specify carbon-fiber superstructures to extend operational range. Mitsubishi Heavy Industries structures in Nagasaki Prefecture require single-source carbon fiber qualification, consolidating supplier rosters.
- Shipbuilding:Commercial hull construction absorbs the broadest epoxy volume across ferry and coastal cargo segments. METI's 2027 compliance deadlines compress procurement cycles among Setouchi-region builders.
- Yachts:Superyacht segments command carbon fiber premiums for weight-sensitive performance hulls. Domestic builders serve both domestic and export contracts with JIS FRP certification.
- Fishing Vessels:Cost-driven operators in Hokkaido resist FRP adoption due to repair network gaps in remote ports. Steel hull substitution inertia persists despite efficiency advantages.
Defense contracts anchor the highest margin tier. Yacht construction is gaining share fastest as export orders recover.
End User:
Procurement sophistication varies sharply: defense contractors demand full material traceability while repair services prioritize inventory velocity.
- Defense Contractors:Technical service agreements replace distributor relationships for critical naval contracts. Direct prepreg supply from fiber manufacturers captures specification control and margin.
- OEMs:Original equipment manufacturers consolidate supplier rosters around vertically integrated fiber-precursor-to-prepreg producers. Yard procurement teams favor manufacturers with captive precursor production.
- Repair Services:Fragmented demand across coastal maintenance yards relies on distributor networks for small-batch resin and fabric supply. JIS-qualified adhesive bonding specialists remain scarce relative to expansion timelines.
- Maritime Academies:Training institutions specify standardized laminates for instructional vessel construction. Curriculum alignment with JIS certification requirements shapes material selection.
OEMs command the largest order flow. Defense Contractors show the steepest specification tightening as modernization programs accelerate.
Distribution Channel:
Channel choice reflects contract scale and technical complexity, with direct relationships displacing intermediaries in defense-tier supply.
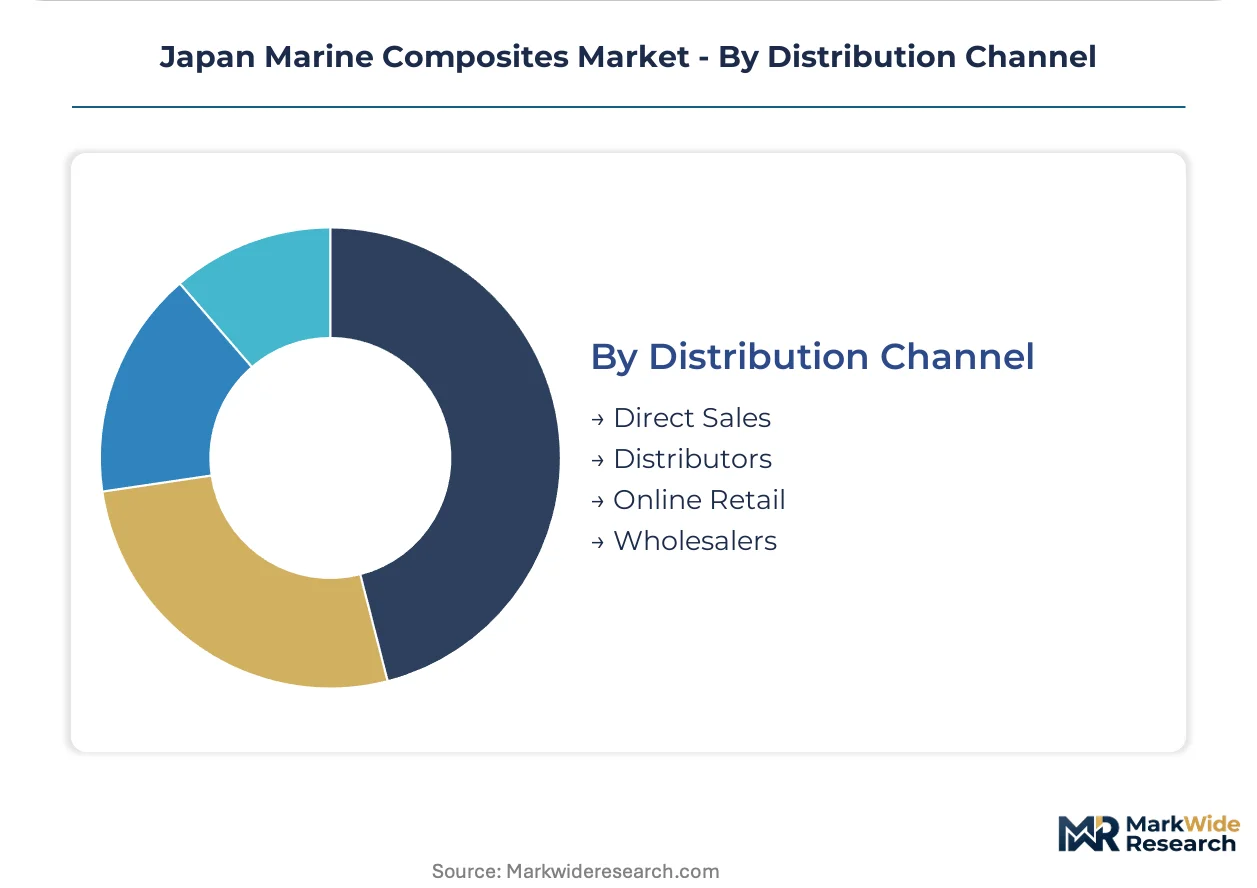
- Direct Sales:Technical service agreements dominate naval and superyacht contracts requiring application engineering support. Toray Industries and Mitsubishi Chemical Carbon Fiber and Composites bypass trading houses for critical specifications.
- Distributors:Regional intermediaries serve commercial yards and repair networks with stocked resin and fabric inventories. Inventory carrying costs concentrate among Setouchi-based distributors.
- Wholesalers:Volume aggregators supply standardized glass fiber and polyester systems to smaller builders. Price competition compresses margins in undifferentiated commodity grades.
- Online Retail:Limited penetration restricted to small-batch repair supplies and tooling accessories. Technical validation requirements constrain digital channel expansion.
Direct Sales captures the highest value per ton. Distributors retain volume leadership across commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between prefectures are redistributing composite fabrication capacity. Yards in regions with streamlined METI environmental approvals attract investment, while legacy clusters face upgrade burdens.
Setouchi Region
Naval patrol craft programs and commercial ferry contracts drive prepreg consumption. METI's 2027 fuel-efficiency deadlines compress procurement timelines among Hiroshima and Ehime prefecture builders. Autoclave infrastructure concentrates in Otake and Imabari, where integrated fiber-to-prepreg supply chains serve both defense and commercial hull contracts.
Kyushu
Offshore wind support vessel demand is emerging around turbine maintenance contracts. Nagasaki Prefecture hosts Mitsubishi Heavy Industries structures requiring single-source carbon fiber qualification. Sasebo-area yards are positioning for crew-transfer boat fabrication as renewable energy infrastructure expands.
Kanto
Yacht construction and maritime academy training vessel programs absorb specialty epoxy volumes. Tokyo Bay regulatory oversight from METI and PMDA shapes resin formulation standards. Chiba and Kanagawa prefecture facilities serve export-bound superyacht segments with JIS FRP certification.
Hokkaido
Commercial fishing fleet operators resist FRP adoption due to repair network gaps in remote ports. Steel hull substitution inertia persists despite efficiency advantages. Local yards focus on steel vessel maintenance rather than composite newbuild capacity.
Chubu
Automotive and aerospace composite expertise spills into marine applications. Aichi Prefecture resin formulators supply low-styrene vinylester systems for Baltic Sea export compliance. Nagoya-area technical centers support infusion-molded epoxy development for mid-size patrol craft.
Japan Marine Composites Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cryogenic-compatible pressure vessel architectures for hydrogen vessel trials. The vendor base clusters around fiber-precursor-to-prepreg integration levels. Three archetypes dominate: integrated chemical conglomerates with captive carbon fiber capacity, specialized prepreg formulators serving defense qualification pathways, and regional resin distributors supporting commercial repair networks. Capacity expansion and direct yard contracting displace trading house intermediaries as primary competitive moves.
Among integrated chemical conglomerates, Toray Industries and Mitsubishi Chemical Carbon Fiber and Composites exemplify the fiber-precursor-to-prepreg archetype. These entities anchor defense-tier supply relationships through captive production infrastructure. Teijin occupies a position within the impact-resistant laminate specialization tier, representing aramid-hybrid system capabilities for fast-attack craft applications.
| Leading Market Players |
|---|
| Toray Industries |
| Mitsubishi Chemical Carbon Fiber and Composites |
| SGL Carbon |
| Hexcel Corporation |
| Gurit Services |
| Teijin |
| Toho Tenax |
| Mitsubishi Chemical Holdings |
| Toray Advanced Composites |
| Others |
Cost & Logistics Intelligence
Carbon fiber prepreg premium tiers diverge sharply from glass fiber commodity grades across Japan's marine composites market, with this bifurcation manifesting in both contract structures and procurement network configurations. Defense-tier buyers absorb aerospace-derived autoclave capacity at three to five times the per-kilogram rate of commercial fishing vessel operators, while METI's 2027 fuel-efficiency mandates compress the premium window for intermediate modulus systems.
Pricing Analysis
Distributor margins absorb 12-18 percent of landed cost for commercial yards lacking direct fiber manufacturer relationships. Three-tier pricing structure across defense-grade carbon prepregs, commercial epoxy laminates, and cost-optimized vinylester systems separates specification-controlled naval contracts from price-sensitive Hokkaido fishing fleets. Cost compression in glass fiber tiers intensifies as Chinese precursor imports undercut domestic acrylonitrile pricing. Commercial fishing vessel operators exhibit highest price sensitivity; defense contractors prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Mitsubishi Heavy Industries and Imabari Shipbuilding, bypassing traditional trading house intermediaries. Geographic supply concentration centers on Japan, South Korea, and Taiwan for carbon fiber precursor and prepregs; acrylonitrile feedstock draws from naphtha crackers in Singapore and South Korea. Raw material dependencies include petrochemical-derived precursor, epoxy resin formulations, and phenolic hardeners. Single-source vulnerability concentrates at three Otake-area autoclave facilities serving naval hull sections. Distribution runs through vertically integrated fiber-to-prepreg manufacturers for defense tiers, regional distributors for commercial repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
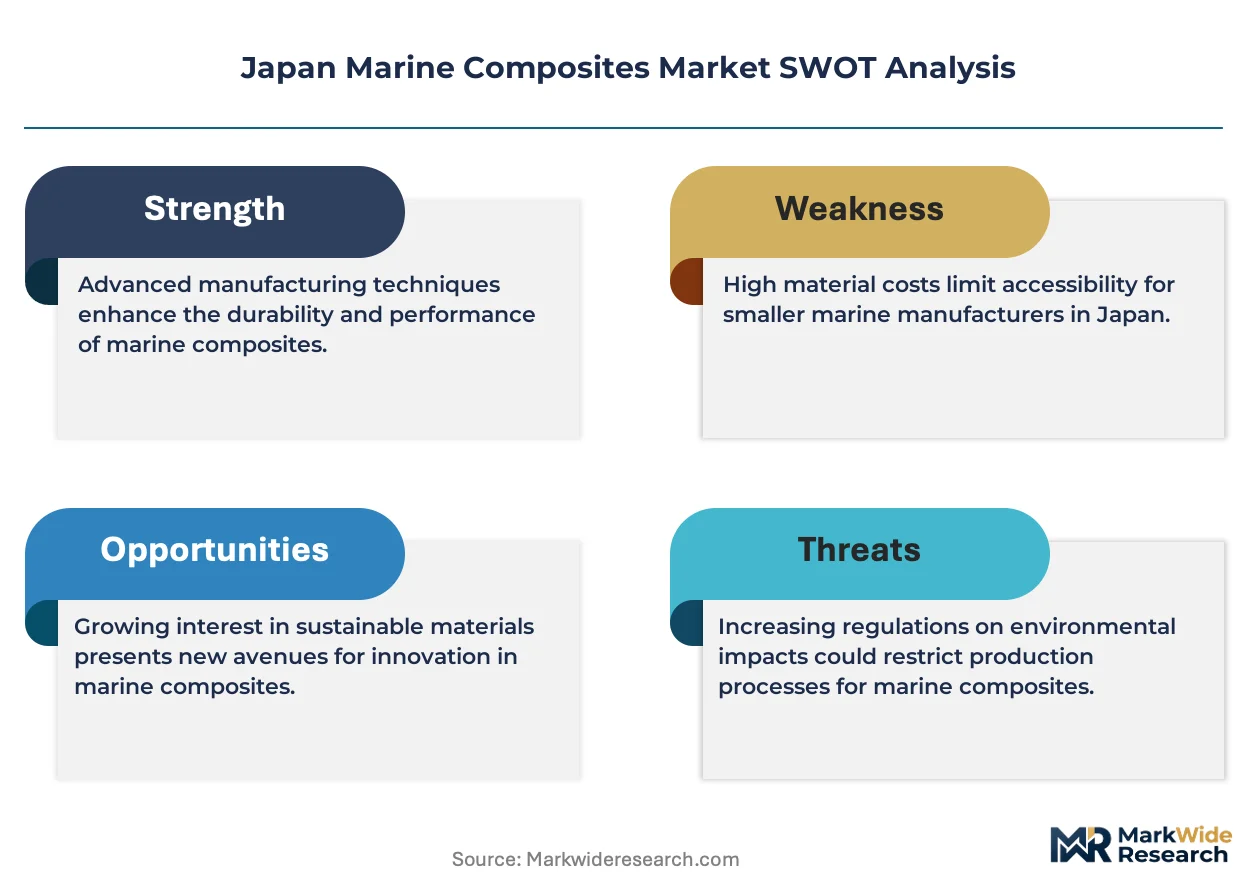
Japan's marine composites market functions as a regulatory compounder where METI's vessel efficiency mandates and JIS FRP construction standards continuously reshape procurement specifications and supplier qualification pathways.
For Market Incumbents: Deepen captive precursor production to defend margin position against Korean carbon fiber imports. Secure additional autoclave capacity in the Setouchi region before 2027 compliance deadlines lock in supplier relationships. Invest in JIS-qualified adhesive bonding certification programs to address technician scarcity threatening yard expansion timelines. Out-of-autoclave curing expertise represents a critical defensive lever against chamber bottlenecks.
For New Entrants and Emerging Players: Digital platform routes for small-batch repair supplies offer the most penetrable entry vector around established distributor networks. Target Kyushu offshore wind support vessels where composite crew-transfer boat demand remains unpenetrated by incumbent naval suppliers. Develop cryogenic-compatible pressure vessel laminates for METI-funded hydrogen ferry trials as a specification wedge. Direct technical service agreements with Sasebo-area yards bypass trading house control.
For Investors and Strategic Acquirers: Consolidation pressure builds where autoclave capacity scarcity meets defense procurement acceleration. Five-to-ten year viability favors vertically integrated fiber-precursor-to-prepreg manufacturers with JIS certification pathways and naval qualification history. Acquisition target archetype: regional epoxy formulators with infusion-molded expertise and untapped autoclave partnerships. Watch hydrogen vessel demonstration project timelines as inflection indicator for cryogenic laminate demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile supply insulates Toray and Mitsubishi from naphtha price volatility. |
| Out-of-Autoclave Curing Technology Deployment | Resin transfer molding adoption by Hiroshima yards decouples hull production from chamber constraints. |
| JIS FRP Certification Investment | Streamlined class rules reduce yard approval timelines and lock in specification relationships. |
| Hydrogen Vessel Pressure Vessel Development | Cryogenic-compatible laminates capture METI-funded ferry demonstration project contracts. |
| Direct Yard Contracting Bypass | Technical service agreements with Setouchi builders displace trading house intermediaries. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged shipyard procurement directors, carbon fiber plant managers, JIS certification auditors, naval program officers at the Maritime Self-Defense Force, and epoxy formulator R&D leads. Secondary validation drew from METI vessel statistics, JIS standard revision records, customs trade data for carbon fiber imports, and SEC filings of listed chemical conglomerates. Bottom-up volume estimates from yard-level consumption patterns triangulated against top-down market sizing from fiber manufacturer shipment disclosures.
Segment-weighting approaches distributed value across product type, application, and end-user dimensions. The analytical framework modeled defense procurement cycles, commercial shipbuilding tender timelines, and yacht export order patterns across the projection horizon. CAGRs derived from historical volume trajectories adjusted for METI regulatory phase-ins and hydrogen vessel trial schedules. Industry-specific forecast inputs included autoclave capacity utilization rates and JIS-qualified technician pipeline data.
The model assumes a particular technology adoption path; alternative pathways for out-of-autoclave curing or hydrogen fuel-cell vessel architectures would alter the outlook. Forecasts reflect base-case assumptions about defense budget continuity, naphtha feedstock pricing bands, and JIS certification timeline adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Marine Engine Cooling Systems Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Recreational Vessel Battery Market
Marine
Marine Chartplotter Market
Marine
Trim Tabs Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Marine LED Lights Market
Marine
GCC ROV Market
Marine
Marine Fender Market
Marine
Yacht Shell Doors Market
Marine
LNG Bunkering Vessel Market
Marine
Marine Spreader Lights Market
Marine
Marine Strip Market
Marine
Marine Navigation System Market