
 Monitor Arm Market | 2026-2036
Monitor Arm Market Size, Share, and Industry Trends Forecast 2026-2036
Monitor Arm Market Intelligence
Enterprise buyer concentration is expanding as Fortune 500 technology and financial services firms consolidate vendor relationships for standardized global office rollouts. Herman Miller, Inc. leverages its contract furniture channel dominance to bundle monitor arms with seating and desk systems. Ergotron, Inc. sustains a technology leadership position in articulating gas-spring mechanisms for clinical and command-center applications. Loctek Ergonomic Technology Corp. anchors high-volume manufacturing scale for private-label and direct-to-business contracts across Asia-Pacific and North American distribution.
A monitor arm is a mechanical support apparatus that attaches a display screen to a desk, wall, or workstation surface through pivot joints, gas springs, or counterbalance mechanisms, typically fabricated from extruded aluminum or die-cast steel with polymer joint housings, and engineered to permit height adjustment, tilt, swivel, and rotation for ergonomic viewing alignment. Its primary commercial purpose is to reduce neck and eye strain while reclaiming desktop surface area in dense workstation configurations. Single monitor arms retain the largest installed base in legacy corporate refresh cycles, though dual monitor arms are capturing the fastest growth trajectory as hybrid work policies normalize multi-screen setups for knowledge workers. Aluminum material grades command the margin pool due to their strength-to-weight ratio and anodized finish compatibility with premium office furniture aesthetics.
OSHA workplace ergonomics guidelines and the EU-OSHA Framework Directive on workstation minimum safety requirements shape product certification and commercial procurement specifications for adjustable monitor mounting equipment. BIFMA Level and GREENGUARD certifications further constrain material selection and volatile organic compound thresholds for institutional buyers in North America. Stakeholders must monitor evolving EPA and REACH substance restrictions on aluminum finishing chemistries and polymer flame retardants that could force supply chain reformulation or regional product variant proliferation.

Market Dynamics
Corporate IT standardization programs are consolidating vendor relationships for multi-monitor workstation rollouts, compressing procurement cycles and privileging contract furniture channels that bundle monitor arms with seating and desk systems.
Growth Catalysts
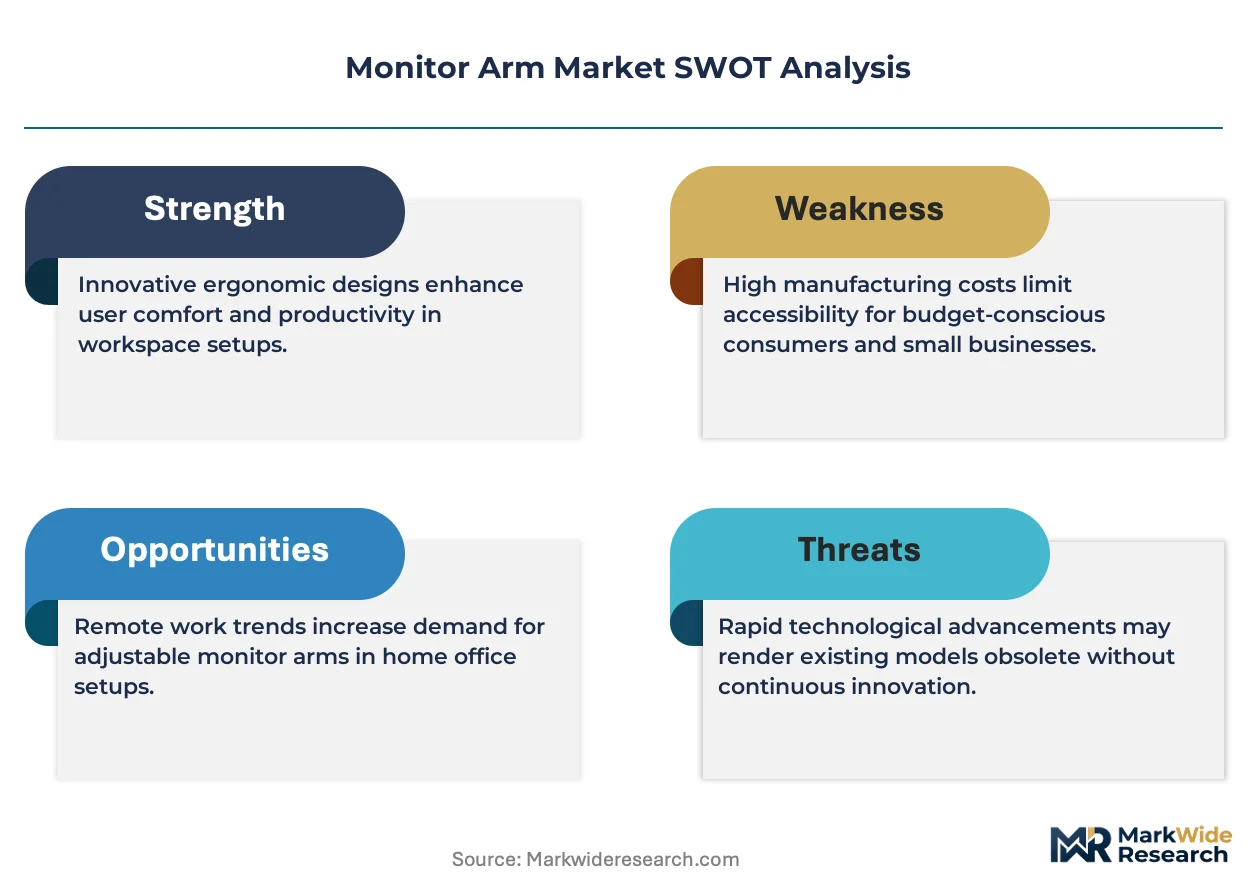
- EU-OSHA Framework Directive:The EU's minimum safety requirements for workstation equipment mandate adjustable monitor positioning in commercial offices, creating procurement pull across Germany, France, and the Netherlands.
- Gas-spring articulation:Advances in counterbalance mechanism precision enable single-hand adjustment across extended reach ranges, satisfying clinical and command-center applications where rapid repositioning is critical.
- Hybrid work normalization:Knowledge worker policies in North American technology and financial services sectors are institutionalizing dual-screen setups as baseline productivity infrastructure.
Market Restraints
- Aluminum alloy input volatility:Extruded 6061-T6 and die-cast ADC12 grade pricing fluctuates with LME spot markets, compressing margin pools for mid-tier fabricators without long-term smelter contracts.
- Polymer flame retardant restrictions:EPA and REACH substance limitations on halogenated compounds in joint housings force supply chain reformulation or regional product variant proliferation.
- Fixed workstation substitution:Integrated monitor lifts in height-adjustable desks displace discrete arm purchases in premium furniture specifications.
Strategic Opportunities
- India commercial office buildout:PLI scheme incentives for electronics manufacturing and BIS certification harmonization create entry pathways for aluminum fabrication specialists.
- Cable management convergence:USB-C power delivery and Thunderbolt docking integration into arm chassis eliminates separate power brick purchases, capturing peripheral value pools.
- GREENGUARD certification tailwind:North American institutional buyers now require volatile organic compound thresholds for furniture-adjacent equipment, favoring anodized finish suppliers with verified supply chains.
Industry Challenges
- BIFMA Level certification timelines:Multi-attribute sustainability verification for institutional procurement creates 6-12 month product qualification delays that compress competitive response windows.
- Legacy VESA mount incompatibility:Non-standard hole patterns on ultrawide and curved displays force adapter proliferation and SKU complexity that strains inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monitor Arm Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Monitor Arm, Dual Monitor Arm, Fixed Mount, Articulating Arm Material: Aluminum, Steel, Plastic, Composite End User: Corporate, Home Office, Gaming, Educational Weight Capacity: Up to 10 lbs, 10-20 lbs, 20-30 lbs, Over 30 lbs |
| Companies Covered | North Bayou SA, Eastern Global Corporation, Herman Miller, Inc., Vogel's Products BV, Loctek Ergonomic Technology Corp., Ergotron, Inc., Atdec Pty Ltd, Legrand AV Inc., Humanscale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monitor Arm Market Strategic Shifts & Innovations
Active engineering focus is shifting toward integrated intelligence and material optimization, with mechanical systems absorbing electronic functionality and sustainability protocols reshaping supply base qualification.
Carbon fiber reinforced polymer struts are absorbing load-bearing functions previously assigned to aluminum extrusions in premium monitor arm segments. Corporate procurement teams in financial services and healthcare verticals are specifying these composites for executive and clinical environments where mass reduction enables cantilevered reach extension. The material transition is compressing traditional metalworking supply chains while elevating tier-one composite molders into furniture component supply bases.
REACH substance restrictions on chromium VI in aluminum anodizing chemistries are forcing finish line conversions across European manufacturing footprints. The regulation eliminates hexavalent chromium conversion coatings from Q4 2024, compelling suppliers to validate trivalent chromium or cerium-based alternatives without sacrificing corrosion resistance or aesthetic matching with legacy office furniture. German fabricators with captive surface treatment capacity are accelerating qualification timelines to defend institutional contract positions.
Direct-to-business procurement portals are displacing traditional contract furniture dealer networks for standardized monitor arm specifications. Fortune 500 technology firms with centralized workplace services teams are consolidating global SKU rationalization through vendor-managed inventory arrangements that bypass regional showroom intermediaries. This channel compression is most visible in North American and UK markets where hybrid work policies have normalized remote specification and direct fulfillment to distributed employee locations.
Monitor Arm Market Segmentation
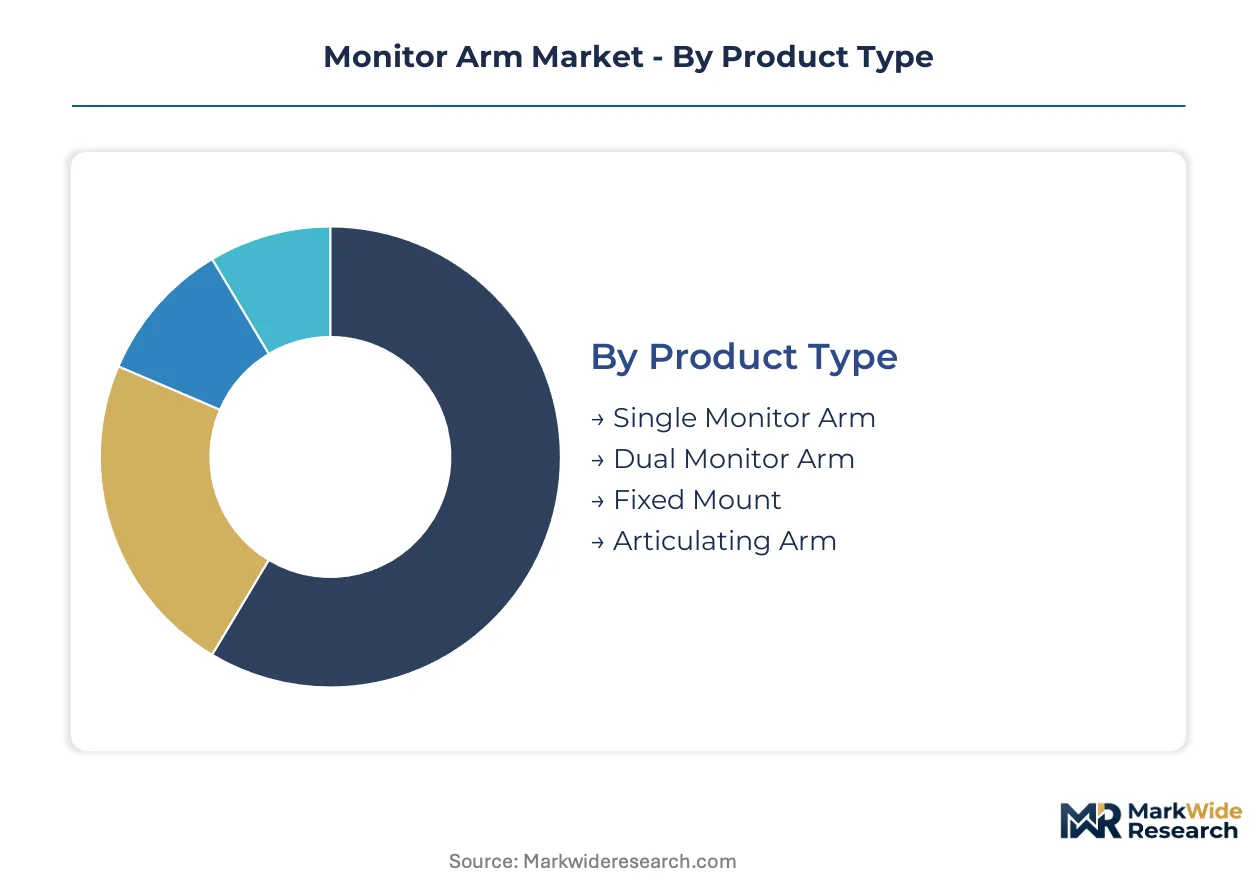
Procurement teams evaluate monitor arms across multiple technical and commercial dimensions, balancing ergonomic compliance requirements against workstation density constraints and material durability specifications. Understanding how demand fragments across these axes reveals where margin pools concentrate and which specifications command pricing premiums in institutional contracts.
Product Type:
Corporate IT standardization programs prioritize installation flexibility and future-proofing against evolving multi-monitor policies.
- Single Monitor Arm:Extruded aluminum construction with gas-spring counterbalance dominates legacy corporate refresh cycles. Demand concentrates in German commercial offices where EU-OSHA Framework Directive mandates adjustable positioning for extended computer use.
- Dual Monitor Arm:Twin-articulating mechanisms with independent pivot joints accommodate asymmetric screen sizes. North American technology and financial services sectors are institutionalizing dual-screen setups as baseline productivity infrastructure, accelerating specification velocity.
- Fixed Mount:Static bracket systems with tilt-only adjustment serve cost-constrained educational deployments and back-office functions where repositioning frequency is minimal.
- Articulating Arm:Multi-joint gas-spring designs enable single-hand adjustment across extended reach ranges for clinical and command-center applications requiring rapid repositioning.
Volume sits with Single Monitor Arm; growth tilts toward Dual Monitor Arm.
Material:
Supply chain qualification timelines and surface treatment chemistry regulations shape sourcing decisions across fabrication tiers.
- Aluminum:Extruded 6061-T6 and die-cast ADC12 grades deliver strength-to-weight ratios essential for cantilevered reach. REACH substance restrictions on chromium VI in anodizing chemistries are forcing European finish line conversions without sacrificing corrosion resistance.
- Steel:Die-cast and stamped configurations anchor high-load segments where mass tolerance permits, though LME spot market volatility compresses margin pools for mid-tier fabricators lacking long-term smelter contracts.
- Plastic:Glass-filled nylon joint housings reduce component cost but face EPA and REACH limitations on halogenated flame retardants.
- Composite:Carbon fiber reinforced polymer struts are absorbing load-bearing functions in premium segments where mass reduction enables extended cantilevered reach.
Aluminum commands institutional specification; Composite is climbing the fastest as financial services and healthcare verticals prioritize mass reduction.
End User:
Procurement authority and compliance sensitivity vary dramatically across buyer types, from centralized workplace services teams to individual consumers.
- Corporate:Fortune 500 technology firms consolidate global SKU rationalization through vendor-managed inventory arrangements that bypass regional showroom intermediaries. GREENGUARD certification thresholds constrain volatile organic compound specifications.
- Home Office:Direct-to-business procurement portals displace traditional contract furniture dealer networks for standardized specifications, with remote fulfillment to distributed employee locations accelerating channel compression.
- Gaming:RGB-integrated chassis and extended reach specifications target enthusiast segments where aesthetic differentiation supports premium pricing.
- Educational:BIFMA Level multi-attribute sustainability verification creates qualification delays that strain competitive response windows in institutional procurement cycles.
Corporate anchors revenue concentration; Home Office is expanding most quickly as hybrid work policies normalize.
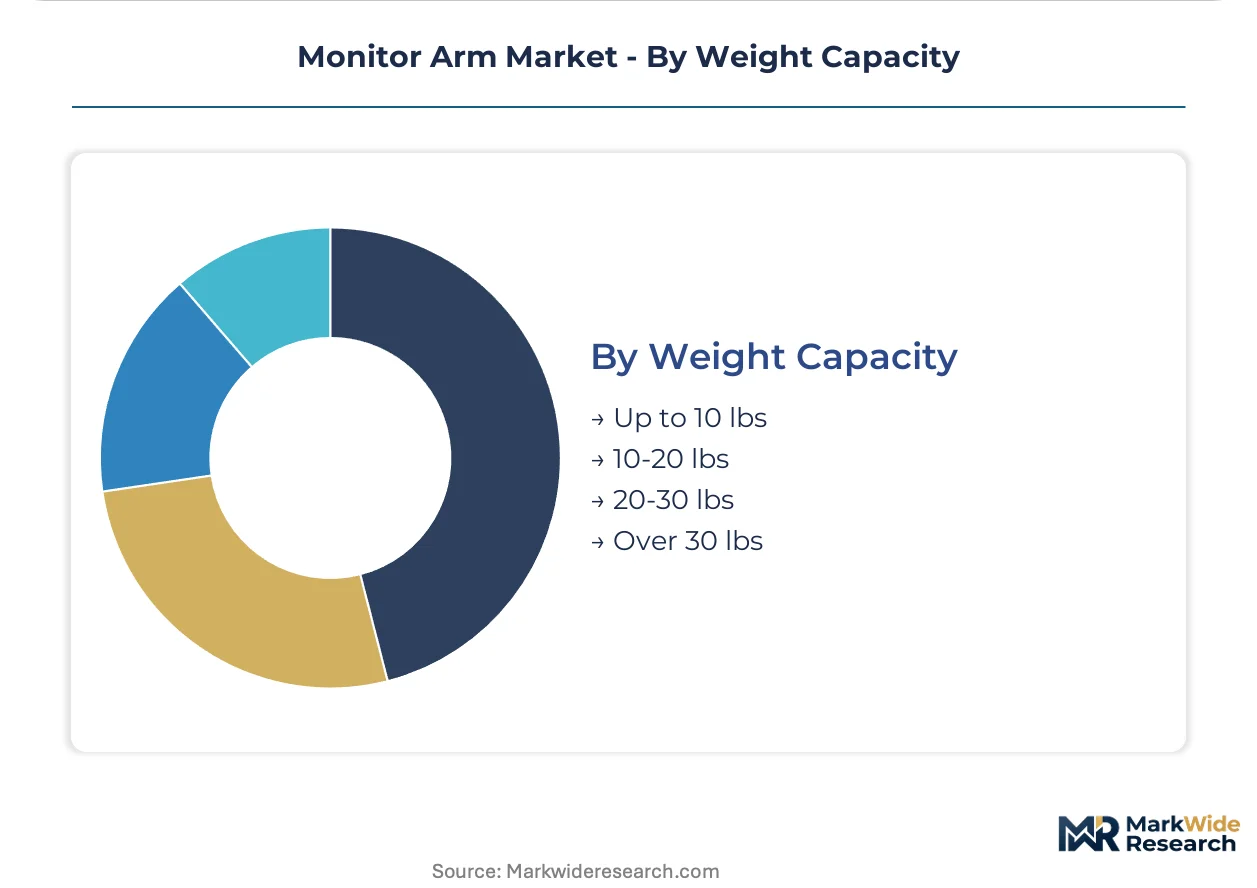
Weight Capacity:
Display technology evolution toward larger panels and curved ultrawide formats is shifting mechanical load requirements upward.
- Up to 10 lbs:Legacy LCD specifications retain installed base in back-office refresh cycles but face displacement as panel sizes increase.
- 10-20 lbs:Standard 24-27 inch commercial displays dominate current corporate deployments, with VESA mount compatibility challenges forcing adapter proliferation.
- 20-30 lbs:Ultrawide and curved display segments require reinforced gas-spring mechanisms and extended joint durability testing.
- Over 30 lbs:Large-format clinical and command-center displays command specialized engineering with premium pricing stratification.
10-20 lbs holds current specification majority; 20-30 lbs is gaining share fastest as display formats diversify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum smelter capacity in China anchors the raw material foundation for monitor arm fabrication, with extrusion mills in Guangdong and Zhejiang provinces supplying semi-finished feedstock to component manufacturers worldwide.
United States
Fortune 500 technology firms in Seattle and Austin are consolidating global SKU rationalization through vendor-managed inventory arrangements. OSHA workplace ergonomics guidelines mandate adjustable workstation components in commercial offices. The Pacific Northwest corridor hosts workplace services teams directing remote fulfillment to distributed employee locations.
Germany
EU-OSHA Framework Directive enforcement drives procurement pull for adjustable monitor positioning in Frankfurt and Munich commercial districts. REACH substance restrictions on chromium VI in anodizing chemistries are compelling finish line conversions. Bavarian fabricators with captive surface treatment capacity are accelerating qualification timelines to defend institutional contract positions.
China
Private-label manufacturing contracts from North American distributors concentrate demand in Shenzhen and Dongguan electronics corridors. MIIT standards for office equipment safety shape export certification requirements. Yangtze River Delta extrusion specialists are absorbing carbon fiber composite molding capabilities for premium segment supply.
India
BIS certification harmonization and PLI scheme incentives for electronics manufacturing are creating entry pathways for aluminum fabrication specialists. Commercial office buildout in Bangalore and Hyderabad is accelerating specification velocity. Mumbai-based procurement teams are consolidating vendor relationships for standardized workstation rollouts.
United Kingdom
Hybrid work policies in London financial services are normalizing dual-screen setups as baseline productivity infrastructure. Contract furniture dealer networks are experiencing channel compression from direct-to-business procurement portals. The Southeast England corridor hosts workplace strategy teams managing distributed fulfillment logistics.
Monitor Arm Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue composite material specialization and integrated cable management systems. The vendor base clusters around three maturity tiers: legacy contract furniture channels with bundled workstation offerings, independent ergonomic specialists with gas-spring articulation expertise, and high-volume Asian fabricators serving private-label contracts. Three strategic archetypes dominate: premium-tier brands leveraging certification compliance, scale-driven manufacturers optimizing aluminum extrusion economics, and regional specialists capturing institutional procurement proximity. Competitive moves concentrate on M&A for captive surface treatment capacity and strategic partnerships for USB-C power delivery integration.
Among North American ergonomic specialists, Herman Miller, Inc. and Ergotron, Inc. exemplify divergent positioning archetypes within the premium tier. Herman Miller occupies a position leveraging contract furniture channel dominance for bundled workstation system sales. Ergotron represents technology leadership in articulating gas-spring mechanisms for clinical applications. Loctek Ergonomic Technology Corp. anchors the scale-driven archetype among Asia-Pacific fabricators, exemplifying high-volume manufacturing capacity for private-label and direct-to-business contracts.
| Leading Market Players |
|---|
| North Bayou SA |
| Eastern Global Corporation |
| Herman Miller, Inc. |
| Vogel's Products BV |
| Loctek Ergonomic Technology Corp. |
| Ergotron, Inc. |
| Atdec Pty Ltd |
| Legrand AV Inc. |
| Humanscale |
| Others |
Cost & Logistics Intelligence
GREENGUARD certification thresholds gate qualified supply access and premium-tier pricing power for North American institutional buyers sourcing furniture-adjacent equipment. REACH substance restrictions on chromium VI in anodizing chemistries further constrain European supplier pools, compressing margin recovery for mid-tier fabricators lacking verified finish-line alternatives.
Pricing Analysis
Volume concentrates in standardized single-arm configurations while margin pools accrue to dual-arm articulating systems with integrated cable management. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales bundling intensity. Cost compression in mid-tier aluminum extrusion runs through LME spot market volatility without long-term smelter contract protection. Educational procurement teams exhibit highest price sensitivity; clinical command-center buyers demonstrate lowest sensitivity due to rapid-repositioning performance requirements.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for electronics-adjacent fabrication, pulling assembly capacity toward Bangalore and Hyderabad corridors. Raw material flows draw from Chinese aluminum smelter capacity in Guangdong and Zhejiang provinces, German captive surface treatment operations, and Yangtze River Delta carbon fiber composite molders. Single-source vulnerability concentrates in European anodizing chemistry conversion timelines ahead of Q4 2024 REACH enforcement. Distribution runs through vendor-managed inventory arrangements that displace regional contract furniture dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU-OSHA Framework Directive enforcement creates a barrier-to-entry moat favoring incumbents with captive certification infrastructure.
For Market Incumbents: Deploy captive surface treatment capacity acceleration to defend German institutional contract positions against REACH-driven supplier attrition. Backward integration into aluminum extrusion secures margin pools against LME volatility. Integrated monitor lifts in height-adjustable desks pose substitution threat requiring dual-arm articulation performance differentiation. For New Entrants and Emerging Players: Direct-to-business procurement portals offer lowest-friction entry path around compressed contract furniture dealer networks. Target India commercial office buildout in Bangalore and Hyderabad where BIS harmonization creates qualification parity with established suppliers. USB-C power delivery integration into arm chassis captures peripheral value pools with minimal mechanical engineering heritage requirements. For Investors and Strategic Acquirers: German fabricator consolidation announcements signal leading indicator that European supply base rationalization is accelerating. Five-to-ten-year viability favors scale-driven manufacturers with aluminum extrusion economics and verified GREENGUARD supply chains. Carbon fiber composite molding capability acquisition targets command premium positioning in financial services and healthcare verticals.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Surface Treatment Capacity Expansion | REACH chromium VI restrictions force finish-line ownership to defend EU-OSHA contract positions. |
| USB-C Power Delivery Integration | Thunderbolt docking convergence eliminates separate power brick purchases in corporate IT specifications. |
| Carbon Fiber Composite Molding Partnership | Mass reduction enables cantilevered reach extension for clinical and executive environments. |
| Vendor-Managed Inventory Arrangement | Fortune 500 workplace services teams consolidate global SKU rationalization through direct fulfillment. |
| India PLI Scheme Manufacturing Footprint | BIS certification harmonization creates entry pathways for aluminum fabrication specialists in commercial office buildout. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across workplace services directors, contract furniture procurement leads, aluminum extrusion plant managers, ergonomic equipment distributors, and clinical facility biomedical engineers. OSHA workplace guidelines, EU-OSHA Framework Directive enforcement records, EPA substance restriction dockets, and BIFMA Level certification databases supplied regulatory validation. Bottom-up shipment data triangulated against top-down corporate IT spend estimates.
Granularity-level modeling addressed product type, material grade, end-user vertical, weight capacity tier, and regional regulatory cluster across the analysis window. CAGRs derived from segment-level volume trajectories weighted by aluminum input cost assumptions and certification compliance timelines. Forecast inputs incorporated hybrid work policy persistence rates and display technology evolution toward ultrawide formats.
The model holds under stable regulatory enforcement timelines and sustained corporate IT standardization programs; deviation in REACH substance restriction acceleration or integrated desk lift substitution velocity would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Mining Automation Systems Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Smart Escalator Market
Industrial Automation
Global Intelligent Process Automation Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
UV Curing System Market
Industrial Automation
Global Robotic Laser Cutting Machine Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
North America Smart Manufacturing Market
Industrial Automation
Intralogistics Market