
 Connected Worker Market | 2026-2036
Connected Worker Market Size, Share, and Industry Trends Forecast 2026-2036
Connected Worker Market Analysis
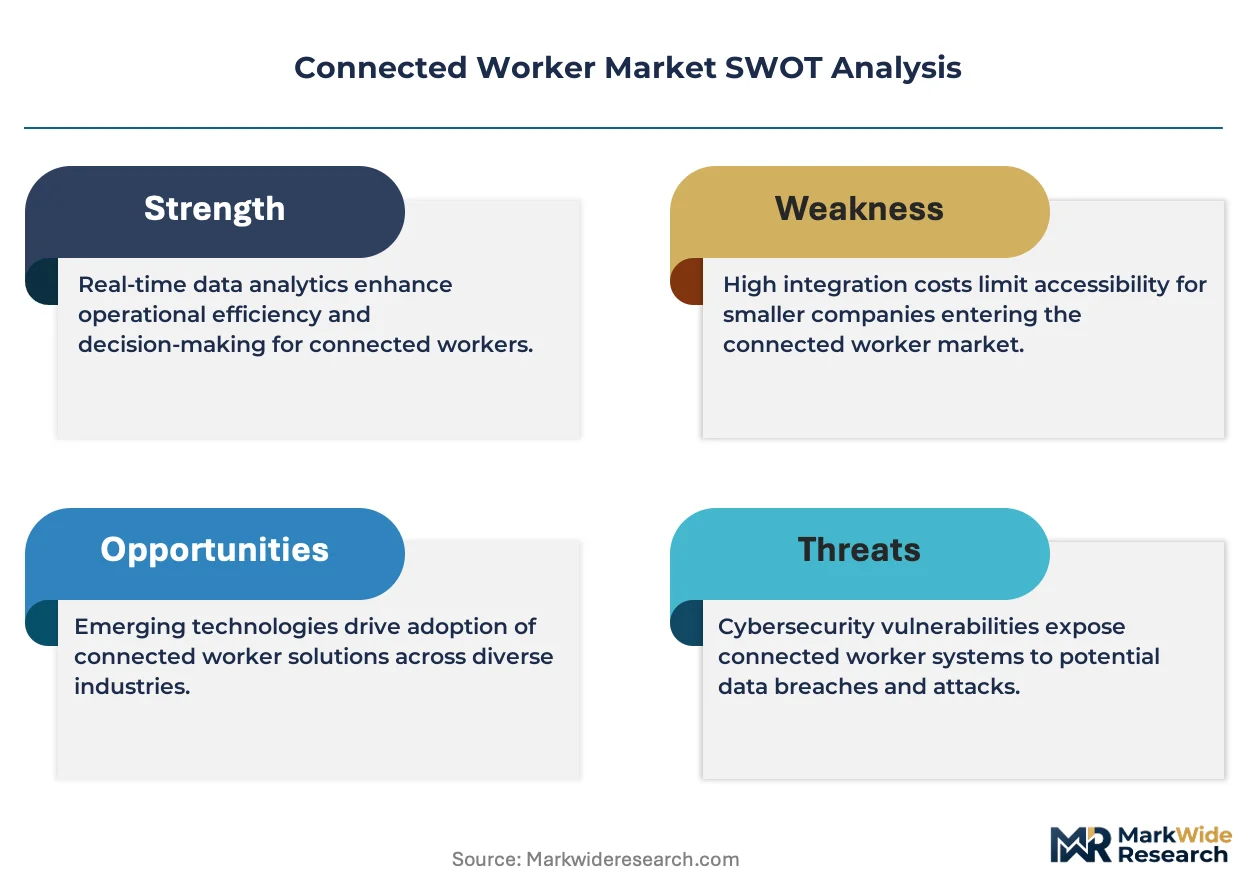
Project finance and leasing arrangements for industrial IoT infrastructure is fragmenting competitive dynamics, allowing mid-sized manufacturers to deploy connected worker platforms without heavy capex burdens. Honeywell International Inc leverages its established industrial automation installed base to cross-sell safety management solutions. Siemens anchors European demand through its digital twin integrations with wearable data streams. Zebra Technologies Corp. specializes in ruggedized mobile hardware that dominates logistics and warehouse environments.
A connected worker system comprises wearable sensors, augmented reality interfaces, mobile applications, and real-time communication platforms that capture biometric, environmental, and operational data to enhance safety, productivity, and decision-making on industrial work sites. These systems typically process telemetry at sub-second latency to trigger automated alerts or workflow adjustments. Wearable Devices and Communication Platforms represent the most mature technology segments with established hardware supply chains, while Edge Computing deployments are expanding fastest as manufacturers seek to reduce cloud dependency for latency-critical safety alerts. Real-Time Monitoring solutions command premium positioning due to their direct linkage with incident prevention and insurance cost reduction.
OSHA mandates continuous hazard monitoring in heavy industries, directly expanding the addressable base for safety management solutions. The EU AI Act imposes conformity requirements on algorithmic decision systems used for worker performance evaluation, reshaping product development priorities for European deployments. FDA oversight of connected health wearables in clinical settings creates a parallel compliance pathway for healthcare end users. Stakeholders must evaluate whether to build in-house edge analytics capabilities or partner with established platform providers as regulatory complexity intensifies.
Market Dynamics
OSHA workplace safety mandates and the EU AI Act's algorithmic transparency requirements are compressing deployment timelines for connected worker platforms, forcing manufacturers to accelerate compliance-oriented implementations while integrating edge computing capabilities for latency-critical safety alerts.
Growth Catalysts
- OSHA Continuous Hazard Monitoring Mandates:Heavy industries in the United States face expanded requirements for real-time environmental and biometric tracking, directly enlarging the addressable base for wearable sensor deployments.
- Smart Factory Integration:Manufacturing floors across Germany's industrial belt are embedding augmented reality headsets and wearable sensors into daily operations as part of digital twin implementations.
- EU AI Act Conformity Requirements:Algorithmic decision systems used for worker performance evaluation in European deployments must meet new transparency standards, reshaping product development priorities and accelerating platform upgrades.
Market Restraints
- Edge Hardware Cost Structure:Ruggedized wearable sensors and augmented reality headsets require specialized semiconductor components whose supply concentrates among Asian foundries, creating input cost volatility.
- Cloud Dependency Technical Limitation:Sub-second latency requirements for automated safety alerts cannot reliably be met through centralized cloud architectures, forcing costly distributed infrastructure investments.
- FDA Parallel Compliance Pathway:Connected health wearables in clinical settings face dual oversight requirements that extend certification timelines and complicate cross-vertical platform standardization.
Strategic Opportunities
- Project Finance and Leasing Arrangements:Mid-sized manufacturers can deploy connected worker platforms without heavy capital expenditure burdens through infrastructure-as-a-service models fragmenting competitive dynamics.
- Automotive and Chemical Vertical Convergence:Germany's automotive giants and chemical producers anchor large-scale implementations that create reference architectures transferable to process industries in France and Italy.
- Logistics and Warehouse Channel Expansion:Ruggedized mobile hardware specialized for these environments opens distribution pathways beyond traditional industrial automation channels.
Industry Challenges
- Edge Analytics Talent Scarcity:Manufacturers struggle to recruit personnel capable of building in-house telemetry processing capabilities as regulatory complexity intensifies around algorithmic transparency.
- Legacy System Integration Friction:Real-time communication platforms must interface with decades-old manufacturing execution systems and enterprise resource planning infrastructure without disrupting continuous operations.
- Cross-Border Certification Timeline Compression:Platform providers face divergent conformity assessment procedures between OSHA mandates, EU AI Act requirements, and FDA oversight pathways that delay multi-territory rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connected Worker Market |
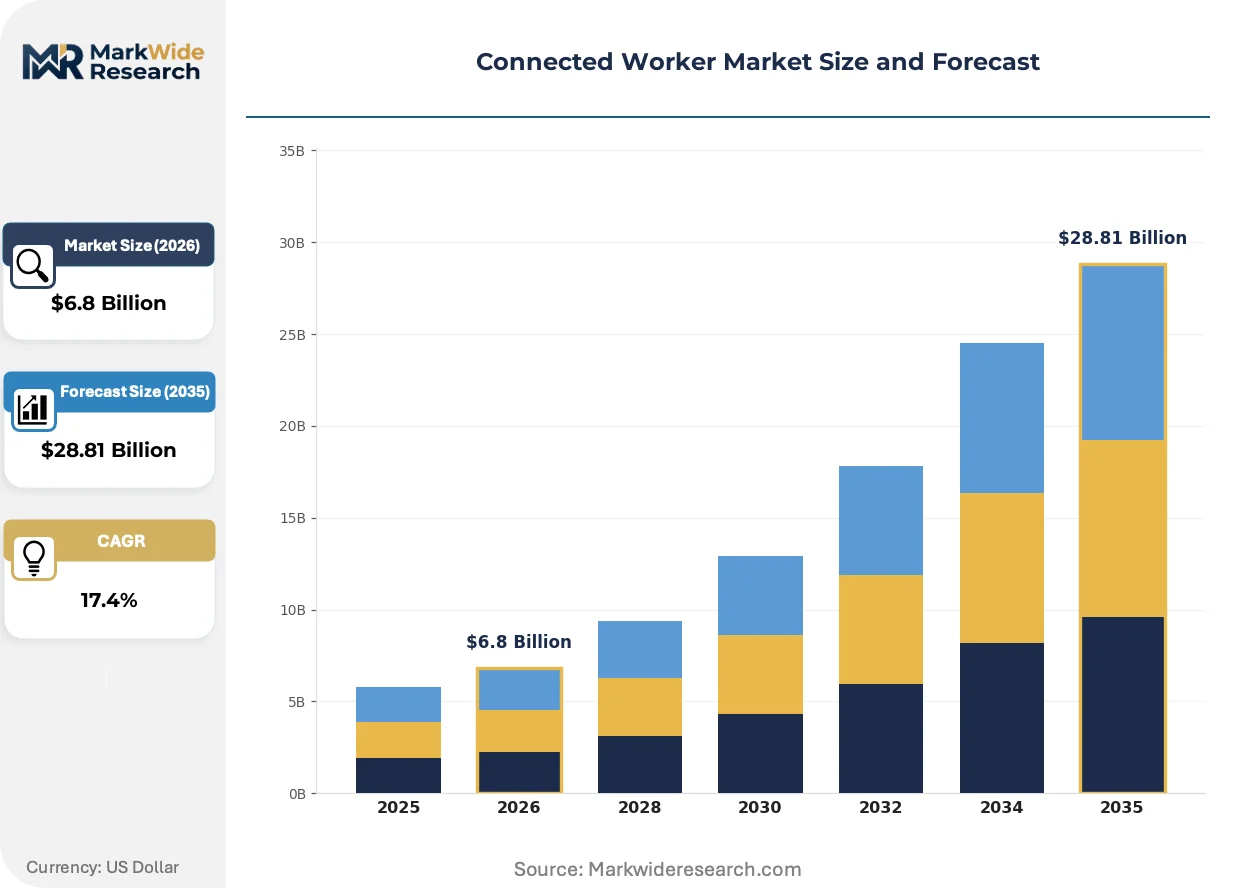
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Wearable Devices, Mobile Applications, Connected Tools, Communication Platforms End User: Manufacturing, Healthcare, Construction, Transportation Solution: Real-Time Monitoring, Safety Management, Workflow Optimization, Data Analytics Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Honeywell International Inc, Zebra Technologies Corp., Microsoft, Siemens, Schneider Electric, PTC, Accenture, 3M Company, Hexagon AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connected Worker Market Emerging Trajectories
Edge computing architectures are displacing cloud-centric processing models as manufacturers prioritize sub-second latency for safety-critical applications. Three interconnected developments are reshaping technology roadmaps and competitive positioning across the connected worker ecosystem.
Wearable sensor telemetry processing is migrating from centralized cloud infrastructure to on-premise edge nodes. Automotive and chemical producers in Germany's Ruhr industrial cluster are deploying localized analytics engines to trigger automated workflow adjustments without network latency. This compression of decision loops is enabling real-time incident prevention that was previously technically infeasible.
The EU AI Act imposes conformity requirements on algorithmic systems evaluating worker performance, creating a compliance architecture that European manufacturers must embed into platform designs. Industrial software vendors are restructuring product development priorities to accommodate algorithmic transparency mandates and audit trail documentation. Safety management solutions with embedded explainability features command premium positioning in German, French, and Italian procurement evaluations.
Mid-sized manufacturers are adopting infrastructure-as-a-service procurement models that unbundle hardware acquisition from software licensing and ongoing platform management. This channel innovation displaces traditional capital expenditure cycles and expands addressable demand beyond Fortune 500 industrial conglomerates. The shift is most visible in logistics and warehouse environments where operational technology budgets face heightened scrutiny.
Connected Worker Market Segmentation
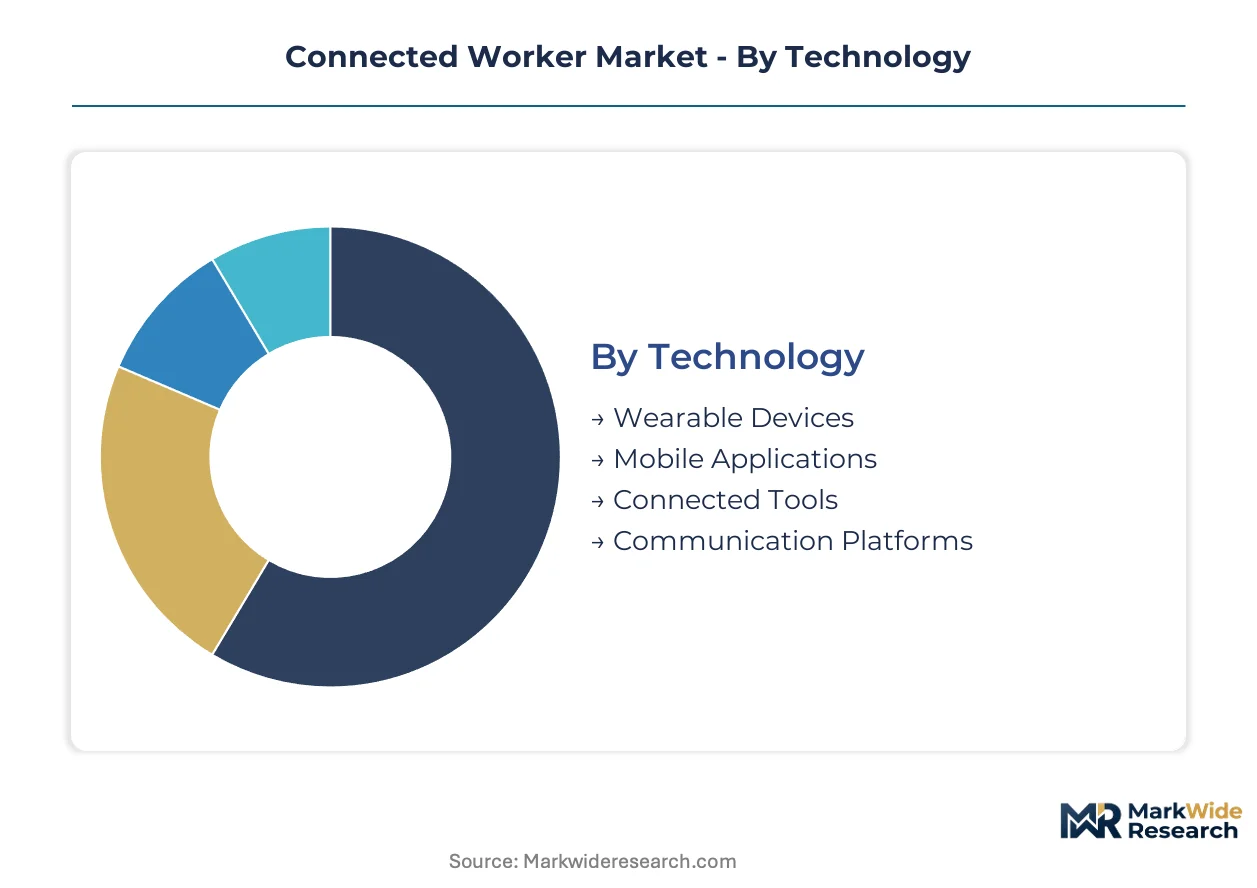
Connected worker platforms serve heterogeneous operational environments where technology maturity, regulatory exposure, and infrastructure readiness diverge sharply across verticals. Segmentation reveals how procurement patterns cluster around latency requirements, compliance burdens, and legacy system constraints rather than uniform feature sets.
Technology:
Wearable sensors and AR interfaces sit at opposite ends of the maturity spectrum, with communication platforms occupying the middle ground where standardization has stabilized.
- Wearable Devices:Biometric and environmental sensors embedded in hard hats, vests, and wristbands capture telemetry for hazard detection. Demand concentrates in German automotive and chemical plants where OSHA-equivalent safety mandates require continuous physiological monitoring. Supply chain concentration in Asian semiconductor foundries creates input cost volatility for ruggedized components.
- Communication Platforms:Real-time voice, video, and messaging infrastructure enables coordination across distributed work sites. Manufacturing floors in the US Midwest and Germany's Ruhr cluster anchor procurement volumes as smart factory integration accelerates.
- Mobile Applications:Task management and digital work instruction software running on ruggedized handhelds.
- Connected Tools:Power tools and equipment with embedded telemetry for usage tracking and predictive maintenance.
Wearable Devices retains volume leadership; Connected Tools holds the steepest expansion curve.
End User:
Cost tier stratification separates heavy industrial deployments from lighter administrative implementations, with construction occupying a mid-tier position where equipment durability premiums apply.
- Manufacturing:Smart factory environments integrate connected worker platforms with digital twin systems and manufacturing execution software. Automotive producers in Germany and process manufacturers in the US Gulf Coast drive specification requirements for sub-second latency safety alerts.
- Healthcare:Clinical settings deploy connected health wearables under FDA oversight, creating dual compliance pathways that extend certification timelines. Hospital systems prioritize biometric monitoring for patient-facing staff and lone worker safety applications.
- Construction:Job sites require ruggedized hardware resistant to dust, moisture, and impact damage.
- Transportation:Logistics and warehouse operators leverage mobile scanning and voice-directed workflows.
Manufacturing dominates procurement value; Healthcare is climbing the fastest as clinical compliance frameworks mature.
Solution:
Application criticality determines margin structure, with incident-prevention solutions commanding premiums over retrospective analytics.
- Real-Time Monitoring:Continuous telemetry processing with automated alert generation for environmental hazards, biometric anomalies, and geofence violations. Insurance cost reduction and regulatory compliance in heavy industries justify premium positioning.
- Safety Management:Incident documentation, evacuation coordination, and emergency response automation. EU AI Act transparency requirements reshape product development priorities for European deployments.
- Workflow Optimization:Digital work instructions and task sequencing for productivity gains.
- Data Analytics:Retrospective performance evaluation and operational intelligence dashboards.
Real-Time Monitoring captures the highest margins; Safety Management is gaining share fastest as algorithmic accountability mandates spread.
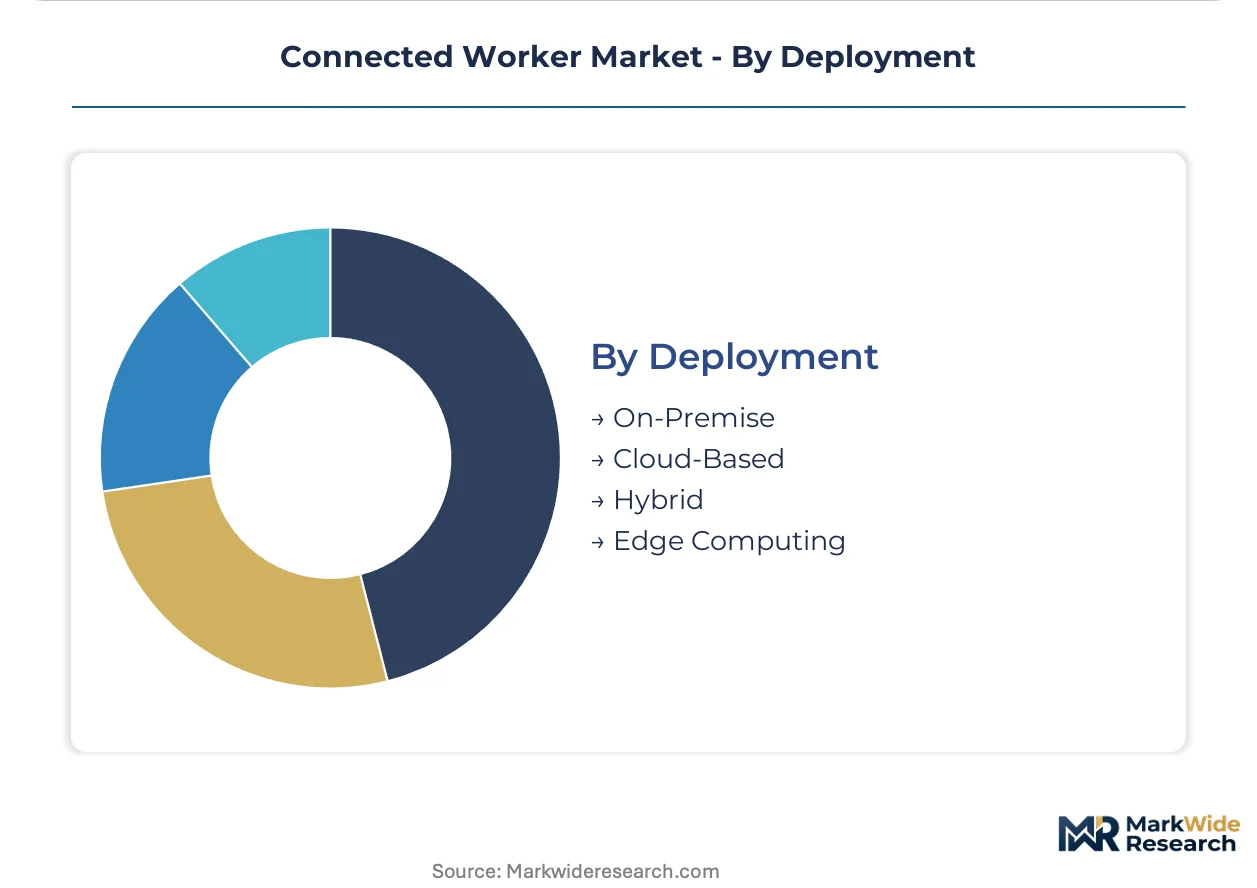
Deployment:
Customer type divides the market between capital-rich conglomerates favoring on-premise control and mid-sized manufacturers seeking operational expenditure flexibility.
- Edge Computing:Localized processing nodes enable sub-second latency for safety-critical applications without cloud dependency. German automotive and chemical producers in the Ruhr industrial cluster deploy localized analytics to trigger automated workflow adjustments.
- Cloud-Based:Centralized infrastructure suits non-latency-sensitive applications with lower data sovereignty requirements. Mid-sized manufacturers adopt infrastructure-as-a-service models to avoid heavy capital expenditure burdens.
- On-Premise:Self-managed servers for organizations with strict data residency requirements.
- Hybrid:Architectures splitting latency-sensitive workloads to edge nodes and archival storage to cloud.
Edge Computing leads technology investment; Cloud-Based maintains the broadest addressable base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates in the United States and the EU AI Act's algorithmic transparency requirements are compressing deployment timelines across industrialized economies. Regulatory pressure is reshaping procurement patterns in manufacturing belts where safety-critical applications dominate.
United States
OSHA continuous hazard monitoring mandates expand the addressable base for wearable sensor deployments in heavy industries. The Department of Labor enforces strict penalties for non-compliance in oil and gas operations along the Gulf Coast. Houston anchors large-scale implementations where process manufacturers integrate biometric tracking with legacy distributed control systems.
Germany
Automotive and chemical producers in the Ruhr industrial cluster drive specification requirements for sub-second latency safety alerts. The EU AI Act imposes conformity requirements on algorithmic decision systems used for worker performance evaluation. Stuttgart and Leverkusen host reference architectures that create transferable deployment models for French and Italian process industries.
China
Smart factory integration accelerates as MIIT promotes digital twin implementations across state-owned manufacturing enterprises. GB standards for industrial IoT interoperability create compliance pathways for domestic platform providers. The Yangtze River Delta concentration of electronics assembly plants generates volume demand for ruggedized mobile hardware and edge computing nodes.
Japan
METI industrial productivity initiatives subsidize connected worker deployments in aging workforce environments. JIS standards for wearable device electromagnetic compatibility streamline certification for domestic manufacturers. The Nagoya automotive corridor implements augmented reality headsets for assembly line quality assurance and technician training programs.
India
PLI scheme incentives for electronics manufacturing attract connected worker platform deployments in greenfield facilities. The country's national workplace safety regulator is drafting mandatory hazard monitoring rules for construction and mining operations. Gujarat and Tamil Nadu industrial zones pioneer infrastructure-as-a-service procurement models that bypass traditional capital expenditure cycles.
Connected Worker Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: diversified industrial conglomerates with installed base advantages, specialized hardware vendors with ruggedized form factors, and enterprise software providers with cloud-native architectures. Two dominant competitive moves define current positioning: cross-selling safety management solutions through existing automation relationships, and infrastructure-as-a-service offerings that fragment competitive dynamics by reducing customer capex barriers.
Within the industrial conglomerate tier, Honeywell International Inc and Siemens exemplify platform providers leveraging established automation footprints to bundle connected worker solutions. Zebra Technologies Corp. occupies a distinct position among hardware specialists, its ruggedized mobile equipment dominating logistics and warehouse channels where operational technology budgets face heightened scrutiny.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Zebra Technologies Corp. |
| Microsoft |
| Siemens |
| Schneider Electric |
| PTC |
| Accenture |
| 3M Company |
| Hexagon AB |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwanese semiconductor foundries for ruggedized sensor components determines both tiered pricing spreads and supply chain resilience investments across connected worker platform providers. This concentration forces buyers into multi-year contracting with volume commitments or premium spot-market exposure.
Pricing Analysis
Certification level creates the primary spread between OSHA-compliant safety systems and uncertified productivity tools. Three-tier pricing structure across premium, standard, and economy levels reflects FDA-grade health wearables, CE-marked industrial sensors, and unvalidated mobile applications. Cost compression in the economy tier is intensifying because Asian hardware vendors are flooding logistics channels with non-ruggedized alternatives. Mid-sized manufacturers show the highest price sensitivity, while German automotive producers accept premiums for sub-second latency guarantees.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for augmented reality headsets and edge computing nodes. Component supply draws from Taiwan, South Korea, and Vietnam for specialized semiconductors, display panels, and battery cells. Single-source vulnerability concentrates in gallium nitride power management chips essential for wearable thermal efficiency. Distribution runs through industrial automation channel partners with certified installation capabilities rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected worker platforms are approaching a platform-economics inflection where interoperability standards determine winner-take-most dynamics. The convergence of digital twin protocols with wearable data streams is restructuring ecosystem value capture.
For Market Incumbents: Harden installed-base defenses through backward integration into edge analytics silicon and exclusive certification partnerships with OSHA-authorized testing laboratories. Cross-sell safety management modules to existing automation customers before cloud-native competitors establish API interoperability. Prioritize captive supply of ruggedized sensors to neutralize Asian hardware commoditization threats.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electronics manufacturing facilities where greenfield infrastructure-as-a-service procurement bypasses legacy vendor lock-in. Target construction verticals in the US Gulf Coast where OSHA enforcement gaps create temporary compliance arbitrage opportunities. Lead with voice-directed workflow applications that require minimal edge infrastructure investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated platform providers with regulatory certification depth. Long-term viability across the analysis window hinges on algorithmic explainability capabilities mandated by the EU AI Act. Monitor FDA breakthrough device designations for connected health wearables as the inflection signal for healthcare vertical expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Infrastructure Deployment | Localized processing nodes in Germany's Ruhr cluster enable sub-second safety alerts without cloud dependency. |
| Algorithmic Transparency Certification | EU AI Act compliance investments differentiate European platform providers in procurement evaluations. |
| Infrastructure-as-a-Service Partnership | Leasing arrangements fragment competitive dynamics by removing capital expenditure barriers for mid-sized manufacturers. |
| Digital Twin Protocol Integration | Siemens and Honeywell leverage automation installed bases to bundle wearable data streams with existing MES systems. |
| Ruggedized Hardware Specialization | Zebra Technologies dominates logistics channels where dust-resistant mobile computers command durability premiums. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers, safety compliance officers, industrial IoT procurement managers, and edge computing architects and refined through secondary validation. Stakeholder interviews combined with customs data for ruggedized hardware imports, OSHA enforcement action records, EU AI Act implementation guidance documents, and SEC 10-K filings from industrial automation providers. Bottom-up unit economics for wearable sensor deployments were triangulated against top-down market sizing from manufacturing value-added estimates.
Demand-supply balance framing anchored the forecast framework across the projection horizon. Segmentation dimensions modeled include technology maturity tier, end-user industry vertical, deployment architecture, and regulatory compliance cluster. CAGRs were derived from adoption curve analysis calibrated to OSHA mandate implementation timelines and EU conformity assessment procedure completion rates. Industry-specific inputs incorporated digital twin integration penetration in German automotive and edge node deployment density in US process manufacturing.
Stress conditions across semiconductor supply disruption severity, tariff rate volatility, and regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about OSHA enforcement intensity and EU AI Act audit frequency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
South East Asia Warehouse Automation Market
Industrial Automation
Global Discrete Automation Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Agricultural Automation Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Europe Retail Automation Market