
 Florida Augmented and Virtual Reality Market | 2026-2036
Florida Augmented and Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Florida Augmented and Virtual Reality Market Insights
Specialized immersive technology talent is reorganizing how Florida studios scale project delivery. Lucid Reality Labs leverages its simulation expertise to anchor defense contracts across the southeastern United States. Covalent Reality differentiates through architectural visualization workflows that dominate Miami-Dade property marketing. AVT Simulation sustains long-term training system partnerships with military installations throughout the Florida peninsula.
Florida augmented and virtual reality encompasses head-mounted displays, spatial computing software, and haptic feedback systems that overlay or replace physical environments with digitally rendered sensory input, typically operating at 90 frames per second to prevent motion disorientation in professional training contexts. These technologies serve commercial visualization, experiential entertainment, and mission-critical rehearsal functions where physical prototyping carries excessive cost or risk. Training simulations command the deepest deployment budgets among application categories, while haptics and gesture recognition represent the fastest-expanding technology layer as industrial clients demand tactile fidelity in remote assistance workflows. Cloud-based deployment models are capturing share from on-premise installations as educational institutions and design studios prioritize scalable subscription access over capital-intensive hardware ownership.
Florida's digital media incentive programs intersect with federal defense procurement standards administered through Orlando-based military contracting offices, creating dual compliance pathways for simulation vendors. The state's consumer protection framework for entertainment venues and OSHA workplace safety guidelines for extended VR sessions shape product liability and insurance requirements for commercial operators. Stakeholders must monitor how Florida's evolving data privacy statutes apply to biometric gaze tracking and spatial mapping data collected during enterprise immersive sessions.
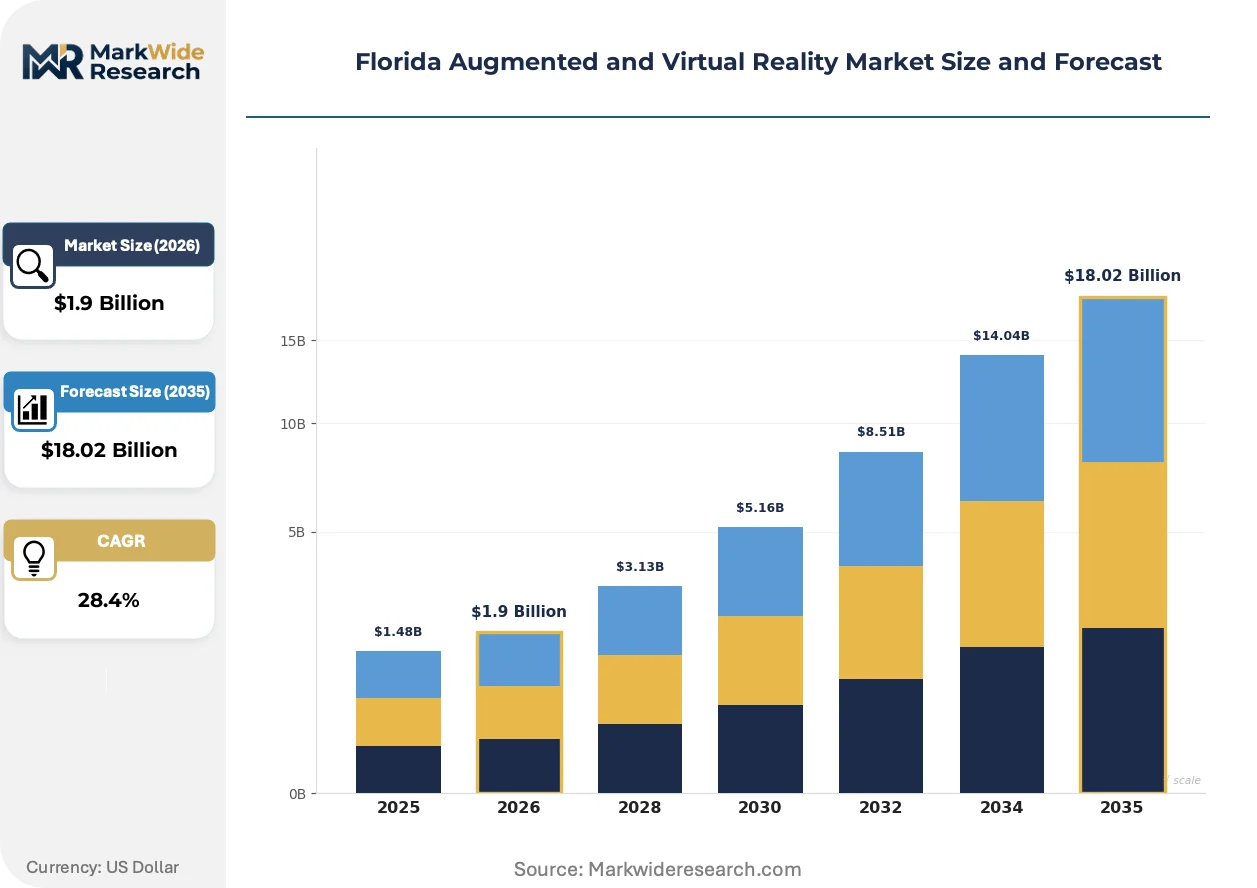
Market Dynamics
Defense procurement consolidation around Orlando military contracting offices is compressing vendor qualification timelines while simultaneously elevating technical compliance thresholds for immersive training systems.
Growth Catalysts
- OSHA workplace safety guidelines:Florida's enforcement of extended VR session protocols validates enterprise adoption by reducing liability exposure for commercial operators deploying head-mounted displays.
- Spatial computing software:Real-time rendering advances at 90 frames per second eliminate motion disorientation barriers that previously limited professional training deployment duration.
- Miami-Dade property marketing:Architectural visualization workflows accelerate pre-construction sales cycles by replacing physical staging with photorealistic virtual walkthroughs.
Market Restraints
- Display panel supply concentration:Micro-OLED fabrication capacity remains captive to Asian foundries, creating input bottlenecks for Florida headset assemblers.
- Biometric data governance:Florida's evolving privacy statutes impose compliance friction on gaze tracking and spatial mapping data collection without clear federal preemption.
- Capital intensity of haptic systems:Force-feedback hardware requires precision manufacturing that local suppliers cannot yet replicate at competitive unit economics.
Strategic Opportunities
- Cloud-based deployment models:Educational institutions across the Florida peninsula prioritize scalable subscription access over capital-intensive hardware ownership.
- Gesture recognition convergence:Computer vision algorithms merge with spatial computing to enable touchless industrial assistance workflows in Tampa manufacturing corridors.
- Film and digital media tax incentives:The state's incentive structure channels production investment toward Orlando immersive content studios seeking qualified spend credits.
Industry Challenges
- Simulation engineer scarcity:Specialized talent capable of integrating physics engines with military training protocols commands premium compensation that strains mid-tier vendor margins.
- Dual compliance pathways:Vendors must simultaneously satisfy state digital media incentive requirements and federal defense procurement standards administered through Orlando contracting offices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Florida Augmented and Virtual Reality Market |
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $18.02 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AR Devices, VR Headsets, Mixed Reality, Haptics, Gesture Recognition Application: Training Simulations, Virtual Tours, Education, Entertainment, Remote Assistance End User: Educational Institutions, Media Production, Defense Organizations, Real Estate Companies, Design Studios Deployment Model: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Cubix, Iron Forge Development, Lucid Reality Labs, Covalent Reality, Parisleaf, Elevux, SoluLab, Infinitas Engineering Inc., AVT Simulation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Florida Augmented and Virtual Reality Market Trends and Innovations
Haptic feedback systems are compressing the tactile fidelity gap between remote assistance and physical presence, while procurement patterns favor subscription economics over ownership.
Varifocal display technology is fragmenting the headset market by eliminating vergence-accommodation conflict that causes eye strain in extended enterprise sessions. Medical training programs at Florida teaching hospitals adopt these systems for surgical simulation curricula. The technology is fragmenting vendor tiers by separating premium optical solutions from commodity fixed-focus hardware.
Florida's consumer protection framework for entertainment venues now mandates biometric data handling disclosures for VR operators collecting gaze tracking information. Commercial venues must implement explicit consent protocols before spatial mapping sessions begin. Miami-based experiential entertainment operators have deployed modified waiver systems to align with these requirements.
Enterprise buyers in Orlando's defense corridor now unbundle hardware procurement from software licensing and ongoing content development. Training simulation contracts separate device delivery from scenario authoring and instructor certification. This unbundling concentrates negotiating leverage with prime contractors while fragmenting subcontractor relationships across specialized capability providers.
Florida Augmented and Virtual Reality Market Segmentation
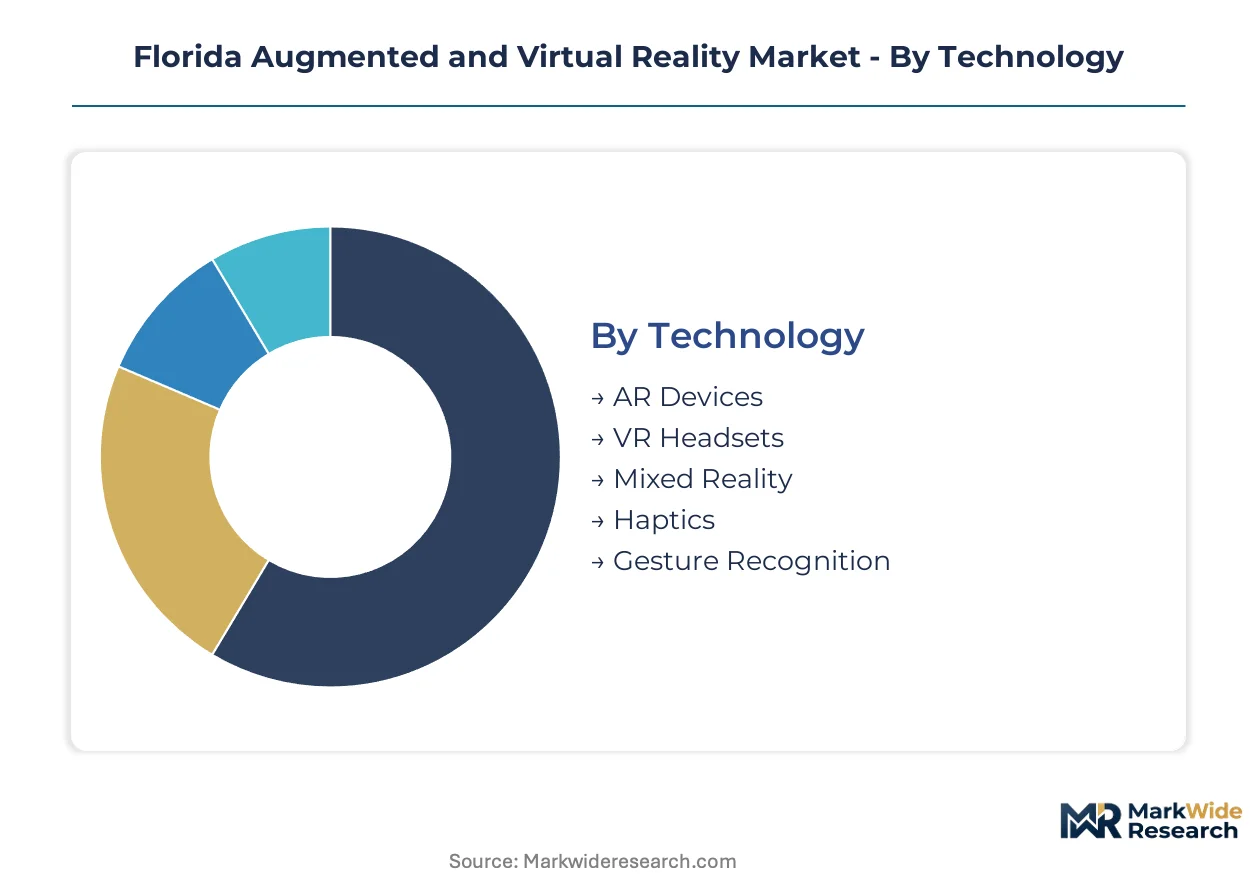
Florida's AR/VR market segments reflect distinct procurement pathways shaped by defense contracting standards, state tax incentive structures, and OSHA workplace safety protocols. Understanding these divisions reveals where compliance complexity concentrates and where deployment economics favor scalable subscription models over capital ownership.
Technology:
OSHA's extended VR session guidelines and federal defense procurement standards administered through Orlando contracting offices create divergent certification requirements across hardware categories.
- VR Headsets:Head-mounted displays operating at 90 frames per second prevent motion disorientation in professional training contexts. Demand concentrates in Orlando's defense corridor where military installations require extended-duration simulation compatibility.
- Haptics:Force-feedback systems deliver tactile fidelity for remote assistance workflows through precision actuators and pressure sensors. Miami-Dade property marketing studios and Tampa manufacturing corridors are expanding adoption fastest as industrial clients demand physical sensation replication without on-site presence.
- AR Devices:Optical see-through displays overlay digital content onto physical environments for maintenance and field service applications.
- Mixed Reality:Passthrough camera systems enable simultaneous physical and digital object manipulation.
- Gesture Recognition:Computer vision algorithms enable touchless control interfaces for hygienic industrial environments.
Established volume favors VR Headsets; emerging adoption favors Haptics.
Application:
Cost tier differentiation separates mission-critical military systems from commercial visualization tools with vastly different margin structures and contract durations.
- Training Simulations:Physics-engine environments replicate combat scenarios, surgical procedures, and emergency response protocols with procedural consequence modeling. Defense organizations across Florida's peninsula command the deepest deployment budgets, with Orlando-based military contracting offices consolidating procurement around vendors meeting dual state-federal compliance pathways.
- Remote Assistance:Real-time spatial annotation and guided workflow overlays connect field technicians with remote experts. Tampa manufacturing corridors and Jacksonville logistics hubs are climbing the fastest as labor scarcity drives touchless knowledge transfer investments.
- Virtual Tours:Photorealistic walkthroughs replace physical staging for pre-construction property marketing.
- Education:Curricular immersive content for STEM and vocational training programs.
- Entertainment:Location-based experiential venues and consumer attraction deployments.
Training Simulations capture the largest contract values; Remote Assistance is gaining share fastest.
End User:
Customer type determines whether procurement flows through federal defense channels, state incentive-qualified media production structures, or commercial enterprise budgets.
- Defense Organizations:Procurement through Orlando-based military contracting offices requires adherence to federal simulation standards and extended vendor qualification timelines. These buyers unbundle hardware from software licensing and content development, concentrating negotiating leverage with prime contractors.
- Real Estate Companies:Miami-Dade property marketing operations accelerate pre-construction sales cycles through photorealistic virtual walkthroughs that eliminate physical staging costs.
- Educational Institutions:State university systems and vocational colleges prioritize cloud-based subscription access over capital-intensive hardware ownership.
- Media Production:Orlando immersive content studios leverage Florida's film and digital media tax incentive structure for qualified spend credits.
- Design Studios:Architectural and industrial design firms integrate spatial computing into client presentation workflows.
Defense Organizations dominate absolute spending; Real Estate Companies show the steepest expansion trajectory.
Deployment Model:
Supply concentration in cloud infrastructure versus edge hardware manufacturing shapes total cost of ownership calculations across buyer segments.
- Cloud-Based:Scalable subscription access to rendering compute and content libraries eliminates upfront hardware capital requirements. Educational institutions across the Florida peninsula and mid-tier design studios favor this model as micro-OLED fabrication bottlenecks constrain local headset assembly capacity.
- Edge Computing:Localized processing nodes reduce latency for mission-critical training simulations where connectivity interruption risks operational integrity. Defense procurement specifications increasingly mandate edge redundancy for field-deployable systems.
- On-Premise:Captive hardware ownership with dedicated facility infrastructure.
- Hybrid:Split architectures combining local rendering with cloud content delivery.
Cloud-Based deployments expand most quickly in commercial segments; Edge Computing defends position in defense applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's AR/VR consumption patterns diverge sharply from national averages, with defense procurement dominating Orlando corridors while Miami-Dade property marketing drives commercial adoption. Tampa manufacturing and Jacksonville logistics clusters are accelerating remote assistance deployment faster than comparable metros elsewhere.
Orlando Metropolitan Area
Defense organizations command the deepest simulation budgets through military contracting offices concentrated around Central Florida. OSHA workplace safety guidelines for extended VR sessions validate enterprise training adoption by reducing liability exposure for commercial operators. The entertainment technology corridor channels film and digital media tax incentives toward immersive content studios.
Miami-Dade County
Real estate visualization workflows accelerate pre-construction sales cycles by replacing physical staging with photorealistic virtual walkthroughs. Florida's consumer protection framework mandates biometric data handling disclosures for VR operators collecting gaze tracking information. Property marketing studios dominate architectural visualization demand.
Tampa Bay Region
Manufacturing corridors are climbing fastest as labor scarcity drives touchless knowledge transfer investments through gesture recognition convergence. The state's evolving data privacy statutes impose compliance friction on spatial mapping data collection without clear federal preemption. Industrial clients demand tactile fidelity in remote assistance workflows.
Jacksonville Logistics Hub
Distribution and transportation operators deploy mixed reality for maintenance and field service applications across warehouse and port facilities. Federal defense procurement standards administered through Orlando contracting offices create dual compliance pathways for simulation vendors serving military-adjacent logistics. Edge computing specifications increasingly mandate redundancy for field-deployable systems.
Greater Fort Lauderdale
Educational institutions prioritize cloud-based subscription access over capital-intensive hardware ownership as micro-OLED fabrication bottlenecks constrain local headset assembly capacity. State university systems integrate spatial computing into STEM and vocational training programs. Design studios leverage scalable rendering compute for client presentation workflows.
Florida Augmented and Virtual Reality Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with prime contractors concentrating negotiating leverage through unbundled procurement while mid-tier vendors fragment across capability niches. Defense procurement consolidation compresses vendor qualification timelines while elevating technical compliance thresholds. Three archetypes dominate: simulation specialists anchoring military contracts, visualization studios serving property marketing, and platform-agnostic developers spanning multiple verticals. Competitive moves center on strategic partnerships for dual compliance pathways and cloud-based deployment model expansion.
Within the defense-specialist tier, Lucid Reality Labs and AVT Simulation exemplify vendors sustaining long-term training system partnerships with military installations throughout the Florida peninsula. Covalent Reality occupies a distinct position among architectural visualization providers, differentiating through workflows that dominate Miami-Dade property marketing. These three represent how geographic concentration around Orlando and Miami creates divergent capability clusters within the same state market.
| Leading Market Players |
|---|
| Cubix |
| Iron Forge Development |
| Lucid Reality Labs |
| Covalent Reality |
| Parisleaf |
| Elevux |
| SoluLab |
| Infinitas Engineering Inc. |
| AVT Simulation |
| Others |
Pricing and Supply Chain Analysis
Micro-OLED fabrication scale economies in Asian foundries compress unit costs for headset assemblers while simultaneously concentrating supply leverage among a handful of display suppliers, creating asymmetric pricing power that elevates floor prices for Florida-based system integrators regardless of volume commitments.
Pricing Analysis
Long-term offtake agreements dominate defense procurement through Orlando military contracting offices, while commercial segments favor subscription-based SaaS tiers with annual licensing renewals. Price differentiation hinges on OSHA certification tier for extended VR session compatibility and customization depth for mission-critical training scenarios. Pricing pressure stems from micro-OLED supply bottlenecks that elevate hardware input costs faster than software margins can absorb. Educational institutions exhibit highest price sensitivity due to capital budget constraints, whereas defense organizations demonstrate lowest sensitivity given mission-critical procurement mandates.
Supply Chain Analysis
Inventory lead times for force-feedback actuators and precision haptic sensors stretch procurement cycles for Tampa manufacturing corridor deployments. Component sourcing draws from Taiwan and South Korea for display panels, China for optical assemblies, and Japan for precision motion sensors. Supply chain risk centers on single-source vulnerability for micro-OLED substrates where alternative qualified suppliers remain limited. Distribution runs through Orlando-based prime contractors who unbundle hardware from software licensing, fragmenting subcontractor relationships across specialized capability providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality around federal budget appropriations creates recovery windows for vendors positioned at technical compliance thresholds, with Orlando contracting office consolidation accelerating vendor turnover during upswing phases.
For Market Incumbents: Secure dual compliance certification pathways that satisfy both Florida digital media incentive requirements and federal defense procurement standards administered through Orlando offices. Anchor long-term training system partnerships with military installations throughout the Florida peninsula to defend against emerging platform-agnostic developers. Deepen vertical integration into cloud-based deployment infrastructure as educational institutions shift procurement toward subscription models. For New Entrants and Emerging Players: Gesture recognition convergence for touchless industrial assistance workflows represents the most penetrable service-layer gap where incumbents under-serve Tampa manufacturing corridors. Target mid-tier design studios in Greater Fort Lauderdale with hybrid deployment architectures that split rendering between local edge nodes and cloud content libraries. Pursue go-to-market partnerships with Miami-Dade property marketing studios seeking photorealistic architectural visualization capabilities without prime contractor overhead. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-based platform developers serving educational institutions across the Florida peninsula. Long-term viability favors acquisition targets with established Orlando defense corridor relationships and unbundled procurement capabilities separating hardware delivery from scenario authoring. Watch for inflection signals in federal simulation training budget allocations through Orlando military contracting offices.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Compliance Certification Investment | OSHA workplace safety protocols and federal defense standards unlock Orlando procurement access. |
| Cloud-Based Deployment Platform Launch | Subscription economics align with educational institution capital constraints across Florida. |
| Haptic System Capability Acquisition | Tactile fidelity differentiation captures Tampa manufacturing corridor remote assistance demand. |
| Strategic Partnership with Prime Contractors | Unbundled procurement leverage concentrates through Orlando-based military contracting offices. |
| Gesture Recognition Technology Integration | Computer vision algorithms enable touchless industrial workflows in labor-scarce manufacturing zones. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with simulation engineers at defense contractors, procurement officers at Orlando military contracting offices, CTOs at Miami-Dade property marketing studios, and curriculum directors at Florida state university systems. Secondary validation drew from OSHA technical guidance documents, federal defense procurement databases, Florida Department of Economic Opportunity incentive program filings, and hyperscaler cloud infrastructure capex disclosures. Bottom-up segment sizing triangulated against top-down market boundary estimates.
Across the analysis window, the forecasting framework modeled technology adoption curves by deployment model, application vertical, and end-user procurement channel, with specific attention to defense contracting cyclicality and educational institution budget appropriation patterns. CAGRs were derived from segment-level growth rate reconciliation against aggregate market boundary constraints. Industry-specific inputs included federal simulation training procurement velocity and micro-OLED fabrication capacity expansion timelines.
Forecasts assume regulatory continuity in OSHA workplace safety enforcement and Florida data privacy statute evolution; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
AR-VR Head Display Equipment Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Collaboration Platform Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality Connected Service Market
Virtual Reality (VR) and Augmented Reality (AR)
North America Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Location-Based Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality (VR) and Augmented Reality (AR) Microdisplay Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in Retail Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Industrial AR Platforms Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Enterprise AR Software Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Box Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Head Show Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality Headset Market