
 Romania Cybersecurity Market | 2026-2036
Romania Cybersecurity Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Cybersecurity Market Insights
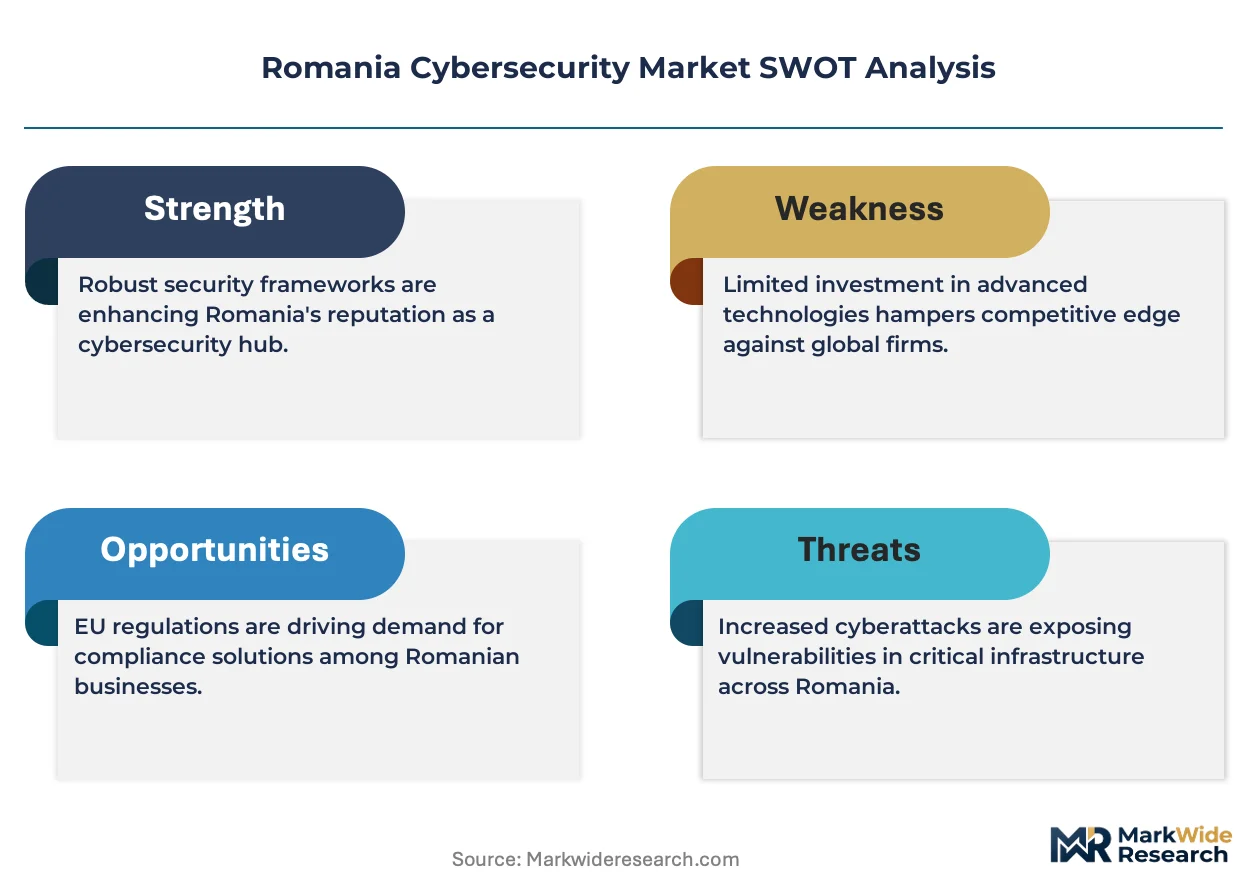
The gap between enterprise-grade threat intelligence platforms and basic signature-based antivirus is broadening across Romanian organizations. Bitdefender SA leverages its native engineering base to sustain R&D intensity in advanced persistent threat detection. Cisco Systems Inc. anchors its position through channel control over government and telecom infrastructure contracts. Check Point Software Technologies Ltd. differentiates via specialized firewall appliances tailored for European data sovereignty requirements.
Cybersecurity encompasses hardware, software, and service-based defenses engineered to protect networks, endpoints, and data assets from unauthorized access, disruption, or exfiltration, typically operating through real-time traffic inspection, behavioral anomaly detection, and automated incident response protocols with sub-millisecond latency thresholds. Endpoint security solutions dominate procurement budgets among Romanian manufacturers retrofitting operational technology environments, while cloud-based deployment models capture the fastest expansion as BFSI institutions migrate core banking platforms. Managed security services concentrate margin pools where Atos Group and Orange Romania compete for multi-year outsourcing contracts.
Romania's NIS2 implementation through the national cybersecurity authority, alongside BIS-aligned critical infrastructure standards and GDPR enforcement by the national data protection agency, mandates incident reporting timelines and supply chain security audits that reshape vendor qualification criteria. The country's central bank issues periodic guidance on operational resilience testing that drives recurring compliance expenditure. Stakeholders must monitor how forthcoming EU Cyber Resilience Act certification requirements will reorder procurement priorities for IoT and software vendors serving Romanian enterprises.
Market Dynamics
NIS2 transposition into Romanian law is compressing procurement cycles for critical infrastructure operators, forcing immediate zero-trust architecture investments while reshaping vendor qualification criteria across Bucharest's technology corridor.
Growth Catalysts
- Critical Infrastructure Mandates:The national cybersecurity authority's incident reporting timelines under NIS2 implementation are compelling energy and transport operators to accelerate security audits and supply chain verification protocols.
- GDPR Enforcement Intensity:Romania's national data protection agency has intensified operational resilience testing requirements, driving recurring compliance expenditure among BFSI institutions migrating core platforms.
- Bucharest Technology Corridor Concentration:Defense contractors and critical infrastructure operators clustering in the capital region are creating dense demand nodes for advanced persistent threat detection capabilities.
Market Restraints
- Specialized Talent Scarcity:Romanian universities produce insufficient cybersecurity engineering graduates relative to zero-trust architecture deployment needs, inflating compensation costs for security operations center analysts.
- Legacy OT Integration Friction:Manufacturing retrofit projects face extended timelines due to incompatibility between modern endpoint detection tools and aging industrial control systems.
- EU Cyber Resilience Act Uncertainty:Pending IoT and software vendor certification requirements are freezing procurement decisions among enterprises awaiting final implementation guidance.
Strategic Opportunities
- Transylvania Manufacturing Belt:Industrial automation investments in Cluj-Napoca and Timișoara are creating underpenetrated demand for operational technology security solutions among automotive and electronics producers.
- Cloud-Native Security Convergence:The intersection of containerized workloads and zero-trust network access is opening white space for vendors offering unified cloud workload protection platforms.
- Managed Security Service Expansion:Multi-year outsourcing contracts for security operations center functions represent margin-rich opportunities as Atos Group and Orange Romania establish service delivery benchmarks.
Industry Challenges
- Security Operations Center Staffing:Romanian enterprises struggle to retain certified incident response analysts amid competition from Western European employers offering remote-work premiums.
- OT-IT Convergence Complexity:Operational technology environments require specialized industrial protocol knowledge that standard IT security certifications do not address, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Cybersecurity Market |
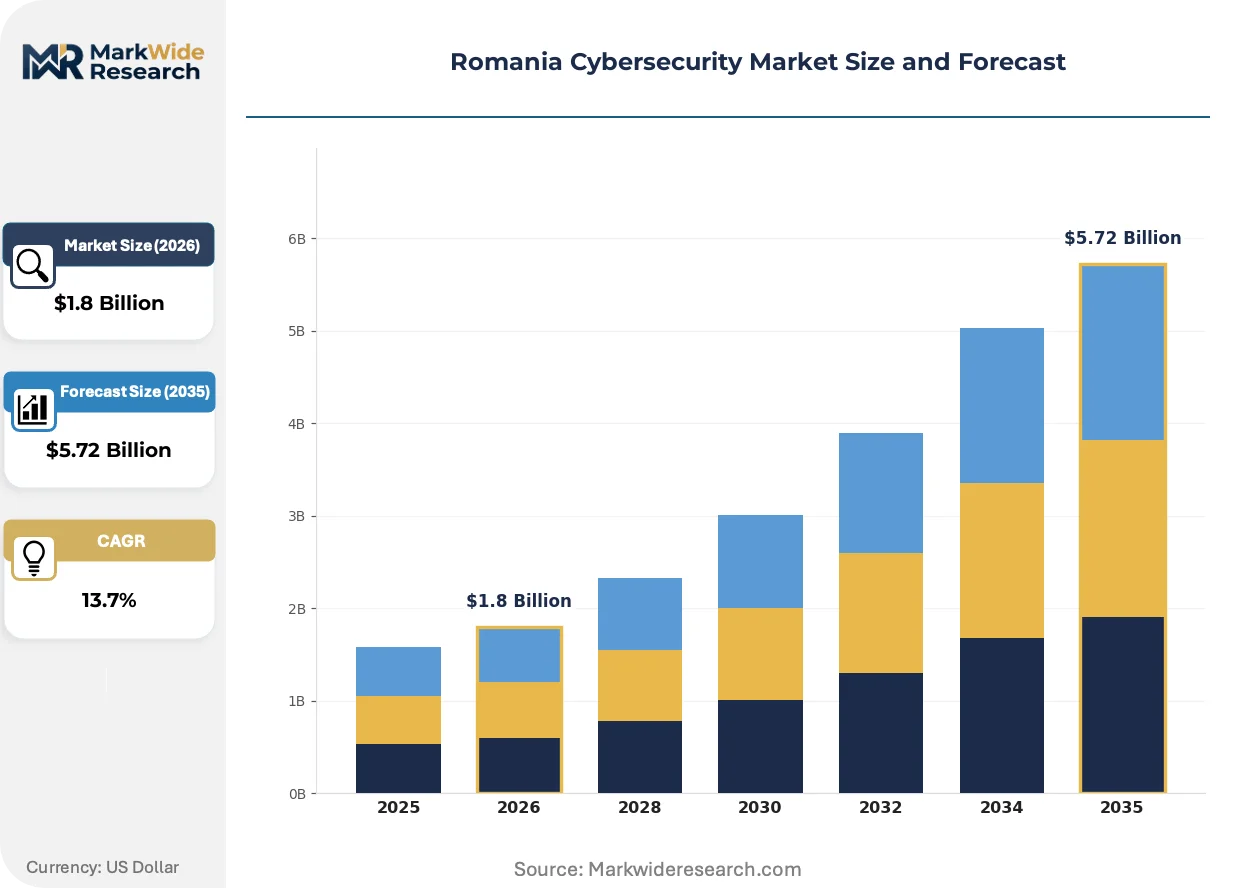
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antivirus, Firewall, Intrusion Detection System, Endpoint Security Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User: Government, BFSI, Healthcare, Manufacturing Service Type: Consulting, Managed Security Services, Incident Response, Risk Assessment |
| Companies Covered | Bitdefender SA, Safetech Innovations, CoSoSys Ltd., Atos Group, Cisco Systems Inc., Check Point Software Technologies Ltd., Fortinet, Palo Alto Networks, Orange Romania, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Cybersecurity Market Trends and Innovations
Behavioral analytics engines are displacing signature-based detection across Romanian enterprise security stacks, compressing dwell-time metrics while elevating automation requirements for security operations workflows.
Extended detection and response platforms are consolidating endpoint, network, and cloud telemetry into unified threat hunting interfaces. Romanian financial institutions are adopting these capabilities fastest, driven by central bank operational resilience testing mandates. This consolidation is compressing standalone endpoint protection vendor margins while privileging integrated platform providers.
The EU Cyber Resilience Act certification framework is mandating security-by-design requirements for IoT and software products entering Romanian enterprise procurement pipelines. Industrial manufacturers serving critical infrastructure must now document vulnerability management lifecycles before contract award. Defense contractors in Bucharest are establishing dedicated compliance functions to navigate these pre-market conformity assessment obligations.
Consumption patterns among Romanian BFSI institutions are rotating toward subscription-based security service arrangements that bundle threat intelligence with managed detection and response. Traditional perpetual license procurement is retreating to smaller manufacturing accounts with limited security operations maturity. This shift concentrates vendor relationships among Bucharest-based system integrators capable of delivering outcome-aligned service level agreements.
Romania Cybersecurity Market Segmentation
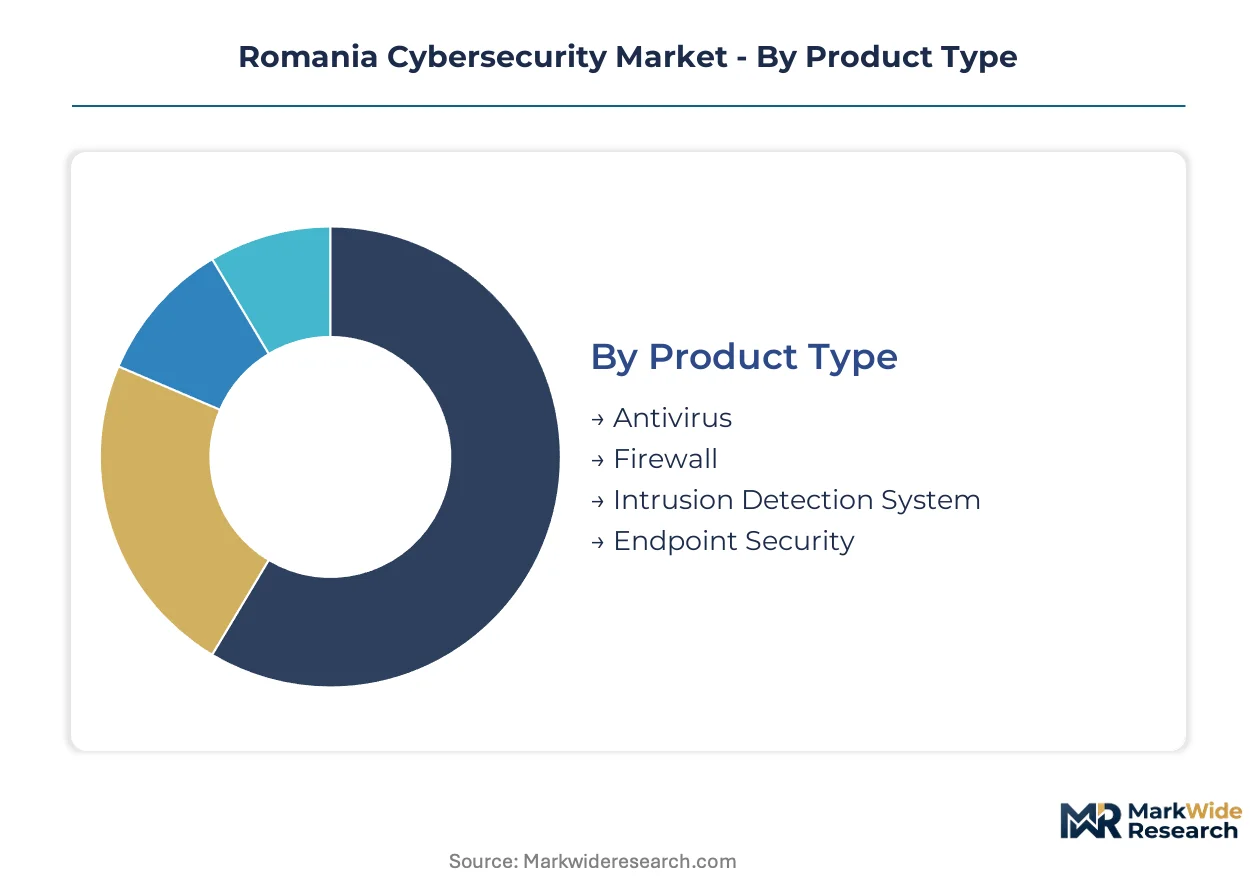
Segmentation reveals how NIS2 compliance deadlines and OT retrofit cycles are fragmenting procurement priorities across Romanian enterprises. Upgrade timelines diverge sharply between critical infrastructure operators facing immediate mandates and manufacturing adopters navigating legacy integration friction.
Product Type:
Replacement cycles accelerate where legacy signature-based tools fail against behavioral threats, compressing vendor switching windows for Bucharest's financial institutions.
- Endpoint Security:Agent-based solutions deploy behavioral analytics engines and automated response protocols to workstations, servers, and mobile devices. Romanian manufacturers retrofitting operational technology environments in Cluj-Napoca and Timișoara are concentrating procurement budgets here, driven by incompatibility between modern detection tools and aging industrial control systems.
- Firewall:Network perimeter appliances enforce traffic segmentation through deep packet inspection and application-layer filtering. Critical infrastructure operators across Bucharest's technology corridor prioritize specialized hardware tailored for European data sovereignty requirements, reshaping vendor qualification criteria under national cybersecurity authority oversight.
- Antivirus:Signature-based malware detection tools remain entrenched in smaller manufacturing accounts with limited security operations maturity.
- Intrusion Detection System:Network traffic monitors identifying anomalous patterns through protocol analysis and threat intelligence correlation.
Volume placements concentrate in Firewall appliances serving government and telecom contracts; the faster expansion belongs to Endpoint Security solutions penetrating industrial automation investments.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from recurring subscription arrangements that bundle threat intelligence with operational support.
- Cloud-Based:Scalable security controls delivered through SaaS architectures eliminate hardware provisioning overhead. BFSI institutions migrating core banking platforms are driving steepest expansion trajectory here, attracted by subscription-based arrangements that align expenditure with outcome-aligned service level agreements.
- Managed Services:Outsourced security operations center functions encompassing continuous monitoring, threat hunting, and incident response. Multi-year contracts in Bucharest concentrate margin pools where Atos Group and Orange Romania compete to establish service delivery benchmarks.
- On-Premises:Locally hosted security infrastructure requiring dedicated hardware procurement and internal operations staffing.
- Hybrid:Mixed architectures combining cloud-delivered controls with retained on-premises appliances for sensitive workloads.
Customer concentration clusters in Managed Services among enterprises struggling to retain certified analysts; Cloud-Based deployment gains share fastest where central bank operational resilience testing mandates accelerate platform migrations.
End User:
Application-specific requirements dictate divergent procurement specifications across regulated sectors facing distinct compliance enforcement intensities.
- BFSI:Banking, financial services, and insurance institutions subject to central bank operational resilience testing and GDPR enforcement by the national data protection agency. These organizations adopt extended detection and response platforms fastest, consolidating endpoint, network, and cloud telemetry into unified threat hunting interfaces.
- Government:Public sector agencies and critical infrastructure operators bound by NIS2 incident reporting timelines and supply chain security audits. Defense contractors clustering in Bucharest's technology corridor create dense demand nodes for advanced persistent threat detection capabilities.
- Healthcare:Medical institutions and pharmaceutical operators managing patient data under GDPR and national data protection oversight.
- Manufacturing:Industrial producers across Transylvania's automotive and electronics belt requiring operational technology security solutions.
Revenue concentration sits with BFSI institutions funding recurring compliance expenditure; Manufacturing represents the most underpenetrated expansion opportunity as industrial automation investments outpace security retrofit cycles.
Service Type:
Customer maturity stratifies procurement between advisory engagements for security program design and operational execution functions requiring specialized talent retention.
- Managed Security Services:Continuous security operations encompassing 24/7 monitoring, threat intelligence integration, and automated incident response. These engagements capture margin-rich opportunities as Romanian enterprises confront certified analyst scarcity amid competition from Western European remote-work premiums.
- Incident Response:Retainer-based and emergency engagement models for breach containment, forensic investigation, and recovery coordination. Bucharest-based system integrators capable of delivering sub-millisecond latency thresholds are consolidating vendor relationships here.
- Consulting:Advisory engagements for security architecture design, zero-trust migration planning, and compliance gap remediation.
- Risk Assessment:Structured evaluation services documenting vulnerability management lifecycles and pre-market conformity assessment obligations under pending EU Cyber Resilience Act requirements.
Procurement volume concentrates in Managed Security Services among mid-market enterprises lacking internal operations maturity; Incident Response is climbing the fastest as NIS2 implementation compresses breach notification timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bucharest's technology corridor concentrates Romania's cybersecurity demand, anchoring procurement gravity for defense contractors and critical infrastructure operators navigating NIS2 compliance deadlines.
Bucharest-Ilfov
The capital region hosts dense clusters of financial institutions and government agencies accelerating zero-trust investments. The national cybersecurity authority enforces incident reporting timelines that compress procurement cycles. Defense contractors along the technology corridor are establishing dedicated compliance functions for EU Cyber Resilience Act preparation.
Transylvania Manufacturing Belt
Cluj-Napoca and Timișoara anchor industrial automation investments creating underpenetrated demand for operational technology security. Manufacturers retrofitting aging industrial control systems face extended integration timelines. Automotive and electronics producers in this belt concentrate endpoint security procurement budgets.
Western Border Corridor
Timiș County and Arad position logistics and transport operators near EU supply chain entry points. NIS2 mandates compel accelerated security audits for critical transport infrastructure. Cross-border data flows intensify GDPR enforcement attention from the national data protection agency.
Black Sea Coastal Zone
Constanța anchors port and energy infrastructure requiring maritime-specific threat detection capabilities. Critical energy operators face compressed compliance timelines under national cybersecurity authority oversight. Offshore logistics clusters drive specialized managed security service contracting.
Central Development Region
Brașov and Sibiu host expanding IT service delivery centers competing for security operations talent. Remote-work premiums from Western European employers drain certified analyst availability. Regional universities struggle to match zero-trust architecture deployment needs with graduate output.
Romania Cybersecurity Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service integration depth, with managed security specialists capturing recurring revenue pools while hardware vendors compete on certification compliance. The vendor base stratifies between integrated platform providers and point-solution specialists. Three archetypes dominate: native engineering-led R&D intensifiers, channel-controlled infrastructure incumbents, and compliance-specialized hardware fabricators. Competitive moves concentrate on multi-year outsourcing contract capture and zero-trust architecture certification alignment.
Within the native engineering tier, Bitdefender SA exemplifies sustained R&D intensity in advanced persistent threat detection. Cisco Systems Inc. anchors channel control over government and telecom infrastructure contracts. Check Point Software Technologies Ltd. occupies a specialized position for European data sovereignty requirements.
| Leading Market Players |
|---|
| Bitdefender SA |
| Safetech Innovations |
| CoSoSys Ltd. |
| Atos Group |
| Cisco Systems Inc. |
| Check Point Software Technologies Ltd. |
| Fortinet |
| Palo Alto Networks |
| Orange Romania |
| Others |
Pricing and Supply Chain Analysis
EU Cyber Resilience Act certification requirements gate qualified supply for Romanian cybersecurity vendors while propping premium-tier pricing access for pre-certified platform providers serving Bucharest's critical infrastructure operators.
Pricing Analysis
Value-based pricing anchored to security operations center uptime guarantees dominates managed security services in Romania, where Atos Group and Orange Romania compete on outcome-aligned service level agreements. Pricing stratifies across premium, standard, and economy tiers based on threat intelligence integration depth and analyst certification levels. Cost compression in the economy tier intensifies because smaller manufacturing accounts lack procurement sophistication to evaluate behavioral analytics capabilities. Government and BFSI institutions show least price sensitivity due to NIS2 compliance deadlines eliminating vendor switching flexibility.
Supply Chain Analysis
Reverse-logistics flows for hardware security module refurbishment and firewall appliance redeployment concentrate service revenue with Bucharest-based system integrators rather than original equipment manufacturers. Component supply draws from Taiwan for semiconductor fabrication, Israel for threat intelligence feeds, and Ireland for EU data sovereignty-compliant cloud infrastructure. Single-source vulnerability in specialized encryption chip supply creates procurement risk for firewall vendors serving defense contractors. Distribution runs through certified channel partners holding national cybersecurity authority vendor qualification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Romania's cybersecurity market operates as a supply-constrained story where certified security operations analyst scarcity props pricing power for managed service providers across Bucharest's technology corridor.
For Market Incumbents: Hedge against talent attrition by establishing captive analyst academies in Brașov and Sibiu, countering Western European remote-work premiums that drain certified incident response capacity. Deepen backward integration into threat intelligence feed development, reducing reliance on Israeli and US-sourced indicators that face export control friction.
For New Entrants and Emerging Players: Capture white space in Transylvania's operational technology security segment, where Cluj-Napoca and Timișoara manufacturers retrofit aging industrial control systems without compatible endpoint detection tools. Target automotive and electronics producers with specialized industrial protocol knowledge that standard IT security certifications do not address.
For Investors and Strategic Acquirers: EU Cyber Resilience Act pre-market conformity assessment obligation announcements are the leading indicator that compliance-specialized hardware fabricators will command acquisition premiums. Long-term viability over a multi-year window favors vendors with embedded national cybersecurity authority relationships and existing critical infrastructure contract portfolios. Monitor NIS2 implementation enforcement intensity for early signals of procurement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Certification | Aligns vendor qualification criteria with national cybersecurity authority mandates for Bucharest government contracts. |
| Managed Security Service Expansion | Captures margin-rich multi-year outsourcing contracts as Atos Group and Orange Romania establish delivery benchmarks. |
| OT Security Specialist Acquisition | Addresses industrial protocol knowledge gaps that extend deployment timelines in Transylvania manufacturing retrofits. |
| Threat Intelligence Feed Integration | Consolidates endpoint, network, and cloud telemetry into unified interfaces demanded by BFSI institutions. |
| Regional Talent Academy Establishment | Counteracts analyst scarcity in Brașov and Sibiu where Western European remote-work premiums drain certified capacity. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with chief information security officers, security operations center managers, national cybersecurity authority officials, and managed service provider executives with validation against ANSSI Romania guidance documents, Banca Națională a României operational resilience circulars, and EU Cyber Resilience Act draft implementing acts. Bottom-up vendor revenue triangulation against top-down IT security expenditure estimates derived from enterprise technology budget disclosures shaped market sizing.
Data-stream reconciliation across deployment model, end-user vertical, and service type segmentation dimensions modeled value trajectories over the projection horizon. CAGRs were derived from weighted regression of historical procurement cycle data against compliance deadline schedules. Threat intelligence platform adoption curves and managed security service contract renewal rates served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Cyber Resilience Act final certification timelines and NIS2 enforcement intensity variations. Practitioners should monitor national cybersecurity authority vendor qualification criteria updates and central bank operational resilience testing mandate expansions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cybersecurity
Big Data Security Market
Cybersecurity
Penetration Testing Market
Cybersecurity
Global Cyber Security in Healthcare Market
Cybersecurity
Europe Cloud DLP Market
Cybersecurity
Global Zero-Trust Security Market
Cybersecurity
Education Data Security Market
Cybersecurity
Global File Integrity Monitoring Market
Cybersecurity
DNS Security Market
Cybersecurity
Portugal Cybersecurity Market
Cybersecurity
India Network Security and Cyber Risk Management Market
Cybersecurity
Global Virtualization Security Market
Cybersecurity
Middle East Cybersecurity Market
Cybersecurity
Wireless Lan Security Market
Cybersecurity
Cyber Warfare Market
Cybersecurity
SD-WAN Security Market
Cybersecurity
Latin America Ransomware Protection Market