
 Agricultural Automation Market | 2026-2036
Agricultural Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Automation Market Insights
Modular equipment configurations—where sensor pods, implements, and autonomy kits unbundle from base tractor platforms—is repositioning buyer choice across the agricultural automation sector. Deere & Company leverages its integrated operations platform to anchor high-margin recurring software revenue alongside hardware sales. AGCO Corporation differentiates through open-architecture FendtONE systems that compete for third-party developer ecosystems. Kubota Corporation specializes in compact autonomous tractors for high-value specialty crop segments in Japan and Europe.
Agricultural automation encompasses electromechanical systems, sensor networks, and algorithmic control layers that execute crop production tasks with minimal human intervention, typically operating through GPS-guided positioning accuracy within 2.5 centimeters and real-time variable-rate actuation. Its primary commercial purpose is to optimize input efficiency, labor allocation, and yield consistency across large-scale farming operations. Automated tractors occupy the largest installed base and margin pool among product types, while drone-based crop monitoring represents the fastest-expanding application segment as imagery analytics mature. AI-enabled decision engines are displacing rule-based automation in irrigation management, where machine learning models process soil moisture, weather, and crop-stage data to generate prescriptive water schedules.
The EPA regulates autonomous agricultural equipment emissions and safety classifications in the United States, while the EU Machinery Directive and CE marking govern market access for robotics and automated systems sold across Europe. India's FSSAI and CEA are developing standards for automated food production traceability that will shape compliance requirements for export-oriented farm operations. Stakeholders must monitor how fragmented national liability frameworks for autonomous machinery accidents evolve and whether interoperability mandates emerge from ISO or regional bodies.
Market Dynamics
Modular unbundling of sensor pods, autonomy kits, and implements from tractor platforms is fragmenting buyer decision-making and eroding traditional OEM bundling power across agricultural automation supply chains.
Growth Catalysts
- EU Farm to Fork Strategy:Binding chemical-use reduction targets force precision application technology upgrades across European arable farming, accelerating variable-rate sprayer and drone-based monitoring deployment.
- Brazilian soybean belt scale economics:Mato Grosso farms exceeding 10,000 hectares achieve payback on autonomous fleets within 36 months through labor reallocation and input efficiency gains.
- GPS-RTK correction networks:Public and private real-time kinematic infrastructure expansion delivers sub-2.5 centimeter positioning accuracy without proprietary base stations, democratizing high-precision guidance.
Market Restraints
- Lithium-ion battery supply concentration:Cobalt and lithium processing capacity clusters in the Democratic Republic of Congo and Chile, exposing autonomous equipment manufacturers to geopolitical supply disruptions and price volatility.
- EU Machinery Directive compliance costs:CE marking requirements for functional safety and electromagnetic compatibility add 18-24 months to product launch timelines for robotics startups.
- Manual labor substitution economics:Seasonal migrant worker availability in California's Central Valley and Spain's Almería greenhouse districts delays autonomous harvesting adoption where wage arbitrage persists.
Strategic Opportunities
- India's FSSAI traceability mandates:Automated production logging requirements for export-oriented horticulture operations create demand for integrated farm management software with blockchain-ready audit trails.
- Specialty crop robotics:Strawberry, apple, and table grape harvesting automation remains underpenetrated relative to row crops, offering first-mover margins for computer-vision-guided selective pickers.
- Japan's compact autonomous tractors:High-value tea, rice, and vegetable plots on terraced terrain favor sub-40 horsepower electric platforms with swarm-coordination capabilities.
Industry Challenges
- Mechatronics talent scarcity:Agricultural equipment manufacturers compete with automotive and aerospace sectors for embedded systems engineers capable of integrating sensor fusion, path planning, and safety-critical control loops.
- Interoperability standardization delays:ISO 11783 (ISOBUS) extensions for autonomous operation lack finalization, forcing proprietary communication protocols that lock customers into single-vendor ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Automation Market |
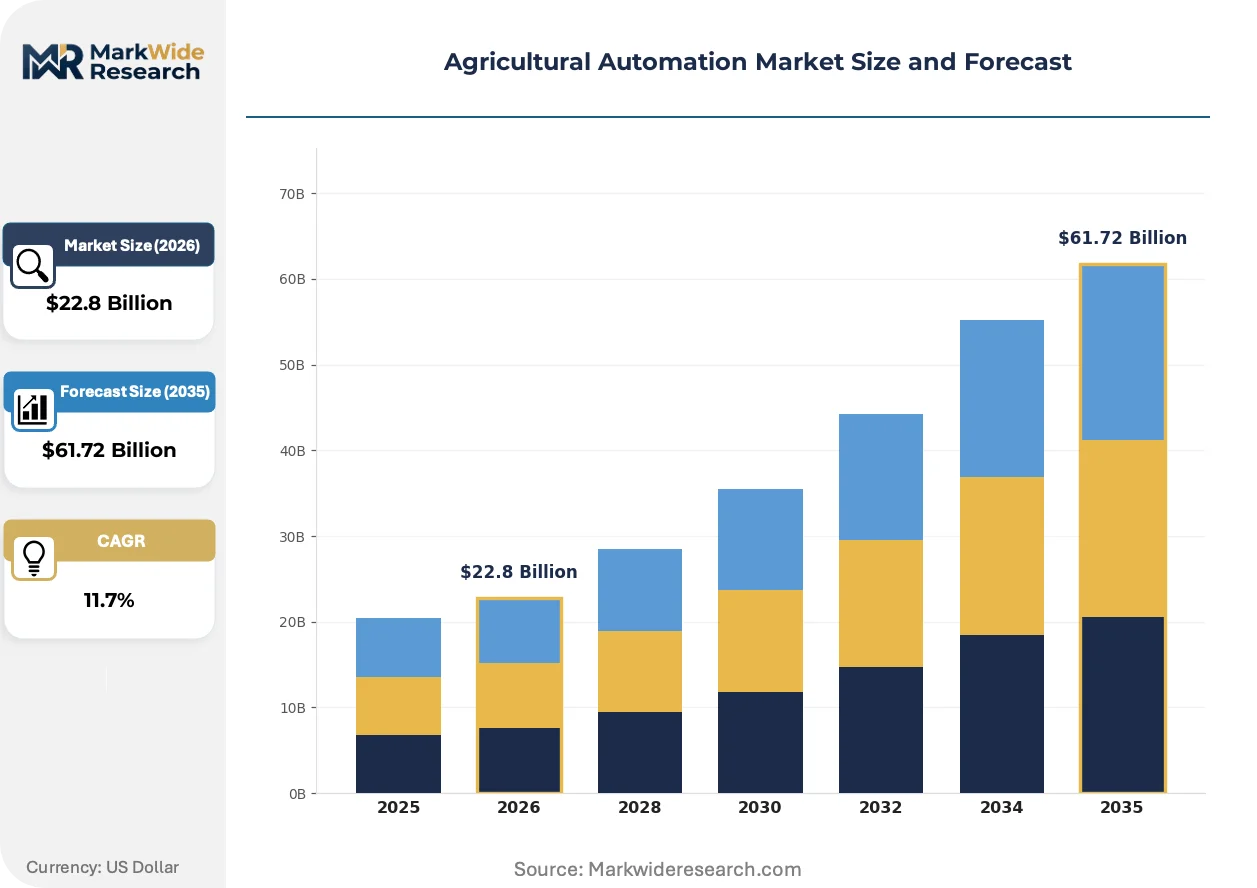
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $61.72 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotics, Sensors, Drones, Automated Tractors Technology: AI, IoT, GPS, Machine Learning End User: Farmers, Agricultural Cooperatives, Research Institutes, Government Agencies Application: Irrigation Management, Crop Monitoring, Livestock Management, Precision Farming |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial N.V., DJI, Lely, Kubota Corporation, Trimble Inc., Topcon Corporation, Raven Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Automation Market Trends and Innovations
Algorithmic decision layers are overtaking rule-based automation as the dominant control architecture, compressing the competitive advantage window for incumbent hardware-software bundles.
Machine learning-based irrigation scheduling is absorbing soil moisture telemetry, weather forecasting, and crop phenology data into unified prescriptive water management systems. Large-scale corn and soybean operations in the US Midwest deploy these platforms to reduce pumping costs while maintaining yield targets. The technology is absorbing capital previously allocated to simpler timer-based or threshold-triggered systems, consolidating vendor relationships around AI-enabled platform providers.
EPA emissions regulations for non-road engines are tightening particulate matter and nitrogen oxide limits, accelerating electrification of sub-100 horsepower equipment categories. California Air Resources Board zero-emission mandates for 2035 are forcing OEMs to redesign powertrain architectures and thermal management systems. Battery-electric vineyard tractors and orchard platforms now dominate equipment trials in Napa Valley and Washington's Yakima Valley.
Equipment-as-a-service contracting is displacing traditional loan-financed ownership among mid-scale US and European grain producers. Per-acre or per-season payment structures transfer technology obsolescence risk from farm balance sheets to OEMs and dealer networks. This model concentrates most visibly in the Great Plains wheat belt and Eastern European black-soil regions where capital constraints and yield volatility amplify preference for operational expenditure treatment.
Agricultural Automation Market Segmentation
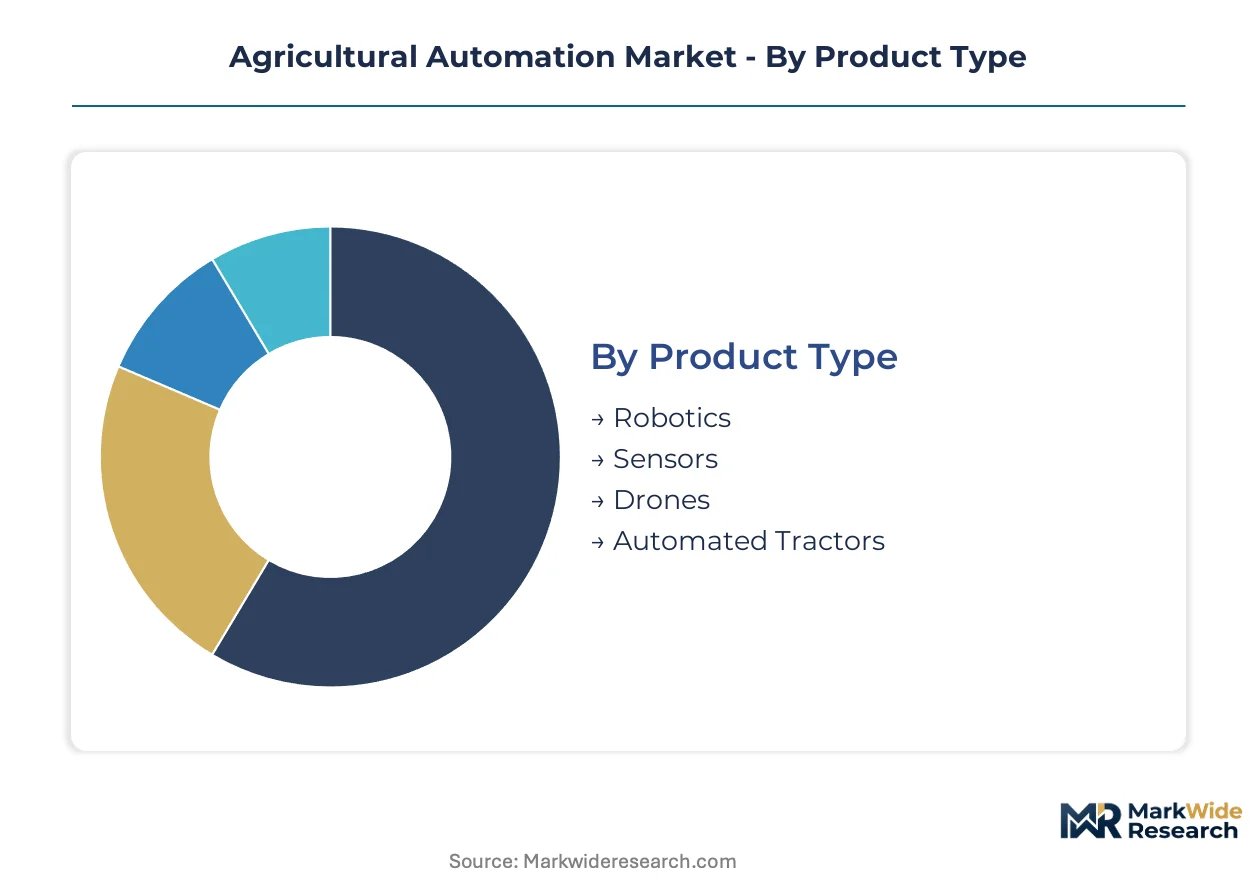
Segmentation in agricultural automation reveals how capital allocation, technical complexity, and operational scale fragment buyer behavior across distinct technology-product pairings. Equipment manufacturers calibrate R&D pipelines and service architectures around these divides, while farm operators match automation intensity to crop value and field geometry.
Product Type:
Capital intensity varies sharply across this dimension, with autonomous ground vehicles demanding the heaviest upfront outlays for mechanical platforms and safety certification.
- Automated Tractors:GPS-RTK guidance systems integrated with hydraulic implement control dominate installed base economics. Midwest US corn-soy operations and Mato Grosso soybean farms deploy these platforms for tillage, planting, and harvest logistics, with payback cycles compressing as labor costs rise and fleet management software matures.
- Drones:Multispectral and RGB payload configurations process imagery through cloud-based analytics pipelines for early-stage stress detection. Brazilian largeholders and Australian broadacre wheat producers drive procurement volume, prioritizing rapid field coverage over sub-centimeter positional accuracy.
- Robotics:Selective harvesting arms and weeding platforms deploy computer vision for crop-weed discrimination and gentle fruit handling. Specialty crop segments in California's Central Valley and Spain's Almería greenhouse districts trial these systems where manual labor availability constrains peak-season throughput.
- Sensors:Soil moisture probes, weather stations, and canopy sensors feed telemetry into variable-rate control loops. These devices attach to existing machinery, lowering entry barriers for mid-scale grain producers seeking incremental precision upgrades without full platform replacement.
Most installed capacity flows through Automated Tractors. Expansion is steepest in Drones as imagery analytics commoditize and regulatory frameworks for beyond-visual-line-of-sight operation stabilize.
Technology:
Technical architecture choices here determine whether farm operators build proprietary data ecosystems or subscribe to vendor-managed platforms.
- AI:Prescriptive models synthesize soil, weather, and crop-stage signals into actionable irrigation and fertility schedules. Large-scale US corn operations and Dutch greenhouse complexes deploy these systems to compress input waste while maintaining yield targets.
- GPS:Real-time kinematic correction networks deliver sub-2.5 centimeter positioning accuracy for autosteer and implement control. Public infrastructure expansion in Germany and private network buildouts in Brazil democratize precision previously locked behind proprietary base stations.
- IoT:Mesh networks and cellular telemetry connect distributed field sensors to cloud dashboards for remote monitoring. Australian dryland wheat producers and Indian contract farming operations prioritize these deployments for water stress alerting and input logistics coordination.
- Machine Learning:Computer vision models trained on crop-specific datasets enable robotic harvesting and autonomous weeding. Strawberry and apple operations in California and Washington State fund development consortia to advance selective picking accuracy.
AI platforms command the highest software margins. Machine Learning applications are climbing the fastest as training data accumulation and edge computing hardware costs decline.
End User:
Procurement authority and technical sophistication diverge across organizational scale and operational mandate.
- Farmers:Individual owner-operators and family partnerships select modular autonomy kits and subscription analytics services to limit capital exposure. Mid-scale US grain producers and Eastern European black-soil operators favor per-acre contracting models.
- Agricultural Cooperatives:Member-owned aggregations pool equipment investment across multiple farms, achieving scale economies in autonomous fleet deployment. Brazilian cooperatives in Rio Grande do Sul and French cereal cooperatives coordinate shared machinery pools.
- Research Institutes:Public and university agricultural experiment stations validate autonomous system performance across diverse agroecological conditions. USDA ARS locations and Wageningen University facilities generate third-party efficacy data shaping commercial adoption curves.
- Government Agencies:Extension services and rural development authorities subsidize precision technology demonstration programs. India's CEA and state agricultural departments in Australia's wheat belt fund farmer-facing pilot deployments.
Cooperatives concentrate the largest order volumes. Individual Farmers are gaining share fastest as financing innovations and equipment-as-a-service models lower entry thresholds.
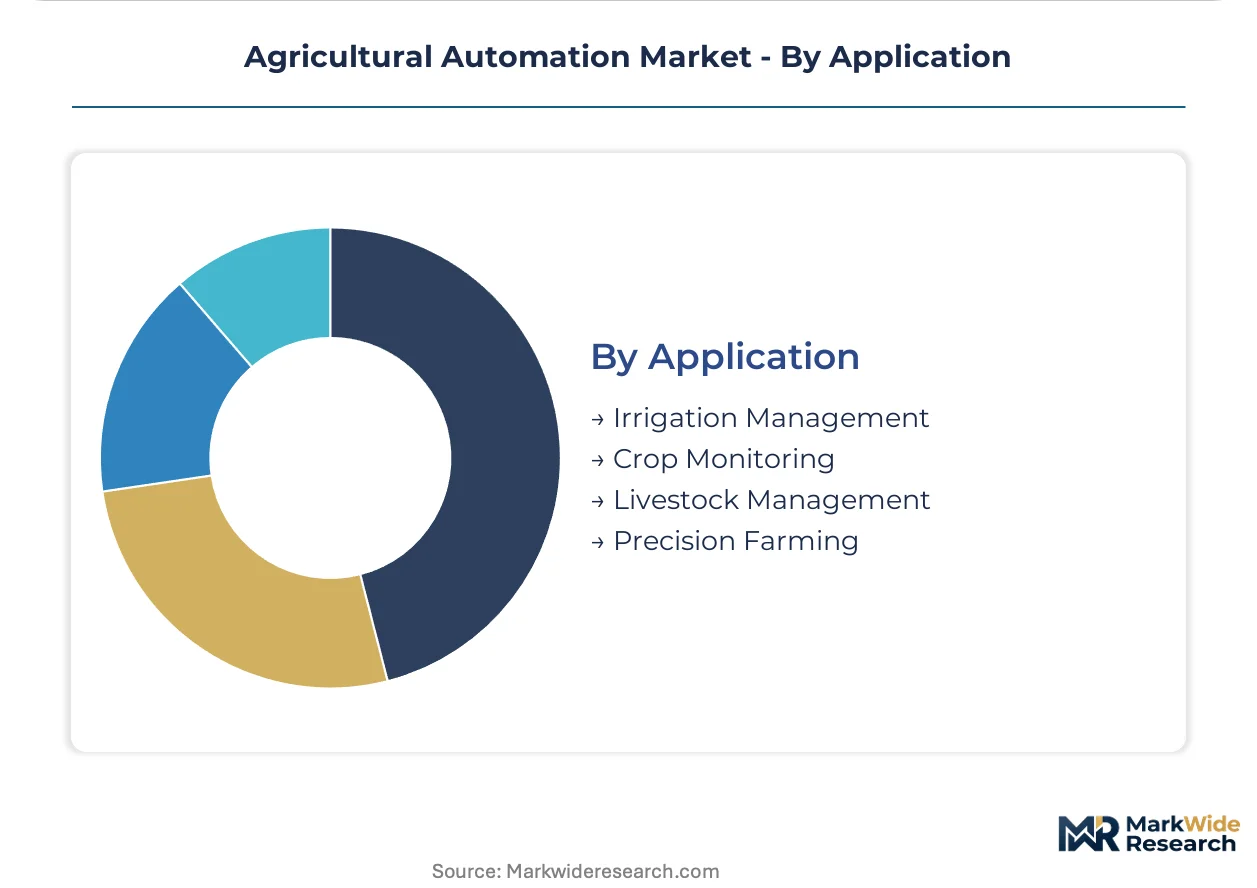
Application:
Automation value crystallizes around specific production bottlenecks where labor scarcity or input waste most severely compress margins.
- Precision Farming:Variable-rate seeding, fertilization, and chemical application optimize input placement at sub-field resolution. North American corn-soy rotations and Ukrainian black-soil grain operations deploy these systems to defend yield consistency against weather volatility.
- Crop Monitoring:Aerial and ground-based sensing pipelines detect pest pressure, nutrient deficiency, and water stress before visible symptoms emerge. Brazilian soybean belt operators and Australian cotton producers prioritize these deployments for early intervention timing.
- Irrigation Management:Soil moisture telemetry and evapotranspiration modeling automate scheduling decisions in water-constrained environments. California's Central Valley almond growers and Israeli desert agriculture operations drive adoption where pumping costs and allocation limits bite hardest.
- Livestock Management:Automated feeding, milking, and health monitoring systems reduce labor requirements in confined animal operations. Dutch dairy cooperatives and US Upper Midwest hog integrators deploy robotics for consistent animal handling and data capture.
Precision Farming absorbs the greatest cumulative investment. Crop Monitoring is expanding most quickly as drone and satellite imagery costs fall and analytics latency compresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision agriculture first achieved commercial scale in the United States during the 1990s with GPS-guided tractors spreading across Midwest corn-soy operations. The technology lineage now extends across multiple continents as labor costs rise and input efficiency mandates tighten.
United States
Midwest grain operations drive autonomous tractor deployment through capital-rich farming cooperatives seeking labor reallocation. EPA emissions regulations for non-road engines accelerate electrification trials in California's Central Valley specialty crop districts. The USDA funds precision technology demonstration programs through ARS locations in Iowa and Illinois.
Brazil
Mato Grosso soybean farms exceeding 10,000 hectares achieve rapid payback on autonomous fleets through input precision and seasonal labor reduction. ANVISA chemical registration requirements intersect with sustainability protocols demanded by EU export buyers. Rio Grande do Sul cooperatives coordinate shared machinery pools across member farms.
Germany
EU Farm to Fork Strategy binding targets force variable-rate sprayer upgrades across Bavarian and Lower Saxony arable operations. CE marking requirements under the EU Machinery Directive extend product launch timelines for robotics entrants. Fendt's integrated operations platform anchors software recurring revenue in southern German manufacturing clusters.
Japan
Compact autonomous tractors address labor scarcity in terraced tea and vegetable plots across Shizuoka and Kyoto prefectures. METI subsidies for smart agriculture adoption lower entry barriers for sub-40 horsepower electric platforms. Kubota's domestic specialization in high-value specialty crop segments leverages swarm-coordination capabilities.
Australia
Dryland wheat producers in New South Wales and Victoria prioritize IoT mesh networks for water stress alerting and input logistics. The TGA and state agricultural departments fund farmer-facing pilot deployments through rural development authorities. Broadacre cotton operations in Queensland drive drone-based crop monitoring procurement volume.
Agricultural Automation Market Competitive Landscape
The competitive structure tilts toward integrated platform providers commanding software recurring revenue alongside hardware sales. Tier-one OEMs anchor high-margin service ecosystems while mid-scale specialists compete on open-architecture flexibility. Three archetypes dominate: vertically integrated full-line manufacturers, modular autonomy kit suppliers, and precision software platform vendors. Strategic moves concentrate on equipment-as-a-service contracting models and geographic expansion into Brazil's Mato Grosso and India's export-oriented horticulture belts.
Among integrated full-line manufacturers, Deere & Company and AGCO Corporation exemplify divergent platform strategies—one leveraging proprietary closed systems, the other cultivating third-party developer ecosystems through open architecture. Kubota Corporation occupies a distinct position specializing in compact platforms for high-value specialty crop segments. These three anchors represent how scale, architecture choice, and crop focus segment competitive positioning across the agricultural automation landscape.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial N.V. |
| DJI |
| Lely |
| Kubota Corporation |
| Trimble Inc. |
| Topcon Corporation |
| Raven Industries |
| Others |
Pricing and Supply Chain Analysis
Large-scale cooperative buyers in Brazil's Mato Grosso and the US Midwest anchor equipment-as-a-service contracting, compressing upfront capital requirements into per-acre operational expenditure models that OEMs price against seasonal cash flow cycles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments autonomous tractor and drone procurement. Premium tiers bundle fleet management software and predictive maintenance; standard configurations compete on hardware specifications alone. Price differentiation hinges on GPS-RTK correction network access and ISO 11783 compliance certification. Cost compression in economy-tier sensor pods is intensifying because Chinese component suppliers are expanding RTK module production. Mid-scale grain producers in Eastern Europe exhibit highest price sensitivity, while Dutch greenhouse operators accept premium positioning for AI-enabled irrigation platforms.
Supply Chain Analysis
Remanufacturing flows for autonomy kits and sensor pods are expanding as Deere and AGCO establish certified refurbishment centers in Iowa and Lower Saxony to extend component lifecycles and defend margin pools. Lithium-ion cell production concentrates in China, South Korea, and Japan, with cobalt refining anchored in the Democratic Republic of Congo. Semiconductor fabrication for machine vision processors draws from Taiwan and South Korea. Single-source vulnerability in rare earth magnet supply creates exposure to export restriction shocks. Distribution runs through dealer networks with embedded service technicians rather than direct OEM-to-farm sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory tailwinds into durable demand, with the EU Farm to Fork Strategy's binding chemical-reduction targets forcing precision application technology upgrades across European arable farming.
For Market Incumbents: Cement software recurring revenue through integrated operations platforms that lock in fleet management data, while acquiring computer-vision startups to defend against modular autonomy kit suppliers eroding hardware margins. Capacity addition in Brazil's Mato Grosso preserves share against emerging Chinese OEMs targeting soybean belt scale economics. For New Entrants and Emerging Players: India's FSSAI traceability mandates in export-oriented horticulture open a window for blockchain-ready farm management software with automated production logging. Specialty crop robotics in California's Central Valley strawberry segment offers lowest competitive density. Partner with agricultural cooperatives in Rio Grande do Sul for shared machinery pool pilot deployments. For Investors and Strategic Acquirers: Agricultural equipment OEMs are the most active acquirer in this space, targeting precision software vendors to fill AI-enabled decision engine gaps. Long-term viability rests on subscription revenue durability rather than hardware shipment cyclicality. Watch for ISO 11783 finalization as interoperability inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contracting | Transfers technology obsolescence risk from farm balance sheets to OEMs in the Great Plains wheat belt. |
| Backward Integration into Lithium Processing | Reduces exposure to DRC cobalt and Chilean lithium supply disruptions for autonomous fleet manufacturers. |
| AI Platform Acquisition | Fills prescriptive irrigation and fertility scheduling gaps as rule-based automation loses competitive position. |
| CE Marking Pre-Certification | Compresses EU Machinery Directive compliance timelines for robotics startups targeting Bavarian arable operations. |
| Swarm-Coordination R&D Partnership | Develops compact tractor coordination for Japan's terraced tea and vegetable plots in Shizuoka prefecture. |
Research Methodology
Bottom-up farm operator modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with fleet managers at Brazilian cooperatives, precision agriculture specialists at USDA ARS locations, and procurement leads at Dutch dairy integrators were validated against secondary sources including EPA non-road engine filings, EU Machinery Directive CE marking databases, and ANVISA chemical registration records. Triangulation across these inputs produces segment-level volume and value estimates.
Input-output matrices map autonomous equipment deployment rates against input efficiency gains and labor cost trajectories across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user scale, and application intensity. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in GPS guidance and variable-rate application. Forecast inputs incorporate GPS-RTK network expansion timelines and battery-electric powertrain cost curves.
Revisions become necessary when EU Farm to Fork enforcement intensity shifts, lithium supply disruptions materialize, or ISO 11783 autonomous operation extensions finalize. Forecasts reflect assumptions about cooperative equipment pooling penetration and equipment-as-a-service contract uptake. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Global Warehouse Automation Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Computer-Aided Manufacturing (CAM) Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Industrial Human-Machine Interface Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Modular High-Bay Solutions Market
Industrial Automation
Global Feeder Automation Market
Industrial Automation
Grippers Market
Industrial Automation
Europe ICS Market