
 Programmable Automation Controller (PAC) Market | 2026-2036
Programmable Automation Controller (PAC) Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Automation Controller (PAC) Market Intelligence
The IEC 61131-3 standard for programmable logic languages is collapsing the distinction between high-end PLCs and PACs, defining the baseline for market entry. Siemens AG leverages its extensive portfolio in factory automation to dominate the European market. Rockwell Automation sustains a strong position in North America through its integrated architecture platform. Schneider Electric competes with a focus on energy management and process automation solutions across diverse end-user industries.
A Programmable Automation Controller (PAC) is a ruggedized industrial computer that combines the functionalities of a Programmable Logic Controller (PLC) with the flexible processing capabilities of a personal computer. It operates on a single platform to manage complex motion control, sequential logic, and process data, often utilizing multi-core processors for high-speed computation. Modular PACs command the largest market share due to their scalability and customization for complex factory automation. Compact PACs, however, show faster growth in machinery monitoring and smaller-scale process control applications.
Product design and market access are governed by safety and interoperability standards, including ISO certifications and the mandatory CE marking for systems sold in the European Union. In China, compliance with GB standards for industrial control equipment is essential, while the EU's Machinery Directive sets stringent safety requirements. Vendor selection will increasingly hinge on a PAC's ability to integrate securely with cloud-based analytics platforms and support edge computing workloads.
Market Dynamics
The convergence of Information Technology (IT) and Operational Technology (OT) stands as the central structural force shaping the market. This integration, a core principle of Industry 4.0, is driving demand for PACs that can execute complex logic while communicating seamlessly with enterprise-level systems.
Growth Catalysts
- Precision Control in Pharmaceuticals:The pharmaceutical production sector's stringent requirements for process validation and data integrity create significant pull for PACs, which offer the necessary precision, traceability, and compliance with manufacturing regulations like those from the FDA and EMA.
- Chinese Industrial Modernization:Extensive factory automation upgrades throughout China, supported by national policies and the enforcement of GB standards for industrial control equipment, are accelerating the replacement of older PLCs with more flexible and powerful PAC-based systems.
- Standardization via IEC 61131-3:The IEC 61131-3 standard is harmonizing programmable logic languages, lowering the barrier for engineers to work across different platforms and accelerating the adoption of PACs by making their programming environment more accessible and uniform.
Market Restraints
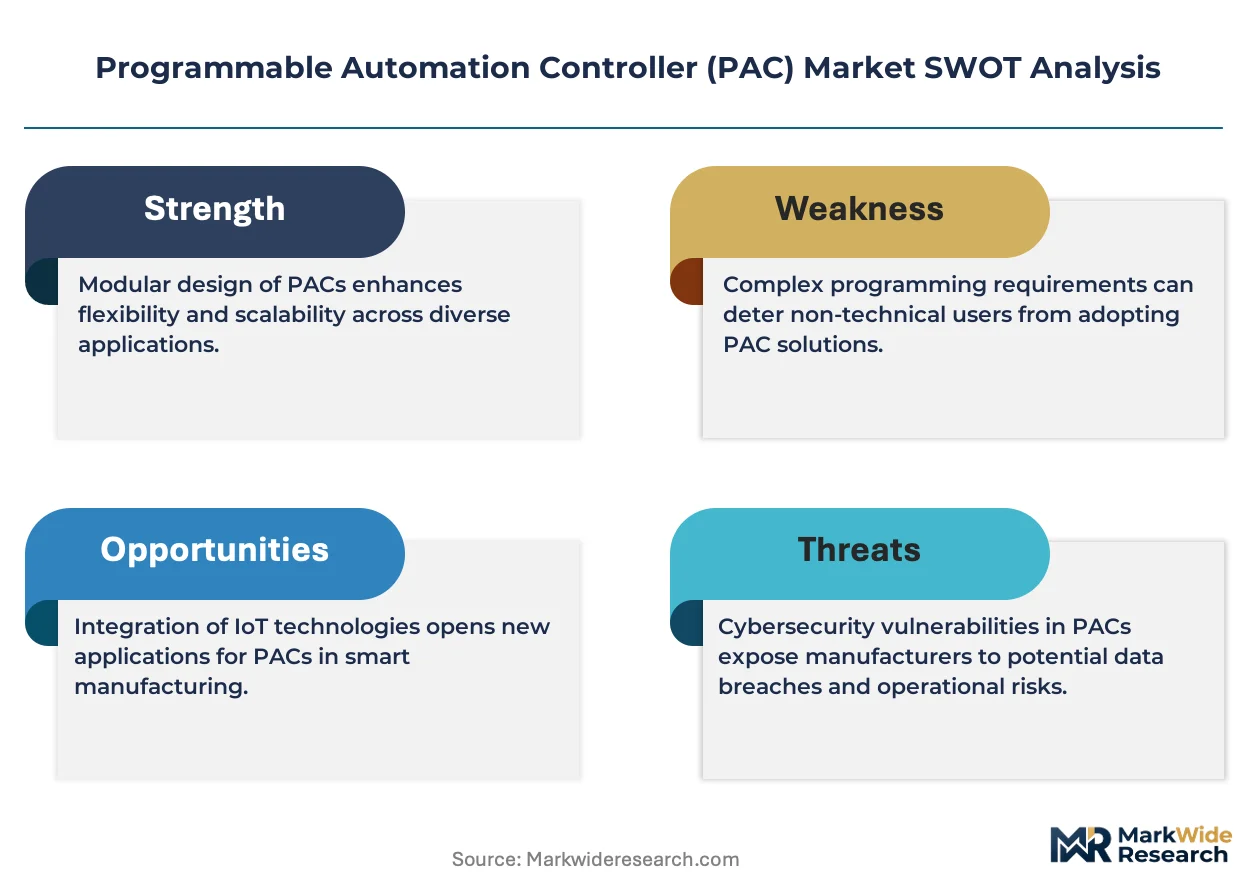
- High Initial Investment:The total cost of deploying a PAC system, including hardware, software licenses, engineering, and integration services, presents a significant capital expenditure barrier, particularly for small and medium-sized enterprises (SMEs) seeking to upgrade their automation infrastructure.
- Legacy System Integration:Significant friction exists when attempting to integrate modern PACs into existing factory environments that rely on older, proprietary communication protocols and legacy equipment, often requiring costly and complex custom gateways or system overhauls.
- PLC Capability Creep:Advances in technology are enabling high-end Programmable Logic Controllers (PLCs) to perform tasks previously exclusive to PACs, creating a substitution threat and compressing the distinction at the lower end of the PAC market.
Strategic Opportunities
- Edge Computing Workloads:Integrating edge computing capabilities directly into PACs creates an opportunity to offer real-time data analytics and machine learning inference at the machine level, reducing latency and reliance on cloud infrastructure for critical process decisions.
- Energy Management Solutions:Regulatory pressures such as the EU Green Deal are creating demand for advanced process optimization to improve energy efficiency. PACs are well-positioned to meet this need by managing complex energy consumption and reporting data for sustainability compliance.
- Automation in Southeast Asia:The expanding manufacturing sectors in countries like Vietnam and Thailand represent an underpenetrated market. These regions are actively modernizing production facilities, creating new demand for scalable and advanced automation controllers beyond basic PLCs.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of automation engineers and technicians who possess hybrid skills in both traditional OT disciplines like ladder logic and modern IT competencies such as network security and object-oriented programming hinders system implementation and maintenance.
- Cybersecurity Vulnerabilities:The increased network connectivity of PACs, essential for Industry 4.0, exposes critical industrial control systems to a wider range of cybersecurity threats, demanding robust security measures and constant vigilance against potential breaches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Automation Controller (PAC) Market |
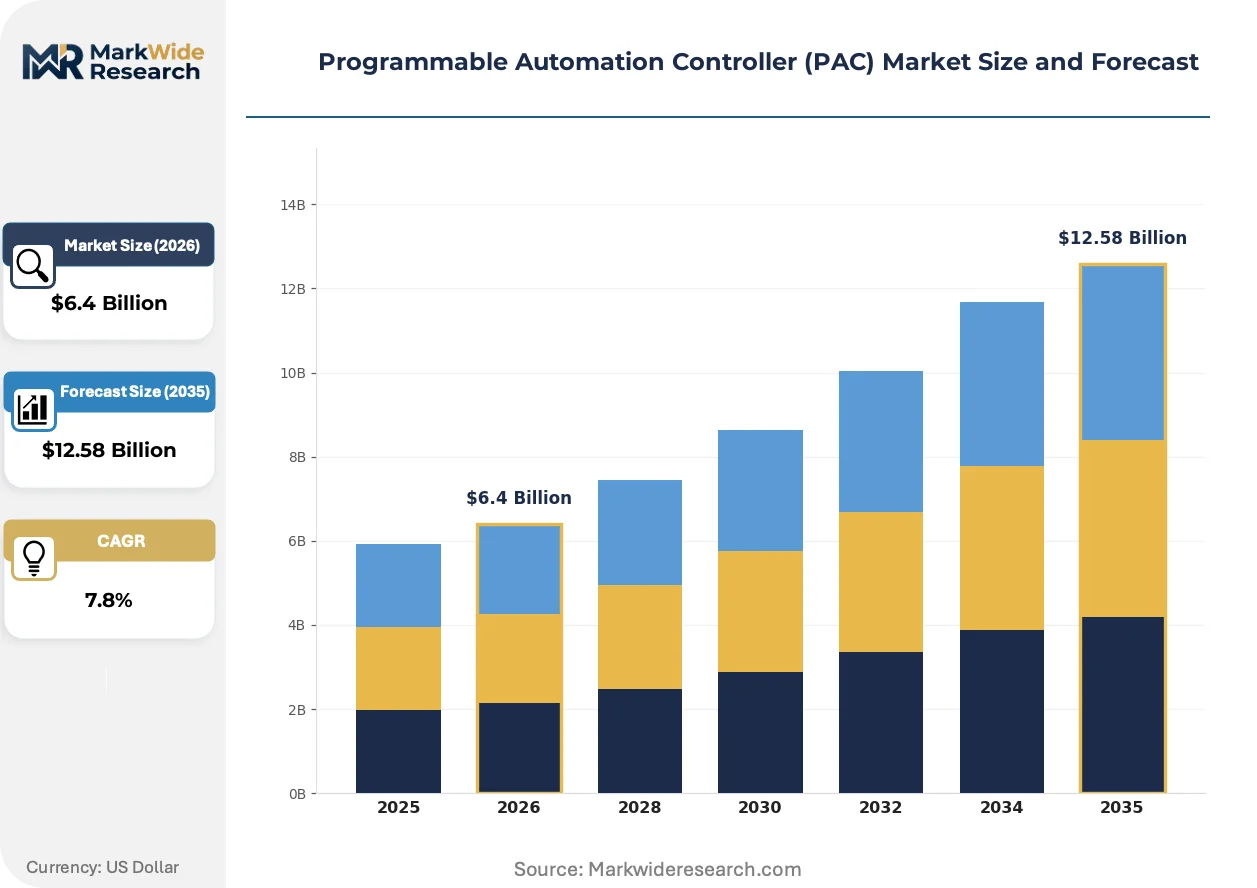
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $12.58 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular PAC, Compact PAC, Fixed I/O PAC, Rack-mounted PAC Technology: Ethernet/IP, Modbus TCP, Profibus, DeviceNet, ControlNet Application: Process Control, Factory Automation, Machinery Monitoring, Building Automation, Water Treatment End User Industry: Consumer Electronics, Aerospace Manufacturing, Oil Refining, Food Processing, Pharmaceutical Production |
| Companies Covered | Mitsubishi Electric Corporation, Emerson Electric, Siemens AG, Yokogawa Electric Corporation, Honeywell International, Rockwell Automation, ABB Ltd, Omron Corporation, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Automation Controller (PAC) Market Strategic Shifts & Innovations
The fusion of operational control logic with advanced data processing is reshaping automation architectures. This integration enables real-time decision-making on the factory floor, creating the foundation for intelligent and adaptive manufacturing systems.
Multi-core processors enable high-speed, parallel processing of control, motion, and data tasks on a single device. Machinery OEMs and system integrators are rapidly adopting these processors for complex packaging and robotic applications. This integration of powerful processing is miniaturizing the control cabinet footprint, combining functions that once required multiple separate controllers.
The EU's Machinery Directive, enforced via mandatory CE marking, sets stringent functional safety requirements for industrial equipment. This regulation compels manufacturers to embed certified safety functions directly into their control architecture. Consequently, PACs with integrated safety capabilities are gaining traction in the European market, particularly within robotics and material handling systems.
End-users increasingly specify PACs supporting open protocols like OPC UA and MQTT, moving away from vendor-locked ecosystems. This shift disrupts the traditional model where integrators were tied to a single vendor's hardware and software stack. The trend is most prominent in factory automation projects in Germany and the United States, where interoperability is key.
Programmable Automation Controller (PAC) Market Segmentation
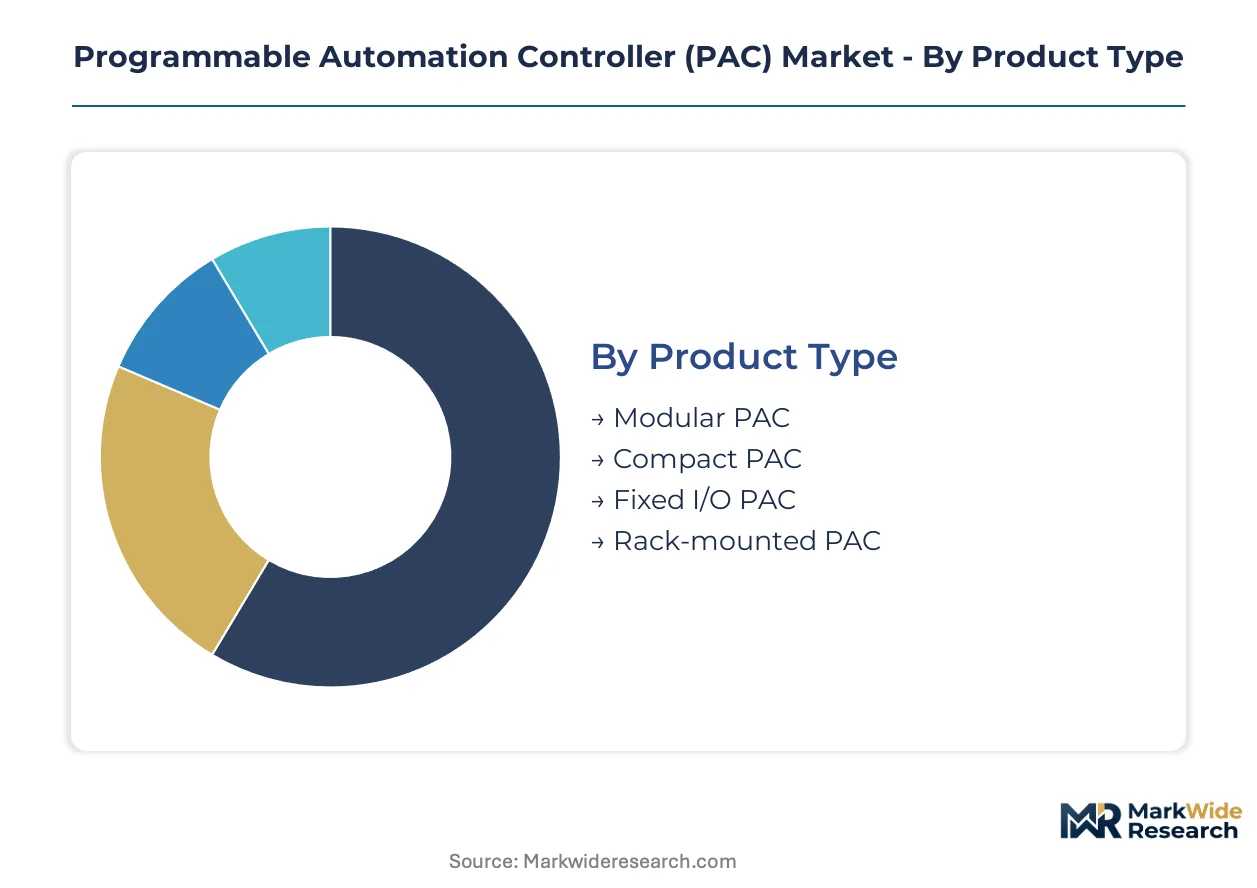
The Programmable Automation Controller (PAC) market is highly differentiated, reflecting the diverse industrial requirements for automation and control systems. Understanding these segmentations is crucial for identifying specific demand pockets, technological preferences, and the strategic positioning of solutions across various end-user environments.
Product Type:
The distribution channels for Programmable Automation Controllers are shaped by the product type, with certain configurations favoring direct sales to large integrators while others move through specialized distributors catering to SMEs.
- Modular PAC:A highly configurable industrial computer, these PACs allow for extensive customization through interchangeable I/O modules and processing units. Demand concentrates in large-scale factory automation projects in China, driven by the need for scalable and flexible control systems for complex production lines.
- Compact PAC:Integrating CPU and I/O into a single, smaller form factor, these controllers are designed for space-constrained applications. Their growth is pronounced in machinery monitoring and smaller process control applications, particularly within the US manufacturing sector, where efficiency and footprint reduction are critical.
- Fixed I/O PAC:These PACs offer a predetermined set of input/output points, simplifying configuration for less complex, dedicated control tasks.
- Rack-mounted PAC:Designed for installation in standard industrial racks, these units provide robust processing power for centralized control systems in large facilities.
By volume, Modular PACs lead the market. By growth pace, Compact PACs are ahead.
Technology:
The choice of communication technology for PACs directly impacts system interoperability and data exchange capabilities across various industrial applications.
- Ethernet/IP:An industrial application layer protocol built on standard Ethernet, it enables real-time control and information exchange across manufacturing operations. This technology is critical for integrating PACs into Industry 4.0 architectures, particularly within advanced factory automation in Germany, where seamless data flow is paramount.
- Modbus TCP:A widely adopted, open industrial communication protocol utilizing TCP/IP for reliable data exchange over standard Ethernet networks. Its simplicity and widespread support make it a common choice for process control applications globally, especially in sectors requiring robust, yet straightforward, connectivity.
- Profibus:A fieldbus standard for factory and process automation, offering high-speed data transfer for distributed control systems in European industries.
- DeviceNet:Based on the Common Industrial Protocol (CIP), this network connects industrial devices, facilitating communication between sensors, actuators, and PACs in discrete manufacturing.
- ControlNet:A real-time control network providing high-speed, deterministic data delivery for critical inter-controller communication and I/O applications.
The dominance of Ethernet/IP reflects a broader industry shift towards open communication protocols and enhanced network connectivity.
Application:
Different PAC applications cater to distinct customer requirements, ranging from large-scale enterprise integration to localized machine-level control.
- Process Control:This application involves regulating continuous or batch processes, such as chemical reactions, temperature, and flow rates, requiring precise and reliable control. The pharmaceutical production sector exhibits significant pull for PACs due to stringent requirements for process validation and data integrity.
- Factory Automation:PACs manage complex, discrete manufacturing processes, coordinating robotics, assembly lines, and material handling systems to optimize production efficiency. Demand is concentrating in manufacturing hubs within China, driven by extensive factory automation upgrades and national policies.
- Machinery Monitoring:PACs collect and analyze performance data from individual machines, enabling predictive maintenance and operational optimization across various industrial settings.
- Building Automation:These systems utilize PACs for managing HVAC, lighting, security, and access control within commercial and industrial buildings, enhancing energy efficiency and operational safety.
- Water Treatment:PACs control and monitor various stages of water and wastewater treatment, ensuring compliance with environmental regulations and optimizing resource usage.
The critical nature of Process Control drives stringent performance requirements for PACs, while Factory Automation benefits from their scalability across diverse production environments.
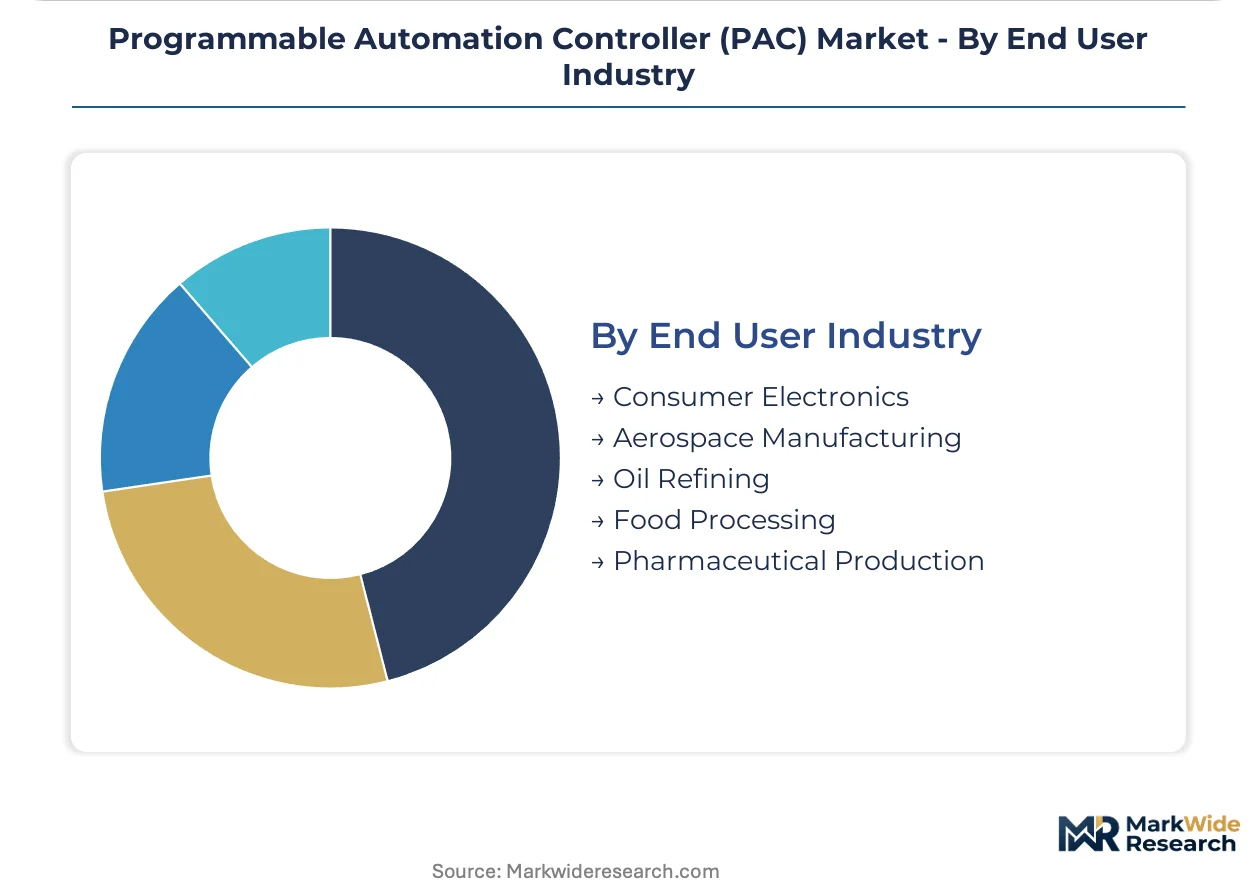
End User Industry:
The maturity of automation adoption varies significantly across end-user industries, influencing the specific PAC features and integration levels required.
- Pharmaceutical Production:This sector requires PACs for precise control over drug manufacturing processes, ensuring adherence to strict regulatory standards like FDA and EMA guidelines for quality and traceability. The stringent requirements for process validation and data integrity create significant pull for PACs in this industry.
- Food Processing:PACs manage various stages of food and beverage production, from raw material handling to packaging, ensuring product consistency, safety, and compliance with hygiene regulations. This industry leverages PACs for optimizing batch processes and maintaining quality control across diverse product lines.
- Consumer Electronics:PACs are integral to the high-volume, precision manufacturing of consumer electronic devices, managing assembly lines and testing equipment.
- Aerospace Manufacturing:This industry uses PACs for highly specialized and complex manufacturing processes, including precision machining and assembly of critical aircraft components.
- Oil Refining:PACs provide robust control for continuous processes in oil and gas refining, managing complex chemical reactions and ensuring operational safety and efficiency.
Regulatory pressures in Pharmaceutical Production mandate advanced PAC capabilities for compliance, whereas Food Processing focuses on throughput and efficiency optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Programmable Automation Controller market exhibits strong demand from industries requiring high precision and compliance, such as pharmaceutical production and advanced manufacturing. These buyers prioritize PACs capable of complex logic and seamless integration with enterprise systems. Regional growth patterns reflect varying levels of industrial modernization and regulatory frameworks.
China
China's market demand for PACs is driven by extensive factory automation upgrades across its manufacturing hubs. National policies supporting industrial modernization, coupled with GB standards, accelerate PAC adoption in centers like the Yangtze River Delta.
United States
The United States market shows robust demand for PACs in machinery monitoring and smaller process control, favoring compact PACs for efficiency. FDA regulations for pharmaceutical production create significant pull for PACs offering precision and data integrity in Midwest industrial clusters.
Germany
Germany experiences strong PAC demand driven by advanced factory automation and integration of open communication protocols like Ethernet/IP. Compliance with the EU's Machinery Directive, enforced via CE marking, compels manufacturers to embed certified safety functions in regions like Baden-Württemberg.
Japan
Japanese industries demand PACs for high-precision manufacturing, robotics, and the automotive sector, focusing on operational efficiency. Policies from METI support digitalization, encouraging advanced automation technology adoption in major industrial areas around Tokyo.
India
India's expanding manufacturing sector, particularly in pharmaceutical production, fuels demand for PACs to enhance process control and data integrity. Government initiatives like the PLI scheme incentivize domestic manufacturing, driving automation upgrades in pharmaceutical clusters like Hyderabad.
Programmable Automation Controller (PAC) Market Key Industry Players
Player mix skews toward established industrial automation conglomerates and specialized technology providers. The market structure is moderately consolidated, with a few dominant global players holding significant influence, alongside numerous regional and niche specialists. Strategic archetypes include integrated solution providers, focused technology innovators emphasizing edge computing, and regional market specialists. Dominant competitive moves involve portfolio diversification into software and services, along with strategic partnerships to expand ecosystem compatibility and address new application areas.
Among global industrial automation suppliers, Siemens AG, a German industrial manufacturing conglomerate, exemplifies an integrated architecture approach dominating the European market. Rockwell Automation, a US-based provider of industrial automation and information products, sustains a strong position in North America through its integrated architecture platform. Schneider Electric, a French multinational specializing in energy management and automation solutions, competes with a focus on diverse end-user industries and process automation.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Emerson Electric |
| Siemens AG |
| Yokogawa Electric Corporation |
| Honeywell International |
| Rockwell Automation |
| ABB Ltd |
| Omron Corporation |
| Schneider Electric |
Cost & Logistics Intelligence
Project-based contracts for complex factory automation systems lock in both supply access and price visibility for large enterprises. This structure allows integrators to manage costs for specialized PAC configurations in regions like China and Germany.
Pricing Analysis
Cost-plus contracts, often indexed to component prices, define the dominant pricing structure for PAC systems. Price differentiation stems from certification levels, such as CE marking for European markets, and the degree of customization required for specific process control applications. Pricing pressure stems from PLC capability creep, particularly for lower-end PACs where high-end PLCs offer similar functionalities. Small and medium-sized enterprises (SMEs) exhibit the highest price sensitivity, while pharmaceutical producers prioritize compliance and functionality over initial cost.
Supply Chain Analysis
Port congestion in key Asian shipping hubs influences inbound logistics costs for PAC components. Geographic supply concentration for core microprocessors and specialized I/O modules primarily resides in Taiwan, South Korea, and China. A structural supply chain risk is single-source vulnerability for advanced multi-core processors, essential for high-speed computation. Distribution runs through a hybrid model, combining direct sales to large system integrators with specialized distributors serving smaller machinery OEMs and end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a high-growth disruption point, driven by the convergence of Information Technology (IT) and Operational Technology (OT) within Industry 4.0 paradigms. This integration reshapes competitive positioning for established automation providers and new entrants alike.
For Market Incumbents: Secure market share by deepening vertical integration into software and services, particularly cloud-based analytics platforms and cybersecurity solutions. Invest significantly in R&D for integrated safety functions to meet stringent regulations like the EU's Machinery Directive, countering the threat from specialized edge computing innovators. Expand capacity in key manufacturing hubs like China to serve extensive factory automation upgrades.
For New Entrants and Emerging Players: Lead with specialized solutions targeting underpenetrated segments, such as compact PACs for machinery monitoring in the US manufacturing sector. Focus on developing PACs that natively support open protocols like OPC UA and MQTT, offering a compelling alternative to vendor-locked ecosystems. A strong go-to-market angle involves partnering with regional system integrators to offer flexible, interoperable solutions for specific industrial applications.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors integrated solution providers with strong software capabilities. Long-term viability remains strong, driven by ongoing industrial modernization and the demand for precision control in sectors like pharmaceutical production. Target acquisition archetype involves mid-cap technology innovators specializing in edge computing or cybersecurity for industrial control systems. A signal to watch is the increasing adoption rate of PACs with certified safety functions.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Software | Expands revenue streams and strengthens ecosystem compatibility with cloud-based analytics platforms. |
| Investment in Integrated Safety Functions | Ensures compliance with regulations like the EU's Machinery Directive and enhances market access in Europe. |
| Strategic Partnerships for Ecosystem Compatibility | Broadens interoperability with diverse industrial communication protocols and reduces vendor lock-in for end-users. |
| Geographic Manufacturing Footprint Expansion | Addresses growing demand from industrial modernization initiatives in regions like China and Southeast Asia. |
| Acquisition of Edge Computing Specialists | Integrates real-time data analytics capabilities directly into PACs, reducing latency for critical process decisions. |
Research Approach
Initial hypotheses were tested against primary input from automation engineers, plant managers, system integrators, and procurement leads, then refined through iterative analysis. This approach combined in-depth primary interviews with rigorous secondary validation from industry reports, technical specifications, and regulatory filings (e.g., FDA, EMA, GB standards). Bottom-up and top-down triangulation ensured consistency across various data points.
Variance decomposition highlighted key drivers influencing market growth across the analysis window, including product type, technology, application, and end-user industry. The analytical framework modeled PAC adoption rates based on factory automation upgrade cycles and industrial modernization policies. Compound annual growth rates were derived from historical data trends and projected technological advancements. Industrial investment data and regulatory compliance timelines were key forecast inputs.
Forecasts assume regulatory continuity in major industrial regimes, including the EU, US, and China; material policy shifts would require re-modeling. Projections reflect current technological trajectories and market dynamics. Potential disruptions from unforeseen geopolitical events or rapid technological obsolescence represent risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Asia Pacific Warehouse Automation Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Industrial Embedded Systems Market
Industrial Automation
Europe Industrial Embedded Systems Market
Industrial Automation
China Factory Automation and Industrial Controls Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Asia-Pacific Automation Components Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
United States Factory Automation and Industrial Controls Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Asia Pacific Industrial Communication Market