
 Global Electric Gripper Market | 2026-2036
Global Electric Gripper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Gripper Market Analysis
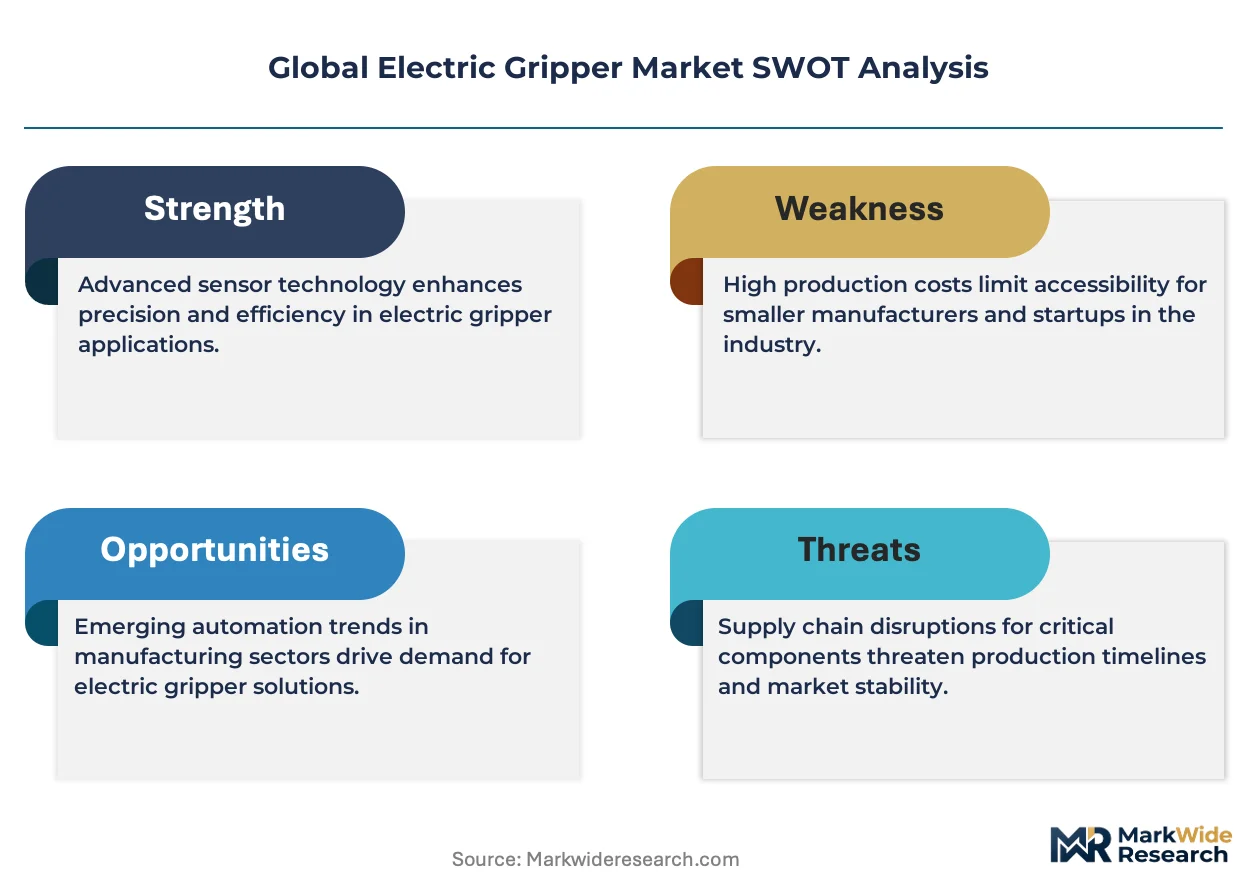
The gap between servo motor precision and pneumatic cost economics is narrowing as brushless DC actuator prices fall and integrated force-torque sensors become standard. SCHUNK leverages its captive sensor manufacturing to control quality across German and Chinese production lines. Festo anchors its position through deep backward integration into valve and drive electronics. OnRobot competes by specializing in quick-change interfaces that reduce robot cell reconfiguration downtime.
An electric gripper is an electromechanical end effector that uses servo motors, stepper drives, or linear actuators to generate programmable gripping force typically between 50 N and 3,000 N, with positional repeatability below 0.02 mm for precision assembly tasks. Electric actuation technology leads unit shipments due to its compatibility with Industry 4.0 data architectures and elimination of compressed air infrastructure. Servo grippers represent the fastest-expanding product category as semiconductor and medical device manufacturers demand sub-millimeter placement accuracy. Custom grippers occupy the highest margin pool where application-specific jaw geometries and multi-axis compliance justify engineering premiums.
The EU Machinery Directive and ISO 10218 safety standards shape product design by mandating force-limiting protocols and emergency-stop integration for collaborative deployments. Japan's METI promotes next-generation manufacturing through subsidies that favor electric over pneumatic automation in SME facilities. China's GB standards for industrial robot safety create compliance thresholds that filter out uncertified imports. Stakeholders must monitor how regional subsidy programs and carbon accounting rules tilt total-cost-of-ownership calculations between electric and legacy pneumatic systems.
Market Dynamics
The electric gripper market is being restructured by the phase-out of pneumatic infrastructure in precision manufacturing, as compressed air systems face carbon accounting penalties and Industry 4.0 incompatibility. This technology substitution is compressing the traditional cost advantage of legacy actuation while elevating servo-electric architectures.
Growth Catalysts
- EU Machinery Directive force-limiting mandates:Collaborative robot deployments in German automotive plants require certified electric grippers with integrated safety protocols, eliminating uncertified pneumatic alternatives from tender processes.
- Semiconductor backend packaging:Wafer handling and die placement operations in Taiwan and South Korea fabs demand sub-0.02 mm repeatability that only servo-electric actuation delivers at production scale.
- Brushless DC actuator cost curves:Magnet material processing advances and Chinese motor manufacturing scale are collapsing price premiums versus pneumatic cylinders below the 500 N force threshold.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China's Inner Mongolia and Jiangxi provinces, creating single-source vulnerability for high-torque servo gripper motors.
- Force density limitations:Electric actuation above 3,000 N gripping force requires prohibitively large motor packages that exceed robot payload constraints in heavy forging and foundry applications.
- Pneumatic installed base lock-in:Existing compressed air infrastructure in Japanese SME machine shops represents sunk capital that METI subsidies alone cannot fully offset within standard depreciation cycles.
Strategic Opportunities
- India PLI scheme for robotics:Production-linked incentives for industrial automation component manufacturing are attracting electric gripper assembly operations to Gujarat and Tamil Nadu industrial corridors.
- Medical device cleanroom assembly:ISO 14644 Class 7 compliant electric grippers eliminate pneumatic oil contamination risks in syringe and implantable device packaging lines.
- AI-driven adaptive grasping:Convergence of machine vision algorithms with integrated force-torque sensing enables real-time grip force modulation for deformable and irregular objects without manual programming.
Industry Challenges
- Safety certification timeline compression:ISO 10218-1 and ISO/TS 15066 collaborative robot safety validations require 8-14 month lead times that mismatch automotive program launch schedules.
- Multi-protocol integration complexity:EtherCAT, PROFINET, and EtherNet/IP fieldbus fragmentation forces gripper manufacturers to maintain redundant electronics SKUs for different robot OEM ecosystems.
- Precision machining talent scarcity:Manufacturing of harmonic drive and planetary gearbox components for servo grippers depends on Swiss and German machining expertise with limited apprentice pipeline replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Gripper Market |
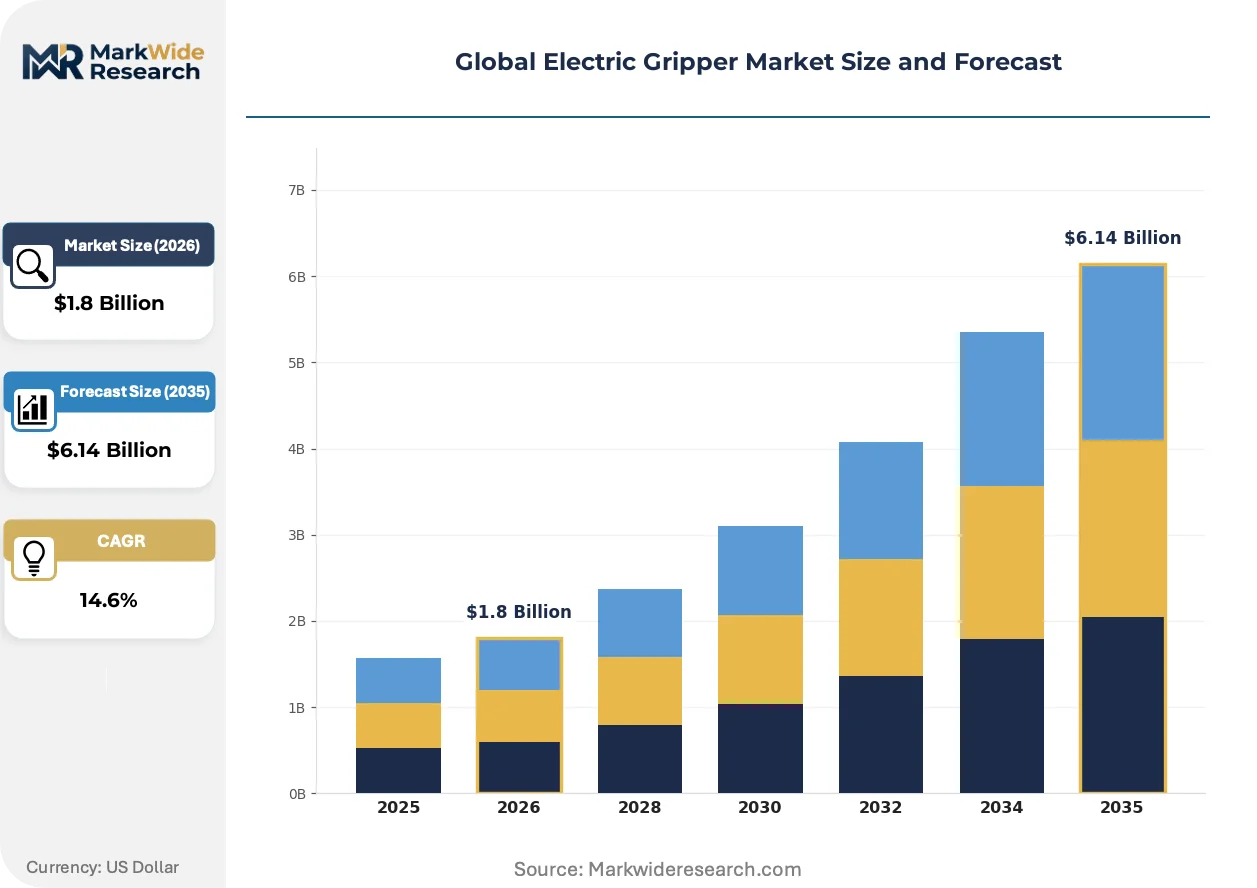
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Finger Grippers, 3-Finger Grippers, Servo Grippers, Custom Grippers Application: Assembly Automation, Robotics, Material Handling, Packaging Solutions End User: Aerospace, Automotive, Electronics, Food & Beverage Technology: Pneumatic Actuation, Electric Actuation, Hydraulic Actuation, Hybrid Systems |
| Companies Covered | SCHUNK, SMC, Destaco, Festo, Parker Hannifin, Zimmer Group, IAI, Gimatic, OnRobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Gripper Market Emerging Trajectories
Servo-electric actuation is converging with sensor fusion architectures to enable autonomous grip adjustment, while regulatory carbon accounting and safety mandates are accelerating pneumatic displacement in regulated industries.
Soft robotics materials are hybridizing with traditional servo-electric frameworks to expand graspable object geometries. Silicone and fabric-reinforced elastomer fingers now integrate with standard servo drives, enabling food handling and delicate electronics manipulation without dedicated tool changes. Bakery and fresh produce packagers in the Netherlands and California are deploying these hybrid systems at pilot scale. The technology is hybridizing rigid precision with compliant adaptability, collapsing the historical trade-off between gripper versatility and placement accuracy.
Japan's METI carbon neutrality roadmap for manufacturing equipment is mandating compressed air leakage audits and efficiency standards that disadvantage legacy pneumatic automation. Facilities failing efficiency benchmarks face surcharge penalties under the country's emissions trading scheme. Small and medium metalworking enterprises in the Nagoya industrial corridor are responding by retrofitting electric actuation into existing robot cells rather than accepting ongoing carbon costs.
Buying committees in automotive tier-one suppliers are consolidating vendor relationships to reduce integration overhead, favoring gripper suppliers offering unified software environments across multiple robot brands. This preference compression is marginalizing point-solution specialists lacking cross-platform compatibility. The pattern is most pronounced in German and South Korean automotive supply chains, where multi-brand robot fleets are standard and single-vendor gripper standardization reduces spare parts inventory and technician training burden.
Global Electric Gripper Market Segmentation
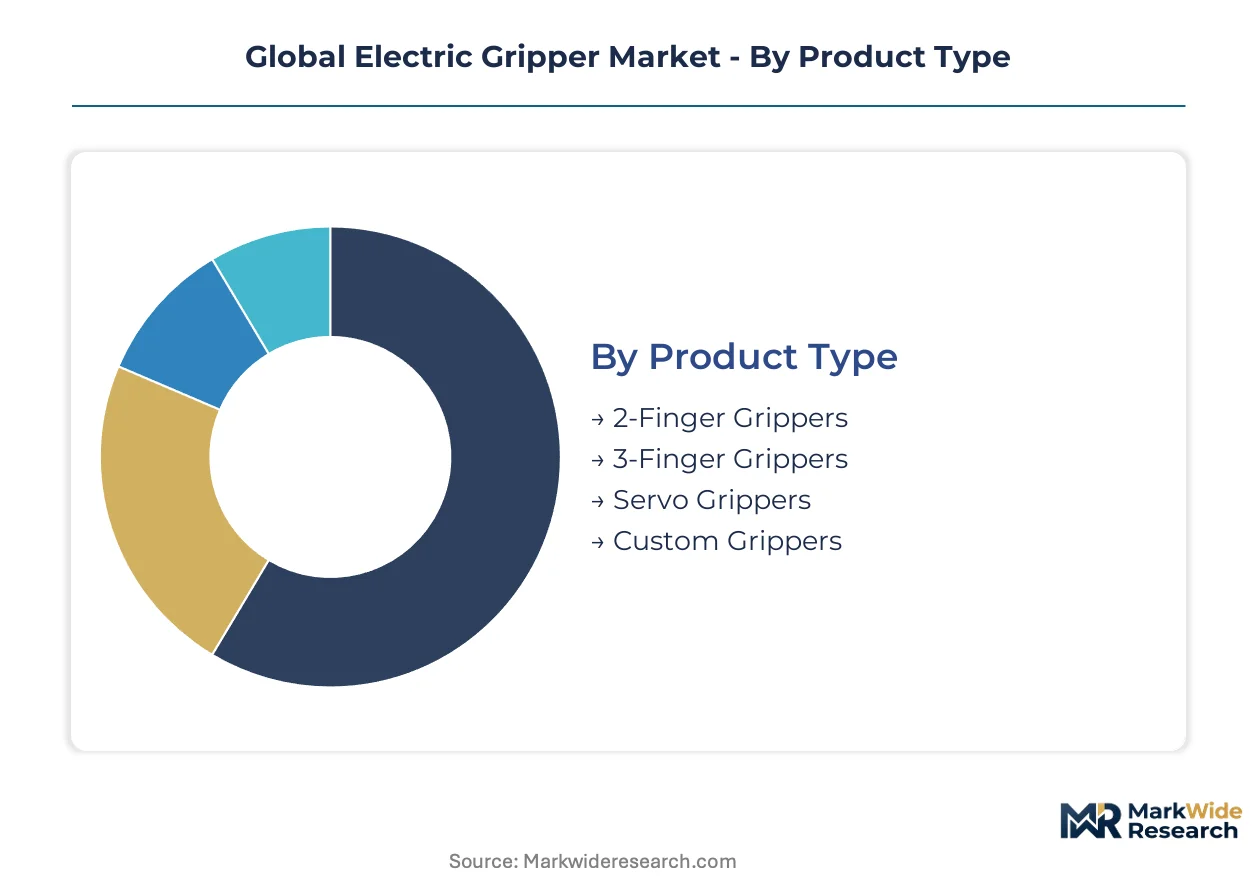
Electric gripper segmentation reveals how actuation technologies, jaw configurations, and end-use precision requirements fragment procurement patterns. Buyers optimize around force density, repeatability specifications, and integration complexity rather than unit cost alone.
Product Type:
Mature two-finger architectures dominate installed bases while emerging multi-axis and application-specific designs capture premium engineering budgets.
- 2-Finger Grippers:Parallel and angular jaw configurations using rack-and-pinion or cam-driven mechanisms deliver gripping forces from 50 N to 1,500 N. German automotive tier-one suppliers specify these for engine component transfer operations where cycle time and mechanical simplicity outweigh adaptive grasping needs. 2-Finger Grippers retain volume leadership; Custom Grippers hold the steepest expansion curve.
- 3-Finger Grippers:Centric and concentric designs with three synchronous fingers achieve uniform clamping force distribution for cylindrical workpieces. Taiwan semiconductor backend facilities deploy these for wafer cassette handling where concentricity errors below 0.01 mm prevent costly substrate damage.
- Servo Grippers:Integrated brushless DC motors with encoder feedback enable programmable force and position profiles across 0.02 mm repeatability thresholds. Japanese medical device manufacturers specify these for syringe assembly lines requiring ISO 13485 traceability.
- Custom Grippers:Application-specific jaw geometries with multi-axis compliance mechanisms address irregular geometries and delicate surface finishes. Swiss watchmaking sub-contractors commission these for micro-mechanical component manipulation where standard catalogs fail.
2-Finger Grippers retain volume leadership; Custom Grippers hold the steepest expansion curve.
Application:
Cost tiers separate high-volume repetitive tasks from precision-engineered operations where downtime penalties dwarf equipment amortization.
- Assembly Automation:Precision placement of components with force-controlled insertion prevents damage to mating parts. South Korean electronics contract manufacturers deploy electric grippers for smartphone camera module assembly where sub-Newton force thresholds protect fragile flex circuits.
- Robotics:Collaborative robot integrations require certified force-limiting grippers with emergency-stop handshaking per ISO 10218-1. German automotive OEMs mandate these for human-robot mixed assembly stations.
- Material Handling:Bin picking and palletizing operations prioritize cycle rate and payload capacity over placement precision. Chinese logistics automation providers specify standard servo grippers for e-commerce fulfillment centers.
- Packaging Solutions:Sanitary designs with IP69K ratings and food-contact materials dominate primary and secondary packaging lines. Netherlands dairy processors deploy these for cheese wheel handling where pneumatic oil contamination risks disqualify legacy actuation.
Material Handling commands the largest installed base; Assembly Automation generates the highest average selling prices.
End User:
Customer type stratification separates regulated industries with certification burdens from price-sensitive volume manufacturers.
- Aerospace:Traceability requirements and exotic material handling drive specification of ATEX-rated and titanium-compatible gripper variants. French aerostructure suppliers specify these for carbon fiber layup operations.
- Automotive:Powertrain and body-in-white operations demand force densities above 2,000 N with MTBF ratings exceeding 50,000 hours. Japanese and German OEMs lead electric gripper penetration as they phase out pneumatic infrastructure.
- Electronics:Miniaturization trends and cleanroom compatibility requirements favor compact servo grippers with integrated force-torque sensing. Taiwan and South Korea fab equipment suppliers dominate procurement.
- Food & Beverage:Hygienic design standards and washdown compatibility constrain material selection and sealing architectures. Italian packaging machinery OEMs integrate these for pasta and confectionery handling lines.
Automotive maintains the deepest electric gripper penetration; Electronics shows the most rapid technology refresh cycles.
Technology:
Supply concentration in motor manufacturing and sensor integration shapes competitive positioning across actuation architectures.
- Pneumatic Actuation:Compressed air cylinders with mechanical grippers retain cost advantages above 3,000 N force thresholds and in legacy installations. Japanese SME machine shops maintain these where METI subsidies prove insufficient for full replacement.
- Electric Actuation:Servo motor and stepper drive architectures dominate new installations below 2,000 N with Industry 4.0 data compatibility. Chinese motor manufacturing scale has collapsed price premiums versus pneumatic alternatives.
- Hydraulic Actuation:High-force density for heavy forging and foundry applications where electric motor packages exceed robot payload constraints. German automotive stamping operations retain these for hot-forming die transfers.
- Hybrid Systems:Combinations of electric precision with pneumatic power density address mid-range force requirements with adaptive compliance. Emerging deployments in Italian ceramic tile handling where surface irregularities demand programmable grip profiles.
Electric Actuation leads new order intake; Hybrid Systems are gaining share fastest in materials processing applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive buyers concentrate procurement authority for collaborative robot integrations, while East Asian electronics manufacturers drive precision servo specifications. Japanese SME metalworkers and Chinese logistics operators represent diverging adoption timelines.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg mandate ISO 10218-1 certified electric grippers for human-robot mixed assembly stations. The EU Machinery Directive's force-limiting protocols eliminate uncertified pneumatic alternatives from tender processes. Bavarian powertrain plants are phasing out compressed air infrastructure ahead of carbon accounting deadlines.
China
Shenzhen and Shanghai electronics contract manufacturers deploy servo grippers for smartphone camera module assembly requiring sub-Newton force thresholds. GB standards for industrial robot safety create compliance thresholds filtering uncertified imports. Yangtze River Delta fab equipment suppliers dominate semiconductor backend packaging procurement.
Japan
Nagoya industrial corridor metalworking SMEs retrofit electric actuation into existing robot cells to avoid METI carbon neutrality surcharge penalties. METI subsidies favor electric over pneumatic automation, though existing compressed air infrastructure represents sunk capital slowing full replacement. Osaka medical device manufacturers specify servo grippers for syringe assembly lines.
South Korea
Busan-Ulsan electronics clusters demand wafer handling repeatability below 0.02 mm for die placement operations. The country's emissions trading scheme accelerates pneumatic displacement in regulated facilities. Seoul Capital Area robot integrators consolidate vendor relationships to reduce multi-brand fleet overhead.
United States
California fresh produce packagers pilot hybrid soft-robotic systems for delicate food handling without pneumatic oil contamination risks. FDA sanitary design requirements constrain material selection for medical device cleanroom assembly. Michigan automotive stamping operations retain hydraulic actuation for hot-forming die transfers above 3,000 N thresholds.
Global Electric Gripper Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement channels. German and Japanese incumbents anchor premium positioning through captive sensor manufacturing and backward integration into drive electronics. Specialist vendors compete on quick-change interfaces and cross-platform software compatibility. Consolidation pressure favors unified software environments; geographic expansion targets Indian PLI scheme corridors and Southeast Asian electronics clusters.
Among German-based precision manufacturers, SCHUNK GmbH & Co. KG and Festo SE & Co. KG exemplify archetypes combining captive component manufacturing with multi-regional production footprints. Zimmer Group represents mid-scale specialists competing through application-specific engineering. These three anchors illustrate how control over sensor integration, valve electronics, or custom jaw geometries shapes competitive positioning without requiring scale-driven cost structures.
| Leading Market Players |
|---|
| SCHUNK |
| SMC |
| Destaco |
| Festo |
| Parker Hannifin |
| Zimmer Group |
| IAI |
| Gimatic |
| OnRobot |
| Others |
Supply Flow & Price Mechanics
Inner Mongolia and Jiangxi provinces anchor rare earth magnet supply for brushless DC servo motors, concentrating pricing power among Chinese processors who index long-term contracts to neodymium and dysprosium spot benchmarks. This geographic chokepoint shapes cost structures downstream, forcing German and Japanese gripper manufacturers to absorb volatility or renegotiate tier-one automotive supply agreements.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate procurement between magnet processors and motor manufacturers, with price adjustments triggered quarterly. Three-tier pricing structure across certified collaborative units, standard servo architectures, and economy stepper variants reflects ISO 10218-1 validation burdens. Cost compression in economy tier intensifies because Chinese motor manufacturing scale collapses premium spreads. Automotive tier-one buyers exhibit lowest price sensitivity due to program lock-in penalties, while logistics automation providers in Chinese e-commerce clusters drive hardest bargain.
Supply Chain Analysis
Supplier-financing facilities with 90-120 day extended terms have become standard for Taiwanese semiconductor equipment suppliers sourcing from Japanese harmonic drive specialists. Magnet processing concentrates in China, precision machining in Germany and Switzerland, and final assembly across China, Germany, and emerging Gujarat corridors under India's PLI scheme. Rare earth supply draws from single-source vulnerability in Inner Mongolia refining capacity. Distribution runs through robot OEM captive channels, integrator specification influence, and direct industrial end-user procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards captive control over force-torque sensor calibration and harmonic drive machining expertise, assets concentrated among German and Swiss specialists with limited apprentice pipeline replacement. This capability scarcity elevates acquisition premiums for precision component manufacturers and forces buyers into long-term sole-source dependencies.
For Market Incumbents: Harden supply security through captive magnet processing partnerships or long-term offtake with Chinese rare earth refiners, while accelerating ISO 10218-1 certification throughput to compress 8-14 month validation timelines. Defend against emerging soft-robotic hybrid entrants by embedding silicone-elastomer finger modules into existing servo platforms, denying white-space to adaptive grasping specialists. For New Entrants and Emerging Players: Establish a beachhead in medical device cleanroom assembly where ISO 14644 Class 7 compliance and FDA validation requirements filter out uncertified incumbents. Target India's Gujarat and Tamil Nadu industrial corridors under PLI scheme subsidies, offering cross-platform EtherCAT-PROFINET compatibility that German automotive buyers increasingly mandate for multi-brand robot fleets. For Investors and Strategic Acquirers: Long-term, this sits as a substitution-cycle play because pneumatic infrastructure phase-out across German automotive and Japanese SME metalworking creates durable replacement demand regardless of macroeconomic cyclicality. Prioritize targets with captive sensor manufacturing or Swiss machining heritage. Watch METI carbon neutrality surcharge enforcement and EU Machinery Directive audit intensity as inflection signals for electric adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Magnet Processing | Secures neodymium supply for high-torque servo motors against Chinese export concentration. |
| ISO 10218-1 Certification Acceleration Program | Compresses validation timelines to match German automotive program launch schedules. |
| Soft-Robotic Hybrid Product Line Launch | Captures Netherlands food handling pilots with silicone-elastomer adaptive fingers. |
| Cross-Platform Software Environment Development | Consolidates vendor relationships for South Korean multi-brand robot fleet operators. |
| India PLI Scheme Manufacturing Footprint | Positions for robotics component subsidies in Gujarat and Tamil Nadu corridors. |
Methodological Framework
The analysis maps servo-electric, hybrid, and pneumatic actuation architectures, each validated through plant engineers at German automotive tier-one suppliers, procurement leads at Taiwanese semiconductor equipment manufacturers, and maintenance directors at Japanese SME metalworking facilities. Primary fieldwork combined with secondary validation from SEC filings of listed automation component suppliers, customs trade data on rare earth magnet flows, and ISO certification registry databases. Bottom-up unit shipment estimates triangulate against top-down industrial robot installation data across the analysis window.
Forecast assumptions held fixed the EU Machinery Directive enforcement trajectory and METI carbon neutrality surcharge implementation, while varying brushless DC actuator cost curves and rare earth supply disruption scenarios. Segmentation dimensions modeled include actuation technology, jaw configuration, end-use industry precision requirements, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to technology substitution patterns in pneumatic displacement. Key inputs span semiconductor backend packaging throughput forecasts and automotive collaborative robot deployment pipelines.
Sensitivities concentrate around Chinese rare earth export policy shifts, ISO 10218-1 validation timeline compression, and German automotive capital expenditure cycles. Forecasts reflect documented assumptions on technology substitution elasticities and carbon accounting rule adoption. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Asia Industry 4.0 Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
United States SCADA Market
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Latin America HMI Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Middle East and Africa Machine Control System Market
Industrial Automation
Rotary Vector (RV) Reducer Market
Industrial Automation
Predictive Maintenance Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Digital Industrial Scales Market