
 Latin America Process Automation Market | 2026-2036
Latin America Process Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Process Automation Market Foresight
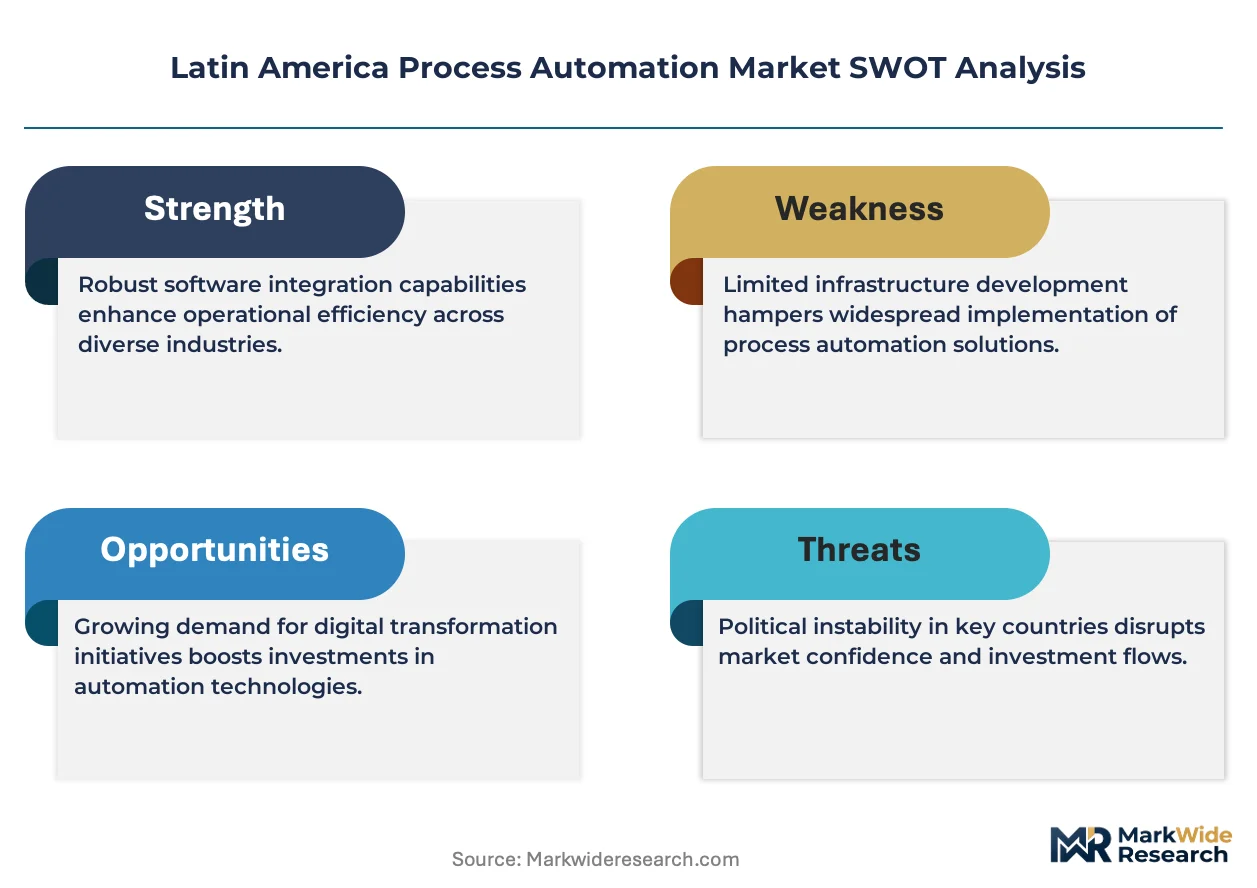
Brazil's ANP environmental compliance mandates for offshore leak detection and flaring reduction is consolidating procurement priorities across Latin American oil and gas automation buyers. ABB Ltd anchors its regional position through deep vertical integration into subsea control systems for Brazil's pre-salt fields. Schneider Electric leverages its local manufacturing footprint in Mexico to sustain competitive positioning in petrochemical DCS deployments. Emerson Electric Co. differentiates through proprietary DeltaV distributed control architectures tailored to Latin American refinery upgrade cycles.
Latin America process automation encompasses programmable logic controllers, distributed control systems, supervisory control and data acquisition platforms, and human-machine interfaces engineered to monitor, control, and optimize continuous and batch industrial processes with millisecond response tolerances and SIL-rated safety integrity. Its primary commercial purpose centers on reducing unplanned downtime, enforcing process uniformity, and enabling predictive intervention across capital-intensive extraction and processing operations. DCS architectures command the largest installed base in oil and gas and chemicals verticals where continuous process control demands centralized loop management. Edge deployment configurations represent the fastest-expanding segment as Brazilian and Mexican operators push analytics closer to wellhead and pipeline assets to compress latency for safety-critical decisions.
Brazil's ANP, Mexico's ASEA, and Colombia's ANH collectively enforce process safety, emissions monitoring, and operational reporting standards that mandate certified automation architectures for hydrocarbon extraction licenses. These regulators require SIL-compliant control systems, encrypted telemetry protocols, and auditable alarm management that elevate vendor qualification barriers and extend replacement cycles. Stakeholders must weigh cloud-hybrid migration paths against ANP-mandated air-gapped safety system requirements when architecting next-generation platform investments.
Market Dynamics
ANP-mandated SIL-compliant architectures for Brazil's pre-salt basin operations are forcing automation vendors to reconfigure product roadmaps around encrypted telemetry and air-gapped safety systems, compressing deployment timelines while elevating qualification barriers for offshore hydrocarbon licenses.
Growth Catalysts
- ANP Leak Detection Mandates:Brazil's environmental regulator requires real-time monitoring systems for offshore platforms, consolidating demand for integrated SCADA-DCS architectures in pre-salt extraction zones.
- Pre-salt Basin Retrofits:Petrobras-led automation upgrades across mature offshore assets are replacing legacy pneumatic controls with electronic distributed systems.
- Edge Analytics Deployment:Mexican pipeline operators are compressing decision latency by positioning predictive algorithms at wellhead assets, bypassing cloud-dependent architectures.
Market Restraints
- Import Duty Volatility:Brazil's ICMS tax regime and Argentina's foreign exchange controls create input cost unpredictability for PLC and HMI hardware sourced from Asian manufacturing clusters.
- Concentrated Component Supply:Specialized safety instrumented system processors depend on captive supply from German and Japanese semiconductor fabricators, exposing Latin American integrators to allocation risk.
- ASEA Certification Friction:Mexico's energy safety agency imposes extended validation timelines for SIL-rated control systems, delaying project commissioning by 8-14 months.
Strategic Opportunities
- Colombia Unconventional Assets:ANH licensing rounds for shale and tight gas formations in the Magdalena Valley remain underpenetrated by integrated automation vendors.
- Digital Twin Convergence:Brazilian operators are merging physics-based process simulation with live SCADA data streams to optimize pre-salt production chemistry.
- Cloud-Hybrid Architectures:ANP's 2023 guidance on encrypted telemetry for non-safety systems creates regulatory space for edge-to-cloud data pipelines in monitoring applications.
Industry Challenges
- OT Cybersecurity Skill Scarcity:Brazilian system integrators face acute shortages of engineers certified in IEC 62443 industrial security standards for offshore platform networks.
- Pneumatic-to-Electronic Migration:Legacy instrument air infrastructure at Mexican refineries requires complete replacement alongside control system upgrades, doubling capex intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Process Automation Market |
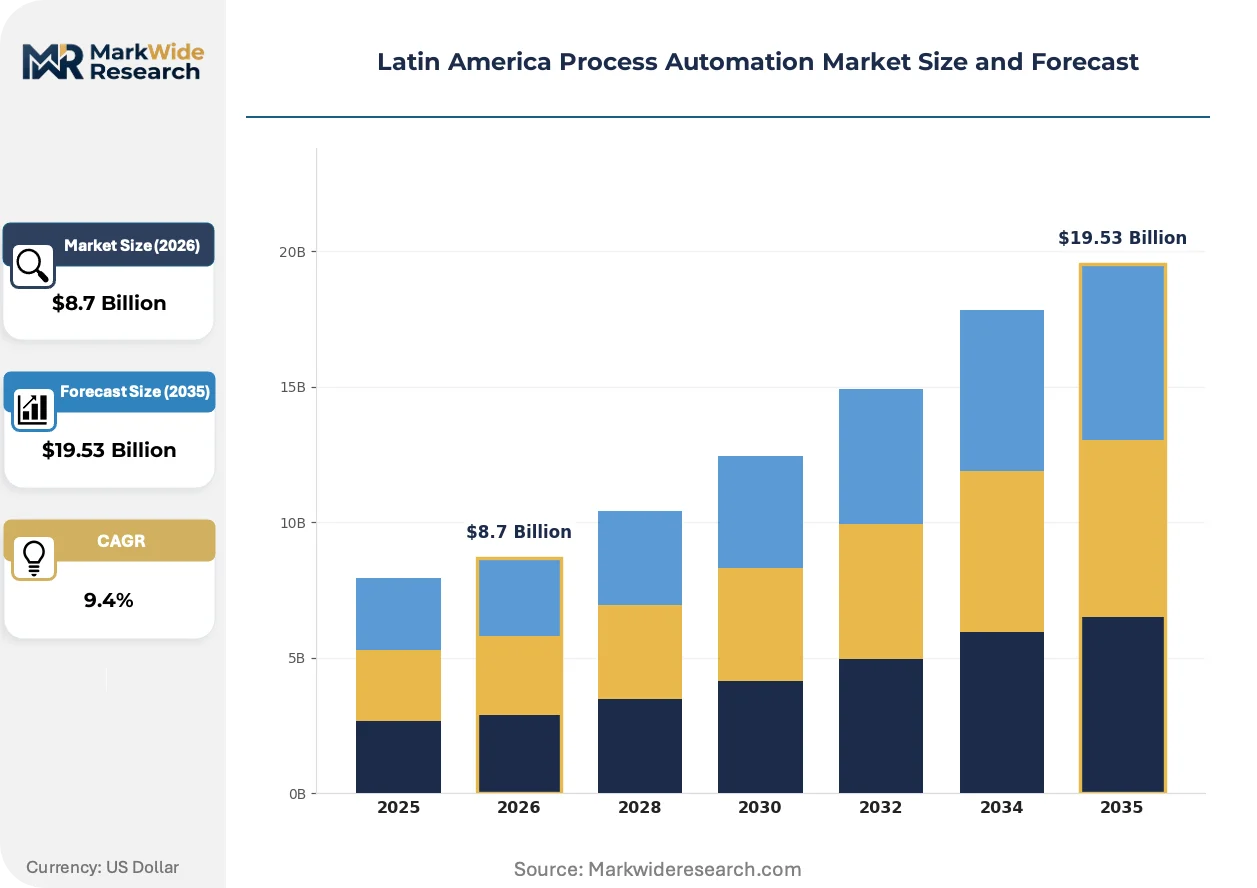
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLC, DCS, SCADA, HMI Industry Vertical: Manufacturing, Oil & Gas, Chemicals, Pharmaceuticals End User: OEMs, System Integrators, Service Providers, Enterprises Deployment: On-Premise, Cloud, Hybrid, Edge |
| Companies Covered | Rockwell Automation, Schneider Electric, ABB Ltd, General Electric Co., Eaton Corporation, Siemens AG, Emerson Electric Co., Mitsubishi Electric, Honeywell International Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Process Automation Market Shifts & Advancements
Edge-native control architectures are displacing centralized DCS topologies across Latin American hydrocarbon operations, compressing response times for safety-critical decisions while complicating regulatory compliance for air-gapped mandate jurisdictions.
Time-sensitive networking over standard Ethernet is expanding into upstream wellhead control applications, replacing proprietary fieldbus protocols. Brazilian pre-salt operators are deploying TSN-enabled remote terminal units to synchronize subsea valve actuation with surface processing. This convergence is expanding into brownfield retrofit specifications, forcing legacy DCS vendors to release gateway modules bridging deterministic Ethernet with existing I/O infrastructures.
ASEA's 2024 technical guidance on functional safety management systems mandates documented alarm rationalization for all new hydrocarbon processing licenses in Mexico. Industrial consequence includes compulsory third-party verification of safety instrumented function designs before operational approval. The refining and petrochemical vertical is most affected, with Pemex contractors accelerating procurement of certified alarm management software to meet commissioning deadlines.
Service unbundling is fragmenting historical DCS vendor relationships across Latin American maintenance contracts. Argentine shale operators are separating hardware provision from lifecycle support, engaging regional system integrators for field service while sourcing controllers through independent distributors. This pattern is most visible in Neuquén basin Vaca Muerta developments, where procurement teams prioritize localized spare parts availability over single-source accountability.
Latin America Process Automation Market Segmentation
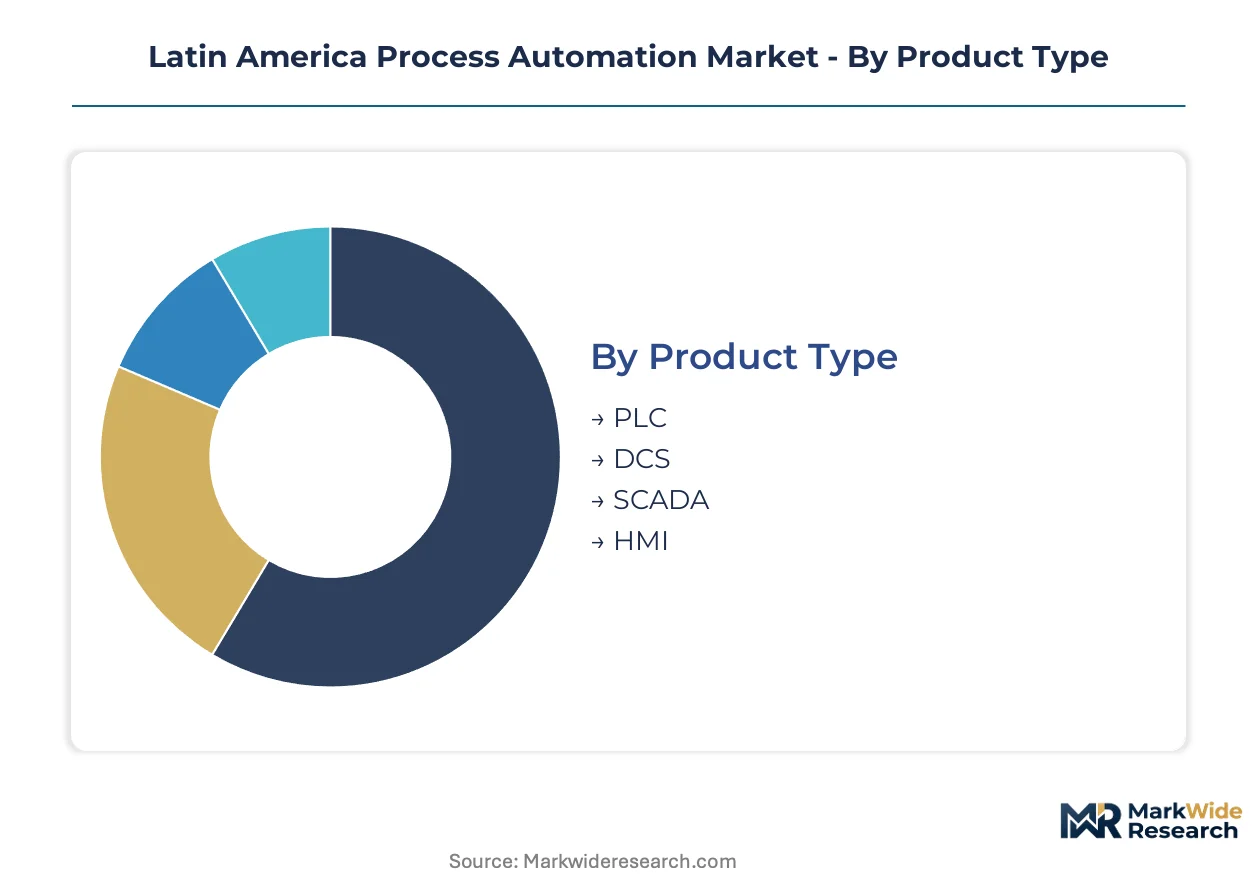
Segmentation in Latin American process automation reveals how capital deployment priorities diverge across control architectures, with regulatory mandates and offshore project economics dictating which technologies command procurement budgets. Understanding these splits clarifies where vendors must anchor certification investments versus where localized integration capabilities win.
Product Type:
Capital intensity varies sharply across control platforms, with subsea-rated distributed systems demanding engineering investment multiples above standard programmable controllers.
- DCS:Centralized loop management architectures engineered for continuous process control with SIL-rated safety integrity. Brazilian pre-salt operators specify these for platform topside processing, driven by ANP-mandated air-gapped safety system requirements that exclude lower-tier alternatives.
- SCADA:Telemetry-centric supervision platforms aggregating remote terminal unit data across geographically dispersed assets. Mexican pipeline operators are consolidating procurement around encrypted protocols for ASEA compliance, compressing vendor qualification timelines.
- PLC:Discrete logic controllers deployed for batch operations and auxiliary equipment sequencing.
- HMI:Operator interface terminals enabling process visualization and alarm management.
DCS absorbs the bulk of installed capacity in hydrocarbon extraction; edge-native control architectures are expanding most quickly.
Industry Vertical:
Application severity determines automation specification tiers, with explosive atmospheres and toxic release risks mandating certified architectures unavailable to lighter manufacturing loads.
- Oil & Gas:Upstream, midstream, and downstream hydrocarbon operations requiring SIL-compliant emergency shutdown systems and leak detection instrumentation. Brazil's pre-salt basin retrofits and Mexico's pipeline expansions concentrate demand for integrated DCS-SCADA architectures with encrypted telemetry.
- Chemicals:Continuous and batch processing operations with hazardous material handling protocols. Colombian petrochemical complexes are modernizing legacy pneumatic controls, creating procurement windows for vendors with local service presence.
- Manufacturing:Discrete assembly and process industries with standard automation requirements.
- Pharmaceuticals:Batch control applications with GMP documentation and electronic record-keeping obligations.
Oil and gas commands the dominant share of premium system deployments; chemicals is climbing the fastest as regional petrochemical capacity expands.
End User:
Procurement authority patterns split between asset owners specifying architectures and intermediaries executing integration, with regulatory liability driving direct enterprise engagement for safety-critical systems.
- Enterprises:Asset-owning operators including Petrobras, Pemex, and regional independents who retain final specification authority for licensed extraction and processing facilities. These entities increasingly unbundle hardware procurement from lifecycle support, fragmenting traditional vendor relationships.
- System Integrators:Regional engineering firms executing brownfield retrofits and commissioning validation. Brazilian integrators face acute IEC 62443 certification shortages, constraining project execution capacity for offshore cybersecurity mandates.
- OEMs:Original equipment manufacturers embedding control systems into packaged process skids.
- Service Providers:Maintenance and spare parts distributors competing on localized inventory availability.
Enterprises dominate specification authority for licensed facilities; system integrators are gaining share fastest as brownfield retrofit volumes rise.
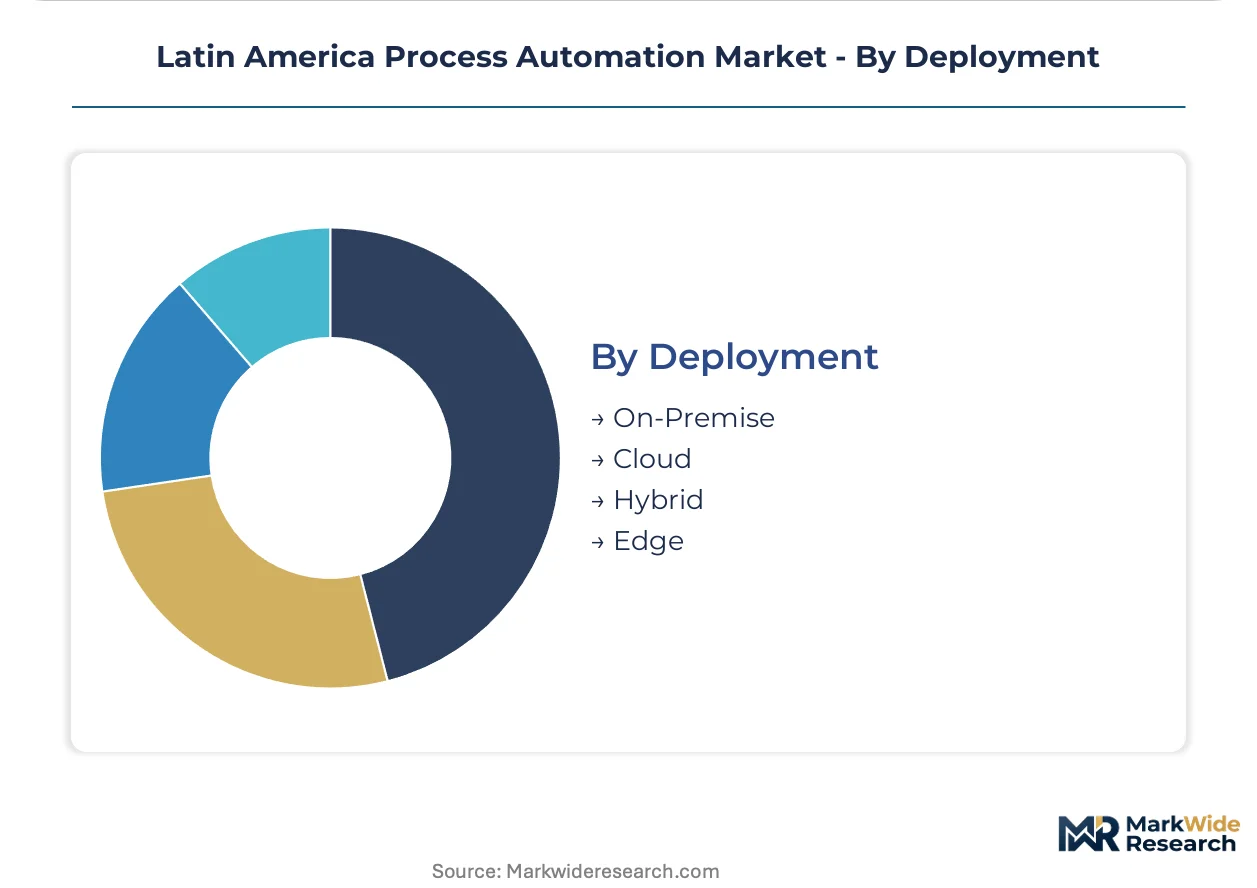
Deployment:
Infrastructure location choices reflect tension between latency compression for safety decisions and regulatory constraints on external connectivity for critical control layers.
- Edge:Distributed compute nodes positioning analytics and control logic at wellhead and pipeline assets. Mexican operators are deploying these configurations to bypass cloud-dependent architectures, compressing response times for leak detection and emergency isolation.
- Hybrid:Architectures partitioning safety-critical loops in air-gapped on-premise systems while routing monitoring data through encrypted cloud pipelines. ANP's guidance on non-safety telemetry creates regulatory space for this model in Brazilian offshore applications.
- On-Premise:Fully isolated control networks mandated for SIL-rated safety instrumented functions.
- Cloud:Centralized data aggregation for non-critical monitoring and optimization applications.
On-premise retains the largest installed base for safety loops; edge deployment is gaining share fastest as operators push analytics closer to field assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rio de Janeiro anchors Latin American process automation demand through Petrobras headquarters and the pre-salt basin engineering ecosystem. The city concentrates specification authority for Brazil's offshore retrofits. Mexican pipeline corridors and Colombian petrochemical clusters complete the regional demand map.
Brazil
Petrobras-led pre-salt retrofits and ANP leak detection mandates drive DCS-SCADA procurement. ANP Resolution 46/2016 mandates real-time monitoring for offshore platforms. Macaé's subsea engineering cluster hosts integrators executing SIL-compliant safety system upgrades.
Mexico
Pemex refinery modernization and Cenagas pipeline expansion compress procurement timelines for encrypted telemetry systems. ASEA's 2024 functional safety guidance extends validation cycles for new licenses. Tula refinery complex in Hidalgo state represents the largest brownfield automation retrofit currently underway.
Colombia
ANH licensing rounds for Magdalena Valley unconventional assets attract first-mover automation vendors. The national hydrocarbon regulator requires certified control architectures for shale extraction permits. Barrancabermeja refining cluster is modernizing legacy pneumatic infrastructure with electronic distributed systems.
Argentina
Vaca Muerta shale operators unbundle hardware procurement from lifecycle support to bypass currency volatility. The federal energy secretariat's local content requirements favor regional system integrators over direct vendor relationships. Neuquén basin drilling activity concentrates demand for wellhead control systems.
Chile
Mining sector electrification and desalination plant automation diversify demand beyond hydrocarbons. The Ministry of Mining's decarbonization roadmap mandates energy management systems for copper concentrators. Antofagasta mineral processing corridor is deploying edge analytics for predictive maintenance.
Latin America Process Automation Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive energy verticals. European and North American multinationals command specification authority at national oil companies. Two archetypes dominate: integrated automation platforms bundling DCS-SCADA-HMI stacks, and specialized safety system vendors with SIL certification depth. Geographic expansion through local manufacturing and strategic partnerships with regional integrators constitute the primary competitive moves.
Among diversified European-based automation conglomerates, ABB Ltd and Schneider Electric exemplify platform breadth. ABB Ltd anchors the subsea control system tier through deep engagement with Brazilian pre-salt engineering specifications. Schneider Electric occupies a position in Mexican petrochemical DCS deployments through its local manufacturing footprint. Emerson Electric Co. represents the North American specialist archetype with proprietary distributed control architectures.
| Leading Market Players |
|---|
| Rockwell Automation |
| Schneider Electric |
| ABB Ltd |
| General Electric Co. |
| Eaton Corporation |
| Siemens AG |
| Emerson Electric Co. |
| Mitsubishi Electric |
| Honeywell International Inc. |
| Others |
Supply & Pricing Matrix
ANP-mandated leak detection and flaring reduction standards gate access to both qualified safety-certified supply and premium-tier pricing for offshore Brazilian automation deployments. Vendors lacking SIL-compliant architectures and encrypted telemetry capabilities face exclusion from pre-salt basin procurement, compressing the qualified supplier base and anchoring price premiums to certification depth rather than hardware cost alone.
Pricing Analysis
Uptime-guarantee contracts tied to production throughput anchor pricing for DCS-SCADA bundles in Brazilian offshore applications. Pricing stratifies across SIL-4 certified safety systems, SIL-2 compliant process controls, and non-certified monitoring tiers, with certification grade and local service presence as primary differentiation drivers. Cost compression in standard PLC tiers intensifies as Argentine shale operators unbundle hardware from support contracts. National oil companies show lowest price sensitivity for safety-critical systems; regional system integrators face acute margin pressure in commoditized HMI segments.
Supply Chain Analysis
Specialized firmware engineering talent shortages in German and Japanese semiconductor clusters constrain output of safety-rated processors for Latin American DCS deployments. Manufacturing concentrates in Germany, Japan, and South Korea for SIL-certified control hardware; Mexico and Brazil host final assembly and localization for non-safety tiers. Supply chains draw from captive silicon foundries for safety instrumented system chips, analog sensors, and subsea-rated actuators. Single-source vulnerability runs through Japanese safety processor fabricators. Distribution runs through authorized regional integrators with ANP or ASEA certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American process automation is consolidating around vendors with regulatory certification depth and localized engineering presence, with ANP and ASEA compliance timelines forcing acquisition of qualified integrators by undercertified competitors.
For Market Incumbents: Deploy certification leverage as the primary defensive mechanism. Deepen in-house production of subsea-rated control hardware to offset German and Japanese semiconductor allocation risk. Acquire Brazilian system integrators with IEC 62443 cybersecurity credentials to capture Petrobras retrofit demand before ASEA-mandated validation timelines extend further. For New Entrants and Emerging Players: Cloud-native SCADA platforms with edge-deployment capabilities represent the most penetrable entry vector. Target Colombian Magdalena Valley unconventional assets where ANH licensing rounds have attracted limited integrated automation vendor presence. Partner with Neuquén basin regional integrators to bypass Vaca Muerta procurement unbundling trends. For Investors and Strategic Acquirers: ASEA's extension of SIL-rated system validation timelines is the leading indicator that Mexican refinery automation retrofit schedules will compress vendor liquidity and create distressed acquisition opportunities. Five-to-ten-year viability favors vertically integrated platforms with captive safety system semiconductor supply. Watch for Pemex contractor payment delays as the inflection signal for integrator distress.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Depth Expansion | ANP and ASEA compliance mandates elevate SIL-rated system vendors above commodity competitors in offshore licensing. |
| Regional Integrator Acquisition | Brazilian IEC 62443-certified engineering firms command scarcity premiums as cybersecurity mandates tighten. |
| Edge-Native Architecture Development | Mexican pipeline operators prioritize latency compression over cloud-dependent SCADA for leak detection. |
| Subsea Hardware Localization | Macaé engineering cluster proximity reduces Petrobras procurement friction for pre-salt retrofits. |
| Alarm Rationalization Software Partnership | ASEA's 2024 functional safety guidance accelerates third-party verification demand for Mexican refineries. |
Research Methodology
Independent corroboration across primary interviews with Petrobras automation engineers, Pemex procurement leads, ANP regulatory affairs officers, and Colombian system integrators underwrites the qualitative findings. Secondary validation drew from ANP Resolution 46/2016 filings, ASEA technical guidance documents, SEC 10-K automation segment disclosures, and Brazilian customs import data for control system hardware. Bottom-up project pipeline enumeration triangulates against top-down hydrocarbon extraction licensing forecasts.
Comparable-period anchoring to pre-salt basin investment cycles and Pemex refinery modernization schedules structured the projection horizon. The analytical framework models deployment across product type, industry vertical, and infrastructure location dimensions. CAGRs derive from segment-level capital expenditure trajectories and replacement cycle analysis. Forecast inputs include ANH licensing round schedules and Argentine federal energy secretariat local content requirement evolution.
The model holds under stable regulatory enforcement intensity and semiconductor allocation continuity; deviation in ANP mandate acceleration or Japanese foundry capacity constraints would shift vendor competitive positioning. A small set of named triggers—ASEA validation timeline extensions, Petrobras divestiture pace, and ICMS tax regime volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
United Kingdom Factory Automation and Industrial Control Systems Market
Industrial Automation
Geosteering Technology Market
Industrial Automation
Linear Motion System Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Middle East and Africa Automated Storage and Retrieval System Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Global System Integrator for Industrial Automation Market
Industrial Automation
Warehouse Automation Equipment Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
GMC Based Motion Controller Market