
 North America Agricultural Tractors Market | 2026-2036
North America Agricultural Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Agricultural Tractors Market Analytics
EPA Tier 4 Final compliance is shifting the cost-of-entry calculus for tractor OEMs, forcing investments in after-treatment systems and engine recalibration. Deere & Company leverages its captive engine manufacturing to absorb regulatory costs internally. CNH Industrial anchors its North American position through dual-brand distribution across Case IH and New Holland Agriculture. AGCO Corporation differentiates via precision-ag integration across its Fendt and Massey Ferguson lineups.
Agricultural tractors are self-propelled power units exceeding 20 engine horsepower, designed to pull or power implements for soil preparation, planting, cultivation, and harvest operations; modern units integrate hydrostatic transmissions, power-take-off shafts rated to 540 or 1000 RPM, and three-point hitch systems for implement attachment. Diesel fuel type still dominates installed fleets across North America, though electric and hybrid architectures are gaining trial deployment in orchard and vineyard specialty tractors where duty cycles favor battery sizing. Large tractors lead value generation due to precision-farming payload requirements, while specialty tractors command margin premiums in confined-space applications.
EPA, CARB, and Environment and Climate Change Canada collectively shape emissions certification pathways and zero-emission equipment incentives across the North American trading bloc. Tier 4 Final enforcement tightens particulate matter and NOx thresholds, compressing development timelines for powertrain engineers. Stakeholders must monitor electrification subsidy durability and charging infrastructure buildout in rural counties to assess platform transition economics.
Market Dynamics
Farm consolidation across the US Corn Belt and Canadian Prairie provinces is concentrating purchasing power among fewer, larger operators who demand higher-horsepower tractors with integrated precision-agriculture capabilities. This structural concentration is compressing equipment replacement cycles and elevating technical requirements for OEM engineering teams.
Growth Catalysts
- EPA Tier 4 Final compliance deadlines:Regulatory enforcement is accelerating fleet turnover as operators retire pre-compliant equipment rather than retrofit aging diesel powertrains. The US Environmental Protection Agency's particulate matter thresholds are pulling forward replacement demand.
- Autonomous guidance systems:GPS-based auto-steering and implement control are reducing operator fatigue and enabling 24-hour planting windows. Large-scale row-crop operations in Illinois and Iowa are standardizing these capabilities across new acquisitions.
- Canadian grain belt expansion:Saskatchewan and Manitoba operators are scaling planted acreage, creating sustained demand for articulated four-wheel-drive tractors above 400 horsepower.
Market Restraints
- Diesel after-treatment cost inflation:Selective catalytic reduction and diesel particulate filter systems have added substantial material cost to Tier 4 Final-compliant engines. The price burden falls heaviest on mid-horsepower utility tractors where margins are thinnest.
- Steel and semiconductor input volatility:Hydraulic component foundries and engine control module suppliers face intermittent allocation constraints. Tier-2 powertrain suppliers in the US Midwest report order backlogs extending six to nine months.
- Electric platform range limitations:Battery energy density constraints currently restrict electrified tractors to sub-100-horsepower specialty applications. Orchard and vineyard operators in California's Central Valley represent the practical ceiling for pure-electric deployment.
Strategic Opportunities
- US Inflation Reduction Act equipment incentives:Tax credits for zero-emission agricultural machinery are improving total-cost-of-ownership calculations for electric tractor trials. USDA Rural Energy for America Program grants are covering charging infrastructure buildout.
- Autonomous implement coordination:Machine-to-machine communication protocols are enabling synchronized tillage and planting operations without human intervention. Technology convergence between tractor guidance and implement control is creating new system-level value pools.
- Precision-ag subscription services:Data-driven agronomy platforms bundled with equipment financing are generating recurring revenue streams. Dealership networks in Nebraska and Kansas are piloting outcome-based service models tied to yield-per-acre guarantees.
Industry Challenges
- Powertrain software integration complexity:Tier 4 Final engine calibrations must synchronize with transmission controllers and hydraulic management systems. Validation timelines for integrated powertrain releases have extended by eight to twelve months.
- Certification timeline compression:California Air Resources Board zero-emission equipment mandates are demanding parallel development tracks for diesel and electric architectures. Engineering teams face resource allocation trade-offs between compliance pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Agricultural Tractors Market |
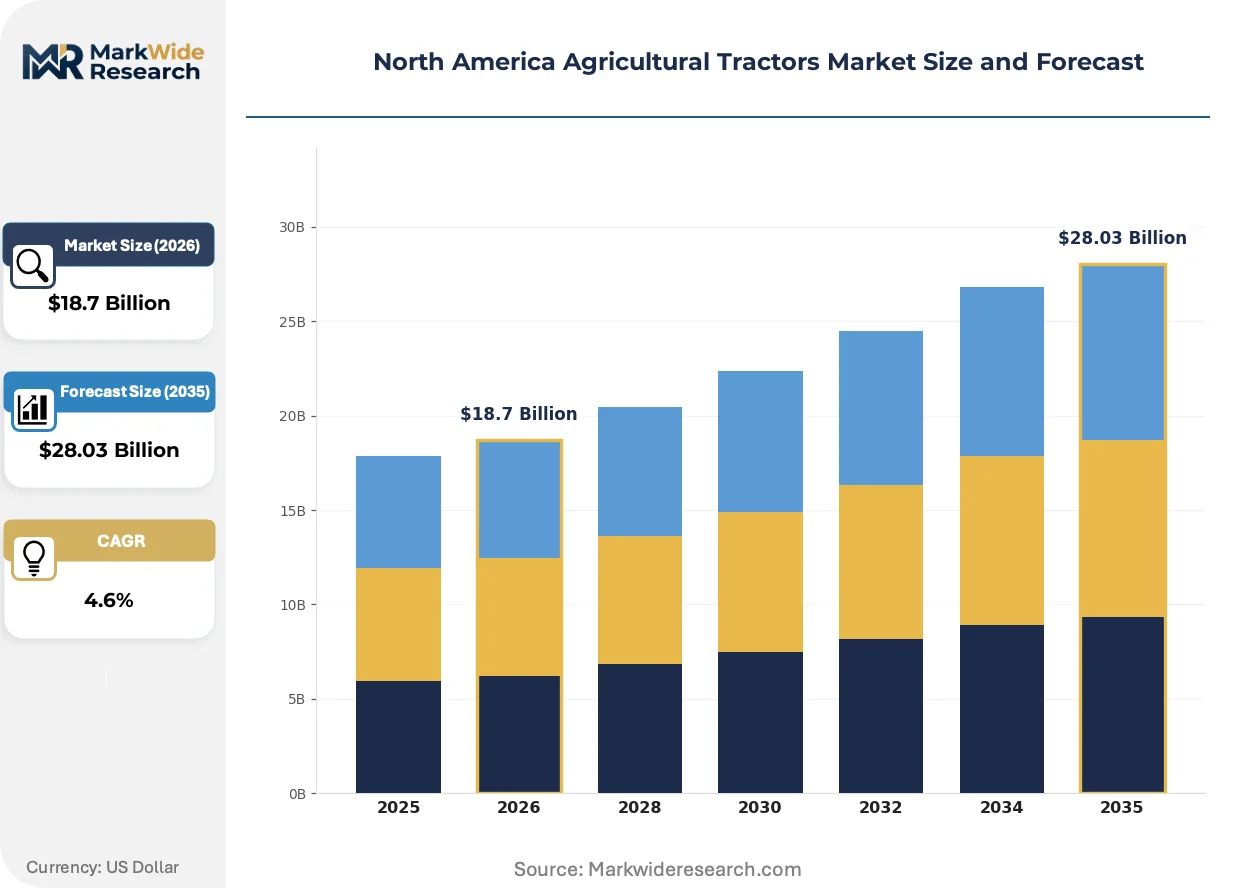
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Tractors, Medium Tractors, Large Tractors, Specialty Tractors Fuel Type: Diesel, Gasoline, Electric, Hybrid Technology: GPS, Automation, Telemetry, Engine Management End User: Farmers, Agricultural Contractors, Cooperative Societies, Government |
| Companies Covered | Kubota Corporation, SDF Group, Deere & Company, Case IH, Massey Ferguson, CNH Industrial, CLAAS Group, New Holland Agriculture, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Agricultural Tractors Market Evolving Landscape
Electrification and autonomous operation are converging to redefine tractor architecture, with implications for powertrain design, dealer service capability, and operator skill requirements across North American farm operations.
Autonomous tractor platforms equipped with LiDAR, radar, and camera arrays are automating field preparation and planting sequences without cab occupancy. Large-scale corn and soybean operators in Indiana and Ohio are deploying these systems for overnight operations during compressed planting windows. The technology is automating labor scheduling and reducing per-acre machinery cost through extended daily utilization rates.
California Air Resources Board's Advanced Clean Trucks regulation is creating compliance templates for off-road equipment categories, with tractor OEMs monitoring precedent for future agricultural equipment mandates. The policy is forcing dual-track engineering investments in both diesel after-treatment optimization and battery-electric platform development. Specialty crop producers in California's Central Valley are becoming early testbeds for zero-emission tractor trials due to localized air quality enforcement.
Equipment-as-a-service contracting is displacing traditional loan-and-lease financing for tractors above 200 horsepower. Dealer groups in Iowa and Illinois are bundling maintenance, telemetry, and agronomic advisory into multi-year operating agreements. The shift is most visible among corn belt operators who prioritize predictable cash flows over asset ownership during commodity price volatility cycles.
North America Agricultural Tractors Market Segmentation
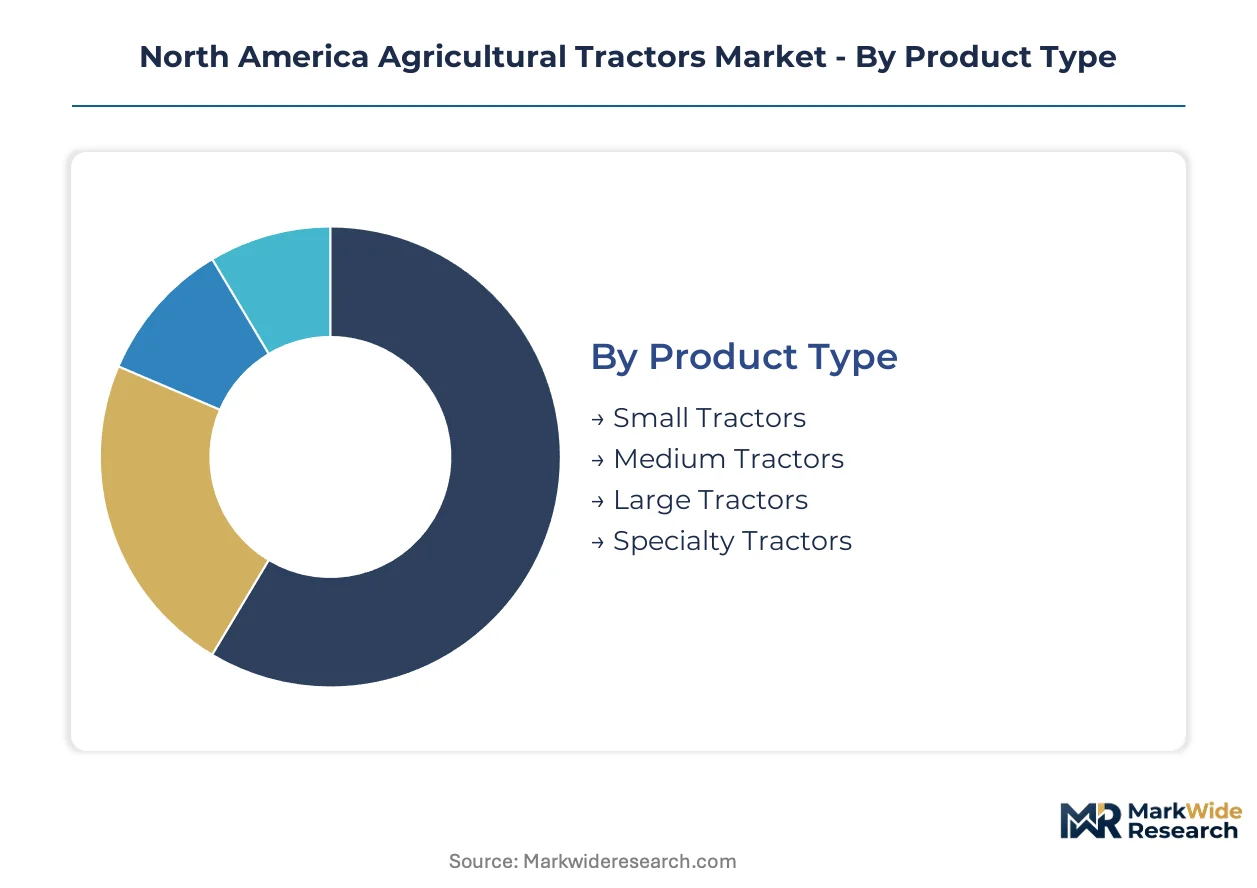
Tractor segmentation in North America reflects divergent operational economics across farm scale and crop type. Equipment specification directly determines capital deployment patterns and aftermarket service intensity for OEMs and dealer networks.
Product Type:
Horsepower rating and chassis architecture separate equipment classes with distinct margin profiles and replacement cycles.
- Large Tractors:Articulated four-wheel-drive units exceeding 300 horsepower dominate acreage coverage in Illinois and Iowa row-crop operations. Fleet standardization among consolidated operators compresses replacement cycles as precision-ag payload requirements escalate.
- Specialty Tractors:Narrow-profile and low-clearance configurations serve California Central Valley orchards and vineyards where confined-space maneuverability commands premium pricing. Battery-electric trials concentrate here due to predictable duty cycles and localized air quality enforcement.
- Medium Tractors:Utility-class units between 75-200 horsepower serve mixed livestock-grain operations across Nebraska and Kansas with versatile three-point hitch compatibility.
- Small Tractors:Sub-75 horsepower machines address hobby farms and municipal maintenance contracts where capital constraints limit specification.
Large tractors lead on scale; specialty tractors lead on momentum.
Fuel Type:
Powertrain selection reflects regulatory pressure, energy infrastructure, and total-cost-of-ownership calculus across operating environments.
- Diesel:Compression-ignition architectures power virtually all high-horsepower field equipment, though EPA Tier 4 Final after-treatment systems have inflated engine costs and extended service intervals. The fuel type retains installed-base dominance across the US Corn Belt and Canadian Prairie provinces.
- Electric:Battery-electric platforms are gaining trial deployment in sub-100-horsepower specialty applications where overnight charging infrastructure and predictable daily duty cycles align with range constraints. California CARB incentives and USDA Rural Energy for America Program grants are accelerating pilot programs.
- Hybrid:Parallel-electric architectures remain developmental, targeting mid-horsepower utility segments where diesel range requirements persist but emissions reduction pressures intensify.
- Gasoline:Spark-ignition engines persist in entry-level compact tractors and lawn-garden crossover equipment where purchase price sensitivity outweighs fuel efficiency considerations.
Diesel retains volume leadership; electric platforms are climbing the fastest.
Technology:
Embedded systems and connectivity layers are redefining equipment value propositions and dealer service models.
- GPS:Satellite-based guidance systems enabling sub-inch pass-to-pass accuracy have become standard specification in Minnesota and North Dakota large-tractor acquisitions. Auto-steering reduces operator fatigue and extends daily productive hours during compressed planting windows.
- Telemetry:Machine-to-cloud data transmission supports predictive maintenance scheduling and fleet utilization optimization. Dealer groups in Iowa and Illinois are bundling telemetry subscriptions into equipment-as-a-service contracts.
- Automation:LiDAR and camera-array systems are enabling cab-free operation for tillage and planting sequences in Indiana and Ohio overnight deployments.
- Engine Management:Electronic control modules calibrate fuel injection and after-treatment regeneration cycles to maintain Tier 4 Final compliance across variable load profiles.
GPS leads on penetration depth; automation leads on expansion trajectory.
End User:
Purchasing authority and capital access determine specification authority and financing structure preferences.
- Farmers:Owner-operators across the US Corn Belt and Canadian grain belts concentrate demand for high-horsepower precision-ag equipment. Consolidation trends are elevating technical requirements and compressing replacement cycles among surviving operators.
- Agricultural Contractors:Custom service providers in Saskatchewan and Manitoba deploy articulated four-wheel-drive fleets to capture acreage expansion economics without land ownership exposure.
- Cooperative Societies:Member-owned purchasing consortia aggregate demand across smaller operators in Wisconsin and Michigan dairy regions, standardizing mid-horsepower utility specifications.
- Government:Federal and state agencies acquire specialized mowing and maintenance equipment for highway corridors and public lands management.
Farmers lead on absolute volume; agricultural contractors lead on fleet turnover velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled powertrain engineers and precision-agriculture software developers concentrate in the US Midwest and Canadian Prairie provinces, anchoring North American tractor innovation clusters.
United States
Consolidated row-crop operators in Illinois and Iowa drive demand for articulated four-wheel-drive tractors exceeding 400 horsepower. EPA Tier 4 Final enforcement accelerates fleet turnover across the Corn Belt. Deere & Company's engineering headquarters in Moline, Illinois anchors captive engine manufacturing and integrated precision-ag development.
Canada
Saskatchewan and Manitoba grain belt expansion sustains demand for high-horsepower field equipment among agricultural contractors. Environment and Climate Change Canada aligns emissions certification with EPA pathways, streamlining cross-border equipment flows. Winnipeg serves as a distribution hub for Prairie province fleet deployments.
Mexico
Commercial vegetable and fruit operations in Sinaloa and Baja California generate demand for mid-horsepower utility tractors. Mexican agricultural modernization programs support mechanization upgrades among medium-scale producers. Querétaro's manufacturing corridor hosts powertrain component suppliers serving North American assembly plants.
North America Agricultural Tractors Market Competitive Landscape
The competitive structure tilts toward diversified machinery conglomerates with captive engine manufacturing and precision-agriculture integration capabilities. Tier 1 suppliers control high-horsepower segments through integrated technology stacks, while specialty equipment specialists capture margin premiums in confined-space applications. Two dominant competitive moves define current positioning: strategic consolidation of precision-agriculture software assets, and backward integration into powertrain component manufacturing to absorb regulatory cost inflation.
Among diversified agricultural machinery conglomerates, Deere & Company, CNH Industrial, and AGCO Corporation exemplify distinct strategic archetypes. Deere & Company anchors the premium-tier vector through captive engine production and precision-agriculture platform control. CNH Industrial occupies a dual-brand position spanning Case IH and New Holland Agriculture distribution networks. AGCO Corporation sits within the technology-forward tier, integrating precision-farming capabilities across Fendt and Massey Ferguson lineups.
| Leading Market Players |
|---|
| Kubota Corporation |
| SDF Group |
| Deere & Company |
| Case IH |
| Massey Ferguson |
| CNH Industrial |
| CLAAS Group |
| New Holland Agriculture |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final compliance gates qualified supply and premium-tier pricing access for North American tractor OEMs, forcing investments in after-treatment engineering that compress margins on mid-horsepower utility segments while elevating cost barriers for non-compliant competitors.
Pricing Analysis
Equipment-as-a-service bundling splits the market between unbundled transactional sales and subscription-based contracts with telemetry and maintenance included. Three-tier pricing structure across premium, standard, and economy levels reflects horsepower rating, precision-ag integration depth, and after-sales service commitment. Pricing pressure stems from diesel after-treatment cost inflation that squeezes mid-range utility tractors where buyer price sensitivity peaks. Large-scale row-crop operators in Illinois and Iowa show least price sensitivity, prioritizing uptime guarantees over capital outlay.
Supply Chain Analysis
Skilled powertrain engineers and precision-agriculture software developers concentrate in the US Midwest, with hydraulic component foundries and engine control module suppliers anchored in Michigan and Ohio. Steel and semiconductor inputs draw from US, Mexican, and Canadian manufacturing corridors. Single-source vulnerability in Tier-2 powertrain suppliers creates six-to-nine-month order backlogs during allocation constraints. Distribution runs through manufacturer-owned dealer networks with captive parts and service operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Agricultural Tractors Market functions as a stable compounder, with farm consolidation across the Corn Belt driving steady replacement demand and precision-ag payload upgrades.
For Market Incumbents: Hedge regulatory cost inflation through backward integration into engine manufacturing and after-treatment systems, mirroring Deere & Company's captive production model. Anchor precision-ag software platforms to equipment financing, creating switching costs that defend against emerging electric-tractor entrants targeting California specialty crop segments. For New Entrants and Emerging Players: Enter via California Central Valley orchard and vineyard operators, where CARB zero-emission mandates and predictable duty cycles create the most penetrable beachhead for battery-electric platforms below 100 horsepower. Partner with USDA Rural Energy for America Program grant administrators to subsidize charging infrastructure buildout and compress customer acquisition costs. For Investors and Strategic Acquirers: Roll-up economics work for precision-agriculture software specialists because farm data monetization capabilities remain fragmented across regional dealer networks and independent agronomy platforms. Target mid-cap telemetry and autonomous guidance developers with proven machine-to-machine protocols. Watch EPA electrification subsidy durability and rural county charging infrastructure buildout rates as inflection indicators for platform transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powertrain Manufacturing | Captive engine production absorbs EPA Tier 4 Final compliance costs and protects margin structure. |
| Precision-Agriculture Platform Acquisition | Telemetry and agronomic data bundling creates recurring revenue streams beyond equipment sales. |
| Equipment-as-a-Service Contract Expansion | Multi-year operating agreements with yield guarantees reduce customer churn during commodity price cycles. |
| Autonomous Guidance System Development | LiDAR and camera-array integration enables overnight cab-free operation for compressed planting windows. |
| Battery-Electric Platform Pilot Programs | California CARB incentives and USDA grants accelerate zero-emission tractor trials in specialty crop applications. |
Research Methodology
Coverage spans the United States Corn Belt, Canadian Prairie provinces, and Mexican agricultural corridors, with primary inputs from each region combining interviews with OEM product planning directors, dealer network operators, large-scale farm owner-operators, and precision-agriculture software developers. Secondary validation draws from EPA certification databases, Environment and Climate Change Canada emissions filings, USDA equipment incentive disclosures, and SEC 10-K filings from listed machinery conglomerates. Bottom-up unit shipment modeling and top-down value aggregation triangulate market size estimates.
Granularity-level modeling extends to horsepower tier, fuel architecture, technology embedding depth, and end-user purchasing authority across state and provincial boundaries. CAGRs derive from replacement cycle analysis, fleet age distribution, and regulatory compliance deadline impacts throughout the projection horizon. Forecast inputs incorporate farm consolidation rates, electrification subsidy durability, and autonomous equipment adoption curves specific to row-crop operational economics.
Inputs from EPA and CARB regulatory filings were available through the study window; gaps in real-time dealer inventory data and proprietary OEM pricing introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions on subsidy program continuity and semiconductor supply normalization. Material deviation in EPA electrification incentive extension or Tier-5 emissions proposal timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Agricultural Haying and Forage Machinery Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
South America Agricultural Tractors Market
Agricultural Machinery
Agricultural Food Grade Rubber Conveyor Belt Market
Agricultural Machinery
Japan Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Vietnam Combine Harvester Market
Agricultural Machinery
Europe Agricultural Tractors Market
Agricultural Machinery
Utility Tractor Market
Agricultural Machinery
India Tractor Market