
 Vietnam Combine Harvester Market | 2026-2036
Vietnam Combine Harvester Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Combine Harvester Market Analytics
Agricultural equipment dealerships across the Mekong Delta are reshaping how combine harvesters reach end users, shifting from state-run distribution to private retail networks with service bundling. Kubota Corporation leverages its established Vietnamese assembly plant to anchor regional supply chains with localized spare parts availability. THACO competes through diversified commercial vehicle channels that extend into farm machinery financing. CLAAS KGaA mbH specializes in high-capacity threshing systems that dominate large-scale contract farming operations in An Giang and Dong Thap provinces.
A combine harvester is a self-propelled agricultural machine that integrates cutting, threshing, cleaning, and grain handling functions into a single operational unit, typically powered by diesel engines ranging from 50 to 400 horsepower depending on crop density and field conditions. Its primary commercial purpose is to reduce grain loss rates and labor dependency during intensive harvest windows for rice, corn, and wheat. Self-propelled units command the dominant share of value given their throughput efficiency on Vietnam's fragmented but intensifying paddy fields. Precision Agriculture technology is gaining traction fastest among agricultural cooperatives seeking yield-mapping capabilities for multi-year field optimization. Medium Power equipment occupies the core volume tier, balancing acquisition cost against the scale requirements of typical Vietnamese farm holdings.
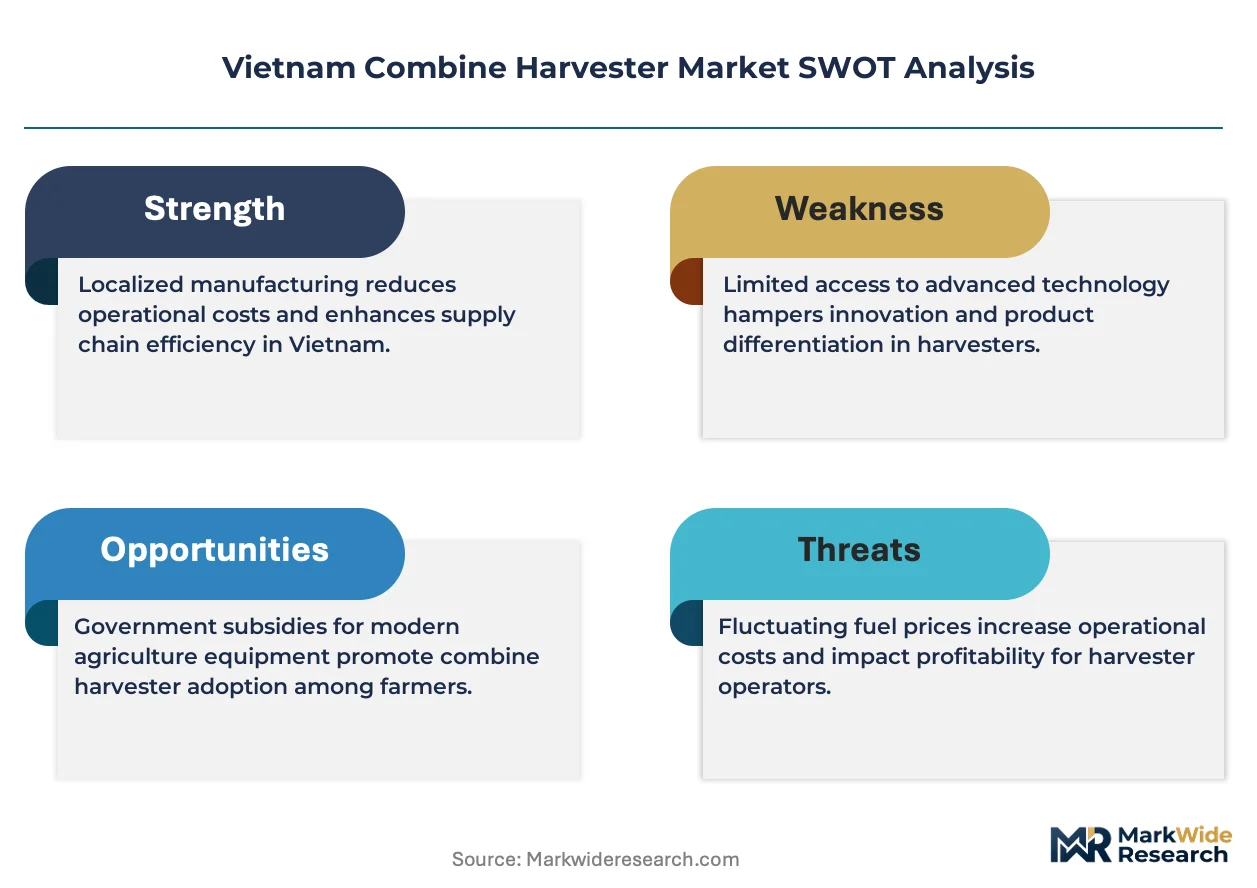
Vietnam's Ministry of Agriculture and Rural Development sets mechanization targets that directly influence subsidy eligibility and import tariff structures for harvesting equipment. The country's national standards body aligns product certification with safety and emissions benchmarks that filter which overseas manufacturers qualify for state-supported procurement programs. BIS-equivalent technical regulations on engine emissions and operator protection are tightening, compelling importers to adapt powertrain configurations for Vietnamese regulatory compliance. Stakeholders must monitor how subsidy disbursement timelines and local-content requirements evolve to determine whether to expand domestic assembly or deepen reliance on fully-imported platforms.
Market Dynamics
Vietnam's agricultural mechanization push is compressing the traditional harvest labor pool while subsidy disbursement timelines create procurement cyclicality that manufacturers must navigate.
Growth Catalysts
- Subsidy Eligibility Expansion:Vietnam's Ministry of Agriculture and Rural Development broadened equipment financing access for agricultural cooperatives, accelerating fleet renewal cycles in the Red River Delta.
- Rice Intensification Mandates:National food security targets require triple-cropping in Mekong Delta provinces, forcing harvest window compression that only mechanized threshing can satisfy.
- Diesel-Electric Hybrid Propulsion:Powertrain electrification prototypes are entering field trials, promising fuel cost reductions that reshape total cost of ownership calculations for commercial farming enterprises.
Market Restraints
- Import Tariff Volatility:Fully-assembled harvester platforms face fluctuating duty structures that disadvantage pure importers against local assemblers with domestic content certificates.
- Credit Access Fragmentation:Smallholder farms in peripheral provinces lack collateral for equipment loans, concentrating demand among larger commercial operators and limiting addressable market depth.
- Spare Parts Distribution Gaps:Mekong Delta service networks remain thin outside major provincial hubs, extending downtime risks that deter first-time mechanization adopters.
Strategic Opportunities
- Precision Agriculture Convergence:Yield-mapping sensors and GPS-guided steering are bundling with base equipment, creating upgrade revenue streams from cooperatives seeking multi-year field data.
- Contract Farming Expansion:An Giang and Dong Thap provinces are consolidating land under professional management, generating concentrated demand for high-capacity threshing configurations.
- Local Assembly Incentives:Domestic content thresholds for state procurement preference are tightening, rewarding manufacturers that expand Vietnamese component sourcing and fabrication.
Industry Challenges
- Certification Timeline Compression:BIS-equivalent emissions and safety standards are evolving faster than test facility capacity, delaying product launches and freezing inventory.
- Technical Operator Scarcity:Provincial vocational institutes produce insufficient certified mechanics for hydraulic and electronic diagnostic work, forcing manufacturers to fund proprietary training programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Combine Harvester Market |
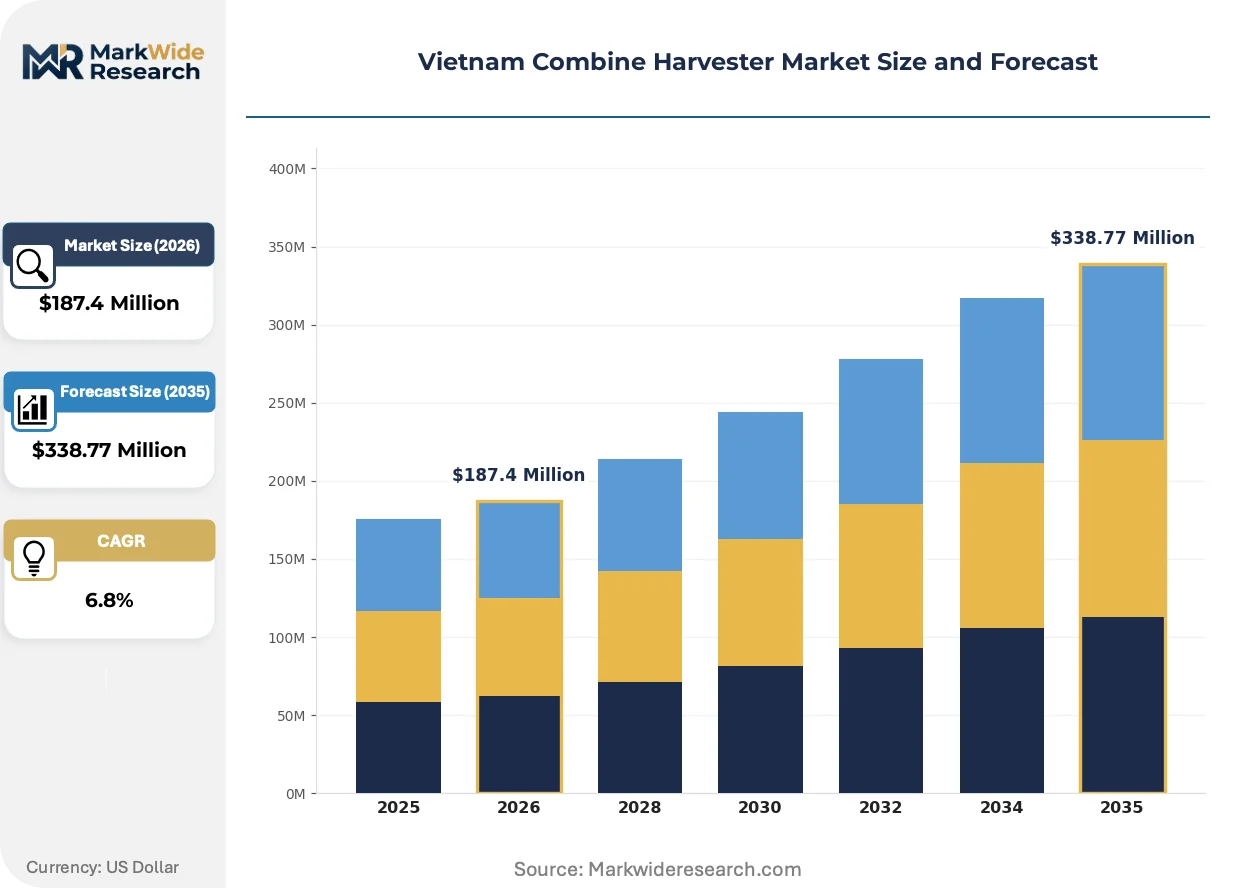
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Propelled, Tow-Behind, Modular, Hybrid End User: Farmers, Agricultural Cooperatives, Contract Farmers, Exporters Technology: Conventional, Precision Agriculture, Smart IoT, Autonomous Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Vietnam Engine and Agricultural Machinery Corporation, Iseki Corporation, Kubota Corporation, Tong Yang Moolsan Co Ltd, Truong Hai Auto Corporation (THACO), CLAAS KGaA mbH, CNH Industrial, ShanDong Huaxin Machinery Co Ltd, Yanmar America Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Combine Harvester Market Evolving Landscape
Automation and data capture technologies are redefining harvester value propositions beyond pure throughput metrics, while regulatory pressure on emissions and safety accelerates product refresh cycles.
Telematics-enabled predictive maintenance is collapsing the traditional reactive service model for Vietnamese fleet operators. Agricultural cooperatives in intensive rice provinces are piloting remote diagnostic subscriptions that flag hydraulic and engine anomalies before field failure. Equipment downtime compression is shifting purchasing criteria from initial acquisition cost toward lifecycle reliability guarantees.
Vietnam's national standards body is tightening BIS-equivalent technical regulations on diesel particulate emissions and operator protection structures. Importers must now recalibrate powertrain configurations and cabin designs for local regulatory compliance before qualifying for state subsidy programs. Medium-power equipment segments face the steepest adaptation costs given their price-sensitive buyer base.
Service bundling is displacing pure equipment transactions across Mekong Delta dealership networks. Private retailers now package financing, preventive maintenance, and spare parts availability into multi-year contracts that lock in customer relationships. Dong Thap and An Giang provinces exhibit the fastest channel transformation, where commercial farming enterprises prioritize uptime assurance over capital expenditure minimization.
Vietnam Combine Harvester Market Segmentation
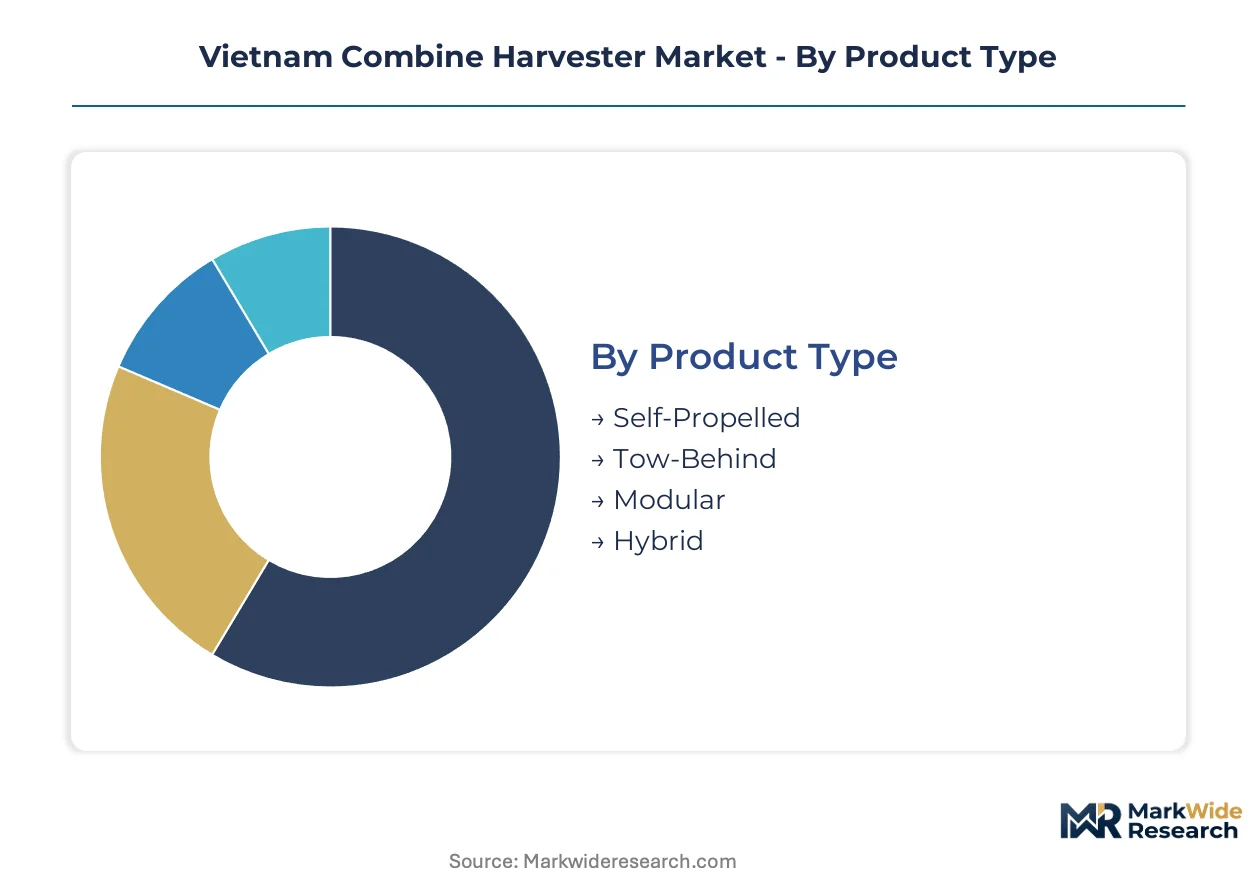
Vietnam's combine harvester segmentation reflects a market transitioning from basic mechanization toward precision-enabled fleet management. Each dimension captures distinct procurement logics across the Mekong Delta's commercial farms and the Red River Delta's cooperative networks.
Product Type:
Mature self-propelled platforms anchor Vietnamese fleet composition while emerging configurations test niche viability.
- Self-Propelled:Integrated diesel-powered units with 50-400 horsepower ratings perform cutting, threshing, and cleaning in continuous passes. Demand concentrates in An Giang and Dong Thap provinces where triple-cropping compresses harvest windows below 14 days per cycle. These units command premium positioning through throughput efficiency on fragmented paddy fields.
- Tow-Behind:Tractor-pulled threshing attachments suit smaller holdings with seasonal mechanization needs. Agricultural cooperatives in Thai Binh and Ha Nam provinces deploy these for cost-controlled fleet flexibility during peak labor shortage periods.
- Modular:Separable header and threshing components enable transport between dispersed plots. Farm service providers in Long An province favor these for multi-client harvesting contracts across non-contiguous landholdings.
- Hybrid:Diesel-electric powertrain prototypes are entering field trials with Vietnam's Ministry of Agriculture and Rural Development support. Commercial farming enterprises in Can Tho province pilot these for fuel cost reduction validation.
Self-Propelled handles the majority of throughput; Hybrid is the fastest mover on share.
End User:
Customer type segmentation tracks land consolidation patterns reshaping equipment ownership models.
- Farmers:Individual owner-operators with holdings under 2 hectares dominate unit volume through subsidized procurement programs. These buyers prioritize acquisition cost minimization over feature depth in Mekong Delta peripheral districts.
- Agricultural Cooperatives:Member-owned entities pool capital for fleet acquisition and shared utilization scheduling. Cooperatives in Hung Yen and Bac Ninh provinces are expanding fastest through Ministry of Agriculture and Rural Development financing access.
- Contract Farmers:Professional management companies operating consolidated land blocks generate concentrated demand for high-capacity configurations. These operators in Dong Thap province specify telematics-enabled uptime guarantees in procurement tenders.
- Exporters:Vertically integrated rice trading houses maintain captive harvesting capacity for quality-controlled supply chain integration. These end users in An Giang province demand traceability documentation aligned with EU and Middle East import standards.
Agricultural Cooperatives capture the steepest expansion trajectory as subsidy eligibility broadens; Farmers retain the deepest installed base.
Technology:
Technology tiers reflect adoption gradients from proven mechanical systems to sensor-integrated automation.
- Conventional:Hydraulically actuated threshing and cleaning mechanisms without electronic control modules. These systems dominate replacement cycles in provinces with sparse dealer service coverage.
- Precision Agriculture:Yield-mapping sensors and GPS-guided steering enable multi-year field optimization. Agricultural cooperatives in Tien Giang province are the primary adopters, bundling these capabilities with ministry-supported digital agriculture initiatives.
- Smart IoT:Cellular-connected diagnostic systems transmit engine and hydraulic performance data to dealer service centers. Fleet operators in Can Tho city prioritize these subscriptions for downtime compression.
- Autonomous:Operator-optional field navigation systems are in limited demonstration with state research institutes. Regulatory frameworks for unmanned agricultural machinery remain under development by Vietnam's national standards body.
Conventional technology maintains the largest active fleet; Precision Agriculture is climbing the fastest on new equipment share.
Power Rating:
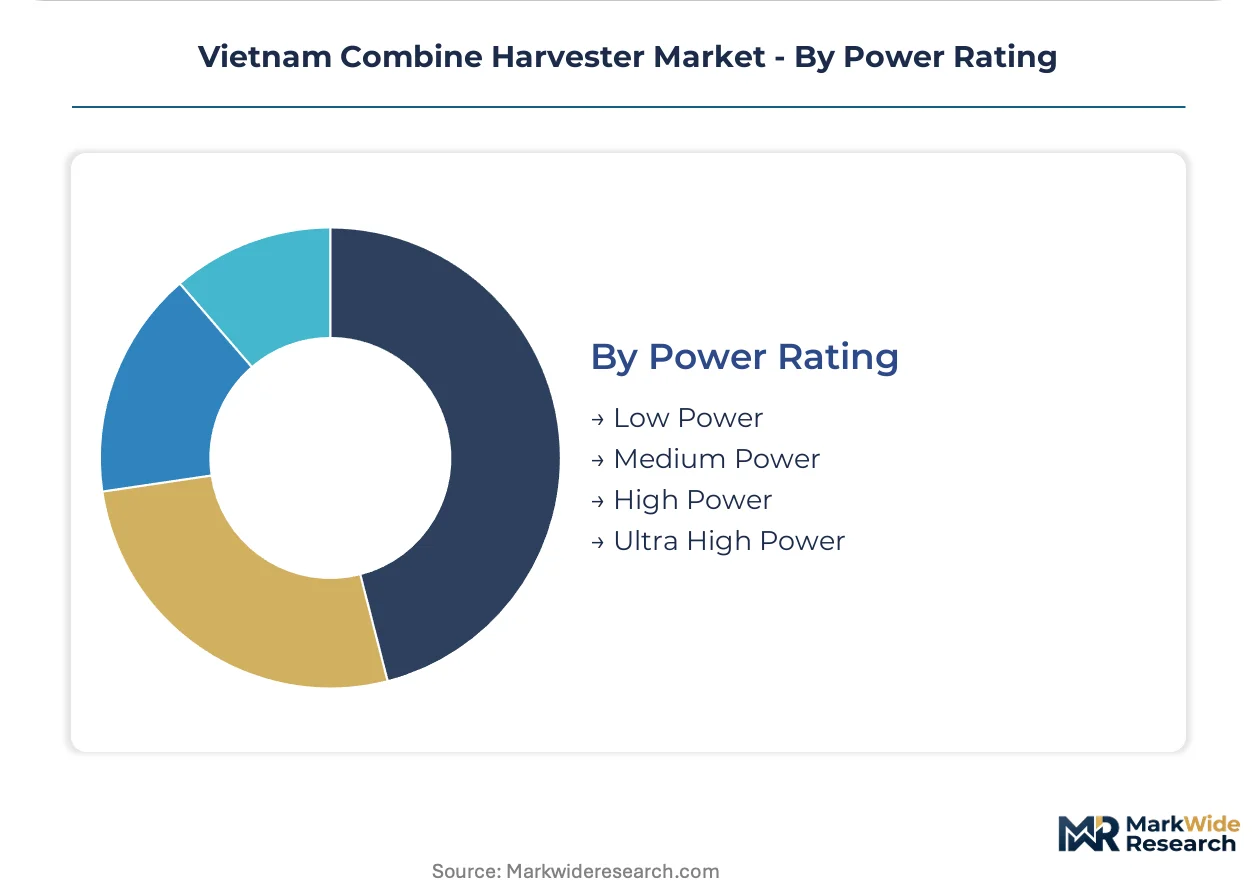
Power segmentation maps equipment scale to farm size distribution and cropping intensity requirements.
- Low Power:Units below 75 horsepower suit smallholder plots and terraced terrain in northern mountainous provinces. These configurations qualify for maximum subsidy rates under rural development programs.
- Medium Power:75-150 horsepower equipment balances acquisition cost against throughput for typical Vietnamese farm holdings. This tier dominates volume in the Red River Delta's intensive rice-growing provinces where double-cropping prevails.
- High Power:150-250 horsepower systems serve commercial operations with triple-cropping mandates. Contract farming enterprises in An Giang province specify these for 12-hour continuous operation capability.
- Ultra High Power:Exceeding 250 horsepower, these configurations address consolidated land blocks exceeding 50 hectares. Limited demand concentrates in state-owned agricultural corporations with centralized procurement authority.
Medium Power generates the highest unit shipments; High Power is expanding most quickly as land consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam's Ministry of Agriculture and Rural Development subsidizes mechanization through provincial disbursement programs that concentrate fleet investment in the Mekong and Red River Deltas. Equipment demand clusters where triple-cropping mandates compress harvest windows below 14 days per cycle.
Mekong Delta
An Giang and Dong Thap provinces anchor commercial farming expansion with consolidated land blocks exceeding 50 hectares. Provincial agricultural departments administer Ministry of Agriculture and Rural Development subsidy verification for cooperative fleet procurement. Can Tho city serves as the regional machinery distribution hub where telematics-enabled service contracts displace pure equipment sales.
Red River Delta
Intensive double-cropping in Thai Binh and Ha Nam provinces generates medium-power equipment volume for agricultural cooperatives. National standards body certification requirements filter import eligibility for state-supported procurement programs. Hung Yen and Bac Ninh provinces exhibit the fastest cooperative fleet growth through expanded financing access.
Central Highlands
Coffee and pepper plantation mechanization is diversifying harvester applications beyond rice in Lam Dong and Dak Lak provinces. Provincial rural development offices coordinate demonstration trials for multi-crop platform adaptations. Pleiku and Buon Ma Thuot function as emerging service centers where spare parts distribution gaps are narrowing through private dealership investment.
Northern Midlands and Mountainous Areas
Low-power equipment dominates terraced terrain in Lao Cai and Yen Bai provinces where smallholder holdings average under 2 hectares. Maximum rural development subsidy rates apply to sub-75 horsepower configurations in these districts. Thai Nguyen province hosts vocational institutes that manufacturer-funded training programs target for mechanic certification expansion.
Southeast Region
Industrial zone proximity in Binh Duong and Dong Nai provinces supports component fabrication for domestic assembly qualification. Local-content thresholds for state procurement preference incentivize Vietnamese parts sourcing. Ho Chi Minh City anchors financing and insurance services that underwrite commercial farming enterprise fleet expansion.
Vietnam Combine Harvester Market Competitive Landscape
On the supply side, the industry is bifurcated between established Japanese and European manufacturers with Vietnamese assembly presence and emerging Chinese and domestic competitors penetrating through price-sensitive segments. Three strategic archetypes dominate: integrated assemblers with localized supply chains, pure importers leveraging financing partnerships, and diversified automotive conglomerates extending into farm machinery. Competitive moves concentrate on domestic content certification for subsidy eligibility and service network densification to compress downtime risks.
Among Japanese-origin integrated manufacturers, Kubota Corporation and Iseki Corporation exemplify the archetype of regional supply chain anchoring through established Vietnamese assembly infrastructure. Within the diversified automotive tier, Truong Hai Auto Corporation represents channel extension from commercial vehicle financing into agricultural equipment. European precision specialists CLAAS KGaA mbH occupy a position emphasizing high-capacity configurations for contract farming concentration in An Giang and Dong Thap provinces. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning in subsidy-administered procurement environments.
| Leading Market Players |
|---|
| Vietnam Engine and Agricultural Machinery Corporation |
| Iseki Corporation |
| Kubota Corporation |
| Tong Yang Moolsan Co Ltd |
| Truong Hai Auto Corporation (THACO) |
| CLAAS KGaA mbH |
| CNH Industrial |
| ShanDong Huaxin Machinery Co Ltd |
| Yanmar America Corporation |
| Others |
Value Network & Pricing Analysis
Can Tho city's machinery distribution hub concentrates regional assembly capacity and aftermarket service infrastructure, translating supply-side density into pricing leverage for dealers bundling multi-year maintenance contracts. Vietnamese domestic content thresholds for state procurement preference compress import-dependent cost structures while rewarding localized fabrication investment.
Pricing Analysis
Certification level against BIS-equivalent emissions and safety standards creates the primary spread between subsidy-eligible premium tiers and non-compliant economy imports. Three-tier pricing structure across premium, standard, and economy levels reflects domestic assembly qualification, telematics bundling, and spare parts availability guarantees. Cost compression in the economy tier is intensifying because Chinese manufacturers penetrate through price-sensitive smallholder segments. Agricultural cooperatives exhibit least price sensitivity due to ministry financing access; individual farmers under 2 hectares face acute budget constraints.
Supply Chain Analysis
Extended payment terms from Japanese and European parent companies anchor working capital flexibility for Vietnamese assemblers competing against cash-upfront Chinese imports. Component sourcing concentrates in Thailand, Japan, and South Korea for precision hydraulics and engine powertrains. Steel sheet and rubber track assemblies draw from domestic Southeast Region fabrication. Single-source vulnerability sits with specialized threshing drum suppliers in Japan. Distribution runs through provincial dealership networks with service bundling displacing pure equipment transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-enabled predictive maintenance subscriptions expand faster than hardware unit sales, transforming harvester procurement from capital expenditure into service-attach relationships. Recurring revenue from remote diagnostic and spare parts availability contracts now exceeds margin capture on initial equipment placement.
For Market Incumbents: Entrench service network density in Dong Thap and An Giang provinces where contract farming consolidation concentrates fleet demand. Deepen backward integration into hydraulic component fabrication to satisfy tightening domestic content thresholds. Defend against Chinese price penetration by locking agricultural cooperatives into multi-year uptime guarantees that commoditized imports cannot match. For New Entrants and Emerging Players: Peripheral Mekong Delta provinces with sparse dealer coverage represent the most penetrable entry point for modular and tow-behind configurations serving smallholder seasonal demand. Low-power equipment segments in northern mountainous districts qualify for maximum rural development subsidy rates with lighter certification burden. Partner with provincial vocational institutes to fund mechanic certification programs that differentiate aftermarket capability. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision agriculture specialists with yield-mapping sensor integration and GPS-guided steering already field-validated. Five-to-ten year viability hinges on regulatory alignment with evolving BIS-equivalent standards rather than hardware scale. Monitor subsidy disbursement timeline compression as the inflection signal for cooperative fleet refresh acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Expansion | Local-content qualification unlocks state procurement preference in Mekong Delta cooperative tenders. |
| Telematics Platform Integration | Remote diagnostic subscriptions compress downtime for An Giang contract farming operators. |
| Service Network Densification | Provincial hub expansion in Long An and Tien Giang narrows spare parts distribution gaps. |
| Precision Agriculture Partnership | Yield-mapping bundling with ministry digital agriculture initiatives accelerates cooperative adoption. |
| Mechanic Certification Program | Vocational institute alliances in Thai Nguyen address technical operator scarcity for hydraulic diagnostics. |
Research Methodology
Cross-validation between equipment distributor sales records and provincial agricultural department subsidy disbursement data anchors the qualitative findings on procurement cyclicality. Primary interviews with agricultural cooperative fleet managers, dealership service heads, and Ministry of Agriculture and Rural Development program administrators combined with secondary validation from customs import records, national standards body certification registries, and diesel engine emissions compliance filings. Bottom-up unit shipment tracking and top-down subsidy budget allocation analysis triangulate market sizing.
Calibration against historical fleet renewal patterns and triple-cropping mandate implementation timelines shapes the projection framework across the analysis window. Segmentation dimensions modeled include power rating tier, technology sophistication level, end-user ownership structure, and regional cropping intensity cluster. CAGRs derive from equipment replacement cycle compression and subsidy eligibility expansion trajectories. Forecast inputs incorporate diesel-electric hybrid prototype trial results and telematics subscription attach rate assumptions.
Practitioners should monitor import tariff volatility and BIS-equivalent standards evolution for early signals of competitive repositioning requirements. Forecasts reflect assumptions on subsidy disbursement continuity and cooperative financing access sustainability. Macroeconomic credit tightening, regulatory certification delays, or powertrain technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Milking Robots Market
Agricultural Machinery
Cow Milking Machine Market
Agricultural Machinery
Agricultural Harvester Market
Agricultural Machinery
Agricultural Tractor Robots Market
Agricultural Machinery
Global Autonomous Tractor Market
Agricultural Machinery
Garden and Orchard Tractors Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Forestry Machinery Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Compact Tractor Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
Hydrogen Powered Tractor Market
Agricultural Machinery
Crawler Tractors Market
Agricultural Machinery
Crop Sprayers Market