
 Netherlands Hydrogen Powered Tractor Market | 2026-2036
Netherlands Hydrogen Powered Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Hydrogen Powered Tractor Market Insights
Specialized hydrogen systems engineering talent is reorganizing competitive dynamics across Dutch agricultural equipment manufacturing. New Holland Agriculture leverages its long-standing dealer network and localized assembly footprint to sustain market presence in the Netherlands. Fendt differentiates through precision farming integration and high-horsepower fuel cell architectures. H2Trac specializes in purpose-built hydrogen tractor platforms designed explicitly for northwest European field conditions and refueling infrastructure.
Hydrogen powered tractors employ proton exchange membrane fuel cells generating 50-300 kW continuous output, with onboard compressed hydrogen storage at 350-700 bar pressure ratings, serving primary commercial purpose of zero-emission mechanized field operations without battery recharging downtime. Standard tractors occupy the dominant revenue position given immediate replacement demand from conventional diesel fleets across Dutch dairy and arable sectors. Autonomous tractors represent the fastest-expanding technology segment as labor costs rise and GPS-guided field autonomy matures. Fuel cell technology leads installed base composition, though hybrid systems are gaining traction where hydrogen refueling station density remains insufficient for pure fuel cell operation.
The EU Green Deal and national Climate Agreement obligations enforced by the Netherlands Enterprise Agency shape equipment procurement subsidies and fleet renewal timelines. REACH chemical safety standards and CE marking requirements govern fuel cell component importation and hydrogen storage cylinder certification. Stakeholders must monitor refueling infrastructure buildout commitments from Gasunie and regional hydrogen hub consortia to align production capacity with actual deployment velocity.
Market Dynamics
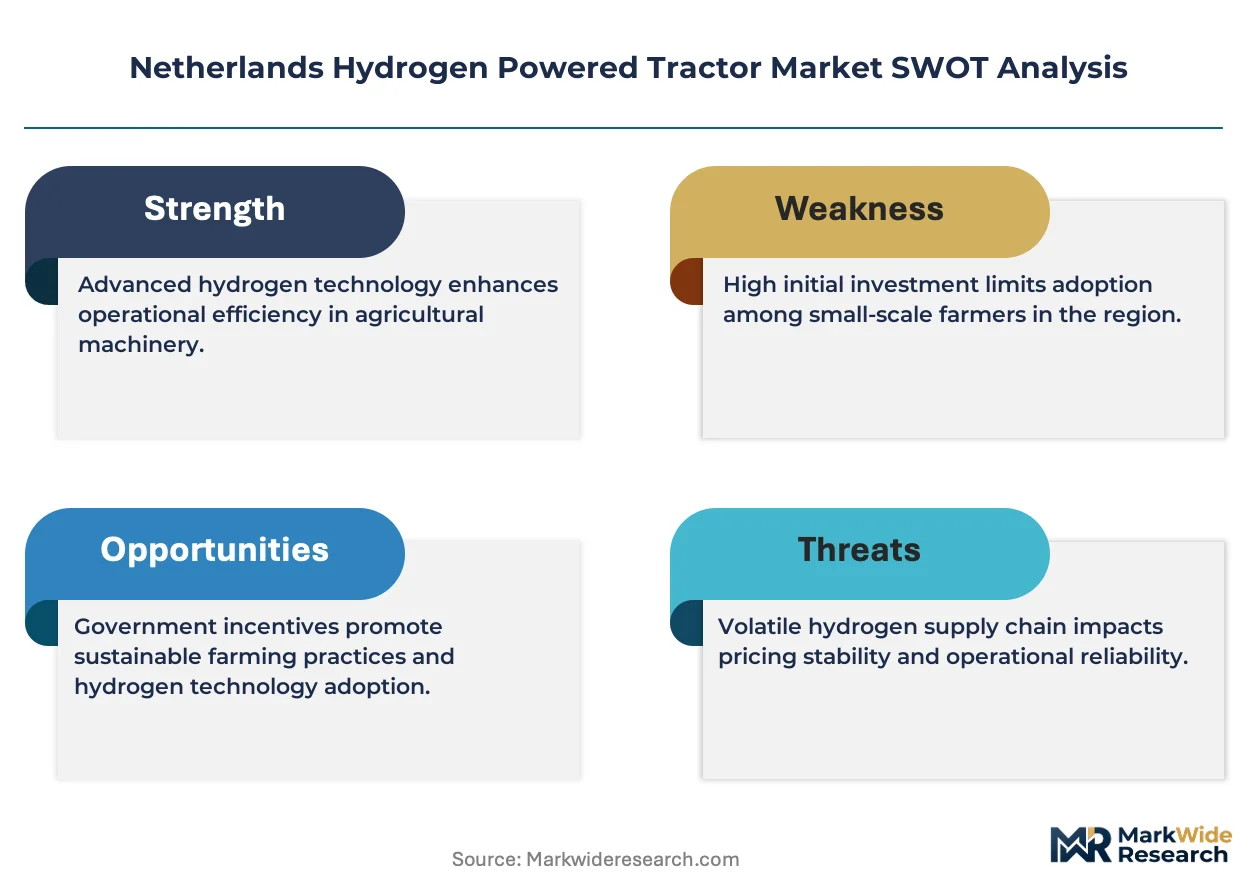
The EU Green Deal's agricultural decarbonization mandates are compressing fleet renewal timelines for Dutch arable cooperatives, forcing immediate capital allocation toward zero-emission mechanization before subsidy windows narrow.
Growth Catalysts
- EU Green Deal enforcement:The Netherlands Enterprise Agency administers procurement subsidies that accelerate diesel-to-hydrogen fleet conversions across Flevoland's potato and onion operations.
- Fuel cell stack efficiency gains:Bosch and Toyota suppliers have reduced total cost of ownership through improved proton exchange membrane performance at 50-300 kW output ranges.
- Arable farming cooperative consolidation:Large-scale Dutch operations in Gelderland and Noord-Brabant are pooling procurement power to secure volume pricing on hydrogen tractor platforms.
Market Restraints
- Compressed hydrogen storage costs:350-700 bar pressure-rated cylinder certification under REACH chemical safety standards adds substantial upfront capital burden for smaller dairy operations.
- Refueling infrastructure gaps:Gasunie's hydrogen hub buildout commitments remain concentrated in coastal industrial zones, leaving eastern agricultural regions underserved.
- Battery-electric substitution threat:Lower-horsepower dairy applications increasingly favor battery tractors where daily duty cycles permit overnight charging.
Strategic Opportunities
- Autonomous tractor integration:GPS-guided field autonomy is converging with fuel cell platforms to address labor cost pressures in Friesland's dairy sector.
- Hybrid system development:Technology blending fuel cells with small buffer batteries captures demand where hydrogen station density remains insufficient for pure fuel cell operation.
- Regional hydrogen hub alignment:The Dutch Climate Agreement's regional consortia present partnership pathways for equipment manufacturers to secure captive offtake agreements.
Industry Challenges
- Hydrogen systems engineering talent scarcity:Specialized fuel cell integration expertise remains concentrated among a limited pool of Dutch agricultural equipment engineers.
- CE marking certification timelines:Fuel cell component importation approvals under EU machinery directives create production scheduling uncertainty for localized assembly operations.
- Dealer network retraining intensity:Existing service infrastructure requires substantial reskilling to handle high-pressure hydrogen storage maintenance protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Hydrogen Powered Tractor Market |
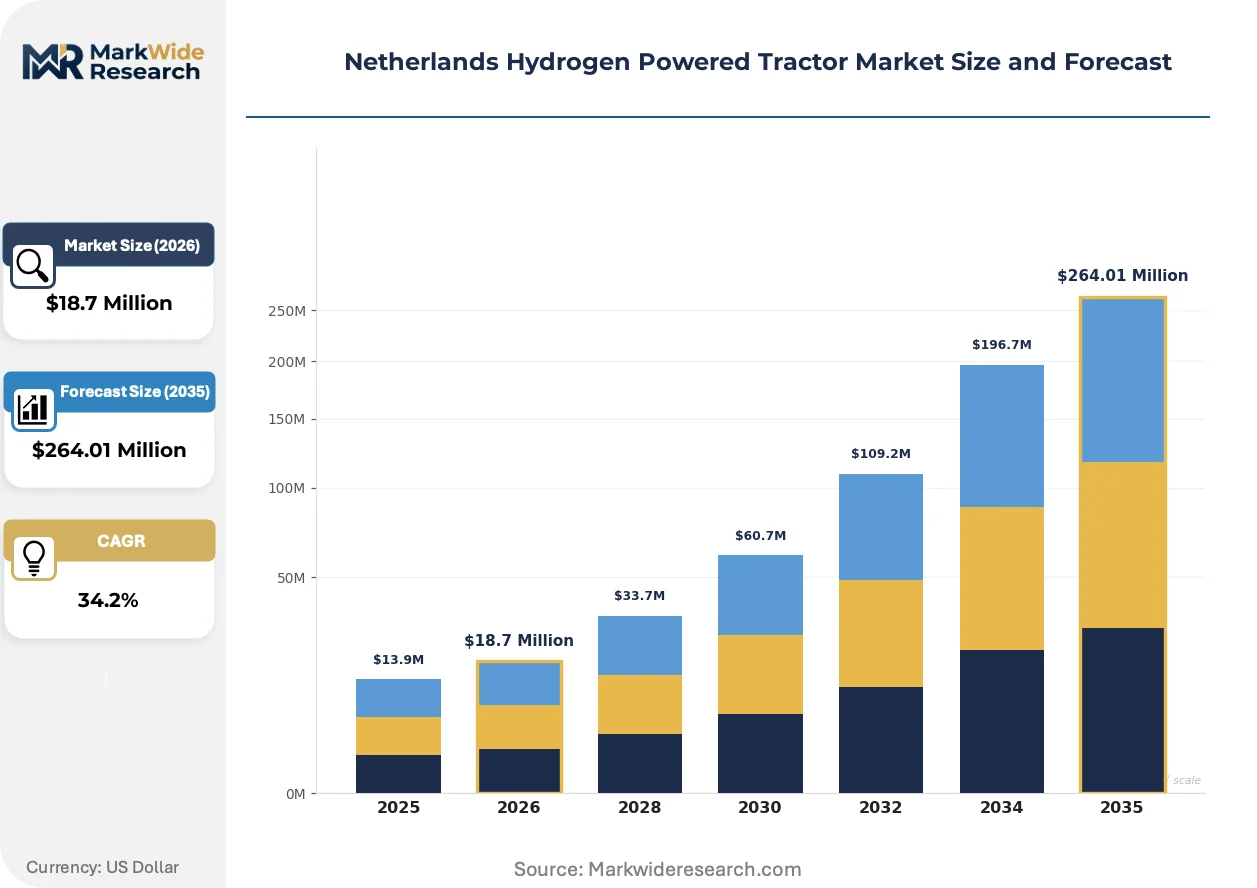
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $264.01 Million |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Tractors, Autonomous Tractors, Compact Tractors, Large-Scale Tractors End User: Agriculture, Horticulture, Landscaping, Government Technology: Fuel Cell, Hybrid Systems, Battery Electric, Electrolyzer Systems Installation: New Construction, Retrofits, Mobile Units, Fixed Locations |
| Companies Covered | Steyr Tractors, AGCO Power, EOX Tractors, Kubota, CNH Industrial, New Holland Agriculture, Fendt, H2Trac, Case IH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Hydrogen Powered Tractor Market Trends and Innovations
Proton exchange membrane fuel cell architectures are actively displacing incumbent diesel-electric hybrid designs across Dutch agricultural equipment portfolios, compressing technology adoption curves.
Fuel cell systems generating 50-300 kW continuous output are supplanting conventional diesel powertrains in high-horsepower arable applications. Flevoland's large-scale potato operations are adopting these platforms at accelerating pace to meet EU Green Deal compliance deadlines. This shift is compressing residual value expectations for used diesel tractor fleets and reallocating capital toward hydrogen-compatible implements.
The Netherlands Enterprise Agency's subsidy frameworks under the national Climate Agreement are mandating zero-emission fleet percentages for cooperative procurement tenders. Dutch dairy and arable sectors must now document carbon intensity reductions to maintain eligibility for operating permits. Noord-Brabant's intensive livestock operations face the steepest compliance ramps, driving earliest adoption of certified hydrogen platforms.
Cooperative procurement pooling is consolidating buyer power among Netherlands arable farming associations. Traditional dealer-direct sales models are yielding to collective tendering structures that specify fuel cell performance guarantees and refueling infrastructure commitments. Gelderland's sugar beet processing cooperatives exemplify this shift, negotiating multi-unit platform purchases with embedded hydrogen supply agreements.
Netherlands Hydrogen Powered Tractor Market Segmentation
Dutch hydrogen tractor procurement patterns diverge sharply across farm scale, crop type, and compliance urgency. Segmentation reveals how EU Green Deal enforcement filters through distinct operational contexts and technology readiness levels.
Product Type:
REACH chemical safety standards and CE marking requirements impose differentiated certification burdens across tractor architectures, reshaping manufacturer prioritization.
- Standard Tractors:These units deploy proton exchange membrane fuel cells generating 50-300 kW continuous output with 350-700 bar compressed hydrogen storage. Demand concentrates in Flevoland's potato and onion operations where immediate diesel replacement timelines compress procurement decisions under EU Green Deal mandates.
- Autonomous Tractors:GPS-guided field autonomy converges with fuel cell platforms to address labor cost pressures. Friesland's dairy sector drives adoption fastest as 24-hour milking operations require uninterrupted mechanized fieldwork without operator fatigue constraints.
- Compact Tractors:Smaller footprint units serve Gelderland's horticultural greenhouses where maneuverability constraints limit larger platform deployment.
- Large-Scale Tractors:High-horsepower architectures dominate Noord-Brabant's intensive arable cooperatives requiring maximum tillage output per machine hour.
Established volume favors Standard Tractors; emerging adoption favors Autonomous Tractors.
End User:
Subsidy accessibility and fleet renewal cycles create distinct procurement velocities across Dutch operational categories.
- Agriculture:Arable farming cooperatives in Flevoland and Gelderland pool procurement power through collective tendering structures. These buyers specify fuel cell performance guarantees and embedded hydrogen supply agreements to secure volume pricing.
- Horticulture:Greenhouse operators in Westland prioritize compact platforms with precision maneuvering for protected cropping environments. Daily duty cycles here favor shorter-range hydrogen configurations.
- Landscaping:Municipal and commercial grounds maintenance contracts in Randstad urban corridors specify zero-emission equipment for public space management.
- Government:Provincial environmental agencies and water boards procure demonstration fleets to validate hydrogen performance under Dutch Climate Agreement pilot programs.
Procurement scale favors Agriculture; subsidy pilot access favors Government.
Technology:
Refueling infrastructure density dictates viable technology selection across Dutch regional hydrogen hub deployment schedules.
- Fuel Cell:Pure proton exchange membrane architectures deliver 50-300 kW continuous output without battery recharging downtime. These systems lead installed base composition where Gasunie's coastal hydrogen hubs provide reliable offtake.
- Hybrid Systems:Technology blending fuel cells with small buffer batteries captures demand in eastern agricultural regions where station density remains insufficient for pure fuel cell operation.
- Battery Electric:Lower-horsepower platforms serve dairy applications with overnight charging capacity, though daily duty cycle limitations constrain broader arable adoption.
- Electrolyzer Systems:Onboard hydrogen generation through electrolysis remains experimental, with limited commercial deployment in demonstration projects.
Operational maturity favors Fuel Cell; infrastructure flexibility favors Hybrid Systems.
Installation:
Capital deployment timing and existing asset bases determine installation modality selection across Dutch farm renewal cycles.
- New Construction:Greenfield agricultural developments in Flevoland's polder regions specify hydrogen-compatible infrastructure from project inception, avoiding retrofit constraints.
- Retrofits:Diesel-to-hydrogen conversion programs extend asset life for cooperatives with recent conventional fleet investments, though CE marking certification timelines create production scheduling uncertainty.
- Mobile Units:Trailer-mounted hydrogen refueling systems serve dispersed operations in Drenthe and Overijssel where fixed station buildout lags.
- Fixed Locations:Permanent on-farm hydrogen production and storage installations align with large-scale cooperative processing facilities in Noord-Brabant.
Greenfield efficiency favors New Construction; legacy asset preservation favors Retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands Enterprise Agency administers procurement subsidies under the national Climate Agreement, anchoring Dutch agricultural decarbonization policy. EU Green Deal mandates compress fleet renewal timelines across Dutch provinces. Regional hydrogen hub deployment from Gasunie creates uneven infrastructure access between coastal and interior farming zones.
North Holland
Flevoland's potato and onion cooperatives drive concentrated demand for high-horsepower hydrogen platforms. The Netherlands Enterprise Agency's subsidy frameworks mandate zero-emission fleet percentages for collective procurement tenders. Noord-Scharwoude's arable processing facilities anchor early hydrogen tractor deployment under Climate Agreement pilot programs.
South Holland
Westland's greenhouse horticulture sector prioritizes compact hydrogen tractors for precision maneuvering in protected cropping environments. REACH chemical safety standards govern 350-700 bar cylinder certification for smaller-scale operations. Delft's agricultural technology cluster supports fuel cell integration engineering for regional equipment manufacturers.
North Brabant
Intensive livestock and arable cooperatives face the steepest EU Green Deal compliance ramps, accelerating certified hydrogen platform adoption. The Dutch Climate Agreement's regional consortia structure partnership pathways for captive offtake agreements. Veghel's food processing hub coordinates multi-unit tractor procurement with embedded hydrogen supply contracts.
Friesland
24-hour dairy operations require uninterrupted mechanized fieldwork, driving GPS-guided autonomous tractor integration with fuel cell platforms. Labor cost pressures intensify as milking schedules constrain operator availability. Leeuwarden's agricultural engineering institutes supply specialized hydrogen systems talent to regional equipment servicers.
Gelderland
Sugar beet processing cooperatives pioneer collective tendering structures that specify fuel cell performance guarantees and refueling infrastructure commitments. Arable farming associations pool procurement power to secure volume pricing on hydrogen-compatible implements. Wageningen's agrotechnology campus anchors research partnerships validating field performance under Dutch soil conditions.
Netherlands Hydrogen Powered Tractor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with dealer network scale and fuel cell engineering capability determining competitive position. New Holland Agriculture leverages localized assembly footprints and long-standing service infrastructure to sustain market presence. Fendt differentiates through precision farming integration and high-horsepower architectures. H2Trac occupies the purpose-built specialist position with platforms designed explicitly for northwest European field conditions. Competitive moves concentrate on strategic partnerships with hydrogen hub consortia and portfolio diversification into hybrid system architectures.
Among established agricultural equipment manufacturers, New Holland Agriculture, Fendt, and H2Trac represent distinct competitive archetypes. New Holland Agriculture exemplifies the integrated leader with dealer network depth and localized production capacity. Fendt occupies the premium-tier position emphasizing precision technology integration. H2Trac anchors the specialist tier with dedicated hydrogen platform engineering. AGCO Power, Steyr Tractors, and CNH Industrial sit within broader industrial conglomerate structures that supply powertrain components across multiple equipment categories. EOX Tractors and Case IH represent additional branded positions within this competitive set, while Kubota's compact equipment heritage informs its approach to smaller-scale agricultural mechanization.
| Leading Market Players |
|---|
| Steyr Tractors |
| AGCO Power |
| EOX Tractors |
| Kubota |
| CNH Industrial |
| New Holland Agriculture |
| Fendt |
| H2Trac |
| Case IH |
| Others |
Pricing and Supply Chain Analysis
Proton exchange membrane fuel cell stacks displacing diesel powertrains are simultaneously relocating component sourcing toward German and Japanese manufacturing corridors and compressing total cost of ownership curves for Dutch arable cooperatives. This substitution dynamic concentrates pricing power among Bosch and Toyota suppliers while forcing localized assemblers to absorb REACH certification premiums.
Pricing Analysis
Geographic price spreads between Flevoland's large-scale potato operations and Friesland's dairy sector reflect divergent procurement scale and subsidy accessibility. Three-tier pricing structure across premium autonomous platforms, standard fuel cell architectures, and economy hybrid configurations stratifies by horsepower output and precision farming integration. Pricing pressure stems from battery-electric substitution in lower-horsepower dairy applications where overnight charging suffices. Small-scale horticultural operators in Westland exhibit highest price sensitivity due to compressed margins in protected cropping, while Noord-Brabant's intensive arable cooperatives prioritize performance guarantees over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for fuel cell stack imports from Japan and South Korea. Component sourcing draws from Germany for precision hydraulics, Japan for membrane electrode assemblies, and Belgium for high-pressure cylinder fabrication. Single-source vulnerability around proton exchange membrane intellectual property creates supply chain risk if Bosch or Toyota constrain allocation. Distribution runs through New Holland Agriculture's long-standing dealer network and emerging direct procurement channels from cooperative tendering structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in Dutch hydrogen tractor adoption rests on EU Green Deal enforcement compressing fleet renewal timelines ahead of narrowing subsidy windows.
For Market Incumbents: Fortify dealer network reskilling programs to handle 350-700 bar hydrogen storage maintenance protocols before service capability gaps widen. Secure captive offtake agreements with Gasunie's regional hydrogen hub consortia to anchor demand visibility. Deepen backward integration into fuel cell stack assembly to reduce exposure to Bosch and Toyota allocation constraints. For New Entrants and Emerging Players: Aftermarket service coverage gaps in eastern agricultural regions present entry pathways for mobile hydrogen refueling and field repair units. Target Drenthe and Overijssel where fixed station buildout lags and incumbent service density remains thinnest. Pursue equipment-as-a-service models bundling tractor access with embedded hydrogen supply to bypass capital-intensive procurement barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture technology platforms seeking hydrogen integration capabilities to complete their stack. Five-to-ten year viability hinges on refueling infrastructure velocity matching equipment deployment. Monitor Gasunie's hydrogen hub commissioning schedules as the critical inflection signal for demand realization.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Hydrogen Hub Partnership | Secures captive offtake with Gasunie consortia anchoring demand visibility for Noord-Brabant cooperatives. |
| Dealer Network Reskilling Program | Builds certified maintenance capacity for high-pressure storage systems before service gaps widen. |
| Hybrid System Architecture Development | Captures demand in eastern regions where station density insufficient for pure fuel cell operation. |
| Autonomous Platform Integration | Addresses Friesland labor constraints through GPS-guided field autonomy converging with fuel cells. |
| Cooperative Procurement Alignment | Aligns production capacity with Gelderland collective tendering structures specifying performance guarantees. |
Research Methodology
A spread of perspectives from agricultural cooperative procurement managers, fuel cell systems engineers, dealer network operators, and Netherlands Enterprise Agency subsidy administrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Green Deal implementation timelines, REACH chemical safety documentation, and CE marking certification databases. Customs records tracking fuel cell component importation, Gasunie infrastructure buildout disclosures, and Dutch Climate Agreement progress reports supplied quantitative anchors. Bottom-up equipment deployment estimates triangulated against top-down subsidy allocation trajectories.
Segmentation dimensions modeled span product type, end user category, technology architecture, and installation modality across the projection horizon. Horsepower tier, precision farming integration level, and regional hydrogen hub proximity provided additional granularity. CAGRs derived from equipment replacement cycle analysis, cooperative procurement pooling trends, and refueling infrastructure deployment schedules. Forecast inputs incorporated EU Green Deal compliance deadline impacts, fuel cell stack efficiency improvement curves, and battery-electric substitution elasticity in dairy applications.
Forecasts assume regulatory continuity in EU Green Deal enforcement and Netherlands Climate Agreement subsidy frameworks; material policy shifts would require re-modeling adoption velocity and fleet renewal timelines. Commodity hydrogen pricing volatility, CE marking certification delays, and unexpected battery-electric performance improvements constitute specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Cambodia Agricultural Machinery Market
Agricultural Machinery
China Agricultural Tractors Market
Agricultural Machinery
Tiller Machine Market
Agricultural Machinery
United States Haying and Forage Machinery Market
Agricultural Machinery
Two-Wheeler Tractors Market
Agricultural Machinery
Europe Agricultural Sprayer Market
Agricultural Machinery
North America Haying and Forage Machinery Market
Agricultural Machinery
Brazil Agricultural Tractors Market
Agricultural Machinery
US Agriculture Drone Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Argentina Agricultural Machinery Market
Agricultural Machinery
North America Agricultural Machinery Market
Agricultural Machinery
Global Crop Harvesting Robots Market
Agricultural Machinery
Rice Mill Machine Market
Agricultural Machinery
Electric Farm Tractor Market