
 United States Alfalfa Market | 2026-2036
United States Alfalfa Market Size, Share, and Industry Trends Forecast 2026-2036
United States Alfalfa Market Analytics
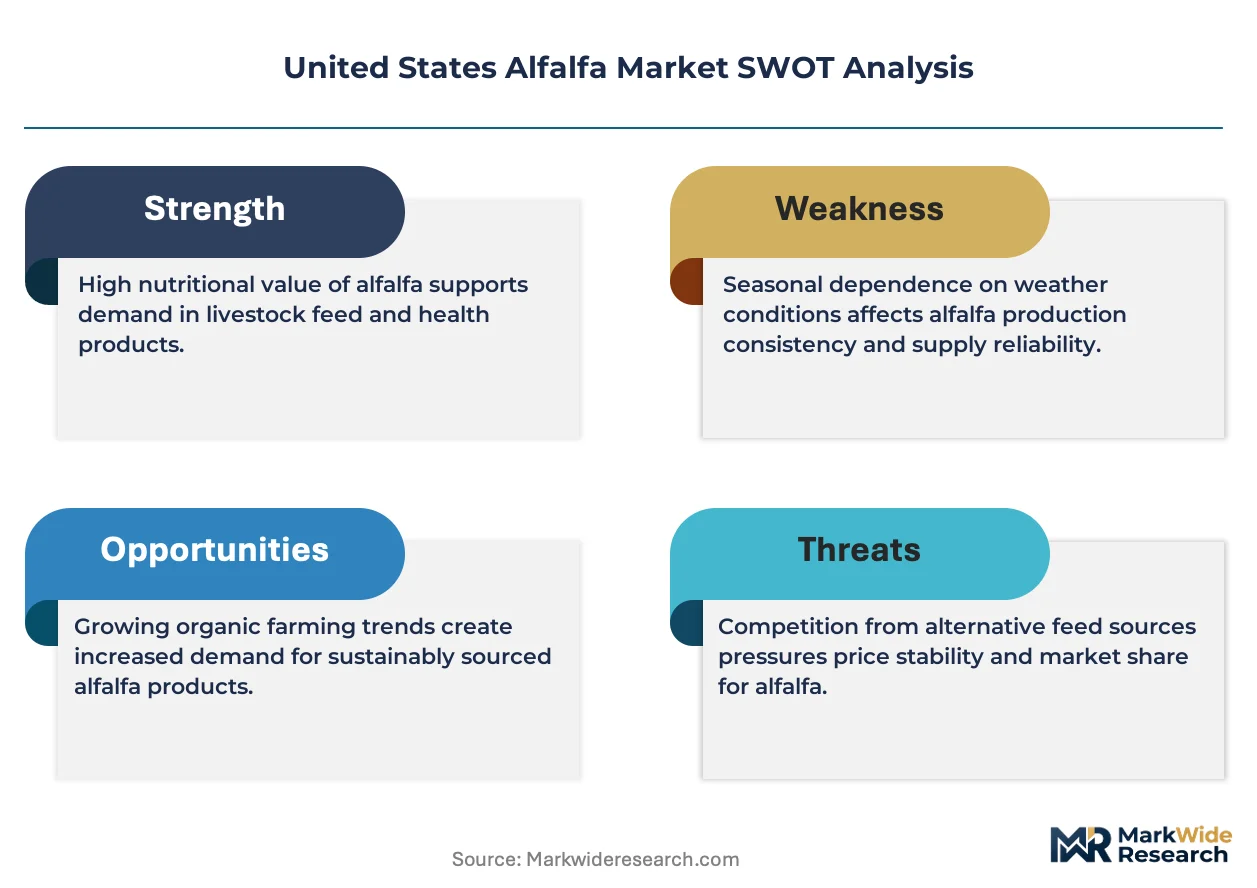
Subscription-based forage testing and nutrition consulting is shifting how alfalfa suppliers monetize relationships beyond physical delivery. Standlee Premium Products leverages vertically integrated production from Idaho fields to packaged retail formats. Anderson Hay & Grain sustains its position through export-grade certification and Pacific Northwest port access. Bailey Farms International anchors a significant share of the California dairy corridor with consistent high-temperature-dried product.
Alfalfa (Medicago sativa) is a perennial legume forage containing 15-22% crude protein on a dry-matter basis, harvested at early bloom for optimal digestibility and sold as hay, pellets, cubes, or silage to support ruminant nutrition and equine diets. Hay dominates volume throughput due to established dairy farm feeding protocols and bulk handling infrastructure, while pellets command premium positioning among pet owners and specialty livestock segments seeking reduced waste and standardized nutrient delivery. The baled form occupies the largest share of physical logistics given compatibility with existing farm equipment, though packaged formats are gaining traction through online and retail channels serving smaller-scale end users.
USDA grading standards, state-level agricultural extension water-use policies, and FDA feed safety regulations under the Food Safety Modernization Act collectively shape product specifications, harvesting timelines, and interstate commerce requirements for alfalfa producers. Compliance with these frameworks determines market access for exporters and influences grower decisions on irrigation investment and harvest scheduling. Stakeholders must monitor evolving drought-response policies in Western states and FSMA traceability expansions that could reshape processing and distribution economics.
Market Dynamics
Precision irrigation infrastructure and USDA conservation compliance requirements are restructuring how alfalfa growers allocate water resources and rotate crops across the Western United States. Dairy processor consolidation in California's Central Valley intensifies pressure on forage suppliers to deliver certified, traceable product at contracted volumes.
Growth Catalysts
- Conservation Reserve Program incentives:USDA payments for cover-crop integration encourage Upper Midwest dairy farmers to expand alfalfa acreage as a nitrogen-fixing rotation crop. This reduces synthetic fertilizer dependency while meeting soil health benchmarks.
- Dairy nutrition optimization:Protein-rich alfalfa hay displaces soybean meal in ruminant diets as feed cost ratios shift. Nutritionists at large cooperatives specify early-bloom harvest protocols to maximize digestible energy content.
- Export-grade dehydration technology:High-temperature drying systems in Idaho and Washington enable moisture-consistent cubes and pellets that meet phytosanitary standards for Pacific Rim markets.
Market Restraints
- Groundwater depletion in California:Sustainable Groundwater Management Act cutbacks restrict Central Valley irrigation allocations, forcing acreage abandonment or expensive well-deepening investments.
- Input cost volatility:Diesel fuel and potassium fertilizer prices swing unpredictably, compressing margins for hay producers who cannot pass through costs under annual supply contracts.
- Substitution by corn silage:Corn silage offers higher energy density per acre and simpler mechanized harvest, displacing alfalfa in some large-scale dairy operations prioritizing total mixed ration simplicity.
Strategic Opportunities
- Subscription nutrition consulting:Forage testing laboratories in Wisconsin and Minnesota bundle laboratory analysis with ration-balancing software, creating recurring revenue beyond physical hay sales.
- Retail packaged formats:Compressed pellets and bagged cubes target equine owners and small-scale livestock keepers through agricultural supply stores and direct-to-farm e-commerce channels.
- Conservation compliance services:Third-party advisors help growers navigate NRCS Environmental Quality Incentives Program applications, monetizing administrative expertise as a standalone offering.
Industry Challenges
- Harvest timing precision:Optimal crude protein content requires cutting at early bloom, a narrow window complicated by labor availability and weather variability across the Great Plains.
- FSMA traceability expansion:FDA Food Safety Modernization Act requirements for lot tracking and hazard analysis impose documentation burdens on smaller hay presses lacking enterprise software systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Alfalfa Market |
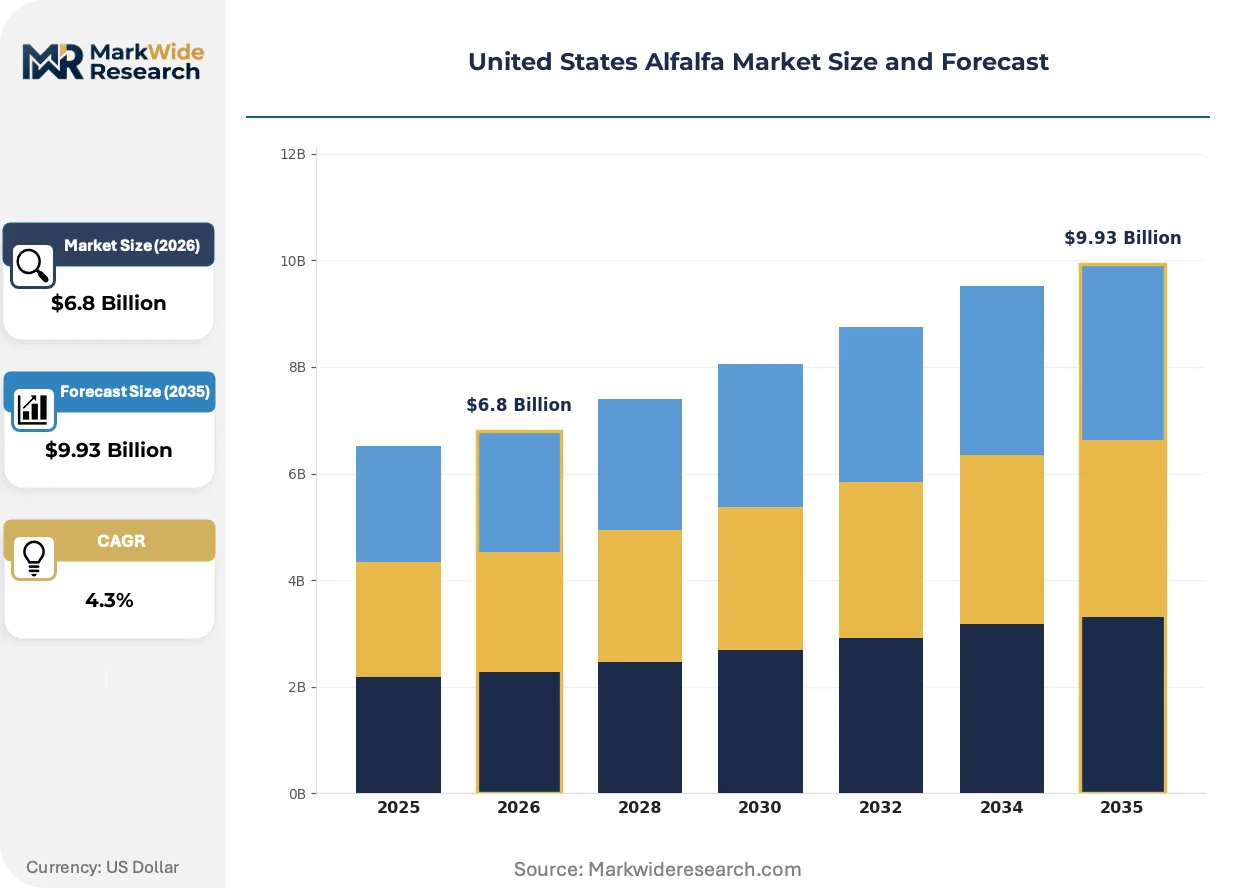
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.93 Billion |
| CAGR (2026 – 2036) | 4.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hay, Pellets, Cubes, Silage Distribution Channel: Wholesale, Retail, Online, Direct Sales End User: Dairy Farmers, Livestock Feeders, Pet Owners, Exporters Form: Loose, Baled, Shredded, Packaged |
| Companies Covered | Al Dahra ACX Global, Bailey Farms International, Anderson Hay & Grain, Border Valley, Hay USA, Standlee Premium Products, SL Follen Company, Knight Ag Sourcing, Green Prairie International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Alfalfa Market Evolving Landscape
Sensor-based crop monitoring and automated irrigation are compressing water use per ton of forage produced while regulatory pressure on groundwater extraction intensifies. These shifts favor capitalized operators capable of integrating data platforms with conservation compliance.
Variable-rate irrigation systems equipped with soil moisture probes and satellite-derived evapotranspiration data are expanding into large-scale operations across the Central Valley and Snake River Plain. Dairy cooperatives with sustainability mandates specify these technologies in supplier qualification programs. The equipment compresses per-acre water consumption while maintaining yield, enabling growers to stay within groundwater basin allocation limits.
USDA Natural Resources Conservation Service has tightened Environmental Quality Incentives Program eligibility to require documented water savings and soil carbon monitoring. This policy shift forces equipment upgrades among participants seeking cost-share payments. Western states with adjudicated groundwater basins now mandate flow meters on new agricultural wells, accelerating meter installation and telemetry adoption among alfalfa growers.
Consolidated dairy processors in California's Central Valley are unbundling nutrition consulting from commodity hay purchases, contracting directly with independent forage testing laboratories. This procurement model shift displaces traditional hay brokers who bundled logistics with advisory services. The pattern concentrates specification-setting power with processor nutritionists while fragmenting supplier relationships across smaller, specialized testing firms.
United States Alfalfa Market Segmentation
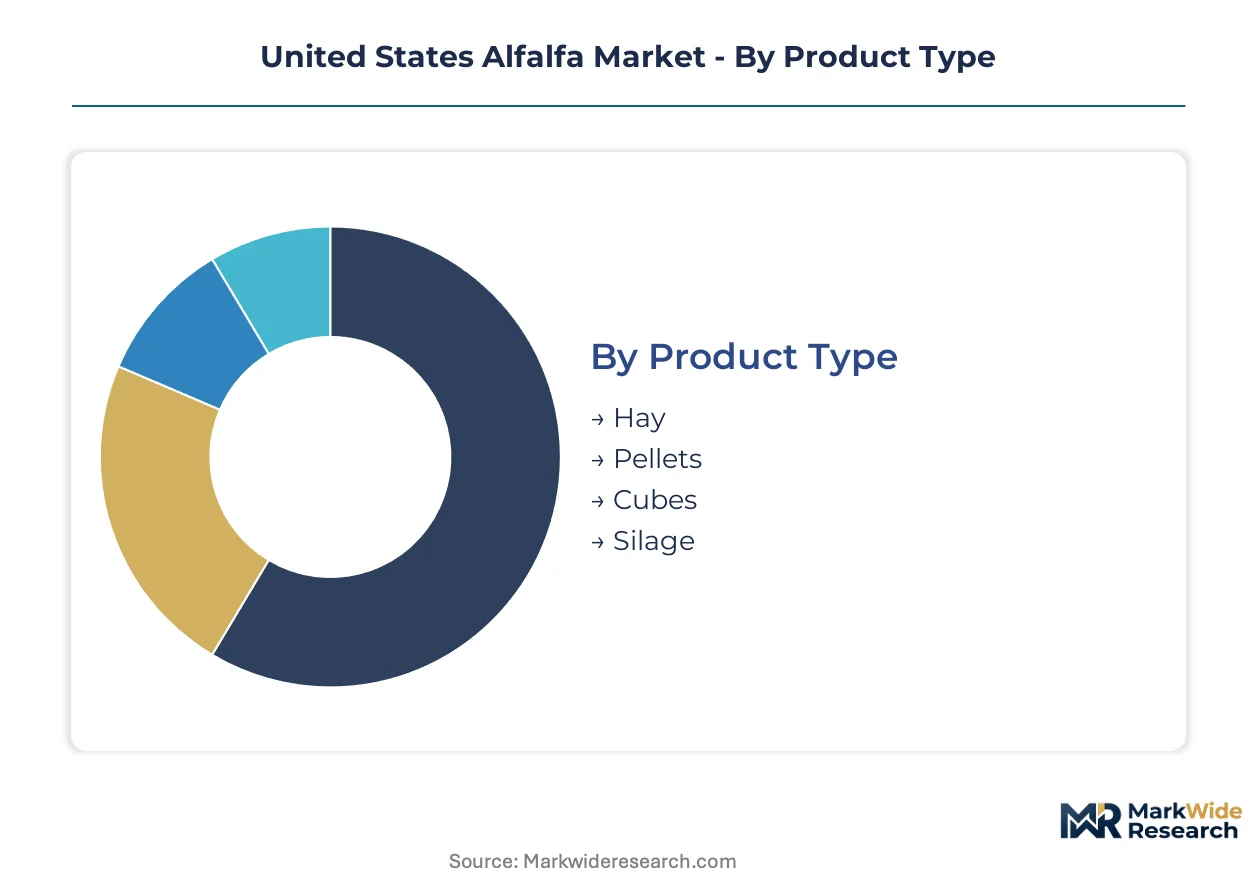
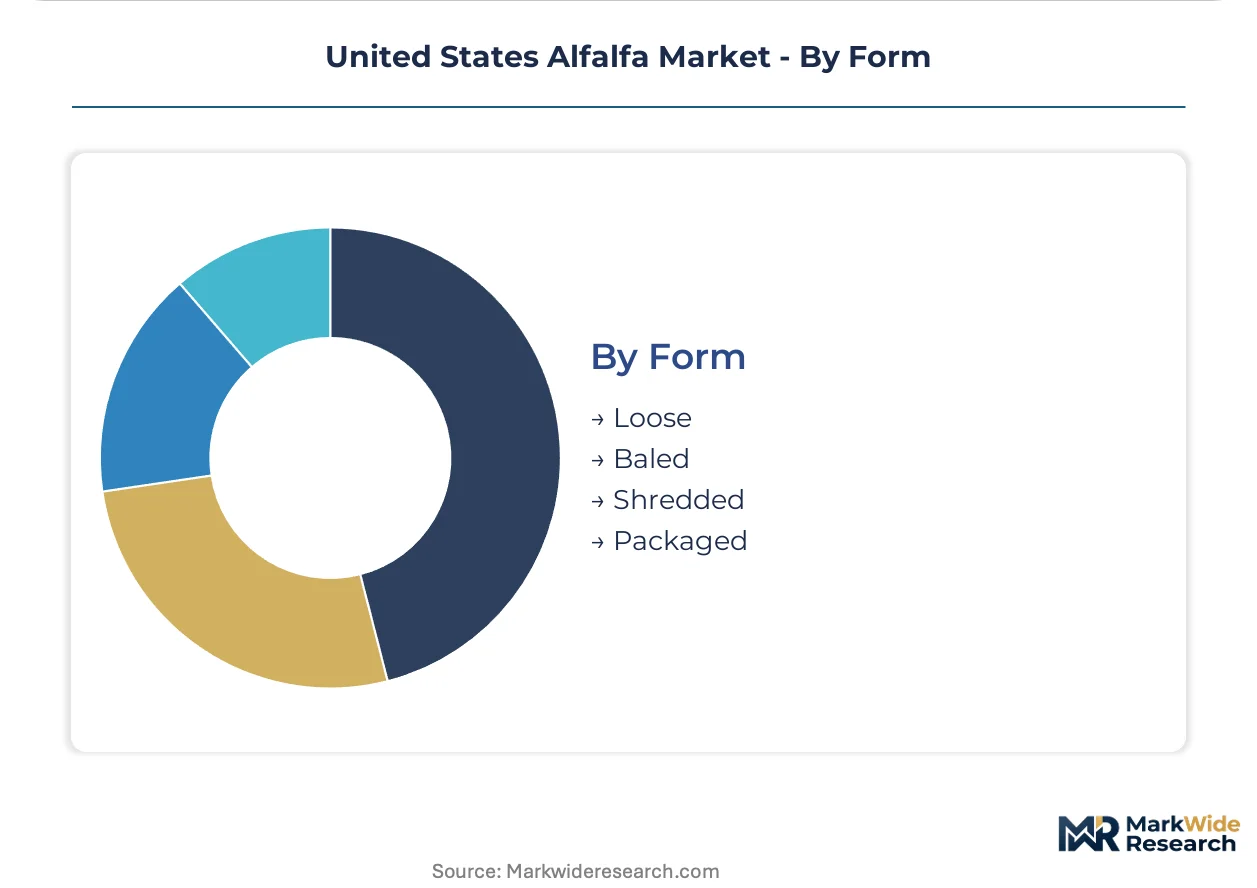
Alfalfa suppliers structure operations around four distinct segmentation axes. Product format determines processing investment and margin capture. Distribution channel shapes customer relationships and working capital requirements. End-user nutrition specifications drive harvest timing and quality premiums. Physical form dictates logistics infrastructure and geographic reach.
Product Type:
Dairy nutritionists and equine owners diverge sharply in their willingness to pay for processing convenience and nutrient standardization.
- Hay:Field-cured bales containing 15-22% crude protein on a dry-matter basis dominate dairy farm feeding protocols across Wisconsin and California. Bulk handling infrastructure at cooperative feed mills reinforces hay's position as the default volume format for large-scale ruminant operations.
- Pellets:Compressed cylinders produced via high-temperature dehydration achieve uniform nutrient density and reduced feeding waste. Pet owners and specialty livestock segments in suburban markets absorb price premiums for bagged convenience and storage stability.
- Cubes:Dense blocks suit automated feeding systems and export containers requiring minimal moisture content. Idaho processors supply Pacific Rim markets through Long Beach port infrastructure.
- Silage:Fermented high-moisture product serves integrated dairy operations with on-farm bunkers and anaerobic storage capacity. Upper Midwest cooperatives specify silage for herd transition diets.
Hay leads volumes today; pellets are gaining share fastest among non-dairy segments.
Distribution Channel:
Channel selection reflects buyer scale, specification complexity, and the value placed on advisory services alongside physical delivery.
- Wholesale:Volume contracts between hay presses and dairy cooperatives specify certified crude protein, acid detergent fiber, and relative feed value. California's Central Valley processors consolidate procurement through qualified supplier lists.
- Retail:Agricultural supply stores and feed dealers stock packaged formats for equine owners and small livestock operations. Staff nutrition advice differentiates independent dealers from commodity brokers.
- Online:Direct-to-farm e-commerce platforms connect Idaho and Washington producers with hobby farmers and horse owners seeking palletized delivery. Subscription auto-ship programs capture recurring revenue.
- Direct Sales:Large dairy operations contract directly with growers for standing crop or scheduled harvest slots. These arrangements bypass broker margins and lock in traceability documentation for FSMA compliance.
Wholesale channels dominate tonnage; online distribution is expanding most quickly in customer acquisition.
End User:
Nutritional specification intensity and regulatory exposure vary dramatically across buyer categories.
- Dairy Farmers:Ration formulators at cooperatives like Land O'Lakes and California Dairies specify early-bloom harvest protocols to maximize digestible energy. Milk production per cow drives willingness to pay for premium-grade forage.
- Livestock Feeders:Beef backgrounding operations in the Great Plains blend alfalfa with corn silage and distiller's grains. Cost per unit of gain determines sourcing decisions.
- Pet Owners:Equine enthusiasts and small-scale livestock keepers prioritize low-dust, mold-free product in convenient packaging. Brand reputation and veterinary recommendations influence purchasing.
- Exporters:Japanese and South Korean importers demand phytosanitary certification and moisture-consistent cubes. USDA Animal and Plant Health Inspection Service protocols govern shipment eligibility.
Dairy farmers absorb the largest tonnage; exporters are climbing the fastest as Pacific Rim demand hardens.
Form:
Physical configuration determines equipment compatibility, labor requirements, and storage economics at the point of consumption.
- Baled:Rectangular and round bales compatible with existing farm loaders and feed wagons dominate commercial dairy operations. Density and twine specification vary by regional handling equipment.
- Packaged:Shrink-wrapped bales and bagged pellets suit retail channels and hobby farms lacking bulk handling infrastructure. Shelf presence and label claims drive positioning.
- Loose:Chopped hay delivered by forage wagons serves specialized equine facilities and small ruminant operations. Dust suppression and leaf retention determine quality perception.
- Shredded:Flaked product accelerates dry-down and suits blending operations requiring rapid hydration. Limited commercial penetration outside custom feed mills.
Baled form anchors physical logistics; packaged formats are expanding most quickly through retail and e-commerce channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward states with favorable groundwater adjudication and EQIP cost-share eligibility, creating compliance-driven geographic sorting across the Western United States. Dairy processor consolidation in California intensifies supplier qualification requirements, while Idaho and Washington leverage export infrastructure for Pacific Rim access.
California
Dairy density in the Central Valley sustains the nation's largest alfalfa offtake, with processors specifying early-bloom harvest protocols for milk production optimization. Sustainable Groundwater Management Act cutbacks force acreage abandonment in overdrafted subbasins, accelerating well-deepening investments among remaining operators. Fresno and Tulare counties concentrate dehydration facilities serving both domestic dairy and export cube markets.
Idaho
Snake River Plain irrigation districts supply consistent water access for high-temperature drying operations targeting Japanese and South Korean phytosanitary standards. USDA NRCS Environmental Quality Incentives Program payments support precision pivot upgrades that document per-ton water savings for basin compliance. Idaho Falls and Twin Falls anchor vertically integrated production from field through packaged retail formats.
Washington
Columbia Basin Project water rights enable large-scale hay presses with direct Long Beach port access for containerized cube shipments. State Department of Agriculture export certification programs align with USDA APHIS protocols for Pacific Rim market entry. Grant County and Adams County concentrate dehydration capacity serving dairy cooperatives and international traders simultaneously.
Wisconsin
Upper Midwest dairy expansion drives alfalfa acreage as a nitrogen-fixing rotation alternative to continuous corn silage. Land-grant university extension services bundle forage testing with ration-balancing software, creating subscription revenue beyond physical hay sales. Dane and Brown counties concentrate cooperative feed mills specifying certified crude protein and relative feed value metrics.
Minnesota
Conservation Reserve Program incentives encourage alfalfa integration into corn-soy rotations for soil health benchmarking and synthetic fertilizer reduction. Private laboratories in the Red River Valley monetize administrative expertise for NRCS program navigation as a standalone advisory service. Otter Tail and Wilkin counties lead acreage expansion among dairy farmers displacing soybean meal with homegrown forage protein.
United States Alfalfa Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated producers capturing premium positioning in retail formats while commodity brokers dominate bulk dairy procurement. The vendor base concentrates among Western hay presses with captive dehydration capacity and Midwestern cooperatives leveraging testing-advisory bundles. Three archetypes prevail: vertically integrated field-to-package operators, export-grade certification specialists, and nutrition-consulting bundlers. Capacity consolidation and FSMA traceability compliance represent the dominant competitive moves reshaping supplier-processor relationships.
Among integrated Western producers, Standlee Premium Products and Anderson Hay & Grain exemplify divergent positioning strategies within the same geographic cluster. Standlee occupies the retail-format tier with packaged pellet and cube distribution through agricultural supply chains. Anderson represents the export-certification archetype, leveraging Pacific Northwest port access for Pacific Rim market penetration. Bailey Farms International anchors the California dairy corridor with consistent high-temperature-dried product specifications. These three illustrate how dehydration infrastructure and channel selection determine margin capture within the same commodity base.
| Leading Market Players |
|---|
| Al Dahra ACX Global |
| Bailey Farms International |
| Anderson Hay & Grain |
| Border Valley |
| Hay USA |
| Standlee Premium Products |
| SL Follen Company |
| Knight Ag Sourcing |
| Green Prairie International |
| Others |
Value Network & Pricing Analysis
Dairy processor consolidation in California's Central Valley is forcing hay suppliers to absorb certification and traceability costs that were previously brokered separately, compressing margins for non-integrated growers while rewarding operators with captive dehydration capacity. This procurement shift elevates price premiums for documented early-bloom harvest protocols and FSMA-compliant lot tracking, penalizing commodity hay presses lacking enterprise software systems.
Pricing Analysis
Distributor margins in wholesale dairy procurement typically run thinner than retail markups on packaged pellets and cubes, where bagged convenience commands substantial premiums from equine owners and small-scale livestock keepers. Three-tier pricing structure across premium, standard, and economy levels separates early-bloom certified hay with full traceability documentation from field-cured standard grades and uncertified commodity bales. Pricing pressure stems from diesel fuel and potassium fertilizer volatility that hay producers cannot fully pass through under annual supply contracts. Large dairy cooperatives exhibit lowest price sensitivity due to milk production optimization mandates, while beef backgrounding operations in the Great Plains drive hardest bargaining on cost-per-unit-of-gain metrics.
Supply Chain Analysis
High-temperature dehydration equipment and precision irrigation infrastructure draw from specialized manufacturers concentrated in California, Idaho, and Washington, with Snake River Plain operators anchoring domestic supply of export-grade cube production. Critical inputs include diesel fuel for field operations, potassium fertilizer for yield maintenance, and twine or net wrap for bale integrity. Single-source vulnerability runs through groundwater basin allocations governed by Sustainable Groundwater Management Act cutbacks that could force abrupt acreage abandonment. Distribution runs through Pacific Northwest port infrastructure for Pacific Rim export markets, cooperative feed mill networks for Upper Midwest dairy concentration, and direct-to-farm e-commerce channels for retail-format growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States alfalfa market functions as a stable compounder anchored by irreplaceable forage demand from dairy operations optimizing milk production per cow through precision nutrition.
For Market Incumbents: Cement defensive positioning through backward integration into captive dehydration capacity and precision irrigation infrastructure that documents water savings for basin compliance. Secure early-bloom harvest slot contracts with consolidated California dairy processors before independent laboratories displace traditional broker relationships entirely. Threat substitution by corn silage intensifies in large-scale operations prioritizing total mixed ration simplicity, requiring incumbents to emphasize protein content and digestibility advantages in cooperative nutritionist engagements. For New Entrants and Emerging Players: Begin with subscription-based forage testing and NRCS program navigation services in Wisconsin and Minnesota, where dairy expansion and Conservation Reserve Program incentives create advisory demand exceeding current laboratory capacity. Target online distribution of packaged pellets and cubes to equine owners and hobby farmers through agricultural supply store partnerships and auto-ship subscription models. Go-to-market leverage rests on bundling laboratory analysis with ration-balancing software that creates recurring revenue beyond physical hay sales. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated Western hay presses combining Snake River Plain water access with Long Beach port infrastructure for Pacific Rim export certification. Long-term viability frames around operators capable of meeting escalating FSMA traceability requirements without broker intermediation. Watch for Sustainable Groundwater Management Act enforcement acceleration in California's Central Valley as inflection indicator that would concentrate production among capitalized Idaho and Washington operators with documented conservation compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Irrigation Infrastructure Deployment | Variable-rate systems with soil moisture probes enable documented water savings for USDA NRCS EQIP eligibility and basin allocation compliance. |
| High-Temperature Dehydration Capacity Expansion | Idaho and Washington processors achieve moisture-consistent cubes meeting Japanese and South Korean phytosanitary standards for Pacific Rim access. |
| Subscription Nutrition Consulting Launch | Wisconsin and Minnesota laboratories bundle forage testing with ration-balancing software, displacing traditional hay broker advisory services. |
| FSMA Traceability System Implementation | Lot tracking and hazard analysis documentation satisfies FDA Food Safety Modernization Act requirements for dairy processor supplier qualification. |
| Retail Packaged Format Development | Compressed pellets and bagged cubes target equine owners through agricultural supply stores and direct-to-farm e-commerce channels. |
Research Methodology
Bottom-up dairy nutrition optimization modeling reconciled against top-down hay press and dehydration facility tracking forms the analytical core of this study. Primary interviews with dairy cooperative nutritionists, hay press operations managers, NRCS conservation planners, forage testing laboratory directors, and agricultural supply store buyers combined with secondary validation from USDA NASS crop production reports, FDA FSMA guidance documents, state groundwater basin adjudication records, and cooperative feed mill procurement disclosures. Triangulation across stakeholder perspectives and documentary sources ensures coverage of both supply-side capacity decisions and demand-side specification evolution.
Historical acreage, yield, and pricing trendlines anchor projection modeling across the analysis window, with segmentation by product format, distribution channel, end-user category, and physical form. Modeled dimensions include hay versus pellets versus cubes versus silage, wholesale versus retail versus online versus direct sales, dairy farmers versus livestock feeders versus pet owners versus exporters, and baled versus packaged versus loose versus shredded configurations. CAGRs derive from regression analysis of planted acreage response to protein feed cost ratios, irrigation allocation constraints, and export demand elasticity. Industry-specific forecast inputs incorporate Sustainable Groundwater Management Act implementation pace and Pacific Rim phytosanitary protocol evolution.
Caveats apply where drought-response policy acceleration, fertilizer price spikes, or corn silage substitution trends could materially shift the outlook for alfalfa acreage and pricing. Forecasts reflect assumptions regarding dairy herd stability, groundwater basin adjudication enforcement consistency, and export certification continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Europe Guar Market
Agriculture and Agri Products
United Arab Emirates Poultry Meat Market
Agriculture and Agri Products
Feed Grade Oils Market
Agriculture and Agri Products
Italy Compound Feed Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Sorghum by-Products Market
Agriculture and Agri Products
Poultry and Eggs Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
United Kingdom Compound Feed Market
Agriculture and Agri Products
Date Palm Market