
 North America Haying and Forage Machinery Market | 2026-2036
North America Haying and Forage Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Haying and Forage Machinery Market Analytics
Canadian Prairie manufacturers of haying equipment is expanding production lines to serve North American demand for high-capacity balers and self-propelled windrowers. Deere & Company anchors its position through precision agriculture integration and extensive dealer networks across the U.S. Midwest. AGCO Corporation differentiates via Fendt and Massey Ferguson brand portfolios targeting custom operators and large-scale producers. CNH Industrial competes through Case IH and New Holland product lines with strong haytools specialization.
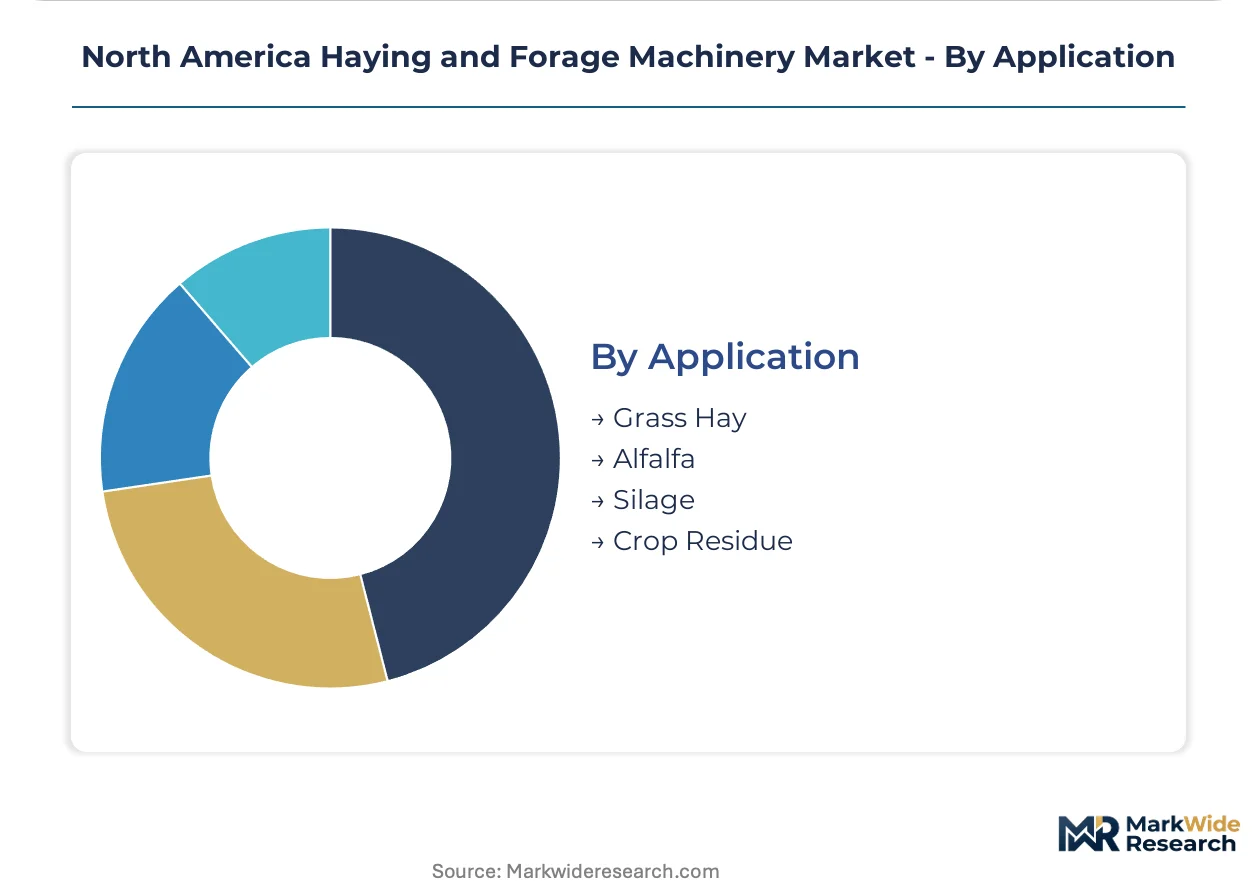
North America haying and forage machinery encompasses equipment designed to cut, condition, rake, bale, and handle forage crops with operating widths ranging from ten to forty feet and baling densities exceeding two hundred kilograms per cubic meter for optimized transport and storage. The primary commercial purpose centers on preserving nutritional value of grass hay, alfalfa, and silage for dairy, beef, and equine feed rations. Balers command the largest product type share as large square and round configurations dominate commercial operations seeking density and weather resilience. Mowers represent the fastest-growing product category as disc and sickle-bar designs advance cutting speed and fuel efficiency. Application demand clusters in silage and alfalfa segments where dairy operations prioritize moisture-controlled harvest windows and rapid field-to-bunker logistics.
EPA Tier 4 Final emissions compliance shapes engine procurement costs and retrofit timelines for equipment fleets across the United States. Health Canada and the Canadian Environmental Protection Act impose parallel exhaust standards affecting cross-border equipment certification and import protocols. USDA conservation programs and Farm Service Agency cost-share incentives influence producer upgrade decisions and machinery replacement cycles. Stakeholders must monitor evolving particulate matter thresholds and precision agriculture data standards as regulatory and technological frameworks converge on equipment interoperability and emissions verification.
Market Dynamics
EPA Tier 4 Final emissions compliance is compressing replacement cycles across the United States while Canadian Prairie dairy consolidation accelerates demand for high-capacity baler fleets.
Growth Catalysts
- USDA Conservation Reserve Program:Cost-share incentives under the Farm Service Agency accelerate machinery upgrades among Great Plains operators replacing aging mower-conditioners.
- Dairy herd consolidation:Large-scale Wisconsin and Minnesota operations invest in self-propelled windrowers to compress harvest windows and preserve alfalfa nutritional value.
- Precision agriculture integration:Yield mapping and moisture-sensing balers enable variable-density bale production for optimized transport logistics.
Market Restraints
- Engine certification costs:EPA Tier 4 Final particulate matter thresholds add procurement premiums to diesel-powered windrowers and self-propelled harvesters.
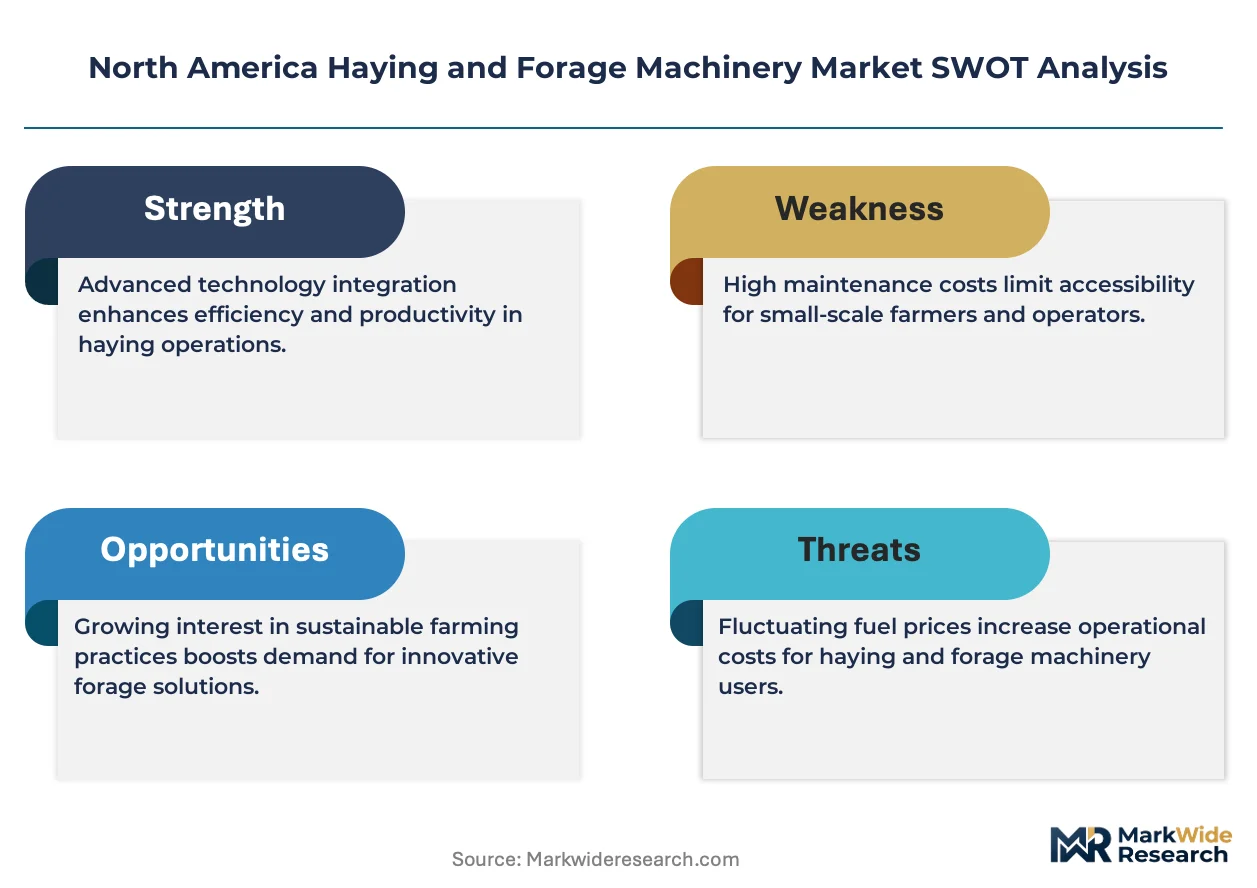
- Steel and aluminum volatility:Input cost swings for baler chamber components compress manufacturer margin stability across production cycles.
- Dealer network concentration:Equipment distribution concentrates through manufacturer-captive channels in the U.S. Corn Belt, limiting price transparency for independent buyers.
Strategic Opportunities
- Manitoba-Saskatchewan expansion:Underpenetrated haying equipment density among expanding Canadian beef operations creates white space for large-square baler deployment.
- Silage additive systems:Convergence of inoculant application technology with forage harvesters enables bundled equipment-chemistry offerings for dairy nutrition optimization.
- Rental and lease channels:Custom operators in Texas and Oklahoma increasingly access high-capacity equipment through seasonal rental rather than ownership.
Industry Challenges
- Diesel technician scarcity:EPA Tier 4 Final after-treatment systems require specialized service capabilities that dealer networks struggle to staff across rural Nebraska and Kansas.
- Precision agriculture integration complexity:Legacy balers lack ISOBUS compatibility, forcing retrofit costs or premature replacement for data-connected fleet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Haying and Forage Machinery Market |
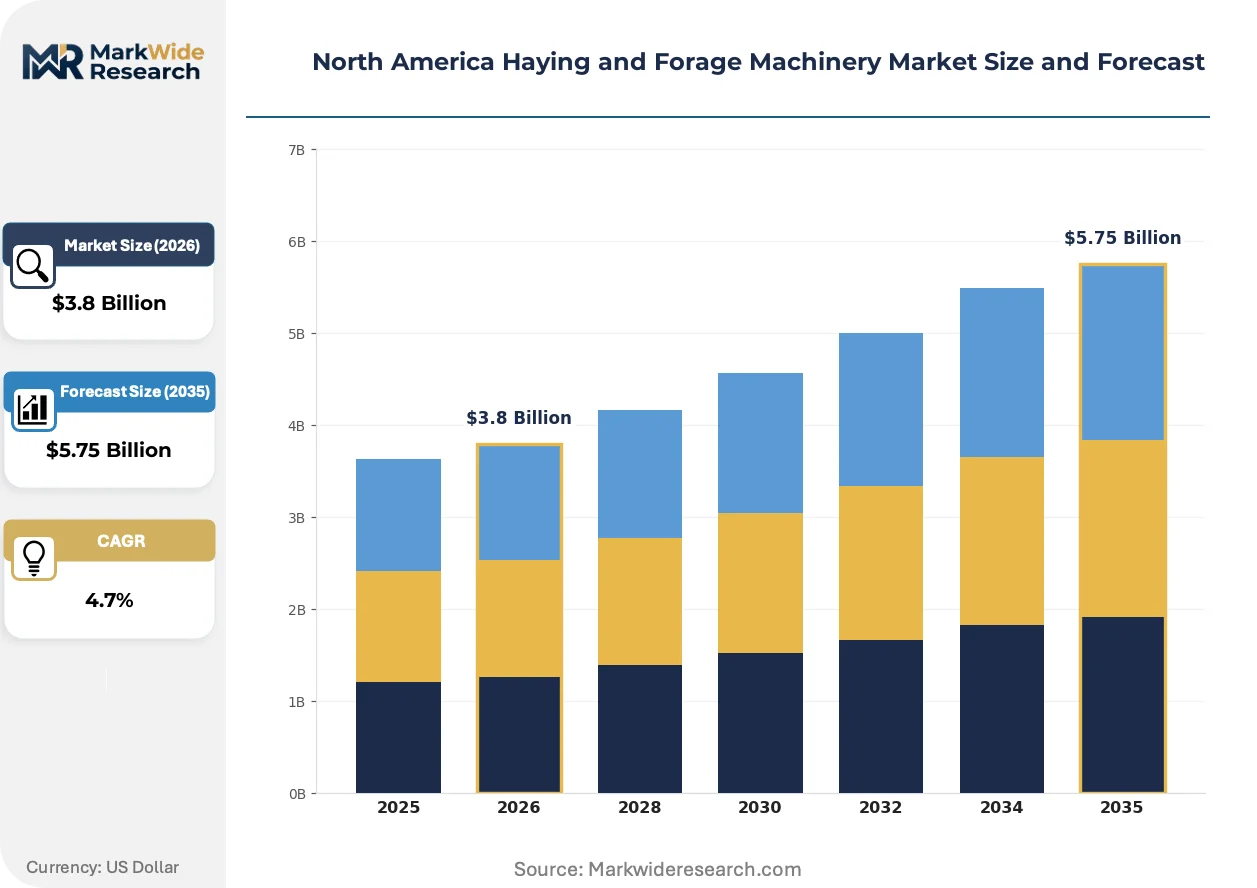
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balers, Mowers, Rakes, Tedders End User: Farmers, Agricultural Cooperatives, Large-Scale Producers, Custom Operators Technology: Conventional, Round, Square, Variable Chamber Application: Grass Hay, Alfalfa, Silage, Crop Residue |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, CLAAS Group, Kubota Corporation, Kuhn Group, Vermeer Corporation, Krone North America, Farm King, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Haying and Forage Machinery Market Evolving Landscape
Equipment intelligence and emissions architecture are converging to redefine competitive differentiation across North American haying operations.
Intelligent baling systems with real-time moisture sensing and density feedback are unifying harvest data with feed management software. Large-scale Alberta dairy cooperatives adopt these systems fastest, replacing manual sampling protocols. The technology is unifying field operations with nutrition planning, compressing the historical separation between harvest and ration formulation.
Health Canada and the Canadian Environmental Protection Act impose exhaust standards parallel to EPA Tier 4 Final, creating cross-border certification harmonization pressure. Equipment manufacturers face dual compliance testing for engines above 56 kW. The Prairie provinces experience accelerated fleet turnover as producers align with both jurisdictions.
Custom operator contracting is displacing traditional ownership models among mid-scale Texas Panhandle beef producers. Third-party harvest services now supply 40% of regional baling capacity, fragmenting equipment procurement decision-making. Oklahoma and Kansas exhibit the sharpest shift toward outsourced forage logistics.
North America Haying and Forage Machinery Market Segmentation
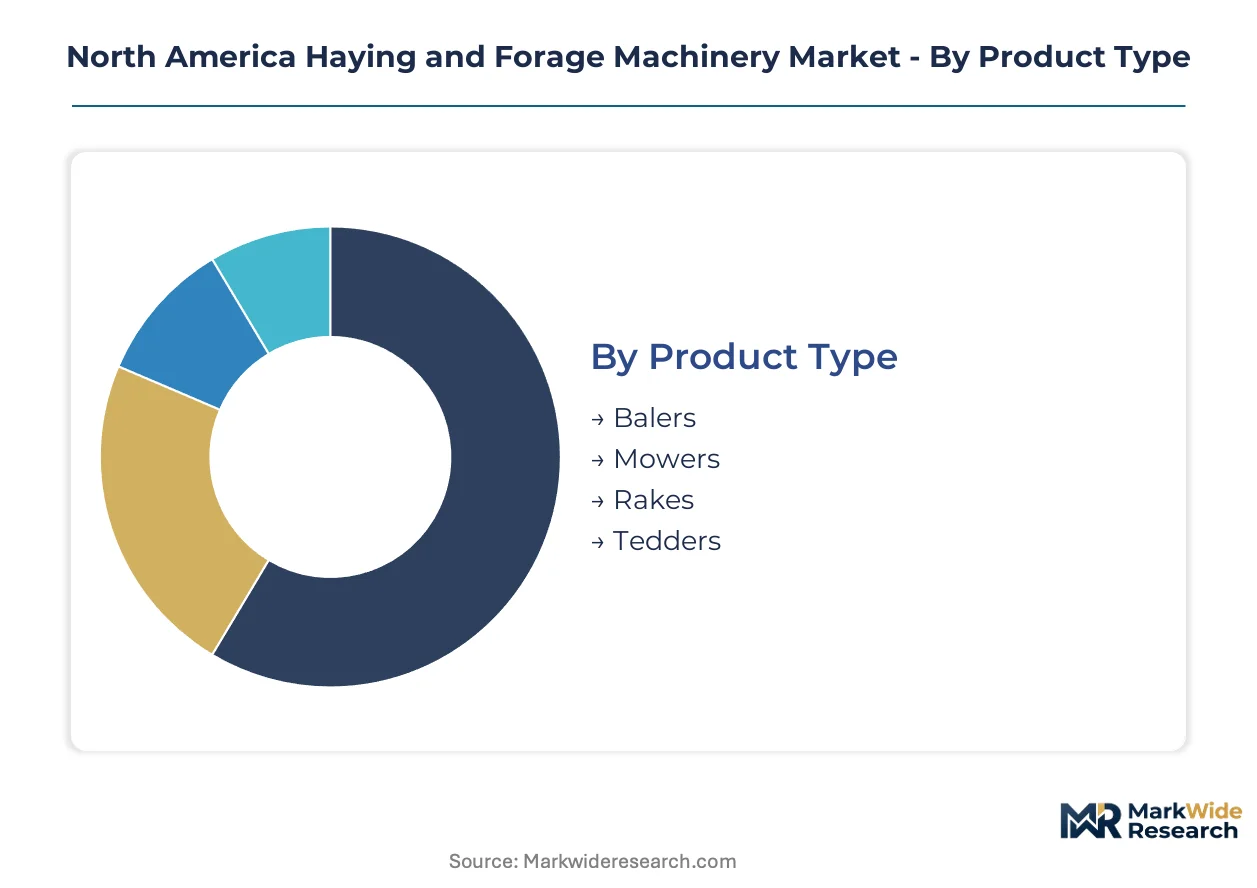
Equipment specification and operational scale create distinct procurement patterns across North American haying operations. Segmentation reveals where capital concentrates and which configurations command premium positioning.
Product Type:
Balers concentrate manufacturing capacity and aftermarket parts revenue, while mower development absorbs the largest R&D allocation among haytools categories.
- Balers:Large square and round configurations dominate commercial procurement, with chamber densities exceeding two hundred kilograms per cubic meter for optimized transport. Wisconsin and Minnesota dairy operations drive replacement demand as moisture-sensing and variable-density systems become standard specifications.
- Mowers:Disc and sickle-bar designs are advancing cutting speed and fuel efficiency through precision blade geometry. Texas Panhandle custom operators are expanding mower-conditioner fleets to capture outsourcing demand from mid-scale beef producers.
- Rakes:Rotary and wheel rake configurations serve distinct windrow formation requirements across varying crop conditions.
- Tedders:Spreading equipment for moisture management sees concentrated demand in humid harvest zones of the upper Midwest.
Balers absorb the bulk of installed capacity; mowers are expanding most quickly.
End User:
Customer scale determines equipment specification complexity and financing structure across the procurement base.
- Large-Scale Producers:Operations exceeding five hundred acres deploy self-propelled windrowers and high-capacity baler fleets with integrated precision agriculture systems. Alberta dairy cooperatives are fastest to adopt intelligent baling with real-time density feedback.
- Custom Operators:Third-party harvest services now supply forty percent of regional baling capacity in Oklahoma and Kansas, creating fragmented procurement decision-making and seasonal rental channel growth.
- Farmers:Owner-operators in the U.S. Corn Belt prioritize ISOBUS-compatible equipment for fleet interoperability.
- Agricultural Cooperatives:Shared equipment pools in Manitoba and Saskatchewan spread capital costs across member operations.
Large-scale producers dominate capital deployment; custom operators are gaining share fastest.
Technology:
Chamber geometry and density control mechanisms differentiate price tiers and application suitability.
- Variable Chamber:Adjustable bale diameter and density settings enable single-machine flexibility across crop types and moisture conditions. Canadian Prairie beef operations are adopting these systems to reduce fleet specialization requirements.
- Large Square:Fixed-chamber high-density configurations optimize long-distance transport logistics for commercial hay exporters.
- Round:Weather-resistant wrapping and handling characteristics dominate on-farm storage applications.
- Conventional:Standard-density fixed-chamber designs serve replacement demand in cost-sensitive segments.
Variable chamber technology captures the steepest expansion trajectory; large square configurations anchor commercial hay logistics.
Application:
Crop-specific moisture and nutritional requirements dictate harvest timing equipment and conditioning intensity.
- Silage:Moisture-controlled harvest windows require rapid field-to-bunker logistics and specialized inoculant application systems. Dairy operations in the U.S. Corn Belt prioritize self-propelled harvesters with integrated additive technology.
- Alfalfa:Leaf retention and nutritional preservation drive conditioning intensity and windrow management specifications. Wisconsin and Minnesota operations invest most heavily in precision moisture sensing.
- Grass Hay:Volume-oriented production for equine and beef markets emphasizes throughput over density optimization.
- Crop Residue:Post-grain harvest collection for bedding and feed supplements creates secondary equipment demand in corn and wheat regions.
Silage applications command the highest equipment specification intensity; alfalfa harvest systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Alfalfa-growing regions across the Great Plains and Canadian Prairies anchor equipment demand for high-density balers and self-propelled windrowers. Dairy herd consolidation in Wisconsin and Minnesota compresses harvest windows and accelerates machinery replacement cycles. Cross-border regulatory alignment between EPA and Health Canada shapes engine certification and fleet standardization.
United States
Wisconsin and Minnesota dairy operations drive demand for moisture-sensing balers with variable-density chambers. EPA Tier 4 Final emissions standards compress replacement timelines for diesel-powered windrowers across Nebraska and Kansas. The Texas Panhandle exhibits rapid growth in custom operator contracting, with third-party harvest services now supplying substantial regional baling capacity.
Canada
Alberta dairy cooperatives adopt intelligent baling systems with real-time density feedback faster than other provinces. Health Canada and the Canadian Environmental Protection Act impose exhaust standards parallel to EPA Tier 4 Final, creating dual compliance testing requirements. Manitoba and Saskatchewan present underpenetrated haying equipment density among expanding beef operations seeking large-square baler deployment.
Mexico
Northern Mexico's dairy belt in Chihuahua and Sonora generates demand for imported used equipment from U.S. fleets. The Secretariat of Environment and Natural Resources implements emissions protocols affecting cross-border machinery trade. Bajío region feedlot operations increasingly source high-capacity balers through dealer networks extending from Texas border states.
North America Haying and Forage Machinery Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue precision agriculture integration and rental channel expansion. The market structure concentrates around full-line manufacturers with captive dealer networks and specialized haytool producers with regional fabrication expertise. Three archetypes dominate: diversified agricultural equipment conglomerates with precision technology platforms, mid-scale specialists focused on baler and windrower engineering, and regional fabricators serving cost-sensitive replacement demand. Competitive moves center on precision agriculture data interoperability and seasonal rental channel development.
Among diversified equipment manufacturers, Deere & Company and AGCO Corporation exemplify the precision-integrated archetype through extensive dealer networks and brand portfolio breadth. CNH Industrial occupies a position spanning both full-line agricultural equipment and specialized haytools through multiple brand holdings. These three conglomerates represent the dominant competitive anchors, while specialized producers such as Vermeer Corporation and Krone North America sit within the dedicated haying equipment tier.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| CLAAS Group |
| Kubota Corporation |
| Kuhn Group |
| Vermeer Corporation |
| Krone North America |
| Farm King |
| Others |
Value Network & Pricing Analysis
Steel and aluminum price volatility for baler chamber components flows through three distinct pricing tiers, with premium manufacturers absorbing input swings through captive forging operations while standard-tier producers pass cost fluctuations to dealer networks.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium-tier manufacturers from unbundled economy offerings in the dealer channel. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 Final certification costs, precision agriculture integration depth, and geographic proximity to assembly plants. Pricing pressure stems from steel tariff exposure on imported chamber components, compressing margins for non-vertically integrated producers. Custom operators in Texas and Oklahoma exhibit highest price sensitivity due to seasonal rental channel alternatives, while Wisconsin dairy cooperatives prioritize specification over cost.
Supply Chain Analysis
High-strength steel supply rests on integrated mills in the United States, Germany, and Japan serving agricultural equipment fabricators. Hydraulic system components, precision sensors, and Tier 4 Final after-treatment hardware anchor upstream dependencies. Single-source vulnerability concentrates in DEF dosing systems and exhaust after-treatment modules from limited certified suppliers. Distribution runs through manufacturer-captive dealer networks across the U.S. Corn Belt, with independent retailers serving Canadian Prairie replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America haying and forage machinery sector is executing a technology-transition phase as ISOBUS-compatible intelligent baling systems displace legacy fixed-density equipment lacking data interoperability.
For Market Incumbents: To counter precision agriculture integration complexity forcing premature fleet replacement, Deere & Company and AGCO Corporation should deepen backward integration into sensor manufacturing and expand certified technician training programs across Nebraska and Kansas. Channel control through captive dealer networks remains the critical lever for defending service revenue attachment rates. For New Entrants and Emerging Players: Direct-to-farm digital sales platforms offer the lowest-friction entry vector for penetrating underpenetrated Manitoba and Saskatchewan beef operations seeking variable-chamber baler alternatives. White-space targets include seasonal rental channel partnerships with Oklahoma custom operators and silage additive system bundling for dairy nutrition optimization. For Investors and Strategic Acquirers: Accelerated fleet turnover in Alberta dairy cooperatives adopting real-time density feedback is the leading indicator that precision-integrated haytool specialists will command acquisition premiums over conventional manufacturers. Target acquisition archetypes include mid-scale baler engineering specialists with ISOBUS-native platforms and established Canadian Prairie distribution. Watch EPA particulate matter threshold adjustments and Health Canada harmonization delays as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Integration | ISOBUS-compatible balers unify harvest data with dairy nutrition software, compressing field-to-ration planning cycles. |
| Dealer Network Certification Investment | Tier 4 Final after-treatment service capabilities differentiate captive channels in rural Nebraska and Kansas. |
| Seasonal Rental Channel Development | Third-party harvest services in Texas and Oklahoma fragment traditional ownership-based procurement patterns. |
| Silage Additive System Bundling | Inoculant application technology convergence creates equipment-chemistry offerings for dairy operations. |
| Canadian Prairie Geographic Expansion | Large-square baler deployment targets underpenetrated beef operations in Manitoba and Saskatchewan. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with equipment dealership principals, dairy operation managers, custom harvest contractors, and aftermarket parts distributors. Bottom-up triangulation across product type, technology tier, and end-user segmentation converged with top-down validation against AEM shipment statistics and USDA machinery sales reports.
Granularity-level modeling deployed equipment-type unit economics at the state-province level, with technology adoption curves and replacement cycle dynamics projected across the analysis window. Segmentation dimensions included product category, chamber configuration, end-user scale class, and application-specific harvest requirements. CAGRs derived from historical shipment patterns, fleet age distribution analysis, and regulatory compliance timeline modeling.
The model holds under stable EPA-Health Canada regulatory alignment and moderate steel price volatility; deviation in emissions threshold acceleration or tariff regime shifts would compress replacement timelines and alter manufacturer margin structures. A small set of named triggers—particulate matter standard revisions, Prairie province dairy consolidation rates, and custom operator market share expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Machinery
Garden Tractor Market
Agricultural Machinery
Electric Tractors Market
Agricultural Machinery
Orchard Tractor Market
Agricultural Machinery
Agricultural Machinery Market
Agricultural Machinery
Europe Agricultural Machinery Market
Agricultural Machinery
Driverless Tractor Market
Agricultural Machinery
Brazil Agricultural Machinery Market
Agricultural Machinery
Germany Agricultural Tractor Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Machinery Market
Agricultural Machinery
Asia-Pacific Agricultural Tractors Market
Agricultural Machinery
United States Agricultural Tractor Market
Agricultural Machinery
Agriculture Drones Market
Agricultural Machinery
Australia Agricultural Machinery Market
Agricultural Machinery
Netherlands Hydrogen Powered Tractor Market
Agricultural Machinery
Turkey Agricultural Tractor Market
Agricultural Machinery
North America Plowing and Cultivating Machinery Market