
 Spain Table Grape Market | 2026-2036
Spain Table Grape Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Table Grape Market Insights
Pre-packaged clamshell configurations is repositioning buyer choice away from traditional open bunches in Spanish retail. Moyca Grapes SL leverages its Murcia-based operations to dominate the seedless segment for Northern European export. SNFL Group anchors its breeding programs in proprietary varietal development that sustains premium pricing across multiple seasons. AM Fresh Group controls extensive cold-chain infrastructure that differentiates its logistics capability from smaller competitors.
Table grapes are Vitis vinifera cultivars bred for fresh consumption rather than wine production, with berries typically harvested at 16-22°Brix soluble solids and packed within 24 hours to preserve stem freshness and shelf appeal. The fruit serves commercial channels ranging from supermarket produce aisles to food service salad bars and juice extraction lines. Seedless varieties capture the fastest growth trajectory as German and British retailers impose strict berry-size specifications that favor premium cultivars. Clamshell packaging commands higher margin pools than loose bunches by reducing shrinkage and extending retail display life. Local markets retain volume dominance in domestic Spanish consumption but face structural compression from supermarket consolidation in Madrid and Barcelona.
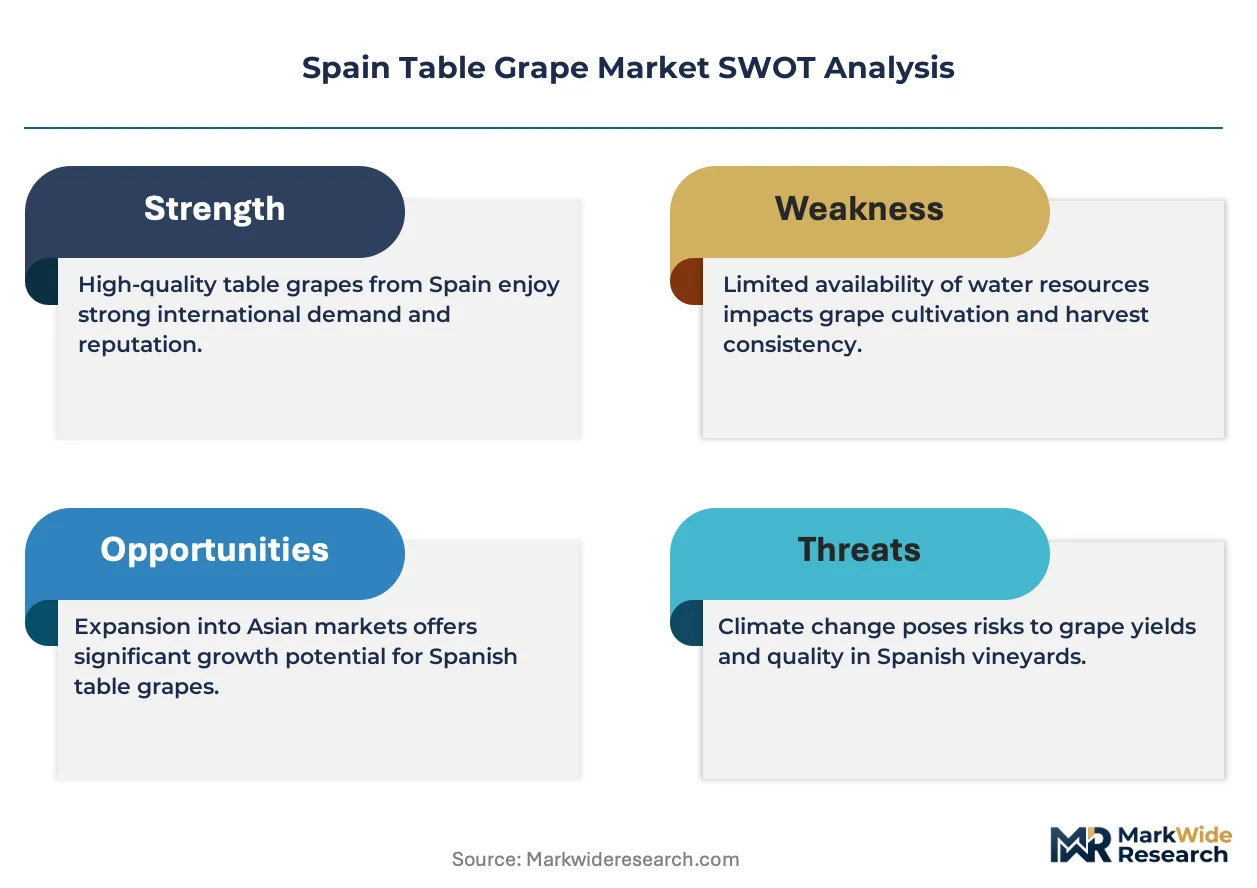
Spain's national food safety regulator enforces EU-wide Maximum Residue Limits under harmonized standards, while the Ministry of Agriculture coordinates export phytosanitary certification for third-country shipments. These frameworks shape grower spray programs, harvest timing decisions, and market access eligibility for non-EU destinations. Stakeholders must monitor evolving varietal registration rules and water-use restrictions in drought-prone growing zones to secure long-term production permits.
Market Dynamics
Pre-packaged clamshell configurations are restructuring retail procurement protocols across Spanish distribution channels, compressing traditional open-bunch formats while forcing upstream packhouse investments in automated weighing and sealing lines.
Growth Catalysts
- EU Maximum Residue Limits harmonization:EFSA-aligned enforcement creates export-ready certification pools that unlock German and British retail access for Andalusian growers.
- Seedless varietal breeding programs:Proprietary cultivar development accelerates berry-size consistency demanded by Northern European supermarket chains.
- Murcia cluster concentration:Coastal plains irrigation infrastructure supports extended harvest windows that stretch supply availability across traditional seasonal gaps.
Market Restraints
- Water allocation volatility:Drought-prone growing zones face Ministry of Agriculture restrictions that cap hectare expansion in Alicante and Almería provinces.
- Phytosanitary certification friction:Third-country export protocols impose documentation lag times that exclude Spanish producers from rapid-response spot markets.
- Substitute berry competition:Moroccan and Peruvian table grape volumes compete directly on shelf-price positioning in core export destinations.
Strategic Opportunities
- Food service channel penetration:Pre-portioned clamshell formats target hotel and catering salad-bar segments currently served by loose bulk supply.
- Cold-chain infrastructure gaps:Temperature-controlled consolidation hubs in Valencia and Huelva provinces enable direct-to-retailer bypass of traditional wholesale markets.
- Organic conversion subsidies:EU Common Agricultural Policy eco-scheme payments offset transition costs for growers shifting residue-dependent spray programs.
Industry Challenges
- Harvest labor availability:Seasonal picker shortages during peak August-September windows force accelerated mechanical harvesting investments that damage stem quality.
- Variety registration timelines:Spanish national catalog approval processes delay commercial deployment of new SNFL Group cultivars by 18-24 months against competitor access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Table Grape Market |
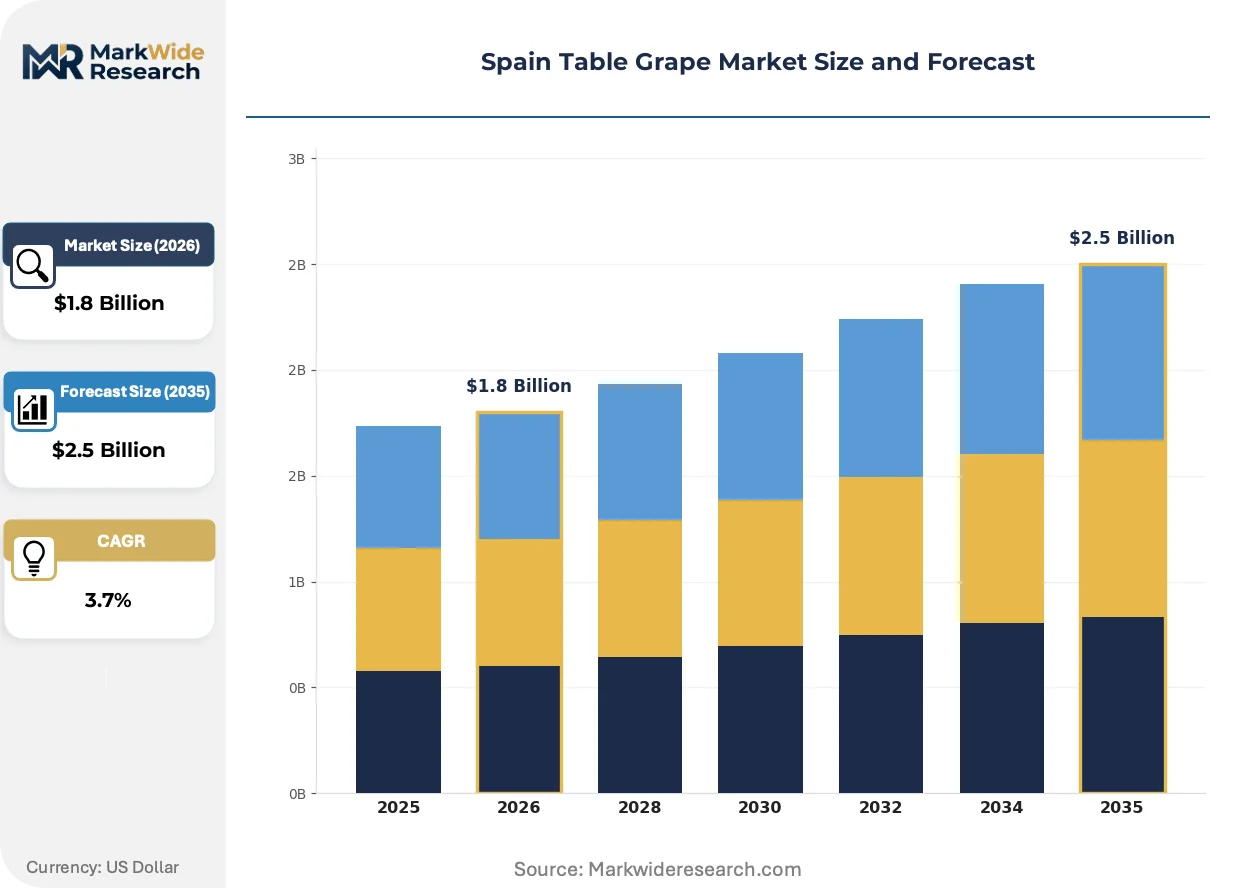
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Red Grapes, Green Grapes, Black Grapes, Seedless Grapes Distribution Channel: Supermarkets, Wholesale Markets, Online Retail, Local Markets Packaging Type: Bunched, Clamshell, Loose Pack, Tray Pack End User: Food Service, Retail Consumers, Juice Producers, Exporters |
| Companies Covered | Moyca Grapes SL, SNFL Group, International Fruit Genetics, El Ciruelo S.L., ITUM S.L., Sanlucar, APOEXPA, AM Fresh Group, Sunworld, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Table Grape Market Trends and Innovations
Packaging automation and residue-testing protocols are compressing traditional supply chain layers while redefining quality benchmarks across export-oriented production zones.
Spectral sorting technology is overtaking manual berry grading at packhouse level. German retail chains now mandate brix and diameter thresholds that optical scanners verify in real-time. This compression is eliminating labor-dependent quality control tiers while standardizing lot consistency for clamshell fulfillment.
EU Green Deal farm-to-fork targets are tightening pesticide reduction mandates that reshape spray program economics. Spanish growers face accelerated biological control adoption timelines to maintain EFSA residue compliance. Andalusian cooperatives are consolidating procurement of predatory mite colonies and pheromone disruption systems to spread transition costs.
Supermarket private-label consolidation is displacing traditional wholesale merchant intermediaries. Madrid and Barcelona retail banners now contract direct with Murcia-based grower associations for programmed volume commitments. This channel compression transfers price volatility risk downstream while capturing margin pools previously held by Mercamadrid traders.
Spain Table Grape Market Segmentation
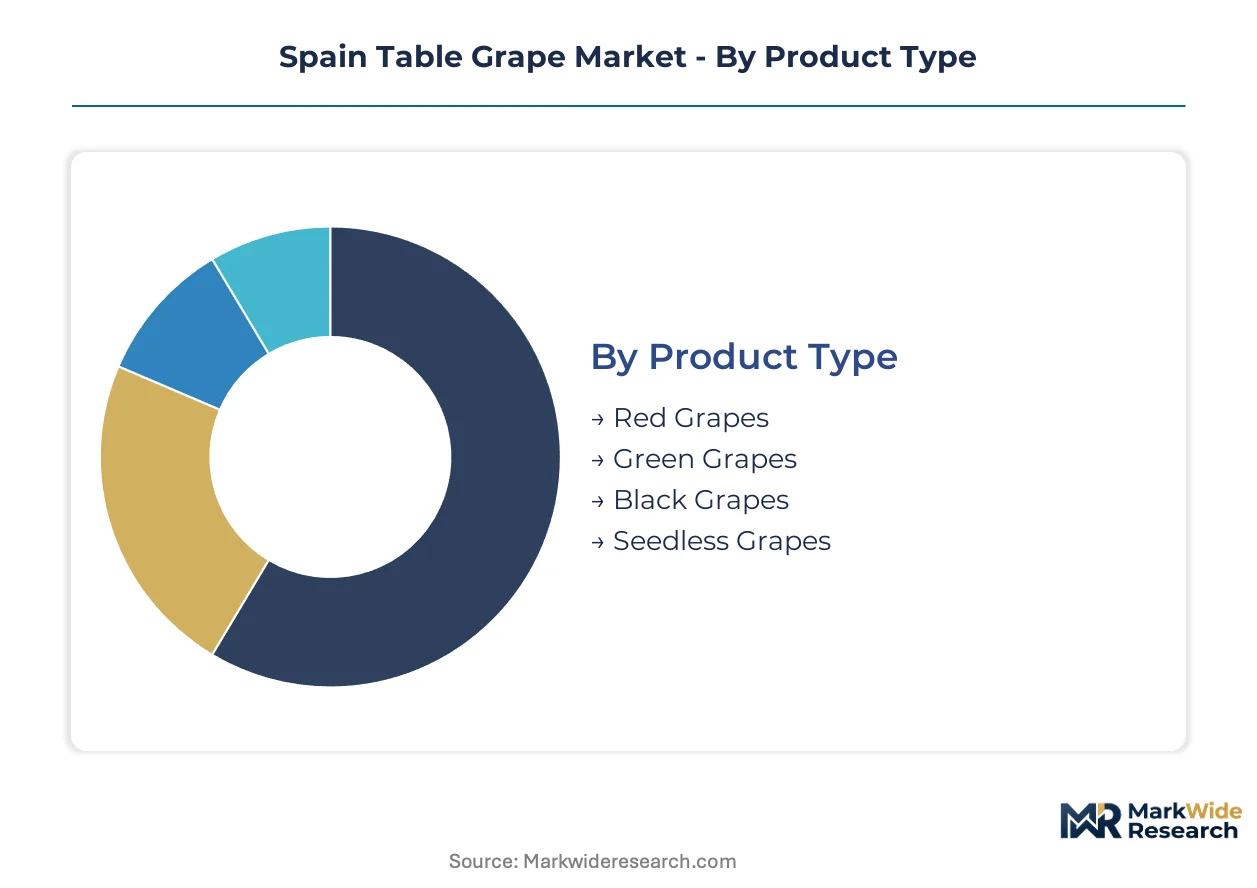
Spanish table grape segmentation reveals how varietal innovation, packaging automation, and channel consolidation are reshaping procurement economics. Growers and packhouses must align production configurations with the specific technical and commercial requirements of each segment tier to capture margin pools.
Product Type:
Upgrade cycles in Spanish vineyards are accelerating as growers replant legacy seeded varieties with proprietary seedless cultivars to meet Northern European retail specifications.
- Red Grapes:Crimson Seedless and Flame Seedless dominate this category, with berry diameters of 18-22mm required by German supermarket chains. Demand concentrates in Andalusia's coastal plains where extended harvest windows align with programmed retail supply contracts.
- Seedless Grapes:Proprietary SNFL Group cultivars command premium positioning through controlled licensing to Murcia-based grower associations. Replacement of traditional seeded acreage is proceeding fastest in Alicante province where water restrictions favor higher-value per-hectare returns.
- Green Grapes:Thompson Seedless and Superior Seedless varieties serve bulk juice extraction and mid-tier retail segments.
- Black Grapes:Midnight Beauty and Autumn Royal cultivars target specialty retail and food service channels with shorter seasonal availability.
Volume placements concentrate in Red Grapes; the faster expansion belongs to Seedless Grapes.
Distribution Channel:
Channel economics diverge sharply between consolidated retail procurement and fragmented wholesale liquidation, with margin capture favoring direct-contracting formats.
- Supermarkets:Mercadona, Carrefour España, and Lidl España operate programmed volume commitments with Murcia grower associations, bypassing traditional Mercamadrid intermediaries. EFSA-aligned residue documentation is mandatory for shelf placement.
- Wholesale Markets:Mercamadrid and Mercabarna still handle spot-market liquidation of secondary-grade fruit, though their volume share is compressing under retail consolidation.
- Online Retail:Amazon España and specialized fresh-produce platforms are gaining traction in urban delivery corridors.
- Local Markets:Municipal mercados and street vendors serve price-sensitive domestic consumers with minimal packaging overhead.
Procurement gravity is shifting toward Supermarkets; Online Retail is climbing the fastest among emerging channels.
Packaging Type:
Automation investments and retail shrinkage reduction are driving format substitution away from traditional open-bunch presentation.
- Clamshell:Pre-portioned 500g and 750g configurations with automated weighing and sealing lines reduce labor dependency and extend retail display life. German chains now mandate this format for premium seedless lines.
- Bunched:Traditional stem-on presentation persists in local markets and discount retail tiers where price positioning outweighs convenience premiums.
- Tray Pack:Modified-atmosphere formats target export logistics with extended shelf-life requirements.
- Loose Pack:Bulk bin configurations serve food service and juice processing channels with minimal handling overhead.
Shipments concentrate in Bunched formats; Clamshell is gaining share fastest as retail specifications tighten.
End User:
End-use specifications fragment across residue sensitivity, berry-size consistency, and volume-scale requirements.
- Retail Consumers:German and British supermarket chains impose strict diameter and brix thresholds that optical sorting technology verifies. AM Fresh Group's cold-chain infrastructure serves this segment with direct-to-retailer logistics.
- Exporters:Third-country shipments require phytosanitary certification from Spain's Ministry of Agriculture, with documentation lag times excluding producers from rapid-response spot markets.
- Food Service:Hotel and catering salad-bar segments are shifting toward pre-portioned clamshell formats from loose bulk supply.
- Juice Producers:Concentrate and NFC extraction lines accept secondary-grade fruit with lower cosmetic specifications.
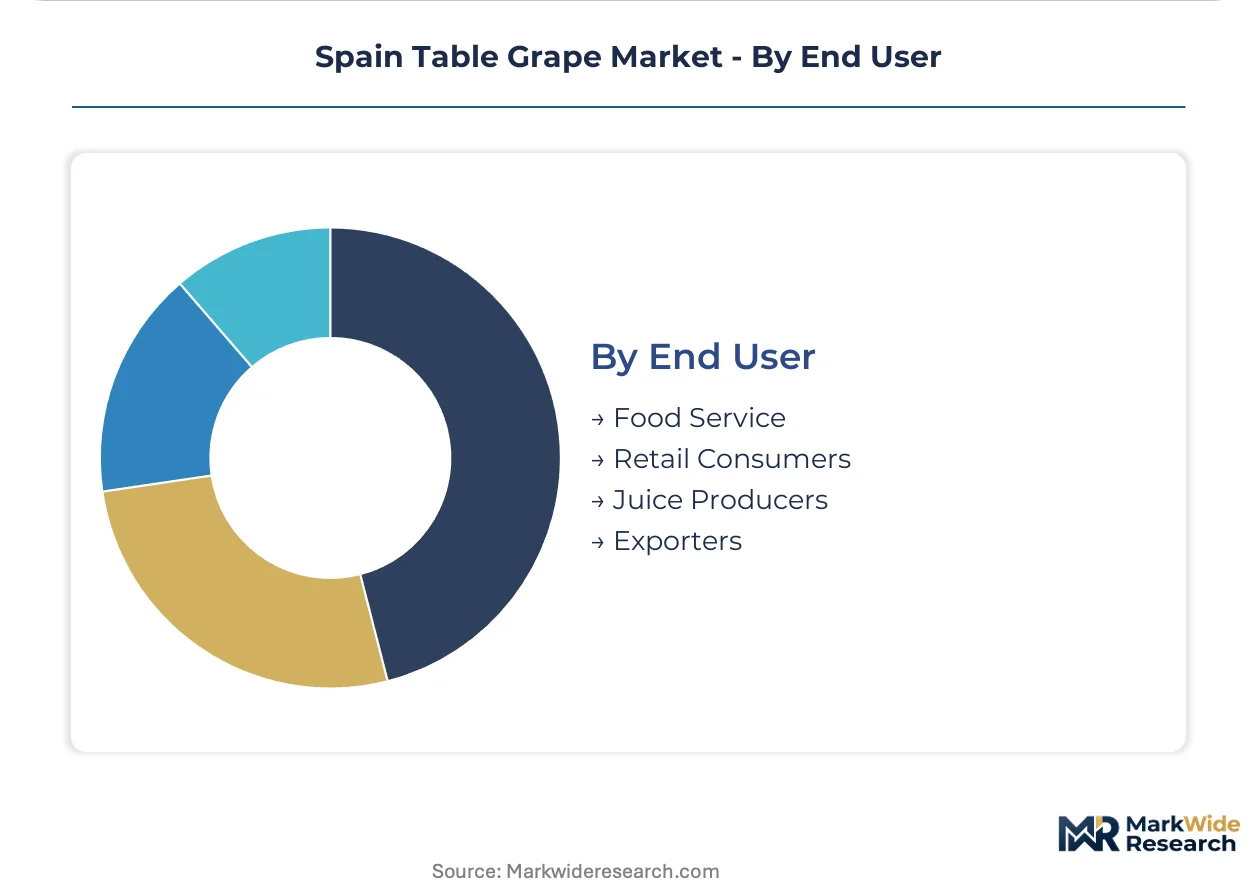
Volume concentrates with Retail Consumers; Food Service is expanding most quickly as clamshell penetration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's table grape production clusters around coastal irrigation zones and agri-export corridors, with regional specialization driving varietal differentiation and cold-chain investment patterns.
Andalusia
Coastal plains in Huelva and Almería provinces host the densest concentration of premium seedless cultivation, where EFSA-aligned residue protocols govern spray program timing. The Ministry of Agriculture coordinates export phytosanitary certification from regional inspection posts. Water allocation restrictions from the Guadalquivir River basin authority are compressing hectare expansion timelines for new vineyard plantings.
Murcia
Moyca Grapes SL anchors seedless grape export volumes from this southeastern cluster, supplying programmed commitments to German supermarket chains. EU Common Agricultural Policy eco-scheme payments are accelerating biological control adoption among cooperative members. The Campo de Cartagena irrigation district supports extended harvest windows through drip infrastructure investments.
Valencia
AM Fresh Group operates temperature-controlled consolidation hubs that bypass traditional wholesale intermediaries for direct-to-retailer logistics. The national food safety authority enforces Maximum Residue Limit compliance testing at Alicante province packhouses. Clamshell packaging automation lines are displacing open-bunch formats in export-oriented facilities.
Catalonia
Mercabarna wholesale market in Barcelona still handles spot-market liquidation of secondary-grade fruit, though retail consolidation is compressing volume share. Local municipal mercados serve price-sensitive domestic consumers with minimal packaging overhead. The Catalan agriculture department coordinates varietal registration support for SNFL Group cultivar trials.
Spain Table Grape Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Spain's table grape value chain, creating tiered competitive dynamics where scale-driven logistics operators confront varietal-breeding innovators. The vendor base fragments between integrated export houses controlling cold-chain infrastructure and cooperative associations aggregating smallholder output. Two strategic archetypes dominate: breeding-led IP holders commanding premium cultivar licensing, and logistics-integrated packhouses capturing margin pools through direct retail contracting. Capacity expansion in automated clamshell lines and backward integration into captive vineyard acreage represent the primary competitive vectors reshaping market structure.
Within the breeding-specialist tier, SNFL Group exemplifies proprietary varietal development strategies that sustain premium pricing across multiple seasons. Moyca Grapes SL and AM Fresh Group occupy positions as scale-driven export operators, with the former representing concentrated seedless production from Murcia-based facilities and the latter anchoring cold-chain differentiation through infrastructure control. These three entities collectively illustrate how intellectual property and logistics capability serve as alternative bases for competitive positioning in export-oriented fresh produce markets.
| Leading Market Players |
|---|
| Moyca Grapes SL |
| SNFL Group |
| International Fruit Genetics |
| El Ciruelo S.L. |
| ITUM S.L. |
| Sanlucar |
| APOEXPA |
| AM Fresh Group |
| Sunworld |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal farm-to-fork pesticide reduction mandates gate qualified supply access and premium-tier pricing for Spanish table grape exporters. Growers meeting EFSA-aligned residue thresholds capture German supermarket shelf placement at margin premiums, while non-compliant volumes liquidate through secondary channels at compressed returns.
Pricing Analysis
Margin tightening in the seedless segment reflects Moroccan and Peruvian import competition pressuring spot-market realizations. Three-tier pricing structure across premium clamshell, standard bunched, and economy bulk levels stratifies by certification grade and berry-size consistency. Cost-down pressure on mid-tier fruit accelerates because German retail chains now mandate optical-grade diameter thresholds. Juice extraction channels exhibit highest price sensitivity; direct-contract supermarket supply shows least elasticity due to programmed volume commitments.
Supply Chain Analysis
German supermarket procurement teams now mandate dual-source qualification across Murcia and Andalusia grower associations to mitigate harvest timing risk. Geographic supply concentration centers on Spain's southeastern coastal provinces, with secondary sourcing from Morocco and Peru filling seasonal gaps. Raw material dependencies span drip irrigation infrastructure, predatory mite colonies for biological control, and automated clamshell packaging films. Single-source vulnerability concentrates in SNFL Group proprietary cultivar licensing. Distribution runs through temperature-controlled consolidation hubs in Valencia and Huelva that bypass traditional Mercamadrid wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's table grape sector is consolidating around backward integration into captive vineyard acreage as the primary competitive lever. Players controlling both breeding IP and cold-chain infrastructure capture margin pools inaccessible to fragmented cooperative competitors.
For Market Incumbents: Lock in long-term cultivar licensing agreements with SNFL Group before variety registration timelines compress competitor access. Acquire automated clamshell packaging capacity in Alicante province to defend against Moroccan volume encroachment on German retail contracts. Secure Ministry of Agriculture phytosanitary pre-certification pools to accelerate third-country export responsiveness.
For New Entrants and Emerging Players: Enter via food service channel white space in pre-portioned clamshell formats targeting hotel and catering salad-bar segments currently served by loose bulk supply. Exploit organic conversion subsidies under EU Common Agricultural Policy eco-schemes to offset transition costs in drought-prone Almería zones. Pursue direct-to-retailer logistics partnerships with Amazon España and specialized fresh-produce platforms.
For Investors and Strategic Acquirers: Accelerated consolidation of Murcia-based grower associations into Moyca Grapes SL-scale entities is the leading indicator that scale-driven logistics operators will outcompete fragmented cooperative structures. Target acquisition archetypes combine captive vineyard acreage with temperature-controlled export infrastructure. Watch for Ministry of Agriculture water allocation restriction announcements as inflection signals compressing hectare expansion economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Vineyards | AM Fresh Group's cold-chain control demonstrates margin capture unavailable to third-party dependent competitors. |
| Automated Clamshell Packaging Investment | German retail chain specifications now mandate optical sorting and sealed configurations for premium seedless lines. |
| Proprietary Cultivar Licensing Agreement | SNFL Group breeding programs sustain multi-season premium pricing through controlled variety deployment. |
| Direct-to-Retailer Logistics Partnership | Bypassing Mercamadrid wholesale intermediaries transfers price volatility risk downstream to retail banners. |
| Organic Certification Conversion Program | EU Common Agricultural Policy eco-scheme payments offset biological control transition costs in water-restricted zones. |
Research Methodology
Spanish Ministry of Agriculture crop statistics, EFSA residue limit documentation, and Mercamadrid wholesale price indices formed the secondary backbone of this analysis. Primary interviews with Murcia grower association managers, German supermarket category buyers, Alicante province packhouse operators, and Ministry of Agriculture phytosanitary certification officers validated production volume and export channel assumptions. Bottom-up vineyard acreage and harvest yield estimates triangulated against top-down retail procurement spend analysis across the projection horizon.
Bottom-up modeling anchored forecast outputs in hectare-level planting data, varietal replacement cycles, and clamshell packaging automation capacity expansion. Segmentation dimensions span product type, distribution channel, packaging format, and end-user application. CAGRs derived from trend-line analysis of historical export volume trajectories and German retail programmed commitment growth. Industry-specific inputs incorporated Guadalquivir River basin water allocation restriction scenarios and EU Green Deal pesticide reduction mandate compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained drought conditions or accelerated Moroccan import tariff adjustments. Deviation in German supermarket private-label consolidation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
Lingonberry Market
Fruits and Vegetables
Goji Berries Market
Fruits and Vegetables
Argentina Fruits & Vegetables Market
Fruits and Vegetables
Morocco Fruits and Vegetables Market
Fruits and Vegetables
Europe Frozen Fruits and Vegetables Market
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
Vegetable Puree Market