
 Adzuki Beans Market | 2026-2036
Adzuki Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Adzuki Beans Market Analytics
Specialized agronomists trained in legume nitrogen fixation is rotating toward contract farming operations across Shandong and Hebei provinces, tightening the labor pool available to smaller processors. ADM leverages its global origination network to secure adzuki bean supply from multiple hemispheres. Fujicco Co. anchors Japanese demand through long-standing relationships with domestic confectionery manufacturers. NANYANG MINGTAI FOODSTUFF CO., LTD. dominates bulk export channels into Southeast Asian food processing hubs.
Adzuki beans, or Vigna angularis, are small reddish legumes containing approximately 20% protein and 60% carbohydrate by dry weight, traditionally processed through soaking, steaming, or milling into sweetened pastes for confectionery applications. The organic product type commands premium positioning as food & beverage formulators seek clean-label protein sources, though conventional supply still occupies the volume base. Health supplements represents the fastest-growing end use industry as adaptogenic and plant-protein positioning extends adzuki derivatives into functional nutrition categories.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict phytosanitary standards on imported adzuki beans, while China's SAMR monitors domestic food safety under GB standards for legume products. The EU's REACH framework and pesticide residue rules shape access for Asian exporters seeking European health store placement. Stakeholders must monitor how carbon accounting requirements under emerging sustainability standards reshape sourcing decisions across the value chain.
Market Dynamics
Contract farming consolidation in China's Shandong Province is compressing procurement timelines and concentrating origination power among networked processors, forcing smaller operators to absorb margin erosion or exit the supply base entirely.
Growth Catalysts
- Organic certification premiums:Health supplements manufacturers in North America and Europe are prioritizing certified organic adzuki protein isolates, pulling supply away from conventional channels.
- Japan's Agricultural Chemicals Regulation Act:Tightened residue limits on imported legumes are accelerating investment in traceable supply chains among exporters seeking market access.
- Confectionery paste innovation:Southeast Asian food processors are reformulating traditional desserts with reduced-sugar adzuki bases, expanding addressable demand in functional sweet categories.
Market Restraints
- Input cost volatility:Synthetic fertilizer price swings directly compress margins for non-organic growers lacking fixed-price contract coverage.
- Supply concentration risk:China's Hebei and Shandong provinces control the majority of East Asian processing capacity, exposing buyers to localized weather and logistics disruptions.
- Regulatory friction:Japan's phytosanitary inspection protocols create extended customs clearance timelines that penalize just-in-time procurement models.
Strategic Opportunities
- Underpenetrated European health retail:Germany and France maintain minimal adzuki protein presence despite strong plant-based nutrition demand, creating first-mover positioning for certified exporters.
- Dual carbon alignment:China's national dual carbon goals are channeling subsidies toward legume cultivation for nitrogen fixation benefits, lowering effective production costs for compliant operators.
- Direct-to-manufacturer platforms:Digital procurement marketplaces are collapsing traditional broker layers, allowing processors to capture margin previously lost to intermediaries.
Industry Challenges
- Specialized agronomist scarcity:Legume nitrogen fixation expertise is concentrating within large contract farming networks, leaving independent processors with degraded crop management support.
- Carbon accounting integration:Emerging sustainability standards require granular emissions tracking across cultivation and processing stages, demanding capital investment in monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adzuki Beans Market |
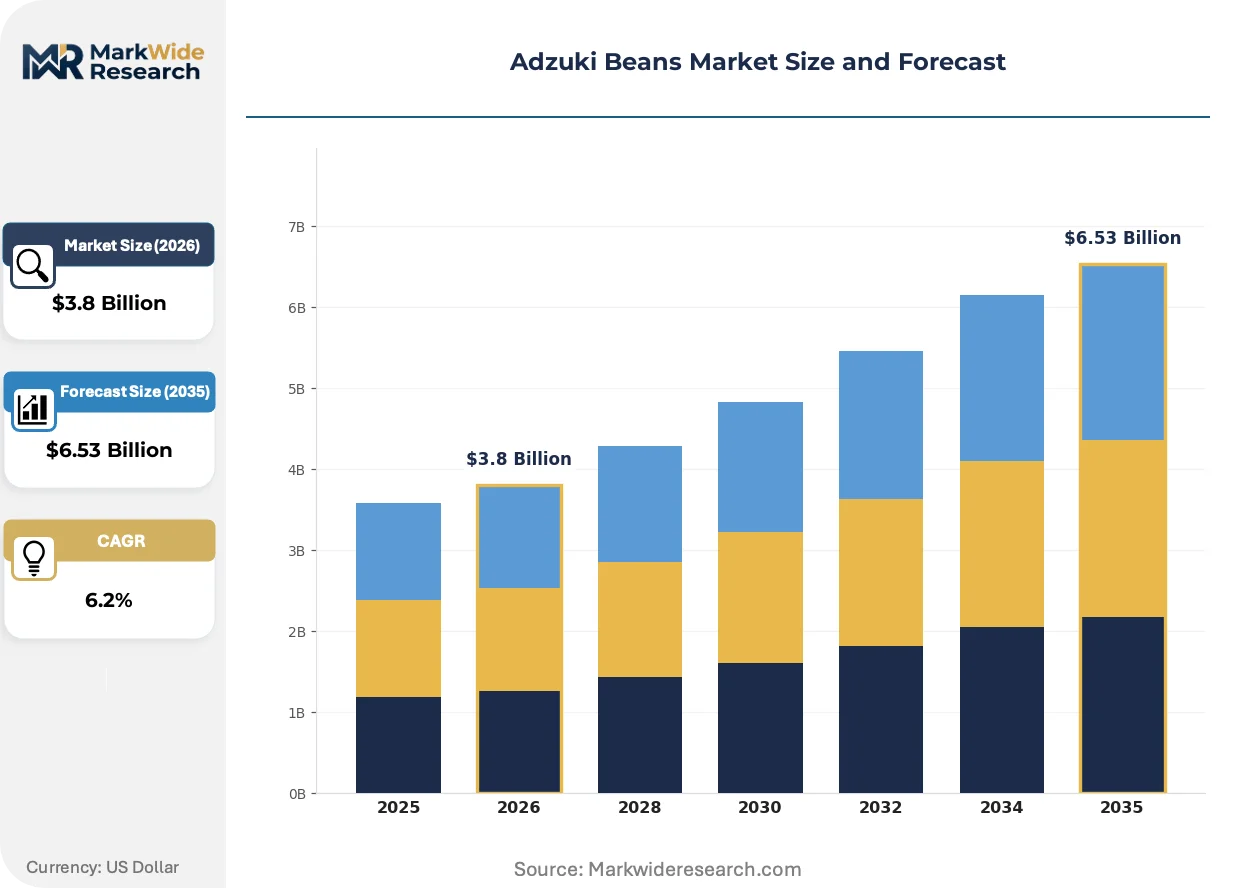
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Packaged, Dried End Use Industry: Food & Beverage, Snacks, Bakery, Health Supplements Packaging Type: Bags, Pouches, Cans, Bulk Distribution Channel: Supermarkets, Health Stores, Online Retail, Specialty Shops |
| Companies Covered | Xi'an Healthway Biotech, Weihai Hongda Import And Export Co., Ltd., NANYANG MINGTAI FOODSTUFF CO., LTD., ADM, Shandong Jinfo Import And Export Co., Ltd., Hebei Nihewan Agricultural Development Co., Ltd., Longnan Yufeng Agricultural Products Development And Distribution Co., Ltd., Fujicco Co., Anhui Guowan Agricultural Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adzuki Beans Market Evolving Landscape
Processing technology and procurement architecture are undergoing parallel transformation, with mechanical innovation compressing extraction costs while digital platforms rewire how buyers access origination.
Spray-dried adzuki protein isolate production is displacing traditional wet-milling infrastructure among mid-scale processors. Health supplements manufacturers in South Korea and Australia are adopting the concentrated protein format at accelerating rates. The technology is displacing legacy paste-based supply relationships that previously dominated B2B protein sourcing.
REACH framework pesticide residue rules are tightening acceptable thresholds for Asian exporters targeting European health store placement. Compliance costs are filtering smaller traders from the supply base. Organic-certified supply chains are absorbing the regulatory burden most effectively, widening the competitive gap against conventional operators.
Long-term offtake contracting is replacing spot market procurement among Japanese confectionery manufacturers seeking supply security. The shift compresses price volatility exposure for processors willing to lock in multi-season volumes. China's contract farming networks are capturing the bulk of this structured demand, reinforcing their origination dominance.
Adzuki Beans Market Segmentation
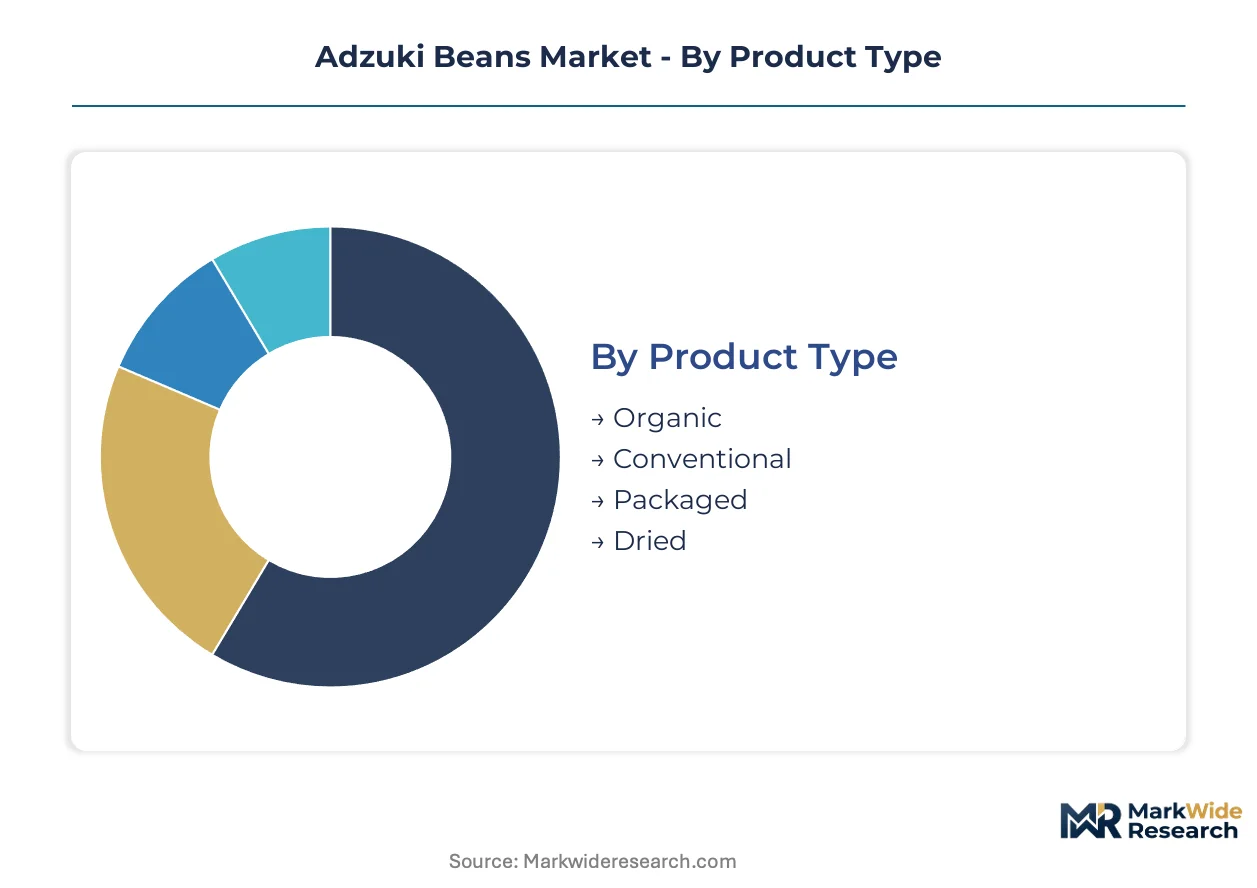
Adzuki bean value pools fragment across certification tiers, application intensity, and channel control points. Procurement managers optimize sourcing by matching product specifications to end-use margin profiles and regulatory exposure.
Product Type:
Organic certification commands the widest margin spreads, particularly in North American and European health supplements channels where residue testing requirements intensify.
- Organic:Cultivated under certified protocols with documented absence of synthetic inputs. Health supplements manufacturers in Germany and France absorb substantial premiums for protein isolates meeting EU organic standards and REACH pesticide thresholds.
- Conventional:Standard cultivation practices dominate volume throughput across East Asian confectionery supply chains. China's Shandong Province contract farming networks supply the bulk of this tier into Japanese paste processing facilities.
- Packaged:Consumer-ready formats target retail shelf placement with standardized weights and branding. Japanese supermarkets and South Korean health stores drive format specifications.
- Dried:Unprocessed whole beans serve industrial rehydration and milling operations. Southeast Asian food processors in Thailand and Vietnam source this tier for traditional dessert manufacturing.
The dominant share belongs to Conventional, while Organic is closing the gap fastest.
End Use Industry:
Application intensity varies sharply: confectionery paste production consumes volume, while protein isolation extracts value.
- Food & Beverage:Sweetened pastes and dessert bases anchor traditional demand across Japan and China. Long-term offtake contracting from Japanese confectionery manufacturers stabilizes procurement timelines for compliant suppliers.
- Snacks:Roasted and flavored whole bean formats target convenience positioning. South Korean and Australian retail channels show expanding shelf space for packaged adzuki snack products.
- Bakery:Paste fillings and flour extenders integrate into premium bread and pastry lines. Southeast Asian bakery chains reformulate with reduced-sugar adzuki bases.
- Health Supplements:Spray-dried protein isolates displace legacy supply relationships among functional nutrition formulators. Australia's TGA-registered manufacturers and South Korean MFDS-regulated facilities are adopting concentrated protein formats at accelerating rates.
Food & Beverage retains volume leadership, though Health Supplements exhibits the steepest expansion trajectory.
Packaging Type:
Format selection tracks customer scale and shelf-life requirements, with flexible formats gaining share in direct-to-manufacturer channels.
- Bags:Woven polypropylene dominates bulk handling across agricultural wholesale and industrial procurement. China's export-oriented processors favor this format for ocean freight efficiency.
- Pouches:Stand-up and flat formats serve retail-ready and health store positioning. German and French organic distributors specify pouch formats for carbon footprint reduction.
- Cans:Hermetic sealing extends shelf stability for premium paste products. Japanese retail channels maintain can format preference for traditional confectionery brands.
- Bulk:Loose loading minimizes unit packaging cost for high-volume processors. Southeast Asian food manufacturing hubs in Thailand and Vietnam absorb this tier for immediate processing intake.
Bags command the installed base, yet Pouches are gaining share fastest in premium channels.
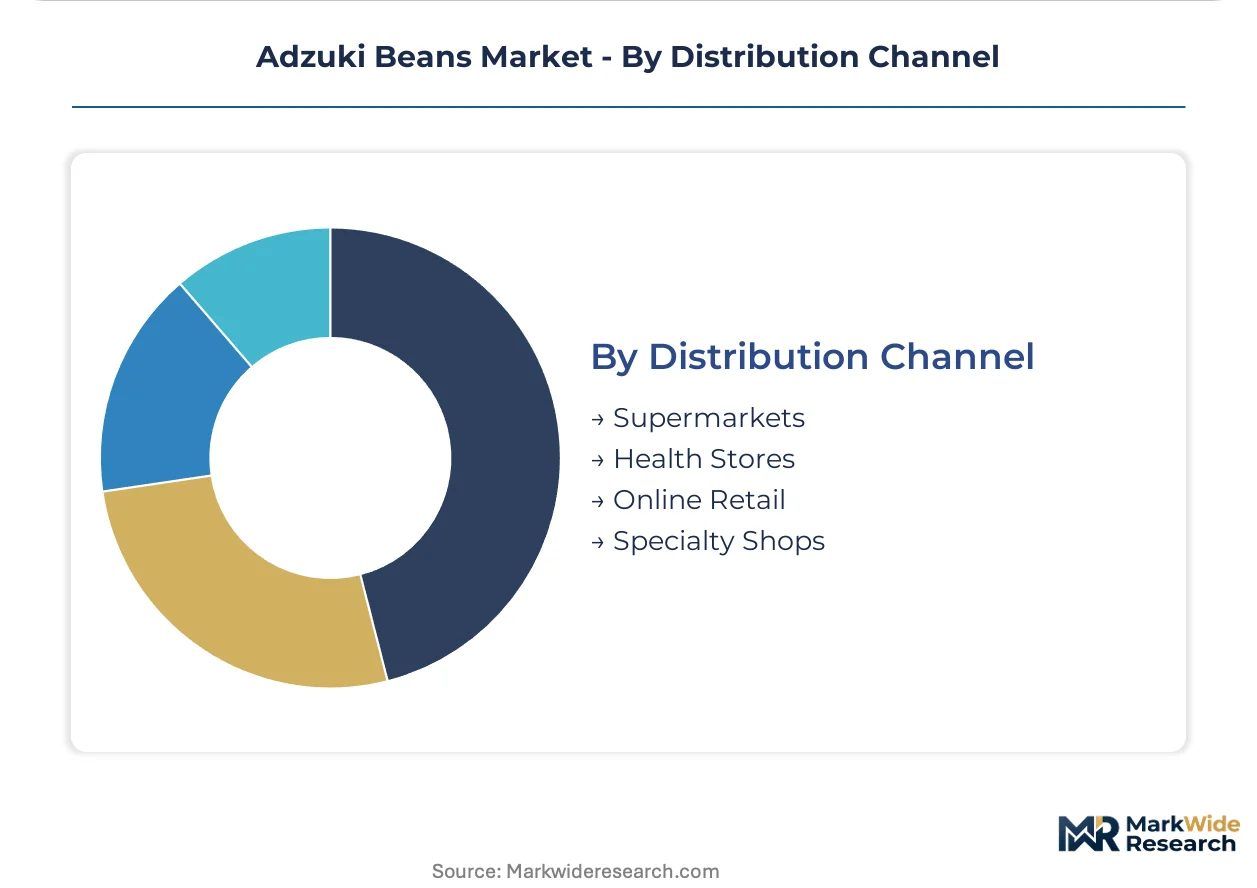
Distribution Channel:
Channel control determines margin capture, with digital platforms collapsing traditional broker layers.
- Supermarkets:Mass retail placement requires standardized packaging and promotional investment. Japanese and South Korean retail chains dominate volume throughput in this channel.
- Health Stores:Specialized retail demands certified organic supply and educational marketing support. Germany's health retail sector shows underpenetrated adzuki protein presence despite strong plant-based nutrition demand.
- Online Retail:Direct-to-consumer platforms enable niche product discovery and subscription models. Australian and North American e-commerce channels accelerate adoption of specialty adzuki formats.
- Specialty Shops:Ethnic and gourmet retailers serve diaspora communities and culinary enthusiasts. Urban centers in France and Germany host concentrated demand for traditional East Asian adzuki preparations.
Supermarkets retain volume dominance, while Online Retail is climbing the fastest among emerging channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR monitors domestic food safety under GB standards for legume products across China's contract farming networks. Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict phytosanitary standards on imported adzuki beans. Germany and France maintain underpenetrated adzuki protein presence despite strong plant-based nutrition demand.
China
Shandong Province contract farming networks supply the bulk of East Asian processing capacity into Japanese paste facilities. SAMR's GB standards for legume products govern domestic food safety compliance across cultivation and milling operations. Hebei and Shandong provinces concentrate origination power among networked processors, forcing smaller operators to absorb margin erosion.
Japan
Domestic confectionery manufacturers anchor demand through long-standing relationships with paste suppliers. The Agricultural Chemicals Regulation Act revisions tighten residue limits on imported legumes, accelerating investment in traceable supply chains. METI oversees industrial policy coordination as phytosanitary inspection protocols create extended customs clearance timelines.
Germany
Health stores show minimal adzuki protein presence despite accelerating plant-based nutrition demand across functional food categories. REACH framework pesticide residue rules shape access for Asian exporters seeking European health store placement. Berlin and Hamburg host concentrated demand for traditional East Asian preparations through ethnic and gourmet retailers.
South Korea
MFDS-regulated facilities adopt concentrated protein formats at accelerating rates for functional nutrition formulators. Australia's TGA-registered manufacturers pull supply from regional export channels. Seoul's retail chains expand shelf space for packaged adzuki snack products in convenience positioning.
Australia
TGA-registered manufacturers drive adoption of spray-dried protein isolates among health supplements formulators. E-commerce channels accelerate specialty format adoption through direct-to-consumer platforms. Sydney and Melbourne concentrate demand for organic-certified supply in premium health retail.
Adzuki Beans Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the adzuki value chain. The vendor base clusters around three strategic tiers: global origination networks with multi-hemisphere supply security, domestic confectionery anchors with long-standing paste relationships, and bulk export specialists with Southeast Asian channel control. Dominant competitive moves include long-term offtake contracting replacing spot market procurement and spray-dried protein isolation displacing legacy wet-milling infrastructure.
Among China-based operators, NANYANG MINGTAI FOODSTUFF CO., LTD. and Shandong Jinfo Import And Export Co., Ltd. occupy positions within the bulk export specialist tier. Fujicco Co. represents the domestic confectionery anchor archetype. ADM exemplifies the global origination network model with multi-hemisphere supply security.
| Leading Market Players |
|---|
| Xi'an Healthway Biotech |
| Weihai Hongda Import And Export Co., Ltd. |
| NANYANG MINGTAI FOODSTUFF CO., LTD. |
| ADM |
| Shandong Jinfo Import And Export Co., Ltd. |
| Hebei Nihewan Agricultural Development Co., Ltd. |
| Longnan Yufeng Agricultural Products Development And Distribution Co., Ltd. |
| Fujicco Co. |
| Anhui Guowan Agricultural Technology |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracting from Japanese confectionery manufacturers locks in multi-season supply access while compressing price volatility exposure for processors embedded within China's Shandong contract farming networks. This structure concentrates origination power among networked operators capable of meeting Japan's Agricultural Chemicals Regulation Act residue limits, forcing smaller processors to absorb margin erosion or exit procurement channels entirely.
Pricing Analysis
Japanese import premiums for certified organic adzuki protein isolates diverge sharply from conventional paste-grade supply sourced through China's Hebei bulk channels. Three-tier pricing structure across premium organic certification, standard contract-grade, and economy spot-market tiers reflects divergence in residue testing rigor and traceability documentation. Pricing pressure stems from synthetic fertilizer cost swings compressing non-organic grower margins lacking fixed-price coverage. Japanese confectionery manufacturers exhibit lowest price sensitivity due to supply security priorities, while Southeast Asian dessert processors operate at highest sensitivity to input cost fluctuations.
Supply Chain Analysis
Strategic stockpiling dominates procurement behavior among Japanese paste processors facing extended customs clearance timelines under METI phytosanitary inspection protocols, while just-in-time models prevail in Southeast Asian food manufacturing hubs. Supply concentrates in China's Shandong and Hebei provinces, with secondary origination from South Korean contract farming operations and Australian organic cultivation. Raw material dependencies center on synthetic nitrogen fertilizers, certified organic compost inputs, and specialized legume inoculants for nitrogen fixation. Single-source vulnerability from China's provincial concentration exposes buyers to localized weather disruption. Distribution runs through ocean freight bulk channels into Japanese port facilities and overland trucking networks across Southeast Asian processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized agronomist expertise in legume nitrogen fixation has concentrated within large contract farming networks, degrading crop management support available to independent processors and creating a bottleneck for quality-assured supply expansion.
For Market Incumbents: Shield origination relationships by embedding agronomist teams directly within Shandong and Hebei contract farming operations, denying smaller competitors access to technical crop management support. Accelerate organic certification investment to capture widening premium spreads as REACH framework pesticide residue rules filter conventional traders from European health store channels. Long-term offtake contracting remains the priority defensive lever against spot-market price volatility. For New Entrants and Emerging Players: Digital procurement platform infrastructure represents a service-layer gap where incumbent processors under-serve mid-scale health supplements manufacturers seeking direct origination access. Germany and France health retail channels offer the most penetrable geography for certified organic protein isolate positioning. Target Australia's TGA-registered manufacturers through direct technical sales emphasizing spray-dried isolate format adoption. For Investors and Strategic Acquirers: Capital is best deployed toward contract farming network operators with embedded agronomist capabilities and established Japanese regulatory compliance track records. Long-term viability across the analysis window hinges on nitrogen fixation expertise scarcity and carbon accounting infrastructure readiness. Watch for inflection in China's dual carbon subsidy disbursement patterns as signal for compliant operator cost advantage expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Investment | Captures premium spreads as REACH rules tighten European market access for conventional supply. |
| Contract Farming Network Expansion | Concentrates origination power among operators capable of meeting Japan's residue limit revisions. |
| Spray-Dried Protein Isolate Capacity | Displaces legacy wet-milling infrastructure among South Korean and Australian health supplements formulators. |
| Digital Procurement Platform Launch | Collapses traditional broker layers, allowing processors to capture margin previously lost to intermediaries. |
| Carbon Accounting Infrastructure Buildout | Positions compliant operators for China's dual carbon subsidy channeling toward legume nitrogen fixation benefits. |
Research Methodology
Desk research of customs trade databases, agricultural commodity exchange records, and regulatory filing repositories preceded structured interviews with contract farming network managers, Japanese confectionery procurement directors, health supplements formulators, and organic certification auditors. Primary fieldwork across Shandong and Hebei cultivation zones combined with secondary validation from SAMR GB standards documentation and Japan's Agricultural Chemicals Regulation Act revision notices. Bottom-up volume estimates from provincial processing capacity data triangulated against top-down demand aggregation from end-use industry consumption patterns.
Variance decomposition across certification tiers, application intensity, and channel control points structured the analytical framework over the projection horizon. Segmentation dimensions modeled include organic versus conventional cultivation protocols, food and beverage versus health supplements end-use intensity, and direct-to-manufacturer versus broker-mediated procurement channels. CAGRs derived from historical price trajectory analysis and demand elasticity coefficients calibrated against nitrogen fixation technology adoption curves and spray-dried isolate format penetration rates.
Forecasts assume regulatory continuity in Japan's Agricultural Chemicals Regulation Act enforcement and China's SAMR GB standards for legume products; material policy shifts would require re-modeling of import channel viability and domestic processing capacity utilization. Practitioners should keep alternative scenarios live as China's dual carbon subsidy disbursement patterns and REACH framework pesticide threshold revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
United Kingdom Fruits and Vegetables Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Dried Fruits Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Brown Shimeji Mushroom Market