
 Global Not from Concentrate (NFC) Puree Market | 2026-2036
Global Not from Concentrate (NFC) Puree Market Size, Share, and Industry Trends Forecast 2026-2036
Global Not from Concentrate (NFC) Puree Market Analysis
Spain is reconfiguring its Mediterranean fruit processing belt with expanded NFC puree capacity aimed at European beverage and baby food clients. Döhler Group leverages integrated orchards in Huelva to secure year-round raw material flows. Tree Top anchors Pacific Northwest apple supply for North American infant formula producers. Symrise AG competes through flavor-house partnerships that embed NFC puree into compounded ingredient systems.
Not from Concentrate puree retains the full cellular structure and native soluble solids of crushed, pressed fruit or vegetable matter without water removal and reconstitution. Manufacturers achieve shelf stability through high-pressure processing or aseptic hot-fill methods that preserve enzymatic activity and color fidelity for downstream formulation. Fruit puree occupies the dominant value share as beverage and baby food applications command premium positioning over commodity vegetable variants. Pouch packaging records the fastest growth trajectory among packaging types, driven by single-serve convenience formats in retail and food service channels.
FDA enforces juice HACCP rules that mandate pathogen controls for NFC puree entering US interstate commerce, while EFSA pesticide maximum residue limits under EU Regulation 396/2005 directly shape orchard management practices for European-bound shipments. CE marking and MEE environmental discharge standards in China constrain new processing facility approvals, tightening supply eligibility for Asian market access. Stakeholders must track evolving allergen labeling mandates and carbon footprint disclosure requirements that will soon differentiate compliant suppliers from excluded volumes.
Market Dynamics
Cold-pressed extraction technology is compressing thermal degradation losses while EU pesticide residue rules under Regulation 396/2005 force orchard management upgrades across supplier bases.
Growth Catalysts
- High-pressure processing:Beverage formulators adopt HPP systems to extend shelf life without heat damage to volatile aromatic compounds.
- EU infant nutrition standards:Tighter EFSA maximum residue limits for baby food-grade purees create premium pricing tiers for compliant suppliers.
- California Central Valley:Processing corridor concentration enables year-round apple and pear supply integration for North American infant formula producers.
Market Restraints
- Input cost volatility:Fresh fruit procurement swings with climate-driven harvest variability in Mediterranean and Pacific Northwest growing regions.
- Supply concentration risk:Huelva-integrated orchard operations control disproportionate European raw material flows through Döhler Group captive supply.
- Technical limitation:Enzymatic browning in aseptic hot-fill pear purees constrains color fidelity for premium beverage applications.
Strategic Opportunities
- Underpenetrated geography:Chinese MEE environmental discharge standards and CE marking requirements filter out non-compliant processors, creating eligibility gaps for qualified entrants.
- Regulatory tailwind:FDA juice HACCP rule enforcement mandates pathogen controls that favor capital-intensive processors over commodity traders.
- Distribution innovation:Single-serve pouch formats penetrate food service channels previously dominated by institutional bulk packaging.
Industry Challenges
- Skill gap in cold-chain management:Aseptic hot-fill and HPP operations require technicians trained in pressure vessel safety and microbial validation protocols.
- Capex intensity:High-pressure processing equipment and aseptic filling lines demand multi-million dollar facility investments with extended depreciation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Not from Concentrate (NFC) Puree Market |
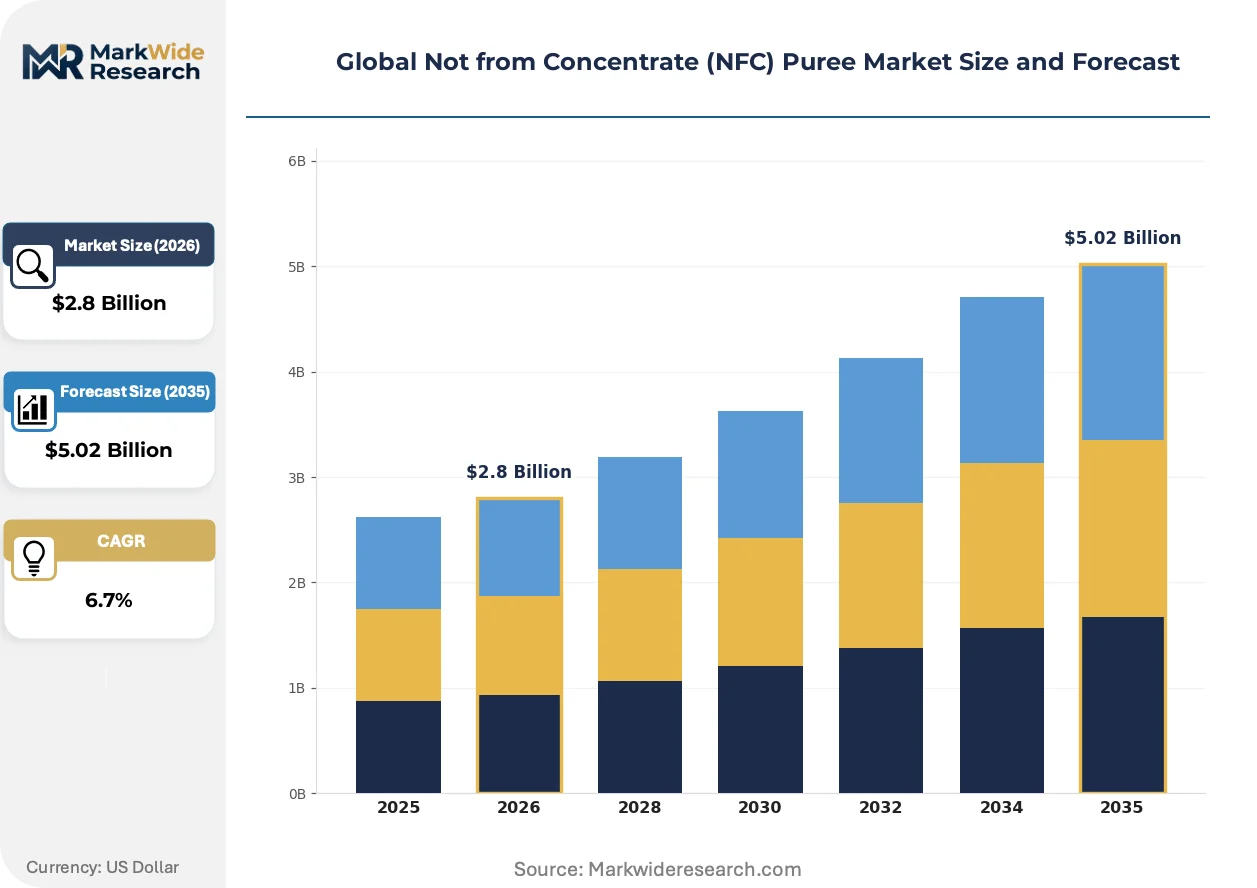
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Puree, Vegetable Puree, Mixed Puree, Specialty Puree End User: Food Manufacturers, Food Service, Retail, Online Retailers Packaging Type: Glass Jars, Pouches, Tetra Packs, Cans Application: Beverages, Baby Food, Sauces, Dressings |
| Companies Covered | Döhler Group, Tree Top, SunOpta, SVZ Industrial Fruit & Vegetable Ingredients, Kerr Concentrates, Hain Celestial Group, Symrise AG, AGRANA Beteiligungs-AG, Monin Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Not from Concentrate (NFC) Puree Market Emerging Trajectories
Extraction and preservation technologies are compressing quality loss margins while regulatory disclosure mandates and channel format shifts restructure competitive positioning.
Cold-pressed extraction systems operate at ambient temperatures to preserve native enzyme activity and aromatic compound profiles in apple and pear purees. Premium infant formula manufacturers in Germany and California are retrofitting lines to accommodate this equipment. Traditional heat-based concentration methods are rendering obsolete for high-value applications where volatile loss directly impacts flavor house acceptance.
EU Regulation 396/2005 pesticide maximum residue limits now extend to processed fruit ingredients entering baby food supply chains. Orchard operators in Huelva and the Central Valley face mandatory buffer zones and integrated pest management audits. European-bound puree volumes require third-party residue certification that commodity traders cannot supply, compressing eligible supplier pools.
Clean-label procurement mandates now require carbon footprint disclosure and allergen traceability documentation from puree suppliers. North American infant formula producers audit orchard-to-pouch chain of custody records. California and German buyers enforce the strictest verification protocols, excluding processors lacking environmental management system certification.
Global Not from Concentrate (NFC) Puree Market Segmentation
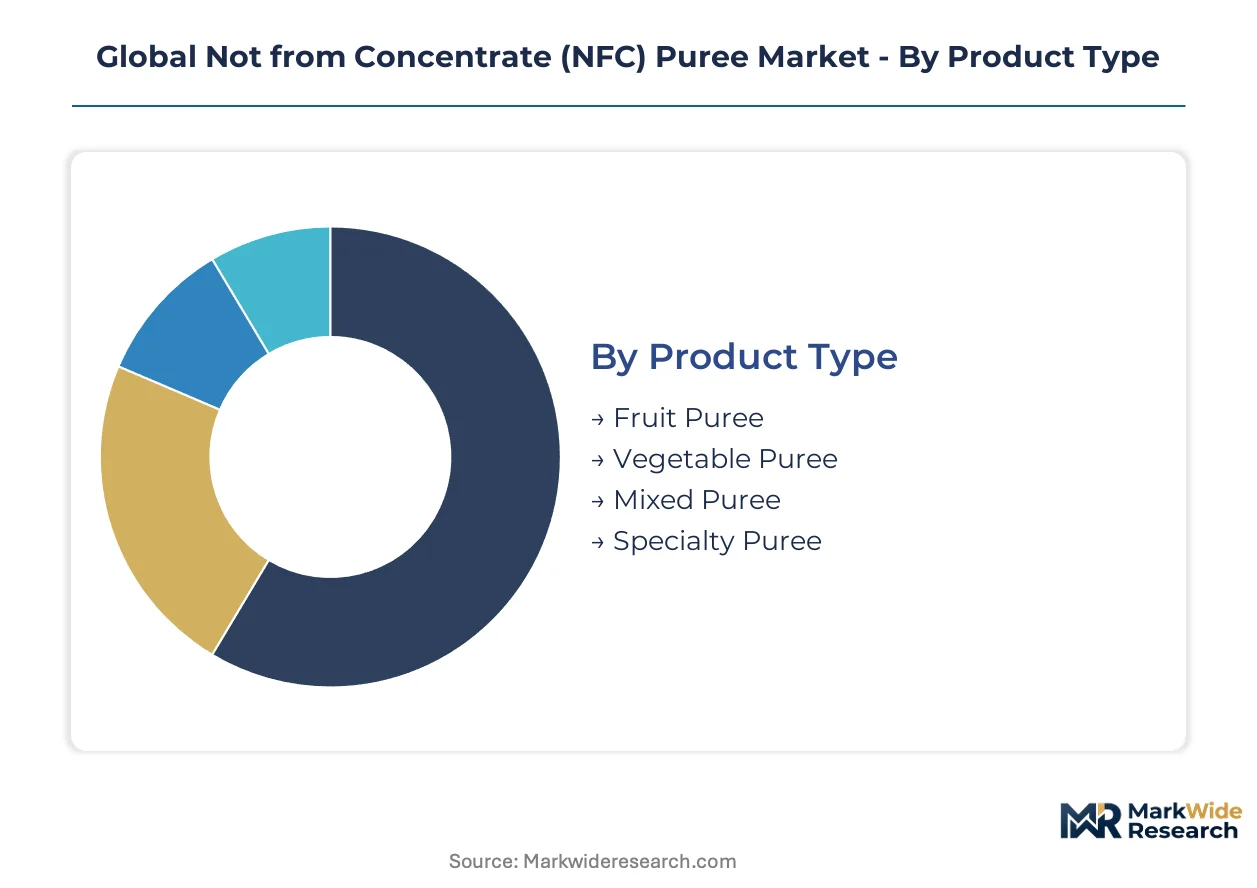
NFC puree segmentation reveals how processing specifications, packaging formats, and regulatory compliance requirements fragment procurement strategies across infant formula, beverage, and food service channels. Distinct technical standards for enzymatic activity, browning resistance, and aseptic stability create tiered supplier eligibility that reshapes competitive positioning.
Product Type:
After-sales technical support intensity varies sharply across product categories, with fruit purees demanding flavor-house calibration services and specialty variants requiring customized enzymatic stabilization protocols.
- Fruit Puree:Retains full cellular structure and native soluble solids from crushed apple, pear, and tropical fruits without water removal. Infant formula producers in Germany and California source premium grades under EFSA pesticide residue limits, with cold-pressed extraction preserving volatile aromatic compounds for downstream flavor integration.
- Vegetable Puree:Carrot, pumpkin, and sweet potato variants carry lower premium positioning than fruit counterparts due to commodity procurement patterns. Demand concentrates in baby food applications where color fidelity and beta-carotene retention specifications drive supplier selection.
- Mixed Puree:Blended fruit-vegetable formulations balance nutritional profiles for pediatric nutrition segments.
- Specialty Puree:Exotic and organic-certified variants command technical service premiums for supply chain traceability documentation.
Fruit puree holds the largest share; momentum sits with specialty puree as carbon disclosure mandates filter out commodity suppliers.
End User:
Cost tier stratification separates capital-intensive processors with integrated orchard control from traders dependent on spot procurement.
- Food Manufacturers:Infant formula and beverage formulators dominate volume offtake, requiring HACCP-validated supply chains and third-party residue certification. California's Central Valley processing corridor anchors North American procurement for this segment.
- Food Service:Institutional buyers prioritize shelf-stable bulk formats with extended ambient distribution tolerance.
- Retail:Supermarket chains enforce clean-label procurement mandates with chain-of-custody documentation requirements.
- Online Retailers:Direct-to-consumer channels favor single-serve pouch formats with premium positioning.
Food manufacturers command the largest share; online retailers are gaining share fastest through convenience-format penetration.
Packaging Type:
Application-driven format selection balances thermal processing compatibility with consumer convenience expectations across channel types.
- Pouches:Flexible single-serve formats penetrate food service channels previously dominated by institutional bulk packaging, with aseptic filling lines enabling ambient distribution without refrigeration dependency.
- Glass Jars:Premium retail positioning for organic and specialty variants where visual transparency supports clean-label marketing claims.
- Tetra Packs:Carton-based aseptic formats optimize logistics efficiency for beverage industry volume buyers.
- Cans:Metal packaging retains relevance for industrial ingredient applications requiring extended shelf stability.
Glass jars retain the largest installed base; pouches are expanding most quickly across retail and food service channels.
Application:
Customer type differentiation separates formulation-intensive buyers requiring technical partnership from commodity traders focused on spot price arbitrage.
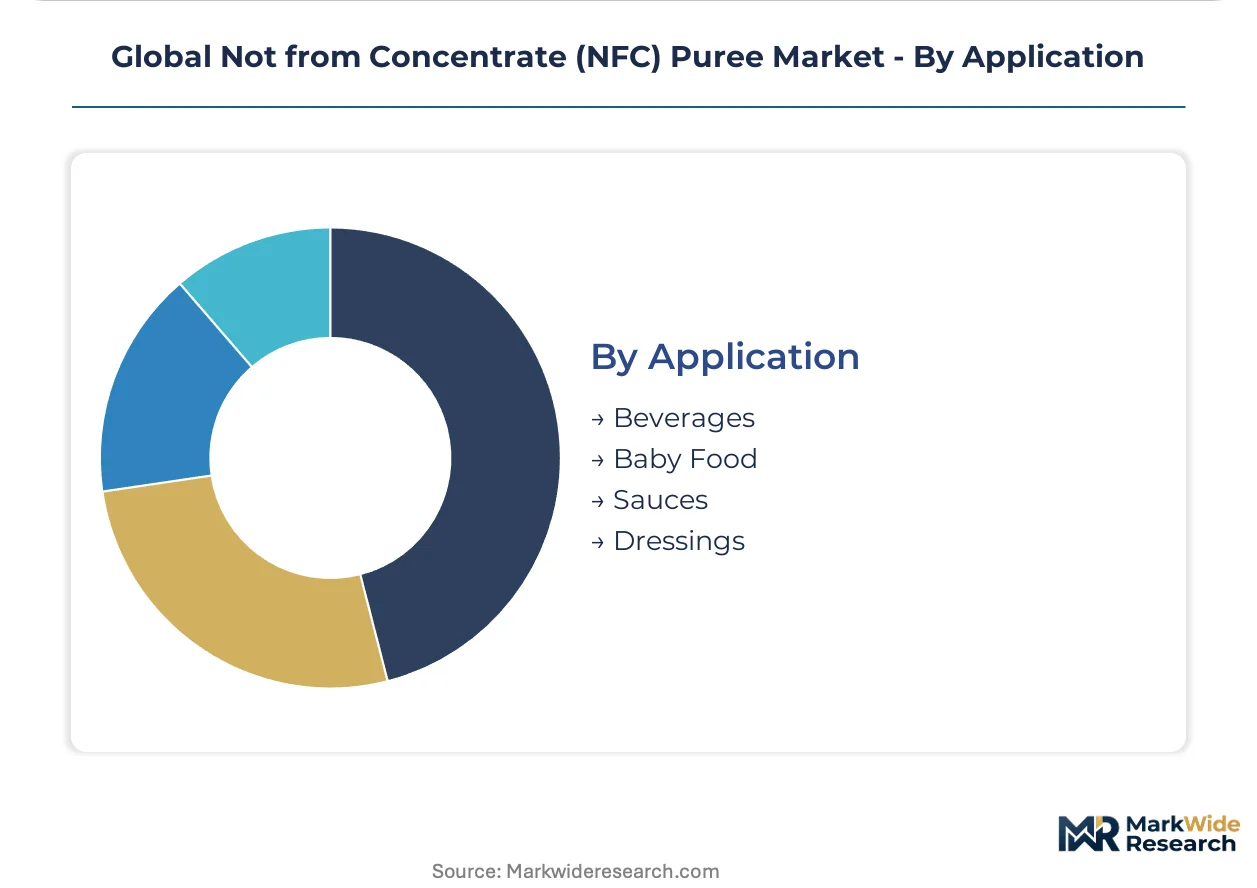
- Beverages:Smoothie and juice formulators adopt high-pressure processing systems to extend shelf life without thermal damage to volatile aromatic compounds, with EU and US buyers enforcing strictest verification protocols.
- Baby Food:EFSA Regulation 396/2005 maximum residue limits and FDA juice HACCP rules create dual-jurisdiction compliance barriers that favor capital-intensive processors over commodity traders.
- Sauces:Viscosity and pH stability specifications drive enzymatic browning management requirements in pear and apple purees.
- Dressings:Emulsion stability needs favor specific pulp content ranges in vegetable puree formulations.
Beverages hold the largest share; baby food shows the steepest expansion trajectory as EU infant nutrition standards tighten supplier eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA juice HACCP rules and EFSA pesticide maximum residue limits under Regulation 396/2005 anchor procurement standards across the dominant United States and German demand centers, with orchard-to-processing corridor integration determining supplier eligibility in each market.
United States
California's Central Valley processing corridor supplies North American infant formula producers with year-round apple and pear purees. FDA enforces pathogen controls through juice HACCP mandates that favor capital-intensive processors over commodity traders. Tree Top anchors Pacific Northwest supply integration for beverage and baby food manufacturers demanding third-party residue certification.
Germany
EFSA maximum residue limits for baby food-grade purees create premium pricing tiers unavailable to non-compliant suppliers. Döhler Group leverages integrated orchards in Huelva to secure year-round raw material flows for European beverage clients. German infant nutrition manufacturers now source exclusively under tightened EU pesticide residue rules that commodity traders cannot satisfy.
Spain
Andalusia's Mediterranean fruit processing belt is reconfiguring with expanded NFC puree capacity aimed at European beverage and baby food clients. EU Regulation 396/2005 forces orchard management upgrades through mandatory buffer zones and integrated pest management audits. Huelva-integrated operations control disproportionate European raw material flows through captive supply arrangements.
China
MEE environmental discharge standards and CE marking requirements constrain new processing facility approvals, tightening supply eligibility for Asian market access. Domestic infant formula producers seek compliant puree imports as local processors face certification barriers. Yangtze River Delta manufacturing clusters concentrate demand for aseptic packaging-compatible purees.
India
FSSAI food safety standards and rising domestic infant nutrition demand are reshaping import procurement patterns. Maharashtra and Gujarat processing hubs evaluate cold-pressed extraction adoption for premium beverage applications. Local orchard operators lack integrated pest management certification required for EU-bound export volumes.
Global Not from Concentrate (NFC) Puree Market Vendor Landscape
Vertically integrated orchard operators and flavor-house-integrated processors split the market between raw material control and formulation partnership models. The vendor base concentrates around two strategic archetypes: captive supply chain operators with integrated orchard assets, and compounded ingredient specialists embedding puree into broader flavor systems. Competitive moves center on backward integration into orchard operations and technology licensing for cold-pressed extraction capacity.
Within the integrated supply tier, Döhler Group and Tree Top exemplify orchard-captive positioning, while Symrise AG occupies the flavor-house partnership vector. Döhler Group represents European integrated operations with Huelva orchard control. Tree Top anchors North American supply integration through Pacific Northwest assets. Symrise AG exemplifies the compounded ingredient archetype through flavor-house partnerships that embed NFC puree into downstream formulation systems.
| Leading Market Players |
|---|
| Döhler Group |
| Tree Top |
| SunOpta |
| SVZ Industrial Fruit & Vegetable Ingredients |
| Kerr Concentrates |
| Hain Celestial Group |
| Symrise AG |
| AGRANA Beteiligungs-AG |
| Monin Incorporated |
| Others |
Supply Flow & Price Mechanics
California's Central Valley processing corridor freight dynamics compress margins for spot-market traders while amplifying price premiums for integrated operators with captive orchard supply and cold-chain control.
Pricing Analysis
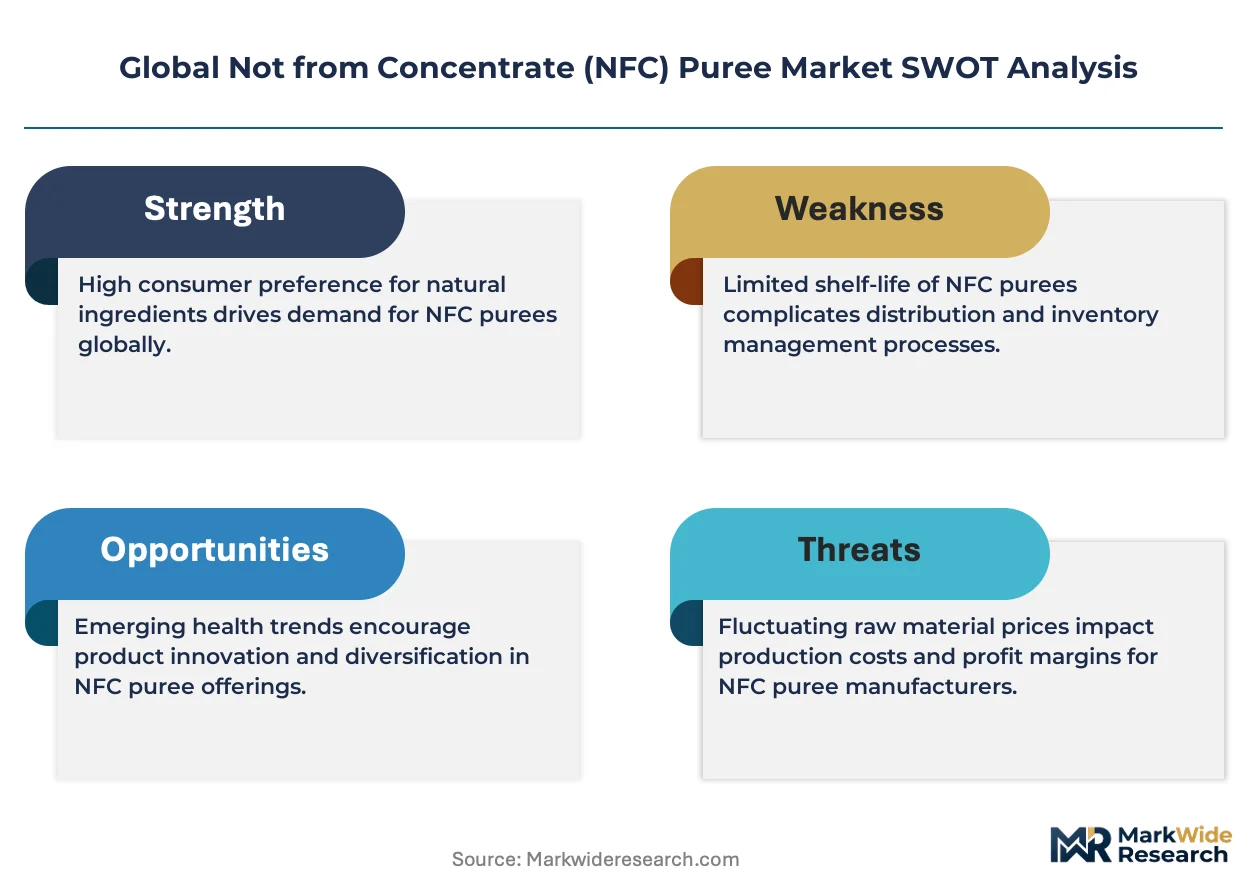
Geographic price spreads between Huelva-integrated European supply and Pacific Northwest spot procurement widen during Mediterranean harvest volatility. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-certified baby food grades from beverage-tier and industrial ingredient volumes. Pricing pressure stems from climate-driven fresh fruit procurement swings in Andalusia and Central Valley growing regions. Food manufacturers with HACCP-validated supply chains show least price sensitivity; commodity traders dependent on spot markets face margin compression.
Supply Chain Analysis
Tariff exposure between US and EU jurisdictions dominates supply chain risk planning for cross-Atlantic puree shipments. Raw material flows concentrate in Spain, the United States, and China, with orchard operations drawing from apple, pear, and tropical fruit cultivars. Single-source vulnerability sits with Huelva-integrated operations controlling disproportionate European raw material volumes. Distribution runs through aseptic packaging facilities to infant formula producers, beverage formulators, and food service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for flavor-house calibration and enzymatic stabilization protocols expand faster than commodity puree volumes, creating recurring-revenue layers that outperform hardware-centric sales.
For Market Incumbents: Entrench through backward integration into Huelva and Central Valley orchard assets to secure captive supply against climate-driven harvest variability. Invest in cold-pressed extraction certification to defend premium positioning as EU Regulation 396/2005 tightens residue compliance barriers. For New Entrants and Emerging Players: Pursue white-space opportunity in Chinese MEE-compliant processing capacity as domestic infant formula producers seek eligible imports. Target specialty puree segments with carbon disclosure documentation and organic certification. Lead with technical partnership models rather than commodity spot supply. For Investors and Strategic Acquirers: EU infant nutrition standard enforcement reshapes the acquisition landscape toward integrated orchard operators with third-party residue certification infrastructure. Five-to-ten-year viability favors processors with environmental management system credentials and aseptic hot-fill capacity. Monitor EFSA maximum residue limit expansion into additional fruit categories as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Operations | Huelva and Central Valley captive supply secures year-round raw material flows for EFSA-compliant production. |
| Cold-Pressed Extraction Capacity Addition | Ambient-temperature processing preserves volatile aromatic compounds for premium infant formula and beverage applications. |
| Third-Party Residue Certification Investment | EU Regulation 396/2005 compliance creates eligibility barriers that exclude commodity traders from baby food supply chains. |
| Aseptic Pouch Format Expansion | Single-serve packaging penetrates food service channels previously dominated by institutional bulk formats. |
| Carbon Footprint Disclosure Program | Clean-label procurement mandates from California and German buyers require chain-of-custody documentation. |
Methodological Framework
Desk research of customs trade databases, FDA juice HACCP enforcement records, and EFSA pesticide residue monitoring reports preceded structured interviews with infant formula procurement directors, beverage flavor house technical leads, orchard operations managers, and aseptic packaging equipment specialists. Primary fieldwork combined with secondary validation from EU Regulation 396/2005 implementation guidance and California agricultural commission harvest data. Bottom-up volume modeling triangulated against top-down value estimates across product type, end user, packaging format, and application segments.
Assumptions held EU infant nutrition standards and FDA pathogen control enforcement constant while varying climate-driven harvest yield scenarios across Mediterranean and Pacific Northwest growing regions. Segmentation modeling spanned fruit puree, vegetable puree, mixed puree, and specialty puree categories crossed with food manufacturer, food service, retail, and online retailer channels. CAGRs derived from slope analysis of historical volume trajectories adjusted for regulatory inflection points and technology adoption curves. Cold-pressed extraction penetration rates and high-pressure processing equipment deployment served as key forecast inputs across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in freight rates, agricultural input costs, or currency exchange volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Global Fruit Concentrate Puree Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Vegetable Puree Market
Fruits and Vegetables
Pineapple Market
Fruits and Vegetables
Kiwi Fruit Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Global Avocado Market