

Haskap Berry Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Haskap Berry Powder Market Insights
Organic-certified and freeze-dried specification tiers is reorganizing competitive dynamics among suppliers. Haskapa leverages its UK-based cultivation network to sustain premium positioning in European nutraceutical channels. BIOHASKAP anchors North American supply through Saskatchewan growing operations. Jilin Longze Biotechnology dominates freeze-dried output capacity for Asian functional food manufacturers.
Haskap berry powder consists of finely milled Lonicera caerulea fruit processed to retain anthocyanin concentrations typically exceeding those of blueberry and açai sources, serving primarily as a natural colorant, flavoring agent, and bioactive ingredient in formulated consumer products. Freeze-dried grades command margin concentration due to superior polyphenol retention and solubility performance in beverage applications, while spray-dried variants occupy volume leadership in cost-sensitive dietary supplement blending. The dietary supplements application segment leads value capture as clinical validation of haskap's cardiovascular and cognitive health properties deepens, though functional food integration by Japanese and South Korean manufacturers is accelerating fastest.
Health Canada and the FDA govern novel food ingredient approvals and health claim substantiation in North America, while Japan's Consumer Affairs Agency oversees Foods with Function Claims registration that shapes market access for bioactive powders. The EU's novel food regulation under EFSA jurisdiction requires pre-market authorization for haskap extracts in member states, creating compliance cost barriers for new entrants. Stakeholders must monitor evolving anthocyanin-specific daily intake guidance and organic certification reciprocity agreements between major producing and consuming jurisdictions.
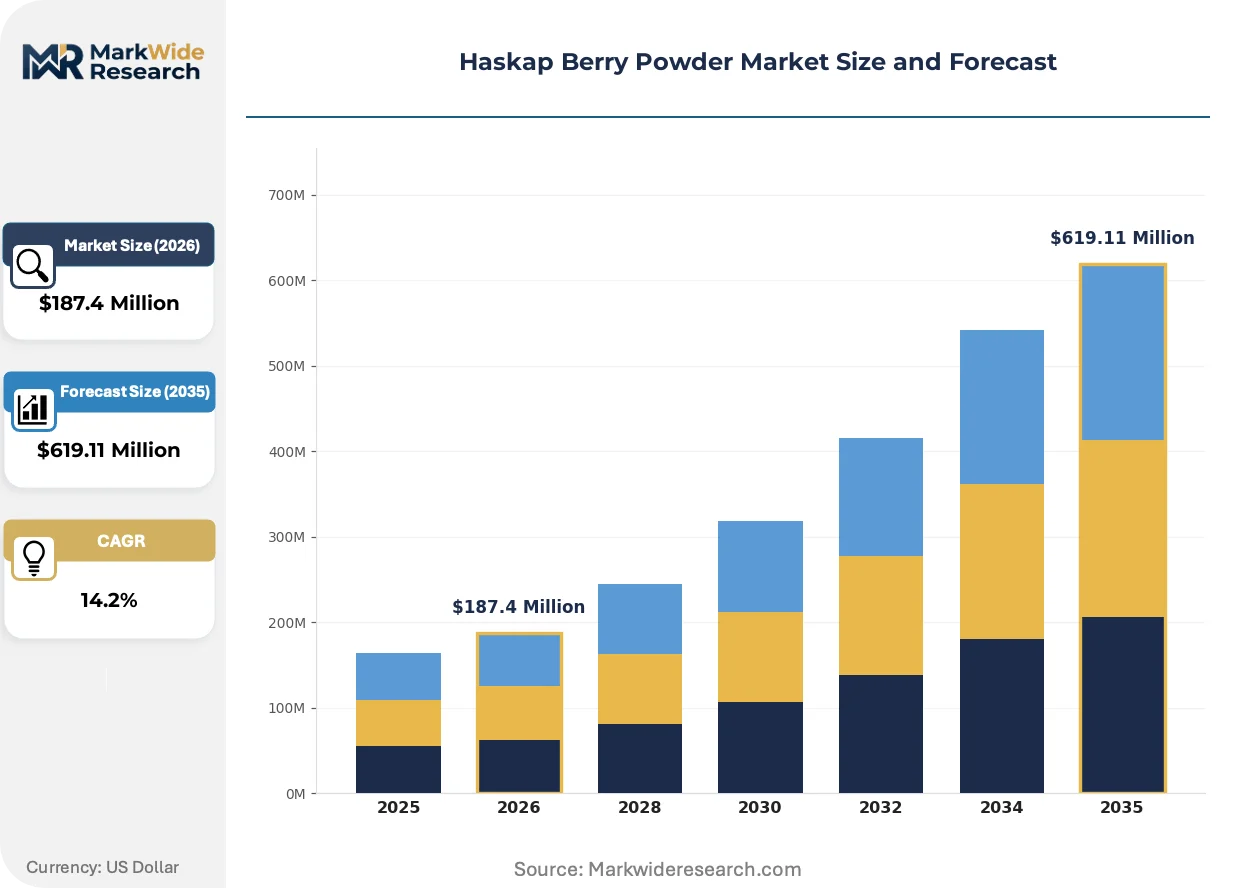
Market Dynamics
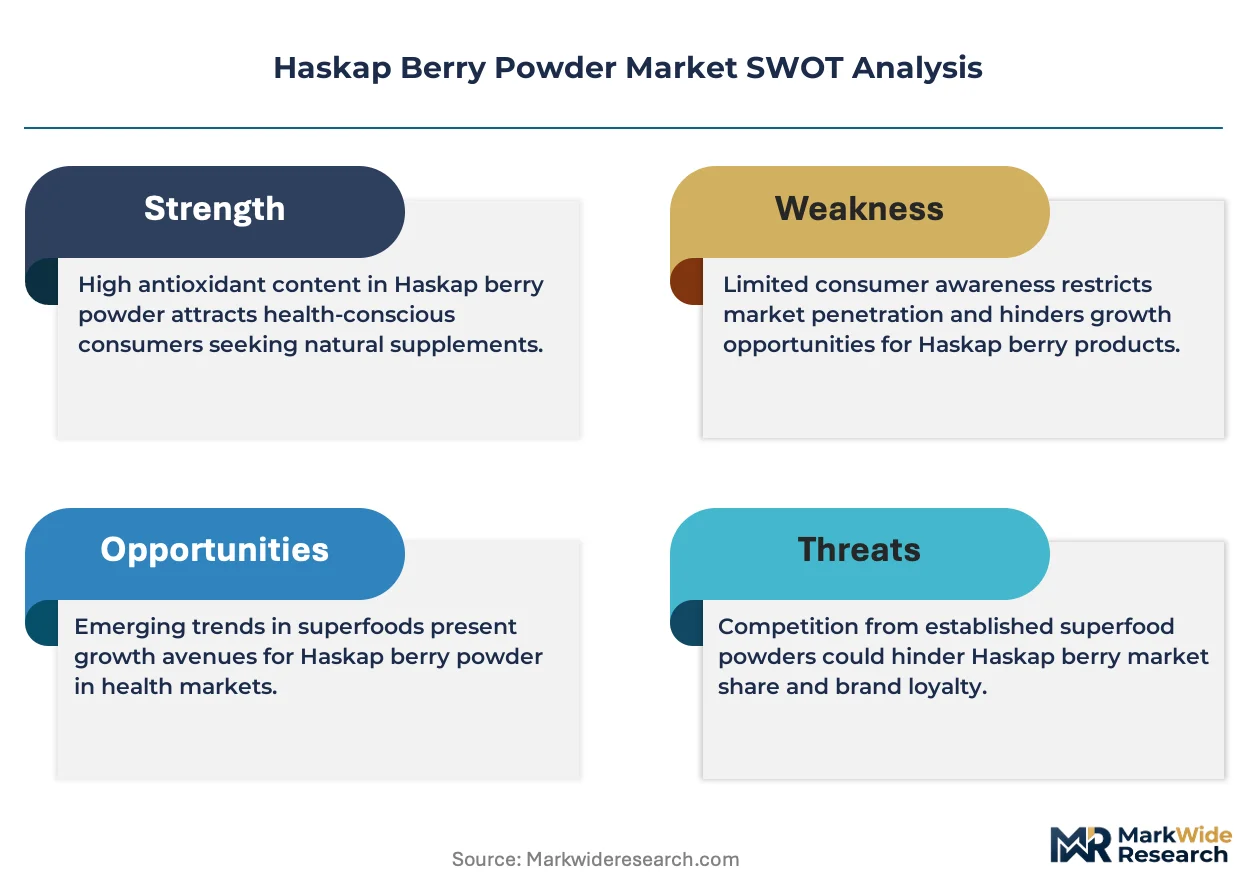
Clean-label formulation mandates from Japan's Consumer Affairs Agency and Health Canada are compressing synthetic additive demand while elevating anthocyanin-rich botanical powders in functional food pipelines. Procurement officers now require freeze-dried certification tiers that were optional five years ago.
Growth Catalysts
- Foods with Function Claims:Japan's CAA registration pathway accelerates haskap powder incorporation into cardiovascular health products. Functional food manufacturers secure shelf-space advantages through this pre-approved claim structure.
- Anthocyanin retention technology:Low-temperature vacuum drying protocols now preserve bioactive concentrations above 85 percent through processing. Supplement formulators specify these grades for cognitive health positioning.
- Saskatchewan cultivation clusters:Canadian Prairie provinces aggregate organic haskap acreage under single-origin traceability systems. North American brands leverage this geography for domestic sourcing narratives.
Market Restraints
- Freeze-drying energy intensity:Natural gas price volatility in European processing facilities elevates unit costs for premium grades. Manufacturers absorb margin compression or pass through to price-sensitive buyers.
- Single-origin supply concentration:Jilin Province freeze-dried capacity dominates Asian functional food procurement. Buyers face concentration risk from weather events or logistics disruptions in this geography.
- EFSA novel food authorization:Pre-market approval timelines for haskap extracts extend 18-24 months in EU member states. Smaller suppliers lack capital reserves to sustain compliance costs through this regulatory friction.
Strategic Opportunities
- South Korean functional beverage channel:Local formulators seek differentiated anthocyanin sources beyond established blueberry and açai suppliers. Haskap powder offers color stability advantages in acidic formulations.
- Direct-to-ingredient procurement platforms:Digital marketplaces connect Prairie growers with North American supplement manufacturers. This channel innovation compresses traditional distributor margins and accelerates sample-to-contract velocity.
- Organic certification reciprocity:Canada-Japan equivalency agreements reduce duplicative audit costs for cross-border shipments. Certified suppliers capture price premiums in both jurisdictions without redundant compliance spend.
Industry Challenges
- Anthocyanin stability expertise:Formulation chemists with shelf-life prediction capabilities for polyphenol matrices command premium compensation. Talent scarcity constrains product development velocity at mid-scale manufacturers.
- Organic certification timeline:Three-year transition periods for conventional orchard conversions delay supply expansion. Growers require working capital bridges through non-certified revenue years.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Haskap Berry Powder Market Trends and Innovations
Processing technology convergence and regulatory claim pathways are restructuring how haskap powder moves from orchard to formulated product. Buyers now specify performance metrics that exceed traditional botanical ingredient standards.
Atmospheric freeze-drying with integrated real-time moisture monitoring is decomposing the quality variance that previously separated artisanal from industrial grades. Japanese functional food manufacturers specify these controlled-atmosphere systems for their anthocyanin retention guarantees. The technology is compressing price spreads between premium and standard freeze-dried tiers as consistency improves across supplier bases.
Japan's Foods with Function Claims system under CAA jurisdiction now recognizes haskap-derived anthocyanins for vascular health substantiation. This regulatory pathway permits packaged food labeling that was previously restricted to pharmaceutical channels. Supplement manufacturers in South Korea and Taiwan are pursuing equivalent registration to access this claim architecture.
Ingredient buyers now mandate third-party anthocyanin potency certificates prior to contract execution. North American dietary supplement brands reject shipments lacking HPLC-verified cyanidin-3-glucoside concentrations. This specification behavior is most visible in cardiovascular health positioning, where label claim defensibility determines retail placement.
Haskap Berry Powder Market Segmentation
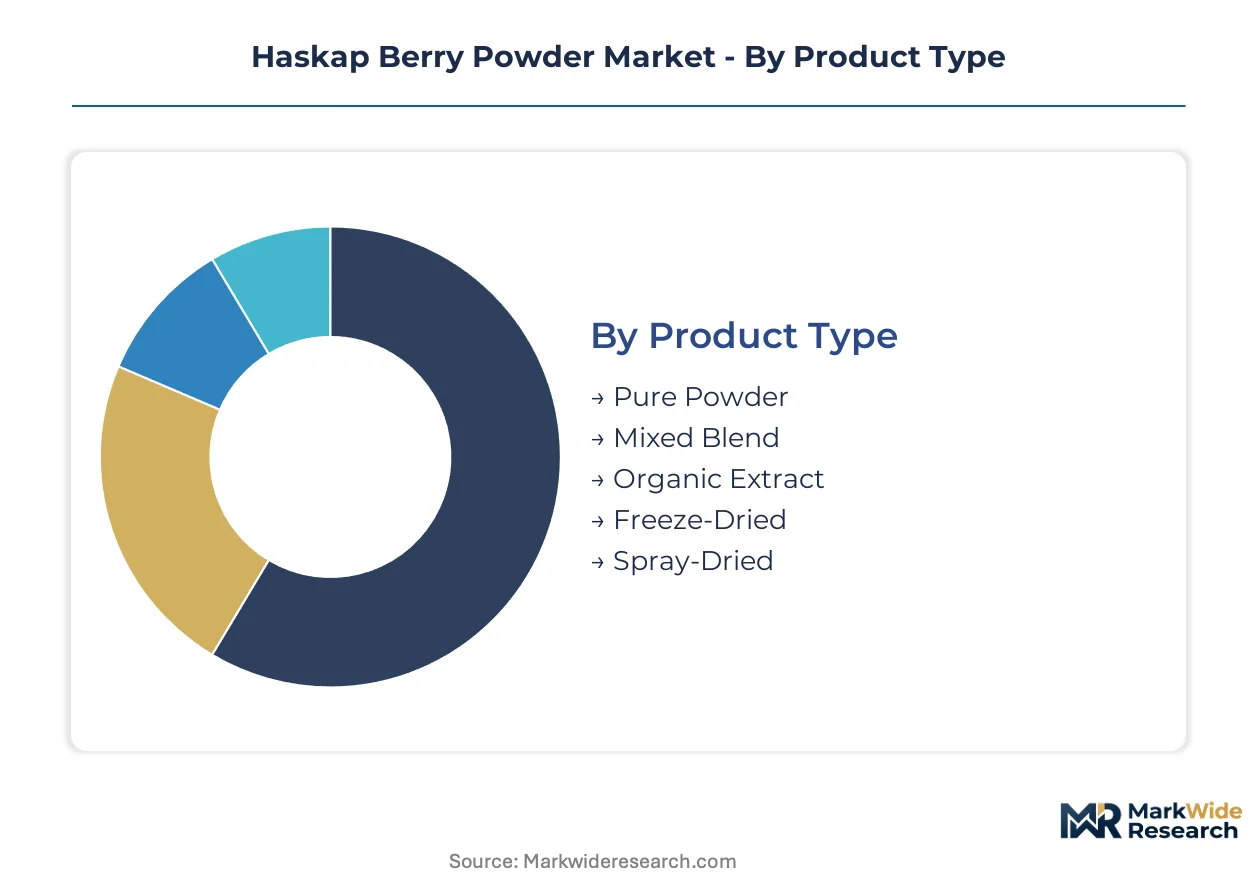
Procurement channels for haskap berry powder diverge sharply by specification tier. Freeze-dried organic grades flow through nutraceutical distributors with third-party potency verification, while spray-dried variants reach food manufacturers via commodity ingredient brokers.
Product Type:
Channel mix splits between premium nutraceutical distributors and commodity food ingredient brokers depending on bioactive retention certification.
- Freeze-Dried:Anthocyanin concentrations exceed 85 percent through low-temperature vacuum protocols. Japanese functional food manufacturers under CAA jurisdiction specify these grades for vascular health claims, absorbing 40-60 percent price premiums over spray-dried alternatives.
- Organic Extract:Solvent-free extraction meets EU organic certification reciprocity standards for cross-border shipment. Canadian Prairie growers leverage Canada-Japan equivalency agreements to reduce duplicative audit costs in both jurisdictions.
- Pure Powder:Single-ingredient specification for clean-label formulators seeking minimal processing disclosure.
- Mixed Blend:Pre-formulated combinations with carrier agents for beverage solubility optimization.
- Spray-Dried:Cost-optimized tier for volume dietary supplement blending where bioactive retention thresholds are lower.
Freeze-dried specifications dominate installed base in premium channels. Organic extract grades are where expansion concentrates as equivalency agreements mature.
Application:
Cost tier separation distinguishes clinical-positioned products from mass-market functional foods, with regulatory claim substantiation driving margin stratification.
- Dietary Supplements:Capsule and tablet formulators specify HPLC-verified cyanidin-3-glucoside concentrations prior to contract execution. North American brands reject shipments lacking third-party potency certificates, particularly for cardiovascular health positioning.
- Functional Food:Japan's Foods with Function Claims registration permits packaged food labeling previously restricted to pharmaceutical channels. South Korean and Taiwanese manufacturers pursue equivalent CAA-recognized registration to access this claim architecture.
- Nutraceuticals:Clinical validation of cognitive health properties deepens procurement specifications for bioactive matrices.
- Beverage Additives:Color stability in acidic formulations drives specification for South Korean functional beverage formulators.
- Personal Care:Anthocyanin antioxidant properties support topical formulation positioning in cosmetic pipelines.
Dietary supplements command value concentration through certification requirements. Functional food integration is climbing the fastest as regulatory pathways standardize.
End User:
Customer type determines specification stringency, with pharmaceutical-adjacent buyers imposing bioactive verification that commodity food producers bypass.
- Dietary Supplement Producers:Shelf-life prediction capabilities for polyphenol matrices command premium compensation for formulation chemists. Talent scarcity constrains product development velocity at mid-scale manufacturers.
- Food Manufacturers:Clean-label formulation mandates from Health Canada and Japan's Consumer Affairs Agency compress synthetic additive demand while elevating anthocyanin-rich botanical specifications.
- Beverage Firms:Acidic formulation stability requirements differentiate haskap from established blueberry and açai suppliers.
- Cosmetic Companies:Antioxidant topical applications drive smaller-volume, higher-margin procurement patterns.
- Health Clinics:Direct practitioner channel for clinical-grade powder distribution in functional medicine protocols.
Dietary supplement producers dominate specification intensity. Food manufacturers are where volume expansion concentrates.
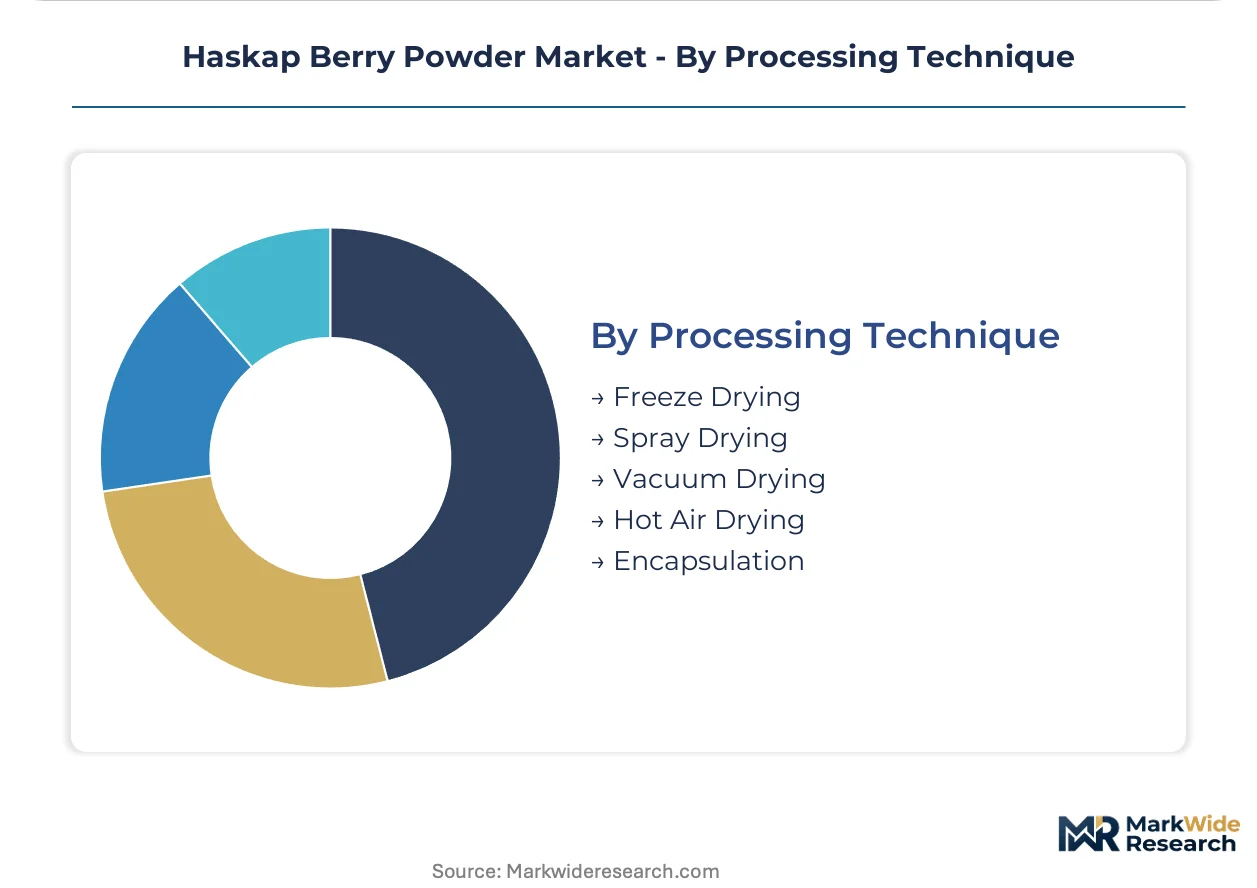
Processing Technique:
Supply concentration in Jilin Province freeze-dried capacity shapes geographic procurement risk profiles for Asian functional food buyers.
- Freeze Drying:Atmospheric systems with integrated real-time moisture monitoring decompose quality variance between artisanal and industrial grades. Japanese manufacturers specify controlled-atmosphere systems for anthocyanin retention guarantees.
- Vacuum Drying:Intermediate bioactive retention at lower energy intensity than freeze-drying protocols.
- Spray Drying:Volume leadership in cost-sensitive applications with faster throughput and lower unit economics.
- Hot Air Drying:Minimal capital requirement for entry-level processing, with corresponding bioactive degradation trade-offs.
- Encapsulation:Protective matrix technologies for shelf-life extension in complex formulation environments.
Freeze drying dominates premium tier installed base. Vacuum drying is where mid-tier expansion concentrates as energy cost pressures persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian Prairie growers export freeze-dried grades to Japanese functional food manufacturers under METI-backed equivalency agreements, while Jilin Province freeze-dried output supplies South Korean beverage formulators seeking anthocyanin alternatives to established blueberry suppliers.
Japan
Consumer Affairs Agency Foods with Function Claims registration drives procurement of HPLC-verified cyanidin-3-glucoside grades for vascular health positioning. METI coordinates equivalency recognition with Canadian organic certification bodies. Tokyo-based formulators specify controlled-atmosphere freeze-dried tiers for shelf-space advantages in convenience retail channels.
Canada
Saskatchewan cultivation clusters aggregate organic acreage under single-origin traceability systems demanded by North American supplement brands. Health Canada clean-label mandates compress synthetic additive demand in functional food pipelines. Prairie provinces processing facilities supply domestic brands with domestic sourcing narratives for premium positioning.
South Korea
Functional beverage formulators seek differentiated anthocyanin sources beyond established açai suppliers for acidic formulation stability. MFDS regulatory pathways for functional claims are accelerating haskap powder incorporation into cardiovascular health products. Seoul-based manufacturers specify color-stable grades for ready-to-drink positioning in convenience store channels.
China
Jilin Province freeze-dried capacity dominates Asian functional food procurement with concentrated supply from Changchun processing clusters. SAMR novel food ingredient oversight shapes import requirements for cross-border shipments. DaXingAnLing region growers supply organic extract grades meeting EU equivalency standards for European nutraceutical distributors.
United States
FDA dietary supplement cGMP enforcement elevates third-party potency certificate requirements for anthocyanin matrices. Pacific Northwest cultivation trials expand domestic supply alternatives to Prairie province imports. California-based functional food startups specify clean-label grades for natural product channel placement.
Haskap Berry Powder Market Competitive Landscape
Listed leaders compete with private specialists across specification tier depth, with public companies dominating freeze-dried capacity investment while family-held operations retain organic certification agility. The structure segments into three archetypes: vertically integrated cultivator-processors, contract manufacturing specialists, and regional trading houses. Capacity expansion and geographic certification reciprocity represent the dominant competitive moves.
Within the integrated cultivator-processor tier, Haskapa and BIOHASKAP exemplify geographic anchoring strategies, with UK-based and Saskatchewan-based operations respectively representing premium-channel and domestic-sourcing archetypes. Jilin Longze Biotechnology occupies a position in Asian freeze-dried supply concentration. These three entities represent the spectrum from European nutraceutical positioning to North American traceability narratives to Asian volume leadership.
| Leading Market Players |
|---|
| Haskapa |
| BIOHASKAP |
| Prairie Hill Farms |
| Phytimpact |
| Vigorous-tech |
| Jilin Longze Biotechnology |
| DaXingAnLing Lingonberry |
| Boreal Biotech |
| Shanxi Xintianyu Biotechnology |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between Saskatchewan cultivation clusters and Japanese functional food manufacturers lock in freeze-dried supply access while fixing price visibility through the Canada-Japan organic certification equivalency window. These contract structures insulate premium-grade procurement from spot-market volatility in natural gas-dependent European processing facilities.
Pricing Analysis
Freeze-drying technology-generation pricing gaps separate atmospheric controlled-atmosphere systems from conventional vacuum protocols, with the former commanding 40-60 percent premiums for anthocyanin retention guarantees. Pricing stratifies across premium, standard, and economy tiers driven by certification level (organic equivalency status) and volume scale. Cost compression in spray-dried grades is intensifying because energy price volatility in European natural gas markets feeds through to processing economics. Dietary supplement producers exhibit least price sensitivity due to HPLC-verified potency requirements, while beverage formulators absorb greatest pressure from acidic formulation stability specifications.
Supply Chain Analysis
Canada and China anchor freeze-dried haskap powder production, with Saskatchewan cultivation clusters supplying North American traceability narratives and Jilin Province processing facilities feeding Asian functional food procurement. Raw material dependencies center on organic orchard establishment timelines, low-temperature vacuum drying equipment, and HPLC verification laboratory capacity. Single-source vulnerability concentrates in Changchun processing clusters where weather events or logistics disruptions cascade through Asian buyer inventories. Distribution runs through nutraceutical distributors for premium certified grades and commodity ingredient brokers for volume spray-dried tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Haskap berry powder demand is recovering from regulatory friction cycles as Japan's Foods with Function Claims system and South Korean MFDS pathways mature, creating predictable claim architectures that justify premium ingredient procurement.
For Market Incumbents: Fortify freeze-dried capacity positions through backward integration into Saskatchewan organic acreage expansion, securing single-origin traceability systems that North American supplement brands specify for domestic sourcing narratives. Invest in atmospheric controlled-atmosphere drying technology to compress quality variance and defend margin position against emerging Jilin Province competitors with energy cost advantages. For New Entrants and Emerging Players: Canada-Japan organic certification equivalency fast-track offers lowest barrier entry for cross-border shipment qualification, enabling price premium capture in Tokyo functional food channels without duplicative audit costs. Target South Korean beverage formulators seeking anthocyanin alternatives to established açai suppliers, leveraging color stability advantages in acidic formulations as differentiated go-to-market positioning. For Investors and Strategic Acquirers: The market sits at a regulatory validation phase that favors vertically integrated cultivator-processors with established equivalency agreements and proven anthocyanin retention technology. Long-term viability over the next decade hinges on organic certification reciprocity expansion and clinical validation depth for cardiovascular health claims. Watch EFSA novel food authorization timeline compression as inflection indicator for European market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Atmospheric Freeze-Drying Capacity Expansion | Japanese CAA-registered manufacturers specify controlled-atmosphere systems for anthocyanin retention guarantees in vascular health products. |
| Organic Certification Equivalency Investment | Canada-Japan equivalency agreements reduce duplicative audit costs and accelerate cross-border shipment velocity for certified suppliers. |
| Saskatchewan Acreage Aggregation | Single-origin traceability systems demanded by North American supplement brands support domestic sourcing narratives and price premium capture. |
| South Korean MFDS Registration Pursuit | Seoul-based beverage manufacturers seek differentiated anthocyanin sources with color stability in acidic ready-to-drink formulations. |
| Direct-to-Ingredient Platform Development | Digital marketplaces connecting Prairie growers with supplement manufacturers compress traditional distributor margins and accelerate sample-to-contract velocity. |
Research Methodology
Cross-validation between primary interviews with ingredient procurement officers and secondary validation through Health Canada novel food filings anchors the qualitative findings in this analysis. The research program combined structured discussions with functional food formulators, organic certification auditors, freeze-drying equipment specialists, and nutraceutical distribution channel managers alongside regulatory database review of CAA Foods with Function Claims registrations, METI equivalency documentation, and EFSA novel food authorization timelines. Bottom-up orchard capacity modeling and top-down functional food ingredient demand estimation provided triangulation checks.
Sensitivity analysis around natural gas price volatility scenarios and organic certification conversion timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include processing technique tier, application category, certification status, and geographic regulatory cluster. CAGRs were derived from installed capacity expansion schedules and claim registration velocity through Japan's CAA system. Industry-specific forecast inputs incorporated anthocyanin potency verification adoption curves and equivalency agreement negotiation status between major producing and consuming jurisdictions.
Decision-makers should treat outputs as directional under base assumptions of sustained Canada-Japan organic equivalency and stable MFDS registration pathway access; material deviation in regulatory reciprocity or energy cost trajectories would warrant model refresh. Recalibration cycles align with material shifts in Foods with Function Claims registration velocity and freeze-drying technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.