
 United States Guacamole Market | 2026-2036
United States Guacamole Market Size, Share, and Industry Trends Forecast 2026-2036
United States Guacamole Market Intelligence
Market Context with Strategic Players
Premium-grade Hass avocado specification is collapsing into mainstream retail as private-label and branded producers race to match restaurant-quality texture and flavor stability. Sabra Dipping Co LLC leverages its refrigerated dips infrastructure to sustain national distribution of high-pressure processed guacamole with extended shelf life. Calavo Growers Inc. anchors the upstream supply chain through its integrated avocado sourcing and ripening operations in California and Mexico. Hormel Foods Corporation differentiates via its refrigerated foods division, competing on food-service portion packs and retail club-channel formats.
Technical Definition and Structural Segments
Guacamole is a prepared avocado-based dip or spread, traditionally composed of mashed Hass avocados, lime juice, salt, and variable inclusions such as jalapeño, tomato, onion, or cilantro, with commercial formulations specifying minimum avocado solids content and pH control for pathogen inhibition. The product serves as a condiment, appetizer, or ingredient across retail grocery, food-service, and institutional channels, with shelf-stable, refrigerated, and frozen variants matching distinct operational requirements. Organic product type commands disproportionate margin attention as USDA-certified supply tightens and price premiums persist above conventional equivalents. Food service distribution channel leads absolute volume throughput, while online retail posts the fastest expansion as direct-to-consumer cold-chain logistics mature. Glass jar packaging retains preference in premium retail positioning, though plastic tub formats dominate unit economics across mass-market supermarkets.
Regulatory Frame and Forward-Looking Close
The FDA governs guacamole under acidified food regulations and Hazard Analysis Critical Control Point protocols, with USDA organic certification creating a parallel compliance track for certified product lines. California Department of Food and Agriculture inspection requirements for incoming Mexican avocados add a state-level layer to federal phytosanitary controls, shaping inbound supply timing and cost structures. Stakeholders must monitor whether evolving FDA front-of-package nutrition labeling proposals and potential sodium-targeting guidance will force reformulation investments or channel repositioning across existing product portfolios.
Market Dynamics
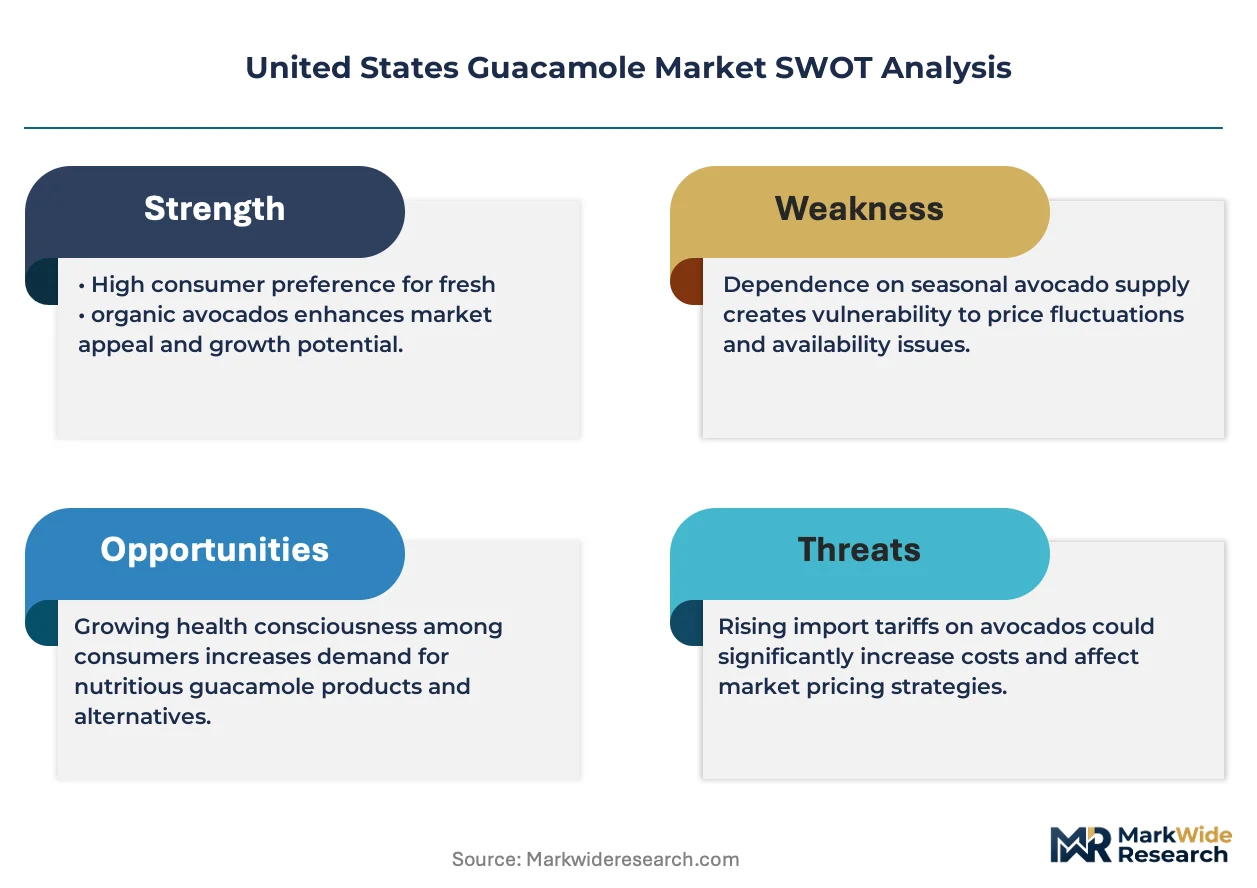
Hass avocado supply concentration in Michoacán and California's Central Valley is forcing US processors to redesign inventory models around harvest volatility and cross-border phytosanitary inspection delays.
Growth Catalysts
- FDA acidified food regulations:Standardized pH and water activity requirements for pathogen control have professionalized manufacturing protocols, elevating food safety credibility across retail and food-service channels.
- Fast-casual dining expansion:Chipotle-style assembly formats and QSR fresh-mex concepts are normalizing guacamole as a standard condiment rather than specialty add-on, embedding volume demand in commercial kitchen specifications.
- High-pressure processing technology:Cold pasteurization methods extend refrigerated shelf life without thermal degradation of texture or flavor, unlocking broader distribution radius for fresh-format products.
Market Restraints
- Perishability constraints:Enzymatic browning and microbial spoilage compress finished goods inventory turns, forcing cold-chain infrastructure investments that inflate delivered cost to secondary markets.
- Single-origin supply risk:Mexican avocado imports face recurrent suspension threats from USDA APHIS due to pest detections, exposing processors to abrupt raw material access interruptions.
- Labor-intensive production:Hand-scooping and batch-mixing operations resist full automation, constraining throughput scalability and compressing margins against mechanized dip categories.
Strategic Opportunities
- USDA organic certification pipeline:Tightened organic avocado supply is creating scarcity premiums for certified processors who secure contracted acreage in California's San Joaquin Valley.
- Direct-to-consumer subscription models:Cold-chain logistics maturation enables fresh guacamole delivery to households, bypassing retail slotting fees and capturing full margin on recurring revenue.
- Clean-label reformulation:Removal of synthetic preservatives and acidulants aligns with FDA front-of-package nutrition labeling trends, positioning products for health-claim differentiation in club and natural channels.
Industry Challenges
- Skilled production workforce scarcity:Experienced operators capable of managing high-pressure processing equipment and HACCP documentation command wage premiums that strain mid-scale processor economics.
- Multi-jurisdictional compliance complexity:Simultaneous adherence to FDA acidified food rules, California Department of Food and Agriculture inspection protocols, and USDA organic handling requirements extends new product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Guacamole Market |
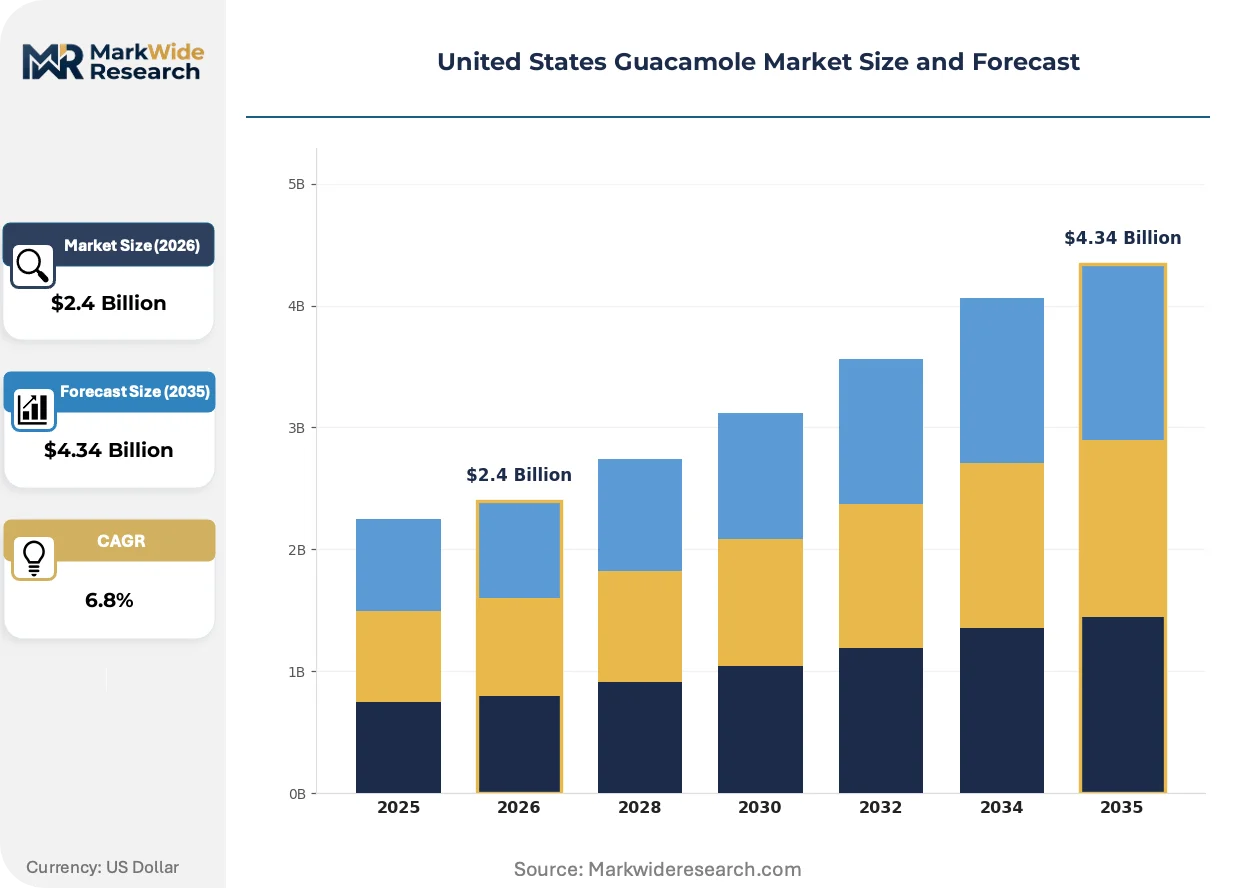
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Spicy, Chunky Distribution Channel: Supermarkets, Online Retail, Food Service, Convenience Stores Packaging Type: Glass Jar, Plastic Tub, Pouch, Bulk End User: Households, Restaurants, Cafes, Caterers |
| Companies Covered | Sabra Dipping Co LLC, Avo-King International Inc., Hormel Foods Corporation, B&G Foods Inc., Ventura Foods LLC, Calavo Growers Inc., Conagra Brands Inc., Snowcrest, Casa Sanchez SF, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Guacamole Market Strategic Shifts & Innovations
Processing technology and packaging formats are diverging between premium fresh-positioned products and value-engineered extended-shelf-life alternatives, fragmenting equipment investment strategies across the supplier base.
High-pressure processing systems are bifurcating the refrigerated guacamole segment into two distinct quality tiers. National retail chains and institutional food-service buyers are adopting HPP-equipped supplier networks to secure 30-to-45-day refrigerated codes. This technology compression is marginalizing traditional thermal pasteurization lines and forcing capital allocation decisions that favor scale concentration among multi-regional processors.
FDA's evolving front-of-package nutrition labeling proposals are pressuring sodium disclosure and serving-size standardization across prepared dip categories. Reformulation investments to reduce salt content without compromising flavor stability are redirecting R&D budgets toward natural acidulant blends and umami-enhancing ingredients. Clean-label product lines in California and Texas retail channels are responding fastest, anticipating competitive disadvantage if federal guidance mandates icon-based warning systems.
Food-service procurement consolidation through broadline distributors is compressing supplier counts and extending payment terms for guacamole manufacturers. Regional restaurant groups are migrating from direct-producer relationships to Sysco and US Foods contract tiers, displacing smaller processors unable to meet volume and traceability requirements. This channel shift is most visible in Florida's tourism-dependent hospitality corridor, where multi-unit operators prioritize supply security over local sourcing preferences.
United States Guacamole Market Segmentation
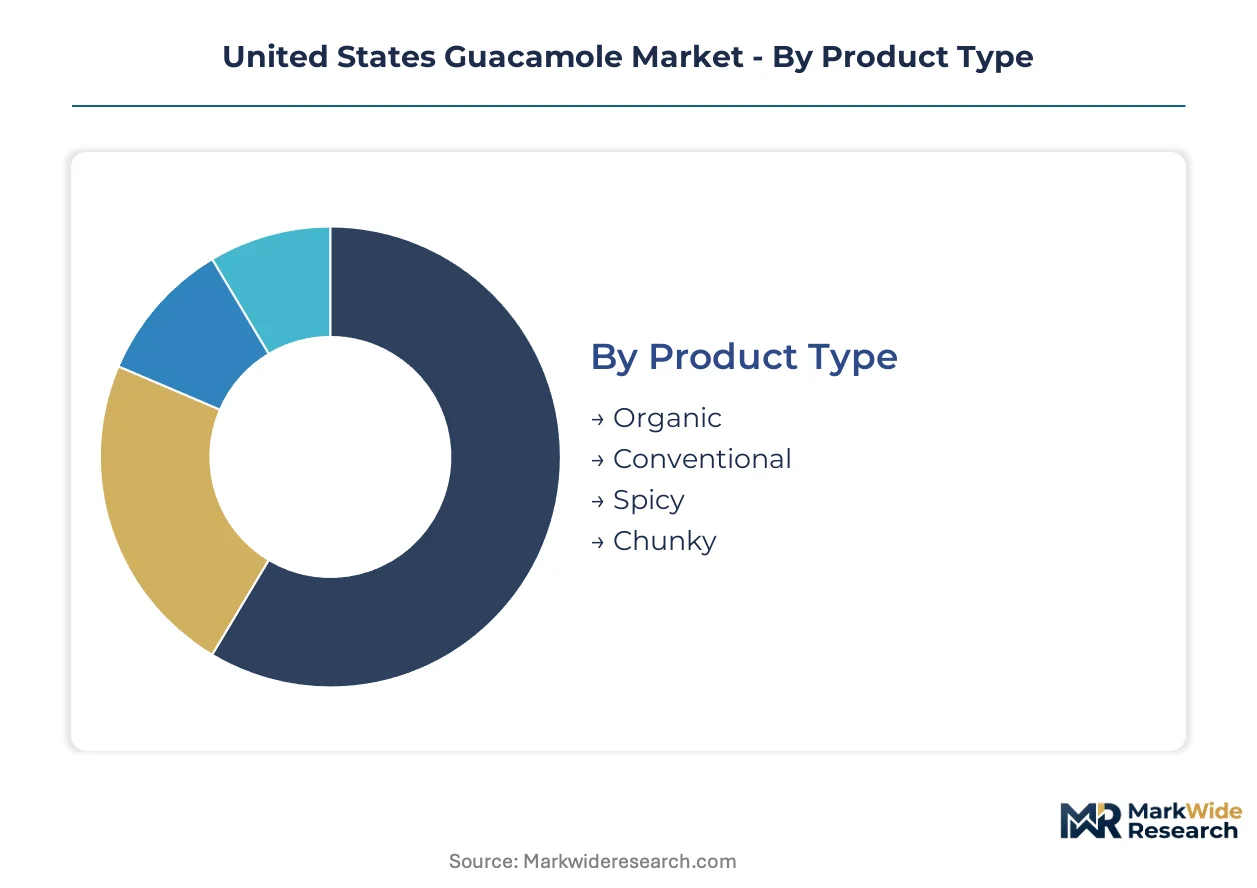
Segmentation in the US guacamole market reveals how supply chain configuration and channel economics fragment competitive strategy. Each dimension—product certification, distribution format, packaging technology, and end-use application—creates distinct margin profiles and operational requirements that processors must navigate simultaneously.
Product Type:
Organic supply concentrates in California's certified acreage, while conventional formats draw heavily from Michoacán import streams. Spicy and chunky variants split between domestic formulation kitchens and regional taste preferences in Texas and Florida.
- Organic:USDA-certified Hass avocados from California's San Joaquin Valley command scarcity premiums due to contracted acreage limitations. Demand clusters in natural grocery channels and club stores where clean-label positioning justifies price elevation.
- Conventional:Mexican-sourced fruit dominates volume throughput, with processors managing phytosanitary inspection delays at California border crossings. This tier supplies mass-market retail and food-service accounts where cost efficiency outweighs certification claims.
- Spicy:Jalapeño and serrano inclusions target Texas and Southwest regional palates through retail salsas and food-service portion packs.
- Chunky:Textured formulations with visible avocado pieces serve premium restaurant applications and deli counter positioning.
Conventional commands the established base. The steepest expansion runs through organic as certified supply tightens and price premiums persist.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin capture potential, with food-service volume contrasting against direct-to-consumer experimentation.
- Supermarkets:Refrigerated case placement in Kroger, Albertsons, and regional banners drives national brand visibility. Slotting fees and promotional calendars compress net margins for emerging suppliers.
- Food Service:Broadline distributor consolidation through Sysco and US Foods defines procurement standards for restaurant chains. This channel leads absolute volume throughput with strict traceability and portion-pack specifications.
- Online Retail:Subscription models and direct-to-consumer cold-chain logistics are maturing fastest, bypassing retail slotting fees.
- Convenience Stores:Single-serve and snack-pack formats target grab-and-go consumption in travel corridors and urban convenience networks.
Food service anchors volume scale. Online retail is climbing the fastest as cold-chain logistics mature and subscription economics improve.
Packaging Type:
Material selection reflects shelf-life requirements against sustainability positioning, with premium retail favoring glass and mass-market optimizing plastic unit economics.
- Glass Jar:Premium retail positioning in natural channels and gift-oriented assortments retains consumer preference for perceived quality and reusability.
- Plastic Tub:Polypropylene and PET formats dominate mass-market supermarkets with lower per-unit cost and lighter shipping weight.
- Pouch:Flexible packaging for single-serve and food-service portion control reduces material waste and storage footprint.
- Bulk:Food-service and institutional buyers receive refrigerated totes or bag-in-box formats for high-volume kitchen operations.
Plastic tub formats capture the volume base. Pouch packaging is gaining share fastest through convenience and food-service efficiency demands.
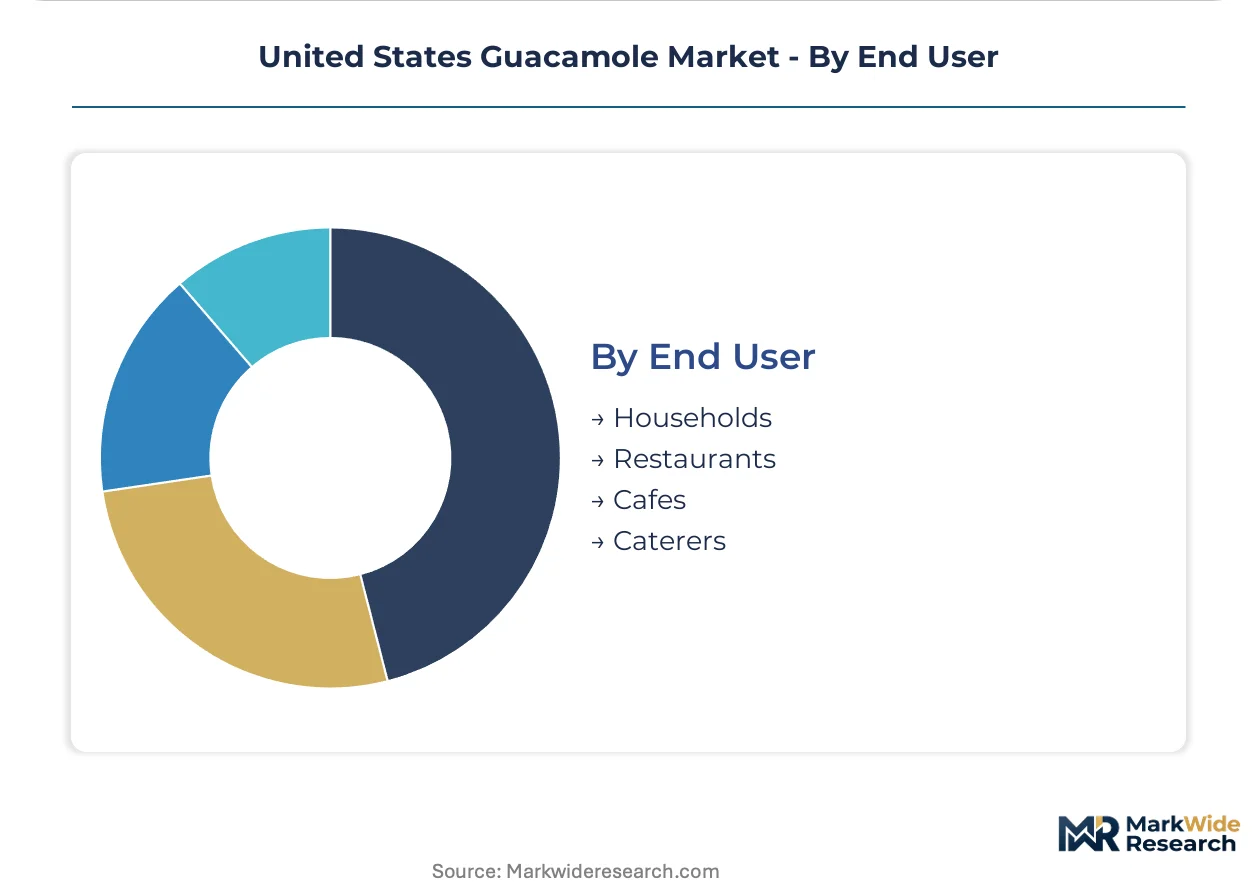
End User:
User segmentation separates at-home consumption patterns from commercial kitchen specifications, with restaurant procurement consolidating while household channels fragment.
- Households:Retail purchase decisions in California, Texas, and Florida concentrate around freshness dating, brand recognition, and price promotion sensitivity.
- Restaurants:Fast-casual chains like Chipotle normalize guacamole as standard condiment rather than specialty add-on, embedding volume in commercial specifications.
- Cafes:Coffee shop and bakery channels adopt smaller portion formats for breakfast and snack applications.
- Caterers:Event-service providers require bulk formats with extended hold times and transport-stable texture.
Restaurants command the established demand base. Household direct-to-consumer channels show the steepest expansion trajectory through subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hass avocado supply chains concentrate in California's Central Valley and Michoacán's avocado belt, creating geographic interdependence that shapes processing capacity placement and cold-chain logistics across the United States.
California
California's San Joaquin Valley hosts the nation's densest concentration of USDA-certified organic avocado acreage, with processors clustering near Fresno and Visalia to minimize post-harvest handling. State Department of Food and Agriculture inspection protocols for Mexican imports add compliance layers at border crossings in San Diego and Otay Mesa. The Oxnard-Ventura corridor anchors ripening and distribution infrastructure serving West Coast retail chains.
Texas
Texas demand concentrates in Dallas-Fort Worth and Houston metro areas, where fast-casual dining expansion and Hispanic food culture intersect. FDA acidified food regulations govern processing facilities in the Rio Grande Valley that handle cross-border fruit movements. Laredo and McAllen function as critical transshipment nodes where phytosanitary inspections delay inbound Mexican avocados during peak harvest windows.
Florida
Florida's tourism-dependent hospitality corridor generates concentrated food-service demand in Orlando and Miami, with broadline distributor consolidation favoring suppliers meeting Sysco and US Foods traceability specifications. State agricultural inspection requirements complement federal USDA APHIS protocols for Mexican avocado entry through Gulf ports. The Tampa-St. Petersburg market shows emerging direct-to-consumer subscription activity as cold-chain logistics mature.
New York Metro
The Northeast corridor's premium retail channels absorb high-pressure processed guacamole with extended shelf life, justifying transportation costs from Midwest and Mid-Atlantic production facilities. FDA front-of-package nutrition labeling proposals drive reformulation activity among suppliers serving Whole Foods and regional natural grocery banners. Brooklyn and Queens host emerging direct-to-consumer fulfillment operations bypassing traditional retail slotting structures.
Illinois
Chicago's central logistics position supports national distribution hub operations for refrigerated guacamole serving mass-market retail banners across the Midwest. Illinois Department of Agriculture food safety inspections align with FDA HACCP requirements for acidified food manufacturing. The broader Midwest manufacturing belt shows limited primary processing capacity, relying instead on inbound shipments from California and Texas production zones.
United States Guacamole Market Key Industry Players
Concentration sits with integrated avocado handlers and diversified refrigerated foods manufacturers who control upstream sourcing and downstream distribution simultaneously. The vendor base separates into three functional tiers: national brand owners with broadline distribution, regional processors serving food-service accounts, and emerging direct-to-consumer specialists. Strategic moves center on securing contracted organic acreage in California and deploying high-pressure processing capacity to extend distribution radius without thermal degradation.
Within the integrated handler tier, Calavo Growers Inc. and Hormel Foods Corporation exemplify divergent approaches to supply chain control, with the former anchoring upstream sourcing operations and the latter leveraging refrigerated foods infrastructure for food-service penetration. Sabra Dipping Co LLC occupies a position emphasizing national retail distribution through established cold-chain networks. These three entities represent distinct archetypes: agricultural integrator, diversified food manufacturer, and refrigerated dips specialist.
| Leading Market Players |
|---|
| Sabra Dipping Co LLC |
| Avo-King International Inc. |
| Hormel Foods Corporation |
| B&G Foods Inc. |
| Ventura Foods LLC |
| Calavo Growers Inc. |
| Conagra Brands Inc. |
| Snowcrest |
| Casa Sanchez SF |
| Others |
Cost & Logistics Intelligence
High-pressure processing technology substitution for thermal pasteurization simultaneously shifts processing capacity toward California and Texas production zones while compressing price premiums between fresh-format and extended-shelf-life tiers. This equipment transition redraws supply geography and pricing economics across the US guacamole market.
Pricing Analysis
FDA acidified food regulations dictate the pricing tier structure across organic, conventional, spicy, and chunky product variants. Three-tier pricing structure across premium organic, standard conventional, and economy food-service tiers separates certified California fruit from Mexican-import conventional supply. Cost compression in the conventional tier intensifies because broadline distributor consolidation extends payment terms and demands volume discounts. Food-service procurement managers show highest price sensitivity, while natural grocery channel buyers accept organic premiums for clean-label positioning.
Supply Chain Analysis
Otay Mesa and Laredo border crossings function as chokepoints where USDA APHIS phytosanitary inspections delay inbound Mexican Hass avocados during peak harvest windows. Supply draws from Michoacán's avocado belt, California's Central Valley, and limited Peruvian counter-seasonal imports. Raw material flows hinge on lime juice concentrates, jalapeño sourcing from New Mexico, and high-barrier packaging films. Single-origin concentration in Michoacán creates tariff exposure and pest-detection suspension vulnerability. Distribution runs through refrigerated trucking networks anchored at Dallas-Fort Worth and Chicago hub operations serving mass-market retail banners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Skilled operators capable of managing HACCP documentation and high-pressure processing equipment command wage premiums that exceed mid-scale processor absorption capacity, creating a structural talent scarcity that shapes competitive outcomes.
For Market Incumbents: Secure contracted organic acreage in California's San Joaquin Valley before scarcity premiums harden, and deploy additional high-pressure processing capacity to extend distribution radius without thermal degradation. Emerging direct-to-consumer specialists threaten margin capture in household channels. Backward integration into ripening operations represents the priority defensive lever. For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription models bypassing retail slotting fees, and target the Tampa-St. Petersburg corridor where cold-chain logistics maturity lags West Coast benchmarks. Household subscription economics show lowest competitive saturation. A go-to-market angle emphasizing chef-curated flavor profiles and customizable heat levels differentiates against mass-market incumbent positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with captive organic supply and HPP-equipped facilities. Long-term viability across a five-to-ten-year window favors agricultural integrators over pure-play refrigerated foods manufacturers. Acquisition target archetype: mid-scale California processors with USDA organic certification pipeline and underutilized production capacity. The signal to watch is FDA front-of-package nutrition labeling finalization timing as a reformulation cost inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captive supply from California's San Joaquin Valley secures scarcity premiums against Mexican import volatility. |
| High-Pressure Processing Capacity Expansion | Thirty-to-forty-five day refrigerated codes unlock national distribution for fresh-format products without thermal degradation. |
| Direct-to-Consumer Channel Launch | Subscription models bypass Kroger and Albertsons slotting fees while capturing full household margin. |
| Clean-Label Reformulation Investment | Removal of synthetic acidulants aligns with FDA front-of-package sodium disclosure trends in natural grocery channels. |
| Broadline Distributor Contract Tier Entry | Sysco and US Foods procurement consolidation demands traceability systems that displace regional food-service competitors. |
Research Approach
The analysis maps organic certification pipelines, HPP technology adoption tiers, and food-service procurement consolidation patterns, each validated through category buyers at retail banners, operations directors at fast-casual chains, and procurement leads at broadline distributors. Primary interviews with plant managers at California processing facilities, regulatory affairs specialists navigating FDA acidified food compliance, and cold-chain logistics coordinators supplemented secondary validation through USDA APHIS inspection data, FDA guidance documents, California Department of Food and Agriculture protocols, and refrigerated trucking rate benchmarks. Bottom-up volume modeling across product type, distribution channel, packaging format, and end-user segments triangulated against top-down category spend estimates.
Model outputs were cross-checked against external benchmarks including Nielsen retail audit movement data, food-service distributor shipment reports, and organic certification acreage filings. Segmentation dimensions across the projection horizon include product certification tier, channel cold-chain intensity, packaging shelf-life specification, and regional consumption cluster. CAGRs were derived from trend extrapolation of volume throughput by segment, adjusted for HPP penetration rates and organic supply constraints. Industry-specific forecast inputs encompass Mexican avocado harvest variability indices and phytosanitary inspection delay distributions at California border crossings.
Underlying assumptions cover sustained FDA acidified food regulatory stability, continued Hass avocado import authorization from Michoacán, and maturation of direct-to-consumer cold-chain logistics, with deviation risk concentrated in USDA APHIS suspension events and organic acreage conversion rates. Revision becomes warranted when FDA front-of-package nutrition labeling mandates cross implementation thresholds or when broadline distributor consolidation accelerates beyond current Sysco and US Foods contract tier expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
US Vegetable Puree Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Mulberry Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Dried Kiwi Fruit Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Global Orange Market
Fruits and Vegetables
Aronia Berries Market