
 Global IQF Fruits Market | 2026-2036
Global IQF Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Global IQF Fruits Market Outlook
Buyer concentration in the food service channel is broadening as regional smoothie chains and ghost kitchen operators diversify procurement beyond legacy frozen food distributors. Dole Food Company leverages its plantation-to-freezer infrastructure in Latin America to secure year-round mango and pineapple supply. Greenyard NV anchors European retail demand through dedicated IQF lines in Poland and Belgium. SunOpta Inc. specializes in organic berry IQF output for North American private-label customers, competing on clean-label certification rather than commodity volume.
Individually quick frozen fruits are fresh produce items blast-frozen at temperatures below minus thirty degrees Celsius within hours of harvest, preserving cellular structure, vitamin content, and texture for industrial and retail applications. The process involves washing, sorting, dicing, and rapid individual freezing on fluidized bed tunnels to prevent clumping. Berries dominate premium grade allocation due to concentrated antioxidant demand from functional beverage manufacturers, while standard grade bananas and mangoes flow primarily into food service smoothie bases where cost efficiency outweighs visual perfection. Organic grade commands tighter supply pools as certified acreage conversion lags behind frozen retail label growth.
FDA food safety modernization rules enforce hazard controls across imported IQF berry supply chains entering the United States, while EU REACH and F-Gas Regulation restrict cryogenic freezing agent chemistry in European processing plants. BIS standards in India govern microbial limits for frozen fruit exports, shaping which processors qualify for cross-border retail contracts. Stakeholders must monitor evolving cold chain traceability mandates and energy cost trajectories to determine whether regional hub freezing or origin-country processing delivers sustainable margin protection.
Market Dynamics
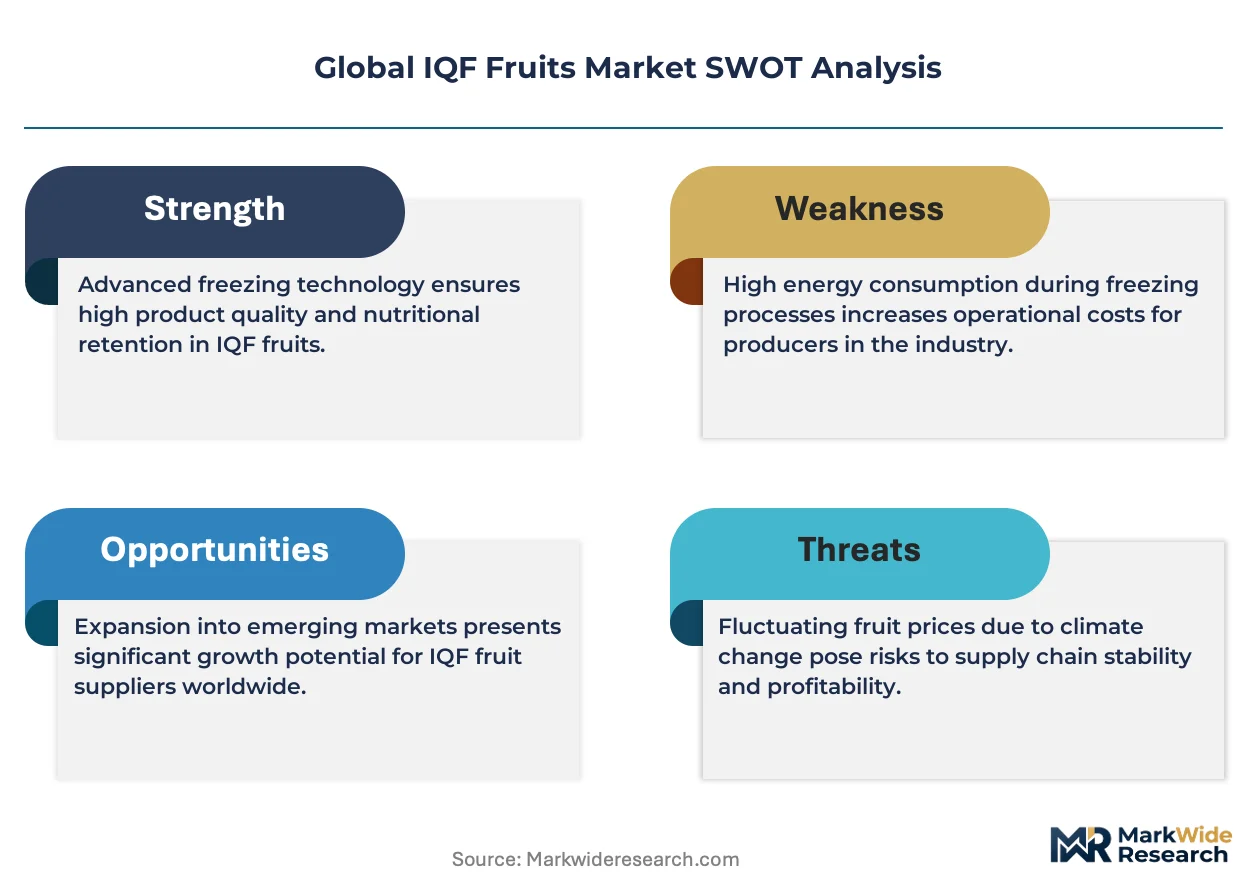
The EU Green Deal's farm-to-fork sustainability targets are compressing processor margins and forcing capital redeployment toward lower-carbon blast freezing infrastructure and closed-loop water recovery systems.
Growth Catalysts
- Smoothie chain procurement expansion:Regional beverage operators are bypassing legacy distributors to source directly from Polish and Belgian freezing facilities, accelerating volume throughput at origin-country processors.
- Organic certification premiums:Functional beverage manufacturers in North America are locking multi-year contracts for certified organic berry supply, pulling acreage conversion faster than frozen retail label growth can absorb.
- FDA modernization enforcement:Hazard control mandates across imported berry supply chains are consolidating qualified supplier pools, advantaging processors with integrated plantation-to-freezer traceability systems.
Market Restraints
- Cryogenic agent cost volatility:EU F-Gas Regulation restrictions on hydrofluorocarbon chemistry are narrowing freezing agent options and compressing processor input cost predictability.
- Polish processing concentration:Greenyard NV and Ardo NV facilities near Warsaw anchor European retail supply, creating geographic vulnerability to regional energy price spikes or logistics disruption.
- Fresh fruit substitution in food service:Short-haul refrigerated distribution improvements are enabling some smoothie operators to switch to chilled produce during peak harvest windows.
Strategic Opportunities
- Indian export qualification:BIS microbial standard compliance is unlocking cross-border retail contracts for processors able to meet frozen fruit export protocols, opening underserved South Asian supply capacity.
- Ghost kitchen channel penetration:Virtual restaurant operators are building direct procurement relationships for IQF mango and pineapple bases, bypassing traditional food service distribution markups.
- Clean-label private-label convergence:North American retailers are consolidating organic berry sourcing under single-processor certification umbrellas, rewarding scale players with multi-SKU contract breadth.
Industry Challenges
- Cold chain traceability system integration:Processors must retrofit legacy freezing lines with blockchain-enabled lot tracking to satisfy EU and FDA audit requirements, stretching IT capital allocation.
- Certified organic acreage conversion timelines:Three-year transition periods for soil certification are lagging behind frozen retail label growth, constraining supply pool expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IQF Fruits Market |
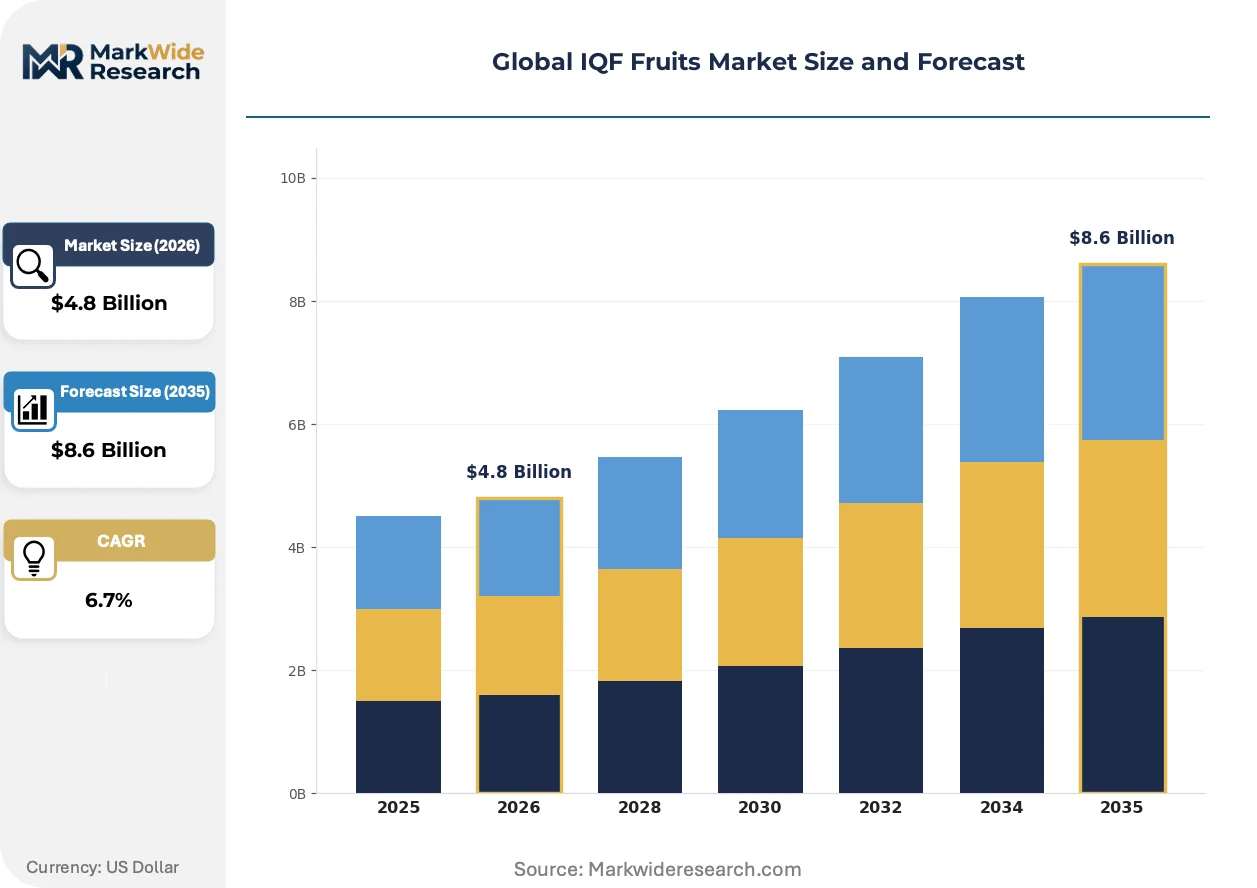
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Berries, Bananas, Mangoes Grade: Premium, Standard, Organic, Conventional End User: Food Service, Retail, Industrial, Hospitality Packaging Type: Cartons, Bags, Trays, Bulk |
| Companies Covered | Dole Food Company, Ardo NV, Greenyard NV, SunOpta Inc., McCain Foods, Conagra Brands Inc., Simplot, Bonduelle, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IQF Fruits Market Strategic Shifts
Fluidized bed tunnel engineering and cryogenic chemistry controls are compressing freezing cycle times while regulatory pressure on carbon intensity is reshaping capital deployment priorities across processing facilities.
Advanced fluidized bed tunnel systems with nitrogen injection controls are achieving sub-thirty-second individual fruit freezing cycles. Premium functional beverage manufacturers are specifying these systems in supplier qualification audits. This compression of processing time is electrifying competitive differentiation around vitamin retention rates and cellular structure integrity.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbons are forcing processor retrofits of blast freezing infrastructure. Industrial consequence includes accelerated adoption of mechanical compression alternatives and ammonia-based systems. Polish and Belgian facilities are most affected, with Greenyard NV and Ardo NV converting lines ahead of mandated deadlines.
Direct procurement relationships between smoothie chains and origin-country processors are displacing layered distributor networks. Ghost kitchen operators and regional beverage chains are negotiating volume commitments with Latin American plantation-freezer integrators. This channel compression is most visible in North American metropolitan markets where Dole Food Company leverages its captive supply infrastructure.
Global IQF Fruits Market Segmentation
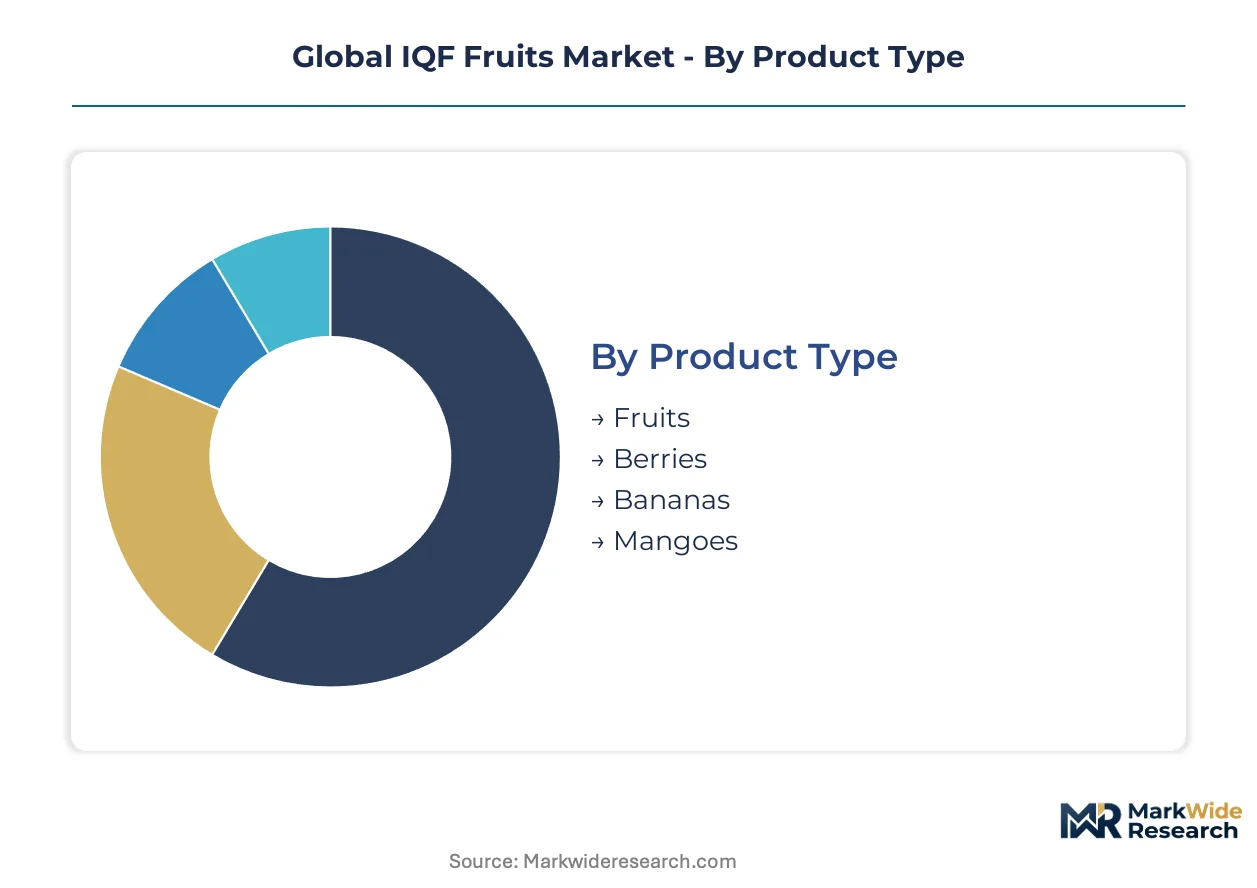
IQF fruit procurement decisions split across four independent axes: raw material characteristics determine processing yield and antioxidant retention; certification grade dictates contract pricing and retail channel access; end-use application shapes freezing protocol and packaging format; while logistics configuration governs cold chain cost and shelf-life extension.
Product Type:
Buyer specifications around cellular integrity, sugar content, and seasonal availability drive product-level procurement prioritization.
- Fruits:IQF pineapple, peach, and melon segments undergo rapid freezing at minus thirty-five degrees Celsius to preserve brix levels and texture for industrial smoothie bases. Demand concentrates in Latin American plantation-freezer integrators supplying North American metropolitan ghost kitchen networks, where year-round consistency outweighs single-origin premiums.
- Berries:Strawberries, blueberries, and raspberries dominate antioxidant-grade procurement from functional beverage manufacturers. Polish and Belgian freezing facilities anchor European retail supply, with organic certification premiums pulling acreage conversion faster than frozen label growth can absorb.
- Bananas:Standard-grade IQF banana chunks flow primarily into food service smoothie bases where cost efficiency governs procurement.
- Mangoes:Premium-grade mango supply chains concentrate in Ecuador and Peru, serving private-label frozen dessert makers.
Volume sits with Fruits; growth tilts toward Berries.
Grade:
Certification tier determines supplier qualification depth, contract duration, and margin protection against input cost volatility.
- Premium:Specifications demand intact cellular structure, uniform dice size, and sub-zero cold chain documentation from harvest through retail. Functional beverage manufacturers in Germany and the United States lock multi-year contracts, paying qualification premiums for nitrogen-injection fluidized bed processing.
- Organic:USDA and EU organic certification requires three-year soil transition periods, constraining supply pool expansion. North American retailers consolidate sourcing under single-processor certification umbrellas, rewarding scale players with multi-SKU contract breadth.
- Standard:Conventional-grade IQF serves food service channels where visual perfection matters less than unit economics.
- Conventional:Non-certified conventional grade fills commodity retail and institutional procurement with minimal traceability overhead.
Standard grade commands current volume share; organic certification climbs fastest on contract premium expansion.
End User:
Channel-specific freezing protocols and packaging requirements segment procurement relationships across distinct operational workflows.
- Food Service:Ghost kitchen operators and regional smoothie chains negotiate direct volume commitments with origin-country processors, bypassing traditional distribution markups. Latin American plantation-freezer integrators capture this channel compression in North American metropolitan markets.
- Retail:Private-label frozen fruit bags and cartons demand clean-label certification and blockchain-enabled lot tracking to satisfy EU and FDA audit requirements. Greenyard NV and Ardo NV anchor European supermarket supply through dedicated IQF lines in Poland and Belgium.
- Industrial:Beverage concentrate and yogurt manufacturers specify brix levels and microbial limits in supplier qualification protocols.
- Hospitality:Hotel and catering procurement prioritizes portion-controlled packaging and extended thaw stability.
Food service channels are expanding most quickly on direct procurement adoption; retail maintains volume concentration.
Packaging Type:
Logistics configuration and shelf-life requirements determine format selection across channel and geography.
- Cartons:Retail-ready folding cartons with resealable closures dominate North American and Western European supermarket frozen aisles, supporting brand differentiation and portion control messaging.
- Bags:Flexible stand-up pouches with zip-lock features serve club store and discount retail channels where unit economics favor material efficiency over structural rigidity.
- Trays:Rigid plastic trays with lidding film target premium retail positioning and food service portion control applications.
- Bulk:Food service and industrial users specify bulk totes and drums for high-volume smoothie base and manufacturing ingredient procurement, minimizing per-unit packaging cost.
Bulk configurations handle current volume concentration; retail-format bags gain share fastest on club store channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland concentrates European IQF fruit processing capacity, with Greenyard NV and Ardo NV facilities near Warsaw serving retail chains across Germany, France, and the United Kingdom. Demand-side pull from smoothie chains and private-label frozen dessert makers is redrawing procurement geography toward origin-country freezing hubs.
Poland
Ghost kitchen operators and regional beverage chains in Western Europe source directly from Polish freezing facilities, bypassing legacy distribution layers. EU F-Gas Regulation mandates on hydrofluorocarbon phase-downs are forcing retrofits of blast freezing infrastructure at major processing plants. Warsaw and Łódź industrial zones anchor European retail supply through dedicated IQF lines serving supermarket frozen aisles.
United States
Functional beverage manufacturers in California and the Northeast are locking multi-year contracts for certified organic berry supply. FDA food safety modernization rules enforce hazard controls across imported IQF berry supply chains, consolidating qualified supplier pools. Dole Food Company leverages plantation-to-freezer infrastructure in Latin America to secure year-round mango and pineapple supply for metropolitan markets.
Belgium
Private-label frozen dessert makers are expanding procurement of individually quick frozen strawberry and mango chunks through Belgian processing hubs. EU Green Deal farm-to-fork sustainability targets are pushing processors toward lower-carbon blast freezing and closed-loop water recovery systems. Ghent and Antwerp freezing facilities serve as consolidation points for North Sea logistics routes.
Ecuador
Premium-grade mango supply chains concentrate in coastal plantation zones, serving private-label frozen dessert makers in North America and Europe. The country's national agricultural regulator enforces microbial limits for frozen fruit exports, shaping qualification for cross-border retail contracts. Guayaquil and Manta port clusters handle bulk IQF shipments with cold chain documentation for functional beverage manufacturers.
India
BIS standards govern microbial limits for frozen fruit exports, unlocking cross-border retail contracts for processors meeting frozen fruit export protocols. Processors in Maharashtra and Gujarat are converting conventional acreage toward certified organic production to capture North American contract premiums. Mumbai and Ahmedabad freezing facilities are expanding capacity to serve underserved South Asian supply demand.
Global IQF Fruits Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue organic certification and direct-to-food-service channel relationships. The vendor base stratifies across three maturity tiers: plantation-integrated multinationals with captive supply, regional freezing specialists with dedicated IQF lines, and private-label processors competing on clean-label certification. Three archetypes dominate: backward-integrated plantation operators, European hub processors with retail channel anchoring, and North American organic specialists. Competitive moves center on M&A for cold chain traceability technology and capacity expansion in low-energy-cost geographies.
Among plantation-integrated operators, Dole Food Company exemplifies the captive supply archetype with Latin American infrastructure. European hub concentration is represented by Greenyard NV and Ardo NV, both occupying positions within the Polish-Belgian processing corridor. SunOpta Inc. anchors the North American organic specialist tier, competing on certification breadth rather than commodity scale. These three patterns illustrate how geography and grade positioning stratify competitive advantage.
| Leading Market Players |
|---|
| Dole Food Company |
| Ardo NV |
| Greenyard NV |
| SunOpta Inc. |
| McCain Foods |
| Conagra Brands Inc. |
| Simplot |
| Bonduelle |
| Kerry Group |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal farm-to-fork sustainability targets gate qualified supply pools and premium-tier pricing access, forcing processors to absorb capital costs for lower-carbon blast freezing infrastructure while functional beverage manufacturers pay qualification premiums for nitrogen-injection fluidized bed processing.
Pricing Analysis
Volume sits with standard-grade IQF banana and pineapple chunks serving food service smoothie bases where unit economics govern procurement; margins concentrate in organic berry supply where three-year soil certification timelines constrain supply pool expansion and lock multi-year contract premiums. Price differentiation hinges on certification grade and nitrogen-injection processing specifications. Cost compression in standard tier is intensifying as fresh fruit substitution encroaches during peak harvest windows. Ghost kitchen operators exhibit highest price sensitivity; functional beverage manufacturers show least sensitivity due to antioxidant-grade specification rigidity.
Supply Chain Analysis
Regional distribution centers in Warsaw and Łódź industrial zones anchor hub-and-spoke patterns serving Western European retail channels, with consolidation points at Ghent and Antwerp freezing facilities handling North Sea logistics routes. Supply concentrates in Poland, Belgium, and Ecuador, drawing from Latin American plantation-freezer integrators for year-round mango and pineapple feedstock. Cryogenic agent chemistry restrictions under EU F-Gas Regulation create single-source vulnerability for hydrofluorocarbon-dependent processors. Distribution runs through direct procurement relationships between smoothie chains and origin-country processors, displacing layered distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global IQF Fruits Market operates as a cost-of-compliance story where FDA food safety modernization enforcement creates a barrier-to-entry moat for processors with integrated plantation-to-freezer traceability systems, consolidating qualified supplier pools and advantaging incumbent scale.
For Market Incumbents: Deploy blockchain-enabled lot tracking retrofits to satisfy EU and FDA audit requirements, stretching IT capital allocation but defending position against emerging entrants lacking integrated traceability infrastructure. Expand ammonia-based blast freezing capacity in low-energy-cost geographies to offset EU F-Gas Regulation compliance costs. Prioritize multi-year organic berry contract lockups before three-year soil transition timelines mature competing supply pools. For New Entrants and Emerging Players: BIS standards in India open a window for export qualification into underserved South Asian supply capacity, targeting cross-border retail contracts with processors meeting frozen fruit export protocols. Penetrate ghost kitchen channel relationships in North American metropolitan markets where direct procurement compression bypasses legacy distribution markups. Pursue clean-label private-label convergence with retailers consolidating organic berry sourcing under single-processor certification umbrellas. For Investors and Strategic Acquirers: Accelerated adoption of mechanical compression alternatives is the leading indicator that capital deployment priorities are shifting toward sustainable margin protection, signaling long-term viability for backward-integrated plantation operators over hub-dependent processors. Target acquisition archetypes: European hub processors with dedicated IQF lines and retail channel anchoring, or North American organic specialists competing on certification breadth. Watch for inflection when Polish energy price spikes force geographic diversification of freezing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Operations | Dole Food Company leverages captive Latin American supply to secure year-round mango and pineapple feedstock. |
| Clean-Label Certification Investment | SunOpta Inc. competes on USDA organic breadth rather than commodity volume to capture North American private-label contracts. |
| Ammonia-Based Freezing Retrofit | Greenyard NV and Ardo NV convert Polish and Belgian lines ahead of EU F-Gas Regulation mandated deadlines. |
| Direct-to-Food-Service Channel Expansion | Ghost kitchen operators bypass traditional distribution markups through volume commitments with Latin American plantation-freezer integrators. |
| Blockchain Traceability Implementation | Processors retrofit legacy freezing lines to satisfy EU Green Deal farm-to-fork sustainability audit requirements. |
Study Parameters
Document review covered customs and trade data, SEC filings from publicly listed processors, EU regulatory submissions under REACH and F-Gas Regulation, and FDA import refusal data, complemented by interviews with freezing facility operations managers, functional beverage manufacturer procurement leads, retail category buyers, and cold chain logistics specialists. Secondary validation drew from agricultural export statistics, organic certification acreage registries, and energy cost trajectories across processing geographies. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Output modeling produced segment-level demand projections across the analysis window, with CAGRs derived from historical volume trajectories and elasticity assumptions against end-use channel growth. Segmentation dimensions included product type, certification grade, end-use application, and logistics configuration. Industry-specific forecast inputs incorporated EU Green Deal compliance cost pass-through rates and organic acreage conversion timelines lagging frozen retail label growth.
Caveats apply where regulatory enforcement intensity, cryogenic agent cost volatility, or fresh fruit substitution rates could materially shift the outlook beyond modeled assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Fresh Fruits and Vegetables Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Pomegranate Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Asia-Pacific Freeze-Dried Fruits and Vegetables Market