
 Global Organic Fruits and Vegetables Market | 2026-2036
Global Organic Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Global Organic Fruits and Vegetables Market Intelligence
The US-EU Organic Equivalency Arrangement is decoupling market access from single-country certification, altering the cost-of-entry calculus for producers. Dole plc leverages its extensive distribution network to supply a wide variety of organic produce across continents. Driscoll’s Inc. specializes in the organic berry segment, controlling proprietary plant varieties and cultivation methods. Fresh Del Monte Produce Inc. competes through its vertically integrated supply chain for bananas and pineapples, ensuring consistent supply and quality control.
Organic fruits and vegetables are agricultural products cultivated without the use of synthetic pesticides, herbicides, or genetically modified organisms. The cultivation process emphasizes soil health and biodiversity, adhering to strict certification standards. Organic leafy greens and berries represent high-value product categories, driven by perceived health benefits. While supermarkets remain the dominant distribution channel, online retailers are gaining share rapidly due to convenience and expanded delivery options for household customers.
The regulatory landscape is governed by national and regional bodies, including the USDA's National Organic Program in the United States and the EU's organic farming regulations (Reg 2018/848). Japan's Agricultural Standard (JAS) certification further defines market access and product labeling in Asia. Producers must now navigate increasingly complex supply chains to ensure traceability and prevent fraud, which is critical for maintaining consumer trust in organic labels.
Market Dynamics
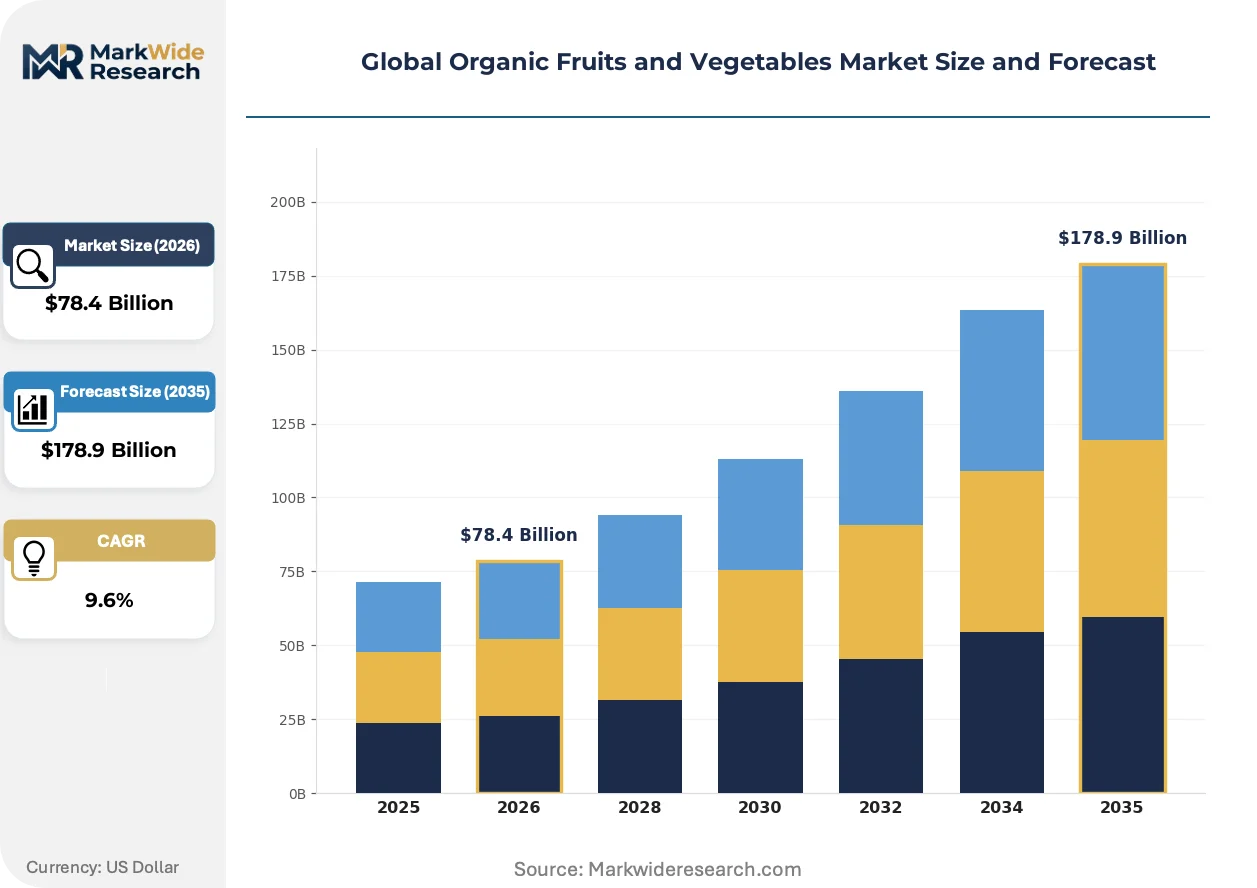
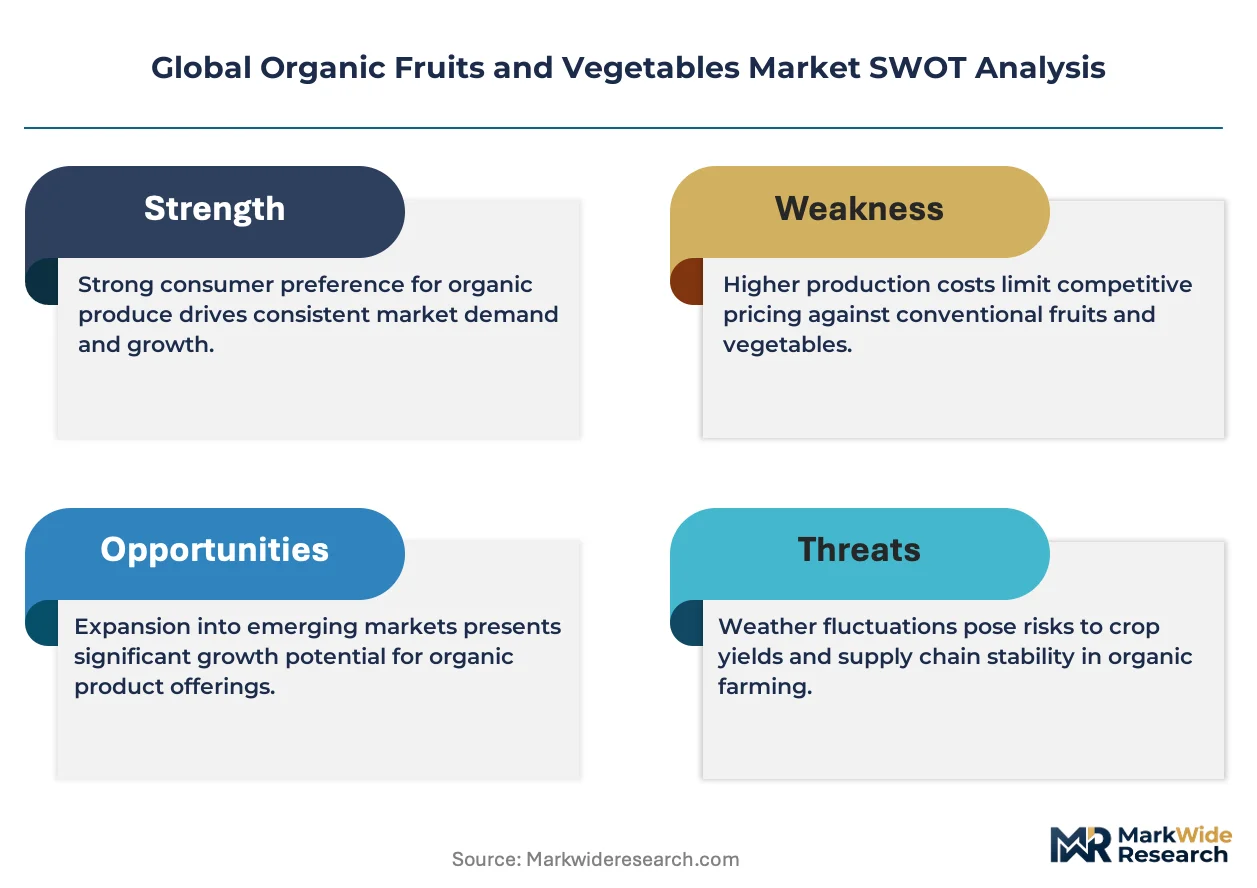
The market's primary dynamic is the tension between global trade harmonization, exemplified by the US-EU Organic Equivalency Arrangement, and the strict enforcement of regional certifications like the EU's Reg 2018/848, which complicates supply chain management for producers.
Growth Catalysts
- Policy Frameworks:The European Union's Green Deal and its Farm to Fork strategy create a strong regulatory pull, mandating sustainable practices and enhancing consumer trust through stricter certification, which benefits certified organic producers.
- Clean-Label Demand:Food processors are increasingly sourcing organic fruits and vegetables as ingredients to meet consumer demand for clean-label products, free from synthetic additives and GMOs, especially in the baby food and health snack categories.
- Channel Expansion:The rapid growth of online grocery retail and subscription box services expands market access for organic produce, offering convenience to household customers and creating new distribution paths for farmers beyond traditional supermarkets.
Market Restraints
- Input Cost Volatility:Producers face higher and more volatile costs for non-synthetic inputs, such as organic-approved fertilizers and pest controls, which compresses margins compared to conventional farming and can be passed on to consumers.
- Climate Sensitivity:Organic cultivation methods, which prohibit many synthetic interventions, leave crops more vulnerable to climate-related shocks, including droughts, floods, and pest outbreaks, leading to greater yield instability.
- Certification Costs:The direct and indirect costs associated with obtaining and maintaining organic certification, including administrative fees and operational changes, represent a significant barrier to entry, particularly for small-scale farmers in developing nations.
Strategic Opportunities
- Controlled Environment Agriculture:Investing in vertical farming and hydroponics for organic production allows for year-round cultivation, protection from climate volatility, and proximity to urban consumption centers, reducing transportation costs and spoilage.
- Emerging Market Penetration:There is significant opportunity for market development in Southeast Asian and Middle Eastern countries, where a growing middle class and heightened health awareness are creating new demand for certified organic goods.
- Value-Added Processing:Opportunities exist in developing processed organic products like frozen fruits, purees, and ready-to-eat salads, which offer longer shelf life, convenience, and capture higher value than raw produce alone.
Industry Challenges
- Certification Complexity:Producers targeting a global customer base must navigate a complex and costly patchwork of national and regional standards, including the USDA's NOP, the EU's organic regulation, and Japan's Agricultural Standard (JAS).
- Supply Chain Fraud:The risk of fraudulent products entering the supply chain, where conventional produce is mislabeled as organic, remains a persistent challenge that erodes consumer trust and requires robust traceability systems to combat.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Organic Fruits and Vegetables Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Apples, Organic Tomatoes, Organic Carrots, Organic Berries, Organic Leafy Greens Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Farmers Markets, Direct-to-Consumer Customer Type: Households, Restaurants, Food Processors, Catering Services, Institutional Buyers Packaging Type: Plastic Containers, Cardboard Boxes, Biodegradable Bags, Glass Jars, Bulk Packaging |
| Companies Covered | Dole plc, Fresh Del Monte Produce Inc., Driscoll’s Inc., Calavo Growers Inc., Nature Fresh Farms, Robinson Fresh Inc., Earthbound Farm, Whole Foods Market, Organic Valley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Organic Fruits and Vegetables Market Strategic Shifts & Innovations
The industrialization of organic agriculture is driving innovation, moving practices from small-scale farming to a technology-integrated global industry. This shift prioritizes supply chain efficiency, data-driven cultivation, and new models for verifying authenticity from farm to consumer.
Blockchain technology provides an immutable digital ledger for supply chain traceability. Major retailers and food processors are adopting it to validate organic claims and combat fraud. This technology is decentralizing verification authority, shifting trust from a single certification body to a distributed, transparent network accessible to all stakeholders.
Regulatory frameworks like the US-EU Organic Equivalency Arrangement streamline transatlantic trade by recognizing each other's certification standards as valid. This policy reduces the compliance burden and costs for producers seeking access to both markets. Small and medium-sized farms in the United States and European Union benefit most, gaining easier entry into large consumer bases.
Consumer purchasing is moving from bulk supermarket buys to curated, subscription-based delivery boxes. This direct-to-consumer model disrupts the dominance of large grocery chains for fresh produce, allowing for better price realization for farmers. The shift is most advanced in affluent urban centers in North America and Western Europe, where convenience and producer-storytelling are valued.
Global Organic Fruits and Vegetables Market Segmentation
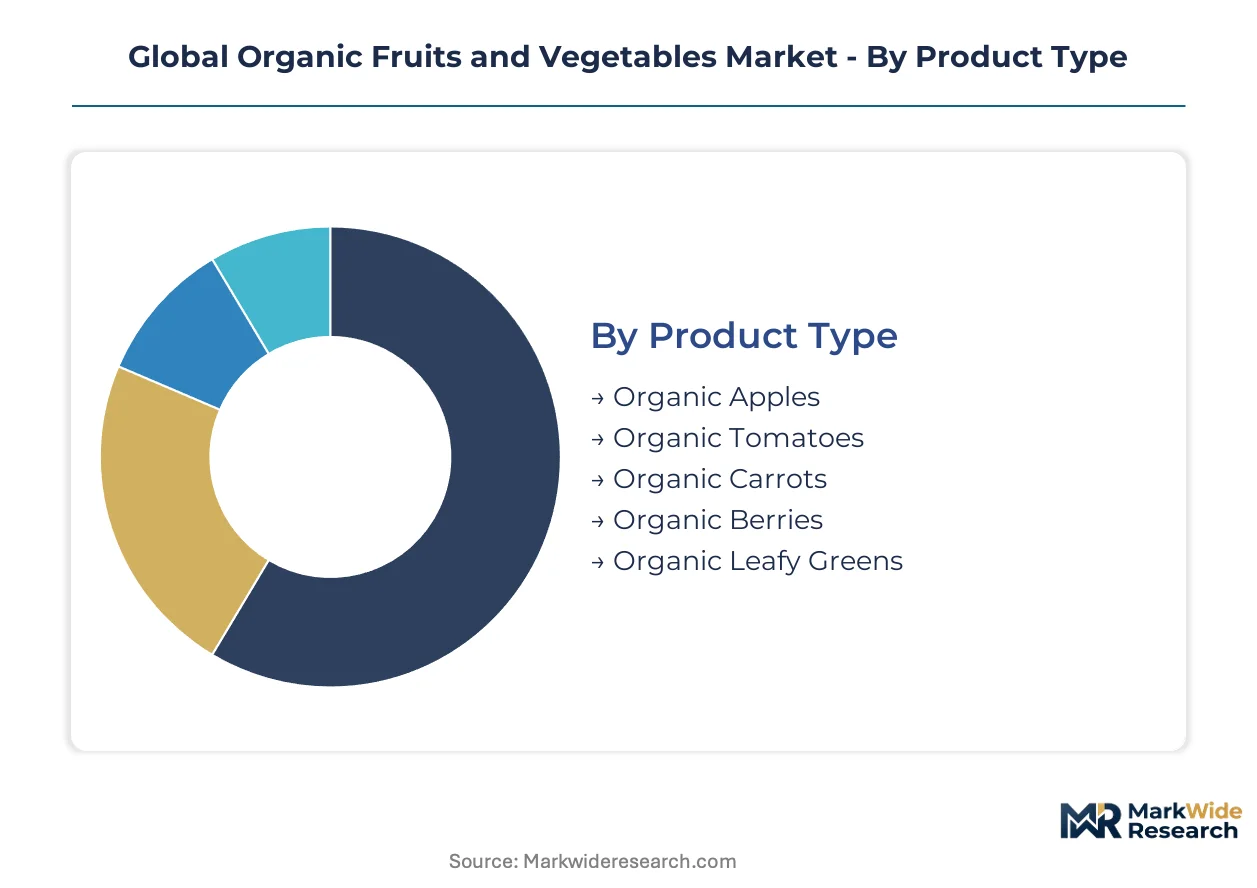
Understanding the Global Organic Fruits and Vegetables Market through segmentation highlights specific demand drivers and supply chain configurations. This granular analysis reveals which product types, distribution channels, customer groups, and packaging formats hold the most commercial significance. Strategic market entry and product development depend on accurately assessing these distinct segment characteristics.
Product Type:
Navigating the complex landscape of organic certification, such as the USDA's National Organic Program or the EU's organic farming regulations (Reg 2018/848), defines market access for specific product types.
- Organic Berries:These high-value fruits command premium pricing due to perceived health benefits and delicate cultivation requirements. Demand concentrates in affluent urban centers across North America and Western Europe, driven by consumer preference for antioxidant-rich foods.
- Organic Leafy Greens:This category includes a diverse range of produce like spinach, kale, and lettuce, prized for nutritional density and versatility. Food processors increasingly source organic leafy greens for ready-to-eat salads and health-focused meal kits, particularly in the United States.
- Organic Apples:Widely consumed globally, organic apples face stringent pest management challenges without synthetic interventions.
- Organic Tomatoes:Versatile in culinary applications, organic tomatoes are a staple for both fresh consumption and processed organic goods.
- Organic Carrots:Known for their health benefits, organic carrots are a consistent demand driver in the root vegetable segment.
Leading the category by volume: Organic Apples. Growing fastest: Organic Berries.
Distribution Channel:
The evolving purchasing habits of household customers and the convenience offered by various channels define the market's distribution dynamics.
- Supermarkets:These large retail chains remain the primary conduit for organic fruits and vegetables, offering broad accessibility and diverse product selections. Their established logistics infrastructure supports consistent supply to a mass consumer base across Germany and the United States.
- Online Retailers:Rapid expansion of e-commerce platforms provides convenience and expanded delivery options, particularly for household customers in urban areas. This channel is gaining significant share in markets like the United Kingdom and Japan.
- Specialty Stores:These outlets cater to niche consumer preferences, often emphasizing local sourcing and premium organic selections.
- Farmers Markets:Direct-to-consumer sales at farmers markets foster trust and provide fresh, locally sourced organic produce.
- Direct-to-Consumer:Subscription box services and farm-to-table initiatives bypass intermediaries, offering better price realization for farmers.
Supermarkets capture the largest share of organic produce sales, while online retailers exhibit the steepest expansion trajectory.
Customer Type:
Demand drivers stemming from specific end-user requirements shape the market's focus on different customer types.
- Households:Individual consumers represent the largest segment, driven by health consciousness and a preference for clean-label food options. Family purchasing decisions in countries like France and Australia prioritize organic produce for daily consumption.
- Food Processors:Manufacturers of baby food, health snacks, and ready-to-eat meals increasingly require organic fruits and vegetables as ingredients. Their demand is concentrated in industrialized food markets, including the United States and the Netherlands.
- Restaurants:Eateries incorporate organic produce to meet consumer demand for healthier and sustainably sourced menu items.
- Catering Services:These services integrate organic options into their offerings for corporate events and private functions.
- Institutional Buyers:Schools, hospitals, and corporate cafeterias procure organic produce to align with wellness initiatives and sustainability goals.
Households constitute the foundational demand base, with food processors representing a growing segment for bulk organic ingredients.
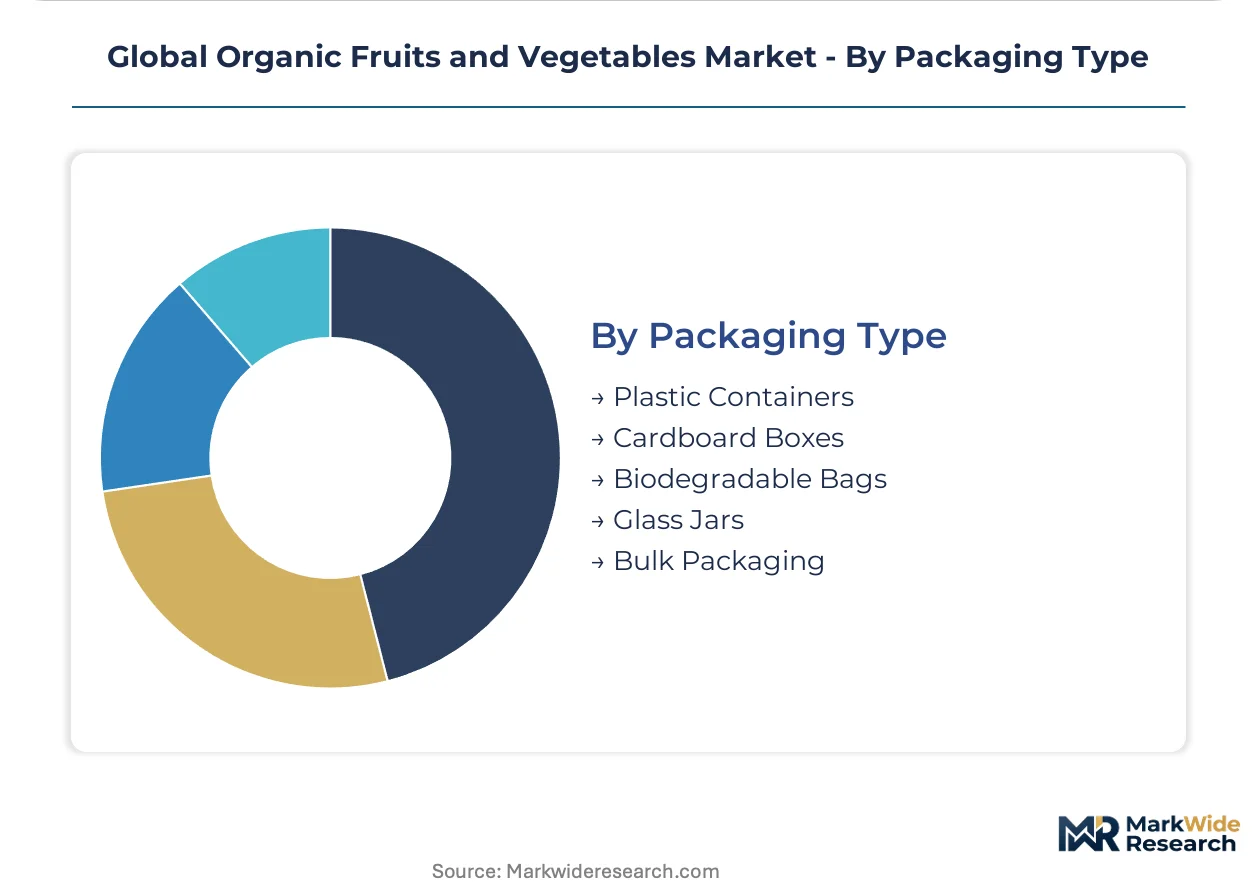
Packaging Type:
The sustainability implications and material costs associated with various packaging types influence producer choices and consumer acceptance.
- Biodegradable Bags:These eco-friendly packaging solutions address consumer concerns regarding plastic waste and environmental impact. Adoption is increasing in markets with strong environmental regulations, such as the European Union.
- Plastic Containers:Offering durability and visibility, plastic containers remain prevalent for protecting delicate organic produce during transit and display. They are widely used for berries and leafy greens across global supply chains.
- Cardboard Boxes:Often used for bulk or larger organic produce items, cardboard provides structural integrity and recyclability.
- Glass Jars:Primarily utilized for processed organic fruit products like purees or jams, glass offers inertness and premium perception.
- Bulk Packaging:This format is common for institutional buyers and food processors, minimizing individual packaging waste and cost.
Plastic containers currently dominate the market for fresh organic produce, but biodegradable bags are gaining market traction due to environmental pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for organic fruits and vegetables is pronounced in developed economies. Consumers in these regions increasingly prioritize health and sustainability in their food choices, driving demand for clean-label products. This preference drives significant market development across key global markets, influencing cultivation and distribution strategies.
Germany
German consumers exhibit a strong preference for organic produce, driven by health and environmental concerns. The EU's Reg 2018/848 strictly governs organic farming practices and certification within the country. Munich and Berlin's urban centers showcase concentrated demand for premium organic fruits and vegetables via supermarkets and online platforms.
United States
American households and food processors drive substantial demand for organic fruits and vegetables. The USDA's National Organic Program (NOP) sets comprehensive standards for organic certification and labeling nationwide. California's Central Valley acts as a critical hub for large-scale organic cultivation, supplying produce to major cities.
Japan
Japanese consumers demonstrate a growing interest in organic produce, fueled by health trends and expanding online retail options. Japan's Agricultural Standard (JAS) certification ensures product authenticity and market access. Tokyo's dense metropolitan area experiences rapid expansion of subscription box services for organic fruits and vegetables.
France
French household purchasing decisions increasingly prioritize organic produce for daily consumption and perceived quality. The EU's Farm to Fork strategy encourages sustainable agriculture and strengthens organic certification across France. Lyon, a major culinary city, shows significant integration of organic ingredients within its restaurant and catering services.
Netherlands
Dutch food processors increasingly source organic fruits and vegetables as ingredients for health snacks and baby food. The EU Green Deal promotes sustainable agricultural practices and organic farming development within the Netherlands. The region around Amsterdam and Rotterdam serves as a key processing and distribution hub for organic produce.
Global Organic Fruits and Vegetables Market Key Industry Players
European producers anchor one tier, emphasizing strict EU organic standards and local sourcing; North American specialists hold another, focusing on scale and diverse product offerings. The market structure presents a tiered landscape, with large integrated players coexisting with niche organic brands. Strategic archetypes include global distributors, specialized organic cultivators, and value-added processors. Companies frequently pursue geographic expansion and portfolio diversification to capture market share.
Within the global distribution tier, Dole plc and Fresh Del Monte Produce Inc. exemplify companies leveraging extensive networks to supply organic produce across continents. Dole plc, with its broad product range, represents a diversified approach to organic market penetration. Fresh Del Monte Produce Inc. showcases vertical integration, particularly for tropical organic fruits like bananas and pineapples, ensuring consistent supply and quality control. These entities anchor the large-scale supply chain, navigating complex international certifications and logistics.
| Leading Market Players |
|---|
| Dole plc |
| Fresh Del Monte Produce Inc. |
| Driscoll’s Inc. |
| Calavo Growers Inc. |
| Nature Fresh Farms |
| Robinson Fresh Inc. |
| Earthbound Farm |
| Whole Foods Market |
| Organic Valley |
| Others |
Cost & Logistics Intelligence
Specialized organic farming labor in regions like California's Central Valley influences production costs, which in turn feeds into pricing-tier spreads across different organic fruit and vegetable categories. This dynamic interaction balances input costs with consumer willingness to pay for certified organic produce. Market efficiency depends on robust logistics and clear regulatory frameworks.
Pricing Analysis
Volume sales of organic produce often operate on tighter margins, while high-value organic berries command significant premiums. The dominant pricing model combines per-unit transactional sales in supermarkets with contract-based long-term offtake agreements for food processors. Price differentiation stems from certification levels, such as USDA's National Organic Program, and perceived health benefits. Margin compression arises from volatile input costs for organic-approved fertilizers and pest controls. Households purchasing daily staples exhibit higher price sensitivity compared to food processors sourcing specialized organic ingredients.
Supply Chain Analysis
Buyers increasingly mandate multi-supplier qualification for organic ingredients to mitigate risks and ensure consistent supply. Supply concentration draws from key agricultural regions, including California in the United States, and specific growing areas within Germany and Spain. The supply chain relies on critical inputs like organic seeds, approved bio-pesticides, and consistent water access. Climate sensitivity represents a structural risk, leading to greater yield instability across regions. Downstream distribution primarily runs through large supermarket chains and rapidly expanding online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, as the significant costs associated with maintaining organic certification increasingly force smaller, less capitalized players out. Strategic moves are essential for sustained competitiveness.
For Market Incumbents: To counter supply chain fraud and input cost volatility, incumbents should deepen vertical integration for high-value organic categories like berries. Leveraging extensive distribution networks, such as Dole plc's, can reinforce market presence and control. Investing in advanced traceability systems will also strengthen consumer trust in organic labels.
For New Entrants and Emerging Players: The EU's Green Deal in Europe opens a window for new entrants focusing on sustainable practices and local sourcing. White-space opportunities exist in controlled environment agriculture, offering year-round supply and reduced climate risk. Targeting subscription box services in affluent urban centers provides a direct-to-consumer go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors patient capital seeking long-term growth driven by health and sustainability trends. Acquisition targets should include niche organic brands with strong regional presence or technology-enabled agriculture startups. A key signal to watch is the widespread adoption of blockchain technology for transparent supply chain verification.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Controlled Environment Agriculture (CEA) | Mitigates climate volatility and enables year-round cultivation near urban consumption centers. |
| Deepen Blockchain Integration | Enhances supply chain traceability and combats fraud, reinforcing consumer trust in organic claims. |
| Diversify Organic Product Portfolio | Captures broader consumer demand beyond raw produce, targeting convenience and value-added segments. |
| Strengthen Direct-to-Consumer Channels | Reduces intermediary costs and fosters direct relationships with household customers for better price realization. |
| Invest in Emerging Market Logistics | Unlocks new demand in Southeast Asian and Middle Eastern countries with growing middle-class populations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. The research combined extensive primary interviews with organic farmers, food processors, supermarket category buyers, and certification body representatives. This approach ensured a comprehensive understanding of market dynamics, triangulating insights from both bottom-up operational perspectives and top-down strategic views.
Data-stream reconciliation integrated diverse market inputs to construct a robust analytical framework across the analysis window. Segmentation dimensions modeled included product type, distribution channel, customer type, packaging format, and regional regulatory frameworks. Compound annual growth rates were derived through a proprietary statistical model, with organic acreage expansion and consumer health awareness indices serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for controlled environment agriculture would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and consumer preference. A model refresh is warranted upon material change in global trade agreements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
North America Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Brined Vegetable Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
United States Blueberry Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
South Africa Fruits and Vegetables Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market