
 Coconut Products Market | 2026-2036
Coconut Products Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Products Market Intelligence
The shift in purchasing power from bulk industrial food processors to health-conscious retail consumers is redrawing the competitive landscape for coconut products. Beverage giants like PepsiCo and Coca-Cola compete through extensive distribution networks for coconut water. Meanwhile, specialists such as Vita Coco Company, Inc. differentiate with strong brand identity and focus on premium segments. Regional powerhouses like Marico Ltd. leverage deep market penetration in South Asia.
Coconut products encompass a range of derivatives from the fruit of the Cocos nucifera palm, processed via methods like cold-pressing for oil or spray-drying for milk powder. These derivatives serve as key ingredients in the food, personal care, and pharmaceutical industries for their nutritional and functional properties. Within product types, coconut oil holds a mature position, while coconut milk and cream show significant expansion in plant-based food applications. The distribution channel mix is evolving, with online retail and specialized health food stores gaining share from traditional supermarkets.
Market access and product claims are governed by food safety standards from bodies like the US FDA and the European Food Safety Authority (EFSA). Additionally, organic certifications under frameworks like the USDA National Organic Program or Japan's JAS standards dictate labeling and influence consumer trust. Stakeholders must now navigate the dual pressures of ensuring supply chain traceability for these certifications while meeting the volume demands of mass-market food and beverage applications.
Market Dynamics
The central tension defining the coconut products market is the collision between the mass-volume requirements of the food and beverage industry and the stringent traceability demands of certified organic and fair-trade consumer segments. This creates a dual-track supply chain, forcing producers to balance scale with verification.
Growth Catalysts
- Plant-Based Diet Adoption:The global shift towards vegan and flexitarian diets propels demand for coconut milk, cream, and yogurt as primary dairy-free alternatives in the food manufacturing sector.
- Organic Certification Frameworks:Regulations like the USDA National Organic Program and EU organic standards provide a premium price pathway and build consumer trust, encouraging producers to adopt certified farming practices.
- Functional Ingredient Demand:The personal care industry's increasing use of coconut oil and its derivatives for their moisturizing and antimicrobial properties in cosmetics and hair care formulations stimulates growth.
Market Restraints
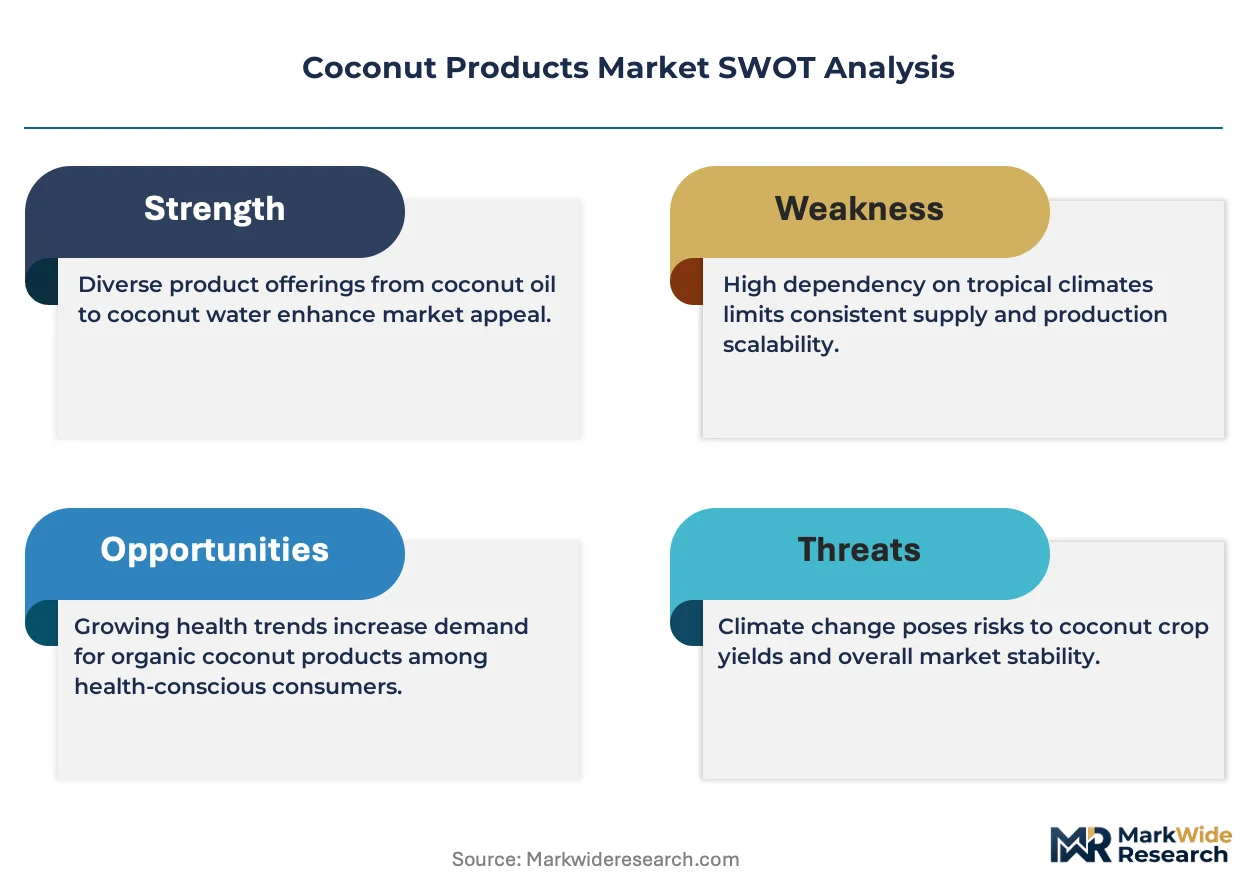
- Geographic Supply Concentration:Over-reliance on a few countries, primarily Indonesia and the Philippines, for raw coconut supply creates significant vulnerability to climate-related events, pests, and local policy shifts.
- Input Price Volatility:Raw material costs are subject to sharp fluctuations driven by weather patterns like El Niño, typhoons, and the spread of crop diseases, which impacts processor margins.
- Intense Substitution Pressure:In the plant-based beverage and oil categories, coconut products face direct competition from alternatives like oat milk, almond oil, and soy, which often have different cost structures and nutritional profiles.
Strategic Opportunities
- Nutraceutical and Pharmaceutical Applications:There is an opportunity to develop and market high-purity coconut extracts, such as medium-chain triglycerides (MCTs), for use in medical foods and dietary supplements.
- Geographic Market Development:Penetrating emerging economies in Latin America and Eastern Europe, where consumer health consciousness is rising but coconut product availability remains limited, offers new growth avenues.
- Byproduct Valorization:Innovations in utilizing coconut husks, shells, and water coir create new revenue streams in horticulture, textiles, and industrial materials, improving overall operational profitability.
Industry Challenges
- Certification and Compliance Burden:Navigating the complex and costly processes for obtaining multiple certifications, such as USDA Organic, EU Bio, and Fair Trade, for different international markets poses a significant operational hurdle.
- Fragmented Smallholder Supply Base:Ensuring consistent quality and implementing traceability systems across a vast network of smallholder farmers, who form the backbone of production, is a major logistical challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Products Market |
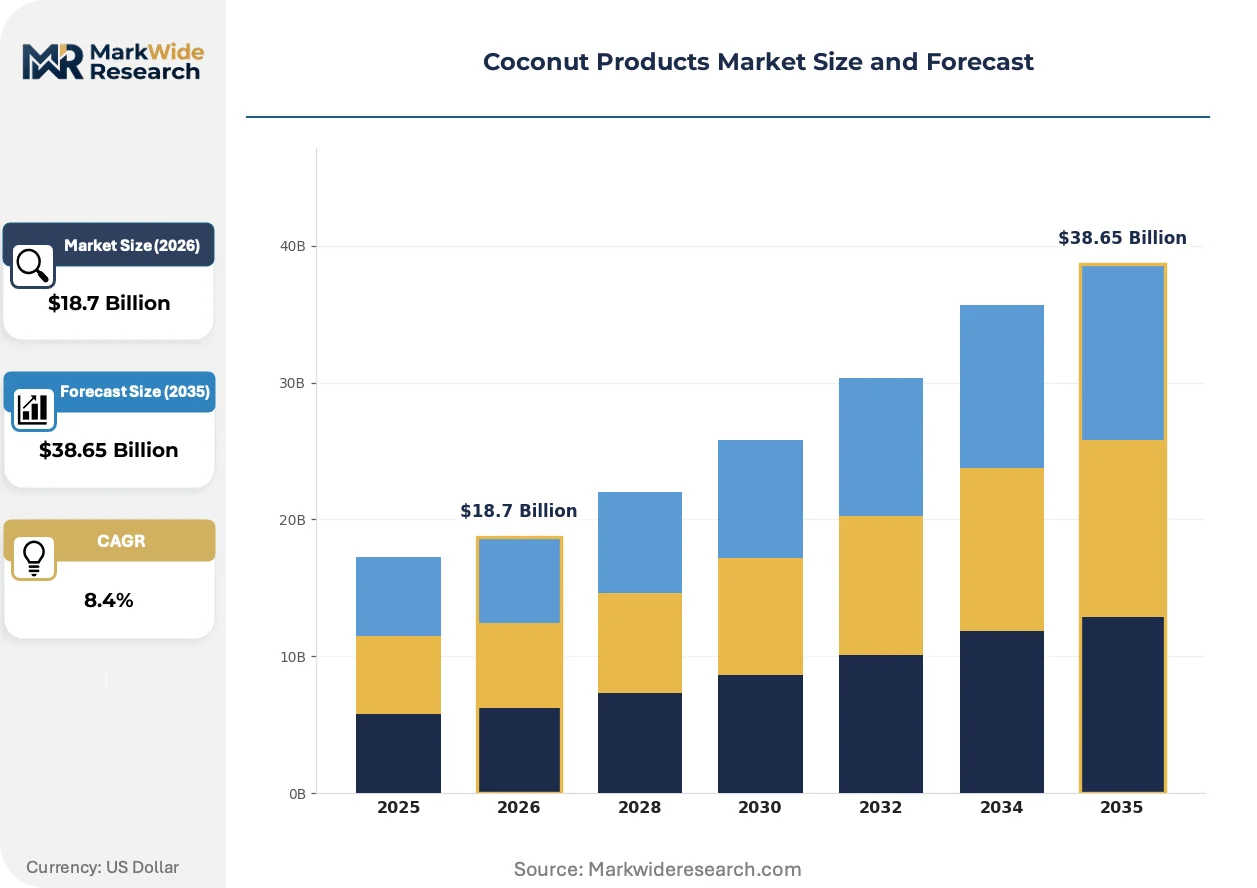
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Oil, Coconut Milk, Desiccated Coconut, Coconut Cream Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale End User: Food Industry, Personal Care, Pharmaceuticals, Homecare Form: Liquid, Powder, Granulated, Solid |
| Companies Covered | Vita Coco Company, Inc., Marico Ltd., Thai Coconut Public Company Limited, Celebes Coconut Corporation, Sambu Group, Renuka Holdings PLC, PepsiCo, Coca-Cola, Axelum Resources Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Products Market Strategic Shifts & Innovations
Product formulation technology is converging with consumer demand for supply chain transparency, creating new value propositions. Innovations focus on enhancing the functional benefits of coconut derivatives while providing verifiable proof of origin and ethical sourcing to an increasingly discerning customer base.
Nano-emulsification technology enables the creation of microscopic droplets of coconut oil. Personal care and functional beverage manufacturers are adopting this process to improve the stability and bioavailability of their formulations. This innovation is miniaturizing the delivery system for coconut’s bioactive compounds, allowing for their incorporation into new product formats like clear nutritional drinks and fast-absorbing lotions.
The European Union's deforestation-free products regulation (EUDR) is a significant policy development. It requires companies to prove that commodities, including coconut, sold within the EU have not originated from recently deforested land. This mandate affects all suppliers to the European market, especially those in Southeast Asia, who must now implement robust geolocation tracking and due diligence systems to maintain market access.
A clear behavioral shift shows consumers prioritizing products with verifiable origin stories and ethical production claims. This trend disrupts the anonymous bulk commodity channel, creating an advantage for brands that provide specific farm-level sourcing details. This demand for radical transparency is most pronounced in the premium food and personal care segments across North American and Western European markets.
Coconut Products Market Segmentation
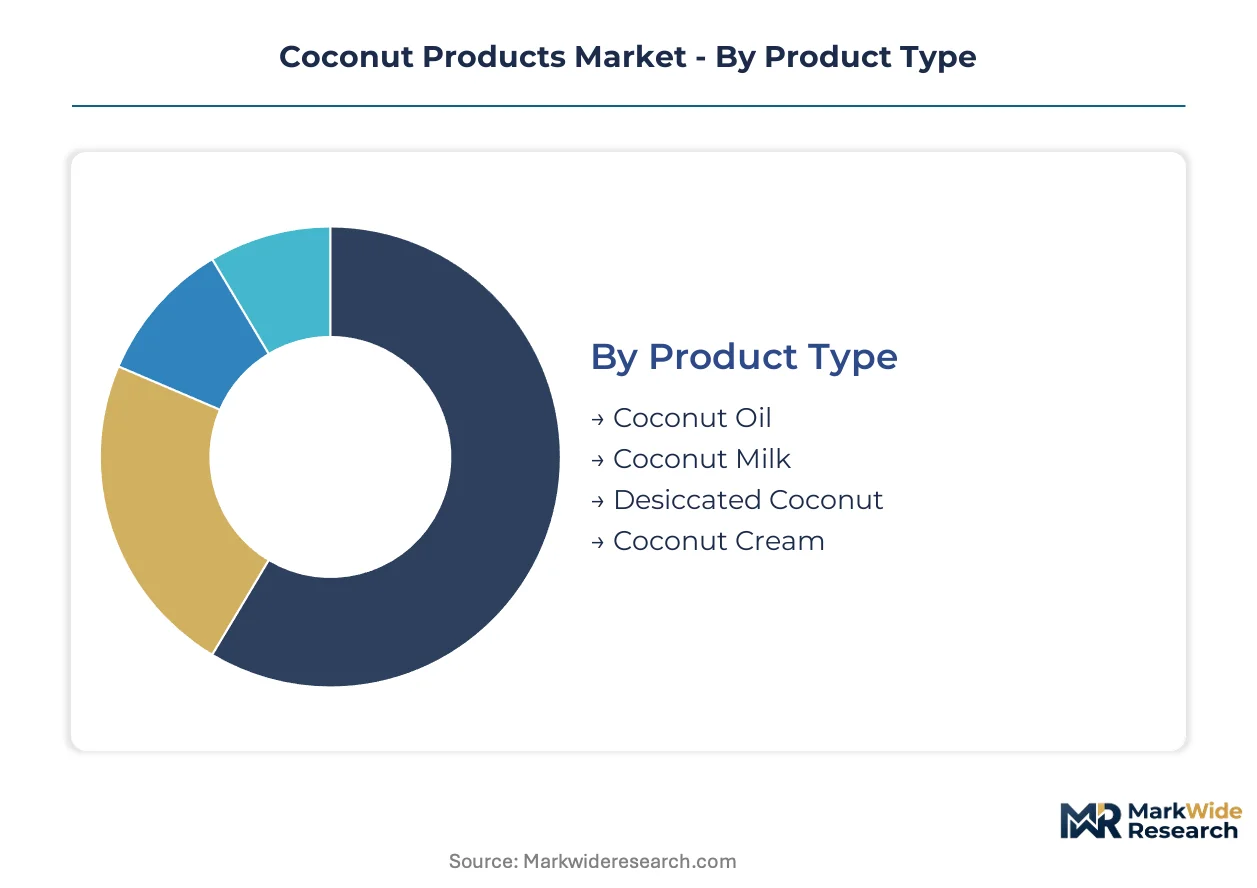
The Coconut Products Market segmentation highlights the diverse applications and consumer preferences influencing product development and distribution strategies. Understanding these distinct segments allows stakeholders to tailor offerings, optimize supply chains, and identify specific growth opportunities across various end-use industries.
Product Type:
Segments in the product type category face varying degrees of substitution pressure from alternative plant-based ingredients and oils. Manufacturers must differentiate through functional benefits or organic certifications.
- Coconut Oil:This product, extracted from the kernel of mature coconuts, is available in virgin, refined, and fractionated forms. Its established use in cooking, baking, and personal care drives consistent demand, especially in South Asia and Southeast Asia.
- Coconut Milk:A dairy-free liquid extracted from grated coconut flesh, coconut milk serves as a foundational ingredient in plant-based beverages, curries, and desserts. Its expansion in North American and European markets is driven by vegan and flexitarian dietary trends.
- Desiccated Coconut:This is dried, shredded coconut meat, used extensively in confectionery, baked goods, and as a topping for various dishes.
- Coconut Cream:A thicker, richer version of coconut milk, coconut cream offers a higher fat content and is preferred for sauces, desserts, and whipping applications.
Coconut Oil retains volume leadership; Coconut Milk holds the steepest expansion curve.
Distribution Channel:
The distribution landscape reflects evolving consumer purchasing habits, with different channels serving distinct customer segments and procurement preferences.
- Online Retail:This channel includes e-commerce platforms and brand-specific websites, providing convenience and a broader product selection to consumers. Online retail is gaining share rapidly, particularly for specialized and premium coconut products in Western markets.
- Supermarkets:Traditional large-format grocery stores remain a primary channel, offering wide accessibility and competitive pricing for mass-market coconut products. These stores serve as the dominant point of sale for most consumers globally.
- Health Food Stores:These specialized outlets cater to consumers seeking organic, natural, and ethically sourced products, often featuring premium and niche coconut derivatives.
- Wholesale:This channel supplies bulk quantities of coconut products directly to food manufacturers, restaurants, and other industrial users.
Supermarkets capture the largest market share; Online Retail is expanding most quickly.
End User:
The end-user segmentation reveals the diverse applications of coconut derivatives, each presenting unique demand drivers and regulatory requirements.
- Food Industry:This sector utilizes coconut products extensively in beverages, confectionery, baked goods, and ready-to-eat meals for flavor, texture, and nutritional value. The plant-based food movement significantly boosts demand for coconut milk and cream in this industry.
- Personal Care:Coconut oil and its derivatives are prominent ingredients in cosmetics, skincare, and hair care formulations due to their moisturizing and antimicrobial properties. This industry values the natural and organic claims associated with coconut products.
- Pharmaceuticals:Coconut derivatives, particularly medium-chain triglycerides (MCTs), find applications in medical foods, dietary supplements, and drug delivery systems.
- Homecare:Coconut oil and its byproducts are incorporated into cleaning agents, soaps, and other household products for their natural cleansing and scent profiles.
The Food Industry represents the largest application segment; Personal Care exhibits strong growth potential.
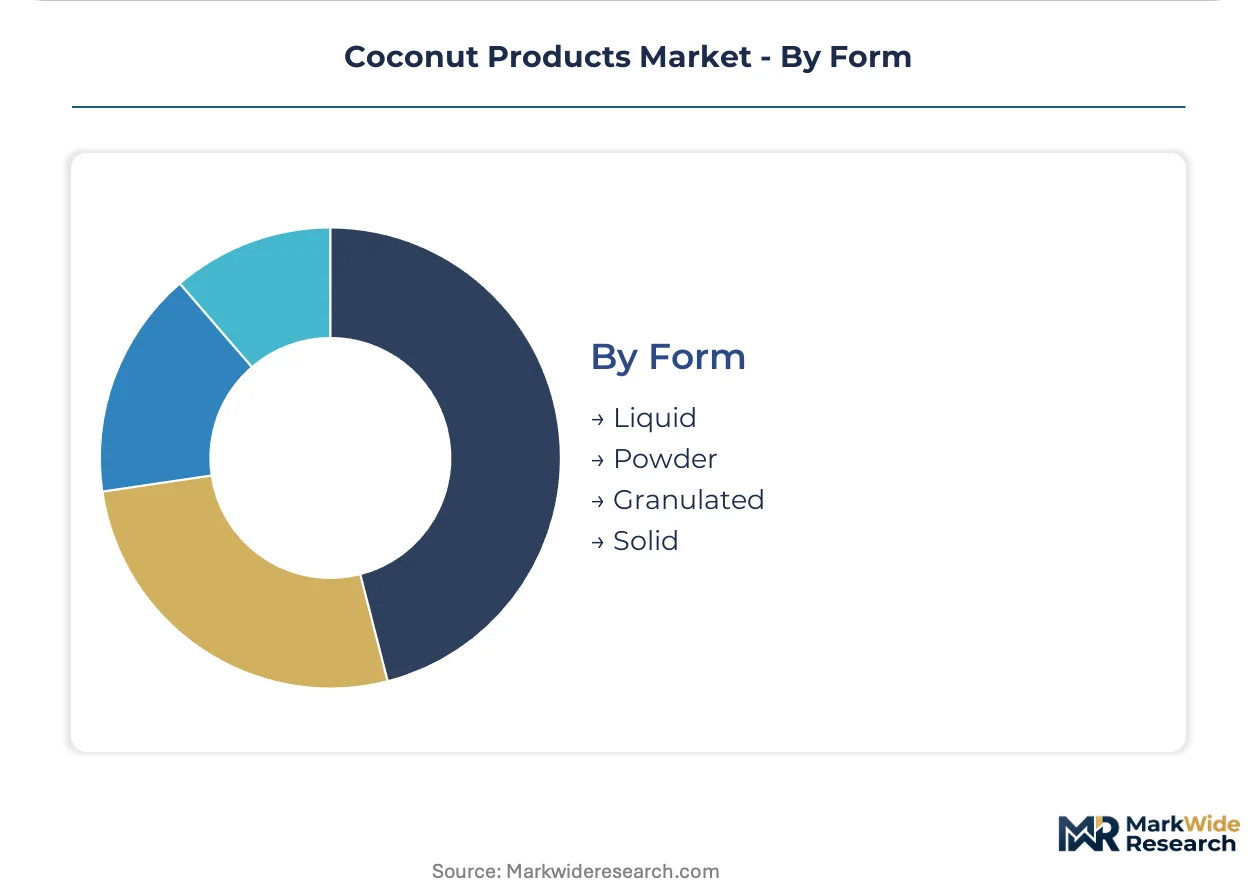
Form:
The form of coconut products dictates their functional properties, shelf life, and suitability for various end-use applications, influencing processing methods and storage requirements.
- Liquid:This form encompasses coconut water, milk, and oil, primarily used in beverages, cooking, and direct consumption. The liquid forms offer immediate usability and are central to the beverage industry.
- Powder:Coconut milk powder and coconut water powder offer extended shelf life and ease of transport, serving as convenient ingredients for baking mixes, instant beverages, and processed foods. Their rehydration capability makes them versatile for manufacturers.
- Granulated:This form typically refers to desiccated coconut, used for texture and flavor in confectionery and baking.
- Solid:Solid forms include coconut meat, copra, and solid coconut oil, used as raw materials for further processing or direct culinary applications.
Liquid forms command the highest volume; Powder forms offer enhanced convenience and shelf stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side concentration for coconut products largely anchors in Southeast Asia, creating a distinct geographical imbalance. This reliance on a few primary producing nations impacts global raw material availability. Demand centers globally drive product innovation and market expansion.
Indonesia
Indonesia drives raw coconut supply, supporting global demand for derivatives in food and personal care. The country's Ministry of Agriculture promotes sustainable farming practices to enhance yield stability. Processing hubs in Sumatra and Sulawesi focus on converting fresh coconuts into oil and desiccated forms for export.
Philippines
The Philippines is a major global supplier of raw coconuts and processed products like coconut oil. The Philippine Coconut Authority (PCA) implements programs to improve farm productivity and quality standards. Mindanao and Palawan serve as critical regions for coconut cultivation and processing facilities.
United States
The United States exhibits strong demand for plant-based coconut products, particularly milk and cream alternatives. The USDA National Organic Program certifies a significant portion of these premium imported products. Health food stores and e-commerce platforms in California and New York show high concentrations of specialized coconut derivatives.
Germany
Germany leads European demand for organic and ethically sourced coconut products, driven by health-conscious consumers. The European Union's deforestation-free products regulation (EUDR) influences sourcing strategies for German importers. Food manufacturers in Bavaria and North Rhine-Westphalia integrate coconut milk into new vegan formulations.
India
India represents a substantial market for coconut oil in traditional cooking and personal care applications. The Food Safety and Standards Authority of India (FSSAI) governs quality and labeling requirements for coconut products. Kerala and Tamil Nadu are major producing states, supplying both raw coconuts and processed goods to national markets.
Coconut Products Market Key Industry Players
Concentration sits with large-scale beverage manufacturers leveraging extensive distribution networks for coconut water. The market structure also includes specialized premium brands and regional players with deep local market penetration. Competitive moves involve strategic partnerships for raw material sourcing and portfolio diversification into new product forms.
Scale-driven beverage corporations like PepsiCo and Coca-Cola leverage their vast distribution capabilities to reach mass markets with coconut water products. Meanwhile, specialized brand-focused entities such as Vita Coco Company, Inc. differentiate through strong brand identity and premium product offerings. Regional powerhouses like Marico Ltd. anchor their position with deep market penetration across South Asia, tailoring products to local consumer preferences.
| Leading Market Players |
|---|
| Vita Coco Company, Inc. |
| Marico Ltd. |
| Thai Coconut Public Company Limited |
| Celebes Coconut Corporation |
| Sambu Group |
| Renuka Holdings PLC |
| PepsiCo |
| Coca-Cola |
| Axelum Resources Corp. |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for raw coconuts lock in both supply access and price visibility for large processors, mitigating some volatility from the commodity spot market. This contract structure allows major buyers to plan production schedules and stabilize input costs, while simultaneously providing a predictable revenue stream for smallholder farmers. The inherent geographic concentration of coconut cultivation in Southeast Asia profoundly shapes these agreements and overall market dynamics.
Pricing Analysis
Volume-based discount structures characterize pricing for bulk coconut derivatives supplied to industrial food processors. Price differentiation stems from the quality grade of the product, such as virgin versus refined coconut oil, and the level of organic certification, like USDA or EU Bio standards. Pricing pressure stems from intense substitution competition from alternative plant-based ingredients in the food and beverage sector. Health-conscious retail consumers, seeking certified organic or ethically sourced products, exhibit lower price sensitivity compared to mass-market industrial buyers.
Supply Chain Analysis
Rising inbound logistics costs, particularly shipping from Southeast Asia, impact processor margins and final product pricing. Geographic supply concentration for raw coconuts remains anchored in Indonesia and the Philippines, creating inherent vulnerabilities. The supply chain draws heavily on raw coconuts and coconut flesh as primary inputs for various derivatives. A key structural risk is commodity price volatility driven by climate events like El Niño and disease outbreaks. Distribution runs through a hybrid model, combining direct wholesale to manufacturers with retail channels like supermarkets and expanding online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coconut products market is experiencing a cyclical recovery, driven by sustained consumer demand for plant-based alternatives and natural personal care ingredients.
For Market Incumbents: Compound existing distribution strengths in traditional retail channels while strategically expanding into specialized health food stores and e-commerce. Diversify sourcing beyond core regions to mitigate climate-related supply shocks and reduce input price volatility. Invest in advanced processing technologies like nano-emulsification to enhance functional properties and differentiate premium product lines against emerging competition from alternative oils. This approach defends against margin erosion from mass-market substitution pressure.
For New Entrants and Emerging Players: Hyper-specific ethical sourcing verification and transparent supply chain narratives offer a service-layer gap where incumbents under-serve. Target premium segments in North American and European personal care markets with innovative, certified organic formulations. A direct-to-consumer online sales model, emphasizing product origin stories and sustainability credentials, provides a compelling go-to-market angle. This strategy capitalizes on discerning consumer preferences for verifiable transparency.
For Investors and Strategic Acquirers: Specialized organic processors with strong brand equity and direct relationships with smallholder farmer cooperatives represent attractive acquisition targets. The long-term viability of this market is strong, supported by persistent demand for natural and plant-based ingredients over the next decade. A signal to watch is the increasing market share of coconut milk and cream in new plant-based food applications, indicating sustained category expansion. Focus on companies with robust certification infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Diversify Raw Material Sourcing | Mitigates geographic supply concentration risks from Indonesia and the Philippines, enhancing supply chain resilience. |
| Invest in Nano-emulsification Technology | Enables new product formats in functional beverages and personal care, expanding market reach and product utility. |
| Strengthen Organic Certification Programs | Secures premium market access and builds consumer trust, especially in demand-heavy European and US markets. |
| Expand Direct-to-Consumer Channels | Captures higher margins and fosters direct brand engagement with increasingly discerning retail customers. |
| Develop Byproduct Valorization Projects | Creates new revenue streams from coconut husks and shells, improving overall operational profitability and sustainability. |
Research Approach
Two parallel data streams informed the analysis: primary stakeholder interviews and extensive secondary validation. Primary insights were gathered through conversations with food manufacturers, personal care formulators, procurement managers, and representatives from smallholder farmer cooperatives. This qualitative data was then triangulated with quantitative information from secondary sources, including USDA and EU organic standards, global trade statistics, and company financial reports. The approach combined bottom-up market sizing with top-down validation.
The forecasting boundary for this market extends across the analysis window, utilizing a robust analytical framework to project future trends. Segmentation dimensions modeled include product type, distribution channel, end user, form, and regional production hubs, providing a granular view. Compound Annual Growth Rates were derived through a regression analysis of historical data and projected forward based on identified growth catalysts. Key industry-specific forecast inputs included plant-based diet adoption rates and the expansion of organic certification frameworks.
Underlying assumptions cover stable raw material supply and consistent regulatory frameworks, with deviation risk concentrated in climate-related events, geopolitical shifts in producing nations, and significant input price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Noni Fruit Powder Market
Fruits and Vegetables
Aubergine Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Kuwait Vegetables and Fruits Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Global Banana Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Annatto Market