
 Psyllium-Based Supplement Market | 2026-2036
Psyllium-Based Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
Psyllium-Based Supplement Market Analytics
Single-serve sachet bundling is hardening as the dominant configuration pattern, replacing bulk jars in pharmacy and online channels. NOW Foods leverages its direct-to-consumer infrastructure to control shelf positioning in North American health stores. Patanjali Ayurved Limited anchors its domestic India presence through Ayurvedic retail networks that emphasize whole-husk traditional formats. Satnam Psyllium Industries specializes in B2B powder supply to contract manufacturers, sustaining volume throughput without branded competition.
Psyllium-based supplements derive from Plantago ovata seed husks, containing soluble fiber that forms a mucilaginous gel at 8-10 times its dry weight in water, primarily functioning to regulate bowel transit and support glycemic response. The product type landscape tilts toward capsules and powders, where convenience and dose precision concentrate margin pools away from raw husk commodity sales. Purity grade segmentation shows organic and non-GMO certifications commanding price premiums as clean-label procurement intensifies among health-conscious consumers and diabetics.
FDA dietary supplement GMPs and FSSAI labeling mandates shape formulation transparency and import clearance protocols for psyllium products crossing into the United States and India. The EU's nutrition and health claims regulation restricts specific gastrointestinal benefit wording, forcing brands to navigate compliant messaging across member state enforcement variations. EFSA pending opinions on fiber-specific health claims will determine whether European market access expands or contracts for psyllium entrants. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with addressable demand pools.
Market Dynamics
Clean-label certification mandates from FSSAI and FDA are compressing formulation transparency timelines while psyllium cultivation clusters in Gujarat and Rajasthan concentrate raw material sourcing power among contract manufacturers.
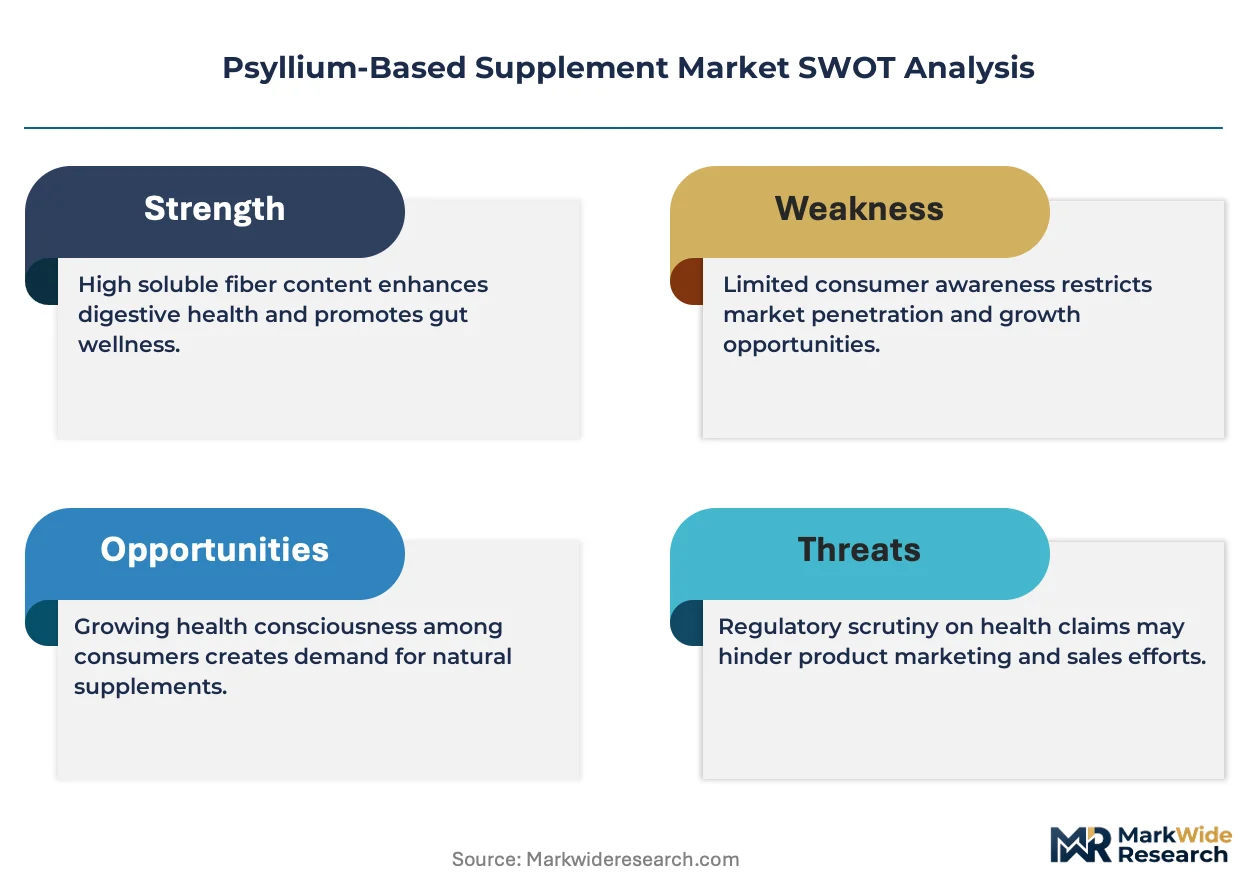
Growth Catalysts
- FSSAI Fortification Guidelines:India's mandatory micronutrient fortification protocols are expanding psyllium inclusion in functional food matrices, pulling husk demand from pharmaceutical into nutraceutical channels.
- Soluble Fiber Glycemic Response Science:Clinical validation of psyllium's postprandial glucose modulation is penetrating diabetic consumer segments, creating repeat-purchase velocity in pharmacy retail.
- Gujarat-Rajasthan Cultivation Clusters:Geographic concentration of Plantago ovata farming is enabling just-in-time powder processing for North American and European contract manufacturers.
Market Restraints
- Monsoon-Dependent Raw Material Volatility:Rajasthan's rain-fed psyllium crop exposes processors to annual yield swings that transmit directly into husk spot pricing.
- EU Nutrition and Health Claims Regulation:EFSA's restrictive gastrointestinal benefit wording prevents specific transit-time messaging, forcing European brands into vague "general well-being" positioning that dilutes conversion.
- Synthetic Soluble Fiber Substitution:Maltodextrin-based prebiotic fibers from corn starch are undercutting psyllium on cost in mass-market beverage applications.
Strategic Opportunities
- Single-Serve Sachet Pharmacy Channel:India's Ayurvedic retail networks are replacing bulk husk jars with unit-dose formats that command shelf-space premiums and expand airport duty-free placement.
- Organic Certification Arbitrage:USDA Organic and India Organic dual-certification is opening price-tier separation for export-oriented processors serving North American natural product retailers.
- Diabetic Meal-Replacement Convergence:Psyllium-gel texture properties are integrating with protein isolate systems in controlled-glycemic shake formulations for metabolic health protocols.
Industry Challenges
- Dual-Jurisdiction GMP Compliance:FDA dietary supplement GMPs and FSSAI labeling mandates impose conflicting batch-record formats that elongate import clearance timelines for cross-border brands.
- Husk Purity Testing Capacity Bottlenecks:Third-party laboratories in Ahmedabad and Gandhinagar face queue compression during harvest-season certification surges, delaying organic claim substantiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Psyllium-Based Supplement Market |
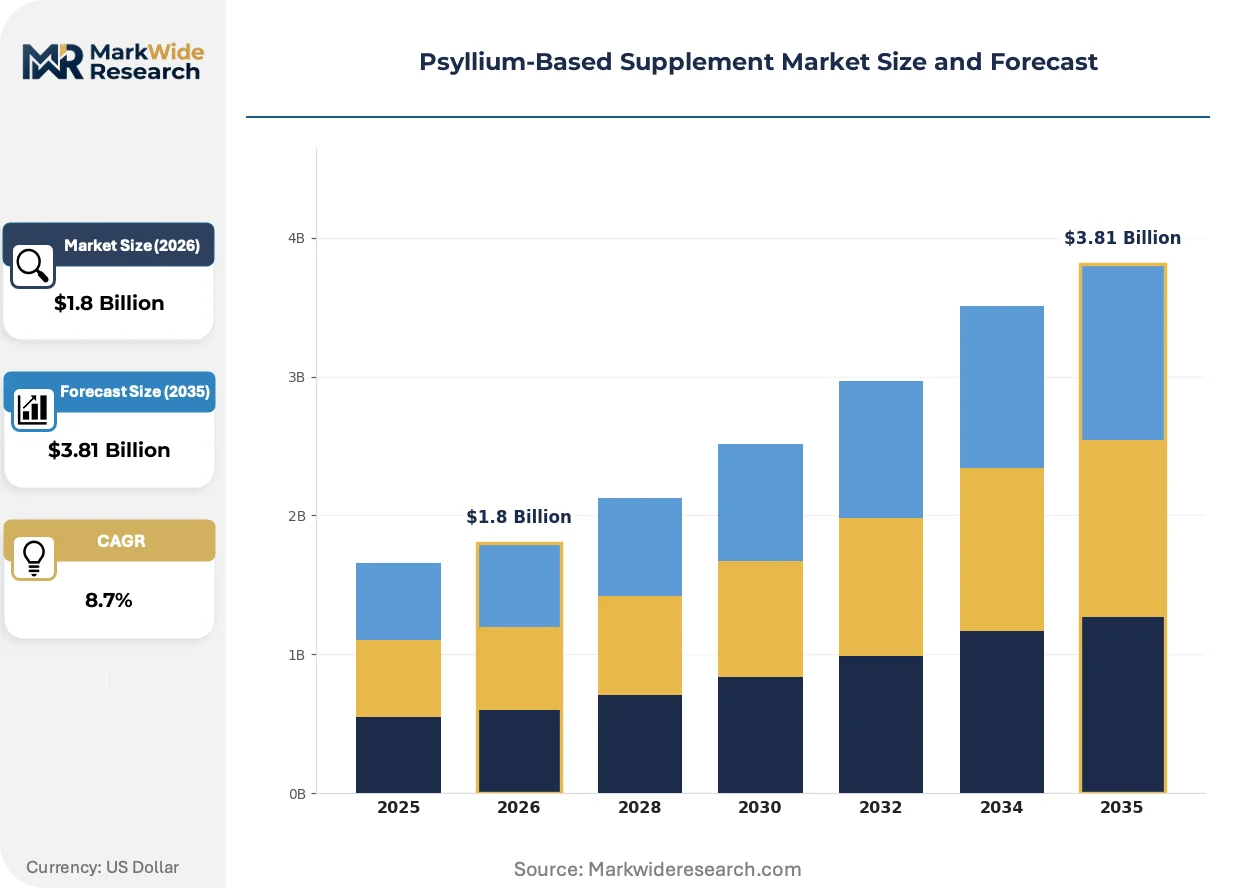
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Psyllium Husk, Powder, Capsules, Granules Purity Grade: Standard, High Purity, Organic, Non-GMO End User: Health Conscious Consumers, Fitness Enthusiasts, Seniors, Diabetics Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Patanjali Ayurved Limited, Yerba Prima, NOW Foods, Satnam Psyllium Industries, Viva Naturals, Tata Consumer Products Limited, Jyot Overseas Pvt. Ltd., Gayatri Psyllium Industries, Himalaya Wellness Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Psyllium-Based Supplement Market Evolving Landscape
Microencapsulation and cold-press processing are reshaping psyllium's functional delivery, while regulatory divergence between FDA and EFSA claim frameworks is forcing parallel formulation strategies.
Cold-press husk processing is consolidating quality-tier separation in the powder segment. Premium supplement brands in North American health stores are adopting this method to preserve mucilaginous gel viscosity. The technology is consolidating margin capture away from heat-dried commodity husk suppliers.
EFSA's pending fiber-specific health claims opinions are compressing European market entry timelines. Brands must pre-position compliant messaging before 2025 enforcement windows tighten. Diabetic-focused product lines face the highest reformulation exposure.
Direct-to-consumer subscription models are displacing pharmacy bulk purchasing among fitness enthusiasts. NOW Foods and Patanjali are diverging on channel strategy—one scaling automated replenishment, the other reinforcing Ayurvedic retail density. This bifurcation is most visible in urban Indian metros and North American coastal cities.
Psyllium-Based Supplement Market Segmentation
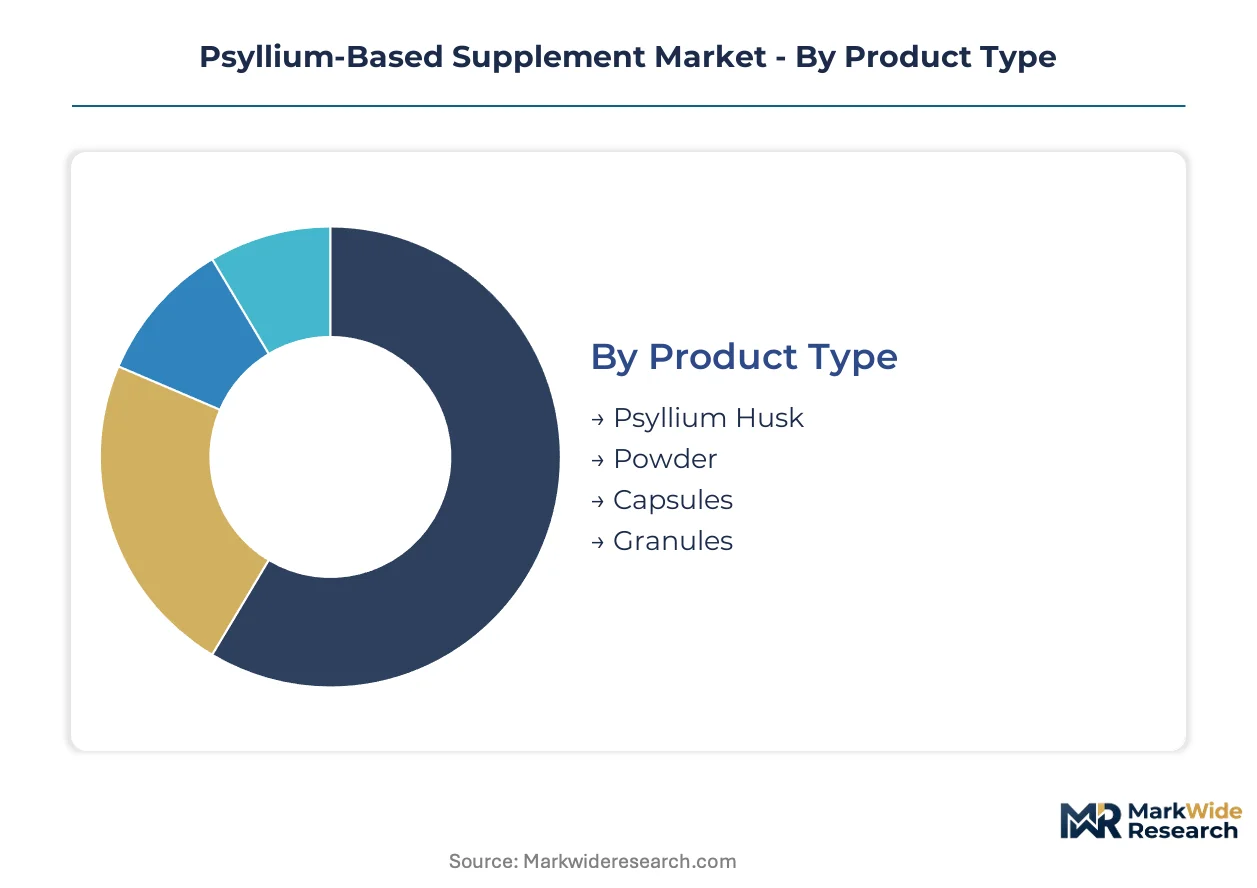
Psyllium-based supplement segmentation reveals how capital deployment and regulatory compliance costs concentrate margin capture across distinct product tiers. Manufacturers must align purification investments with addressable demand pools that diverge sharply by end-user health status and channel access.
Product Type:
Capsule and powder formats absorb the heaviest upfront capital for precision dosing equipment and moisture-controlled filling lines, while raw husk processing requires minimal fixed-asset commitment.
- Psyllium Husk:Whole-seed outer coating sold in bulk retains traditional Ayurvedic positioning. Gujarat's contract manufacturers dominate supply to North American natural product importers seeking unprocessed inputs for in-house encapsulation.
- Powder:Mechanically milled husk at 40-60 mesh particle size enables rapid gel formation. Cold-press processing preserves mucilaginous viscosity for premium diabetic meal-replacement formulations in US health stores.
- Capsules:Pre-measured doses eliminate scoop variability for fitness enthusiasts tracking macronutrient intake. Hard-shell gelatin and HPMC vegetarian variants split procurement between pharmacy and direct-to-consumer channels.
- Granules:Agglomerated particles improve dispersibility in beverage applications. Satnam Psyllium Industries supplies B2B volumes to European contract manufacturers facing EFSA health claim restrictions.
Most installed capacity flows through Powder. Expansion is steepest in Capsules.
Purity Grade:
Organic and Non-GMO tiers extract price premiums through dual-certification auditing costs that standard grades bypass entirely.
- Standard:Conventional husk meeting basic FSSAI and FDA purity thresholds. Rajasthan rain-fed cultivation supplies mass-market bulk jars through Indian Ayurvedic retail networks.
- High Purity:Refined to 99%+ mucilage content with reduced sand and extraneous matter. US pharmaceutical contract manufacturers specify this grade for fiber supplements making structure-function claims.
- Organic:USDA Organic and India Organic dual-certification requires three-year transition fields and segregated processing lines. Ahmedabad laboratories face queue compression during harvest-season certification surges.
- Non-GMO:Identity-preserved supply chains from Gujarat cultivation clusters satisfy North American clean-label procurement mandates without full organic compliance cost.
Organic commands the widest price-tier separation. Non-GMO is gaining share fastest among export-oriented processors.
End User:
Diabetic and senior segments concentrate repeat-purchase velocity through pharmacy channel reimbursement alignment, while fitness enthusiasts drive subscription model adoption.
- Health Conscious Consumers:Broad demographic seeking preventive gut health maintenance. Single-serve sachet bundling replaces bulk jars in online retail channels serving this price-sensitive segment.
- Fitness Enthusiasts:Protein-shake integration drives demand for neutral-taste, rapid-dispersing powder. NOW Foods targets automated replenishment to capture coastal US metro demand.
- Seniors:Regularity-focused positioning aligns with pharmacy shelf placement. FSSAI fortification guidelines expand psyllium inclusion in functional food matrices targeting this demographic.
- Diabetics:Clinical validation of postprandial glucose modulation creates protocol-driven prescribing. Controlled-glycemic shake formulations integrate psyllium-gel texture with protein isolate systems.
Diabetics generate the highest per-user lifetime value. Fitness enthusiasts show the steepest subscription growth curve.
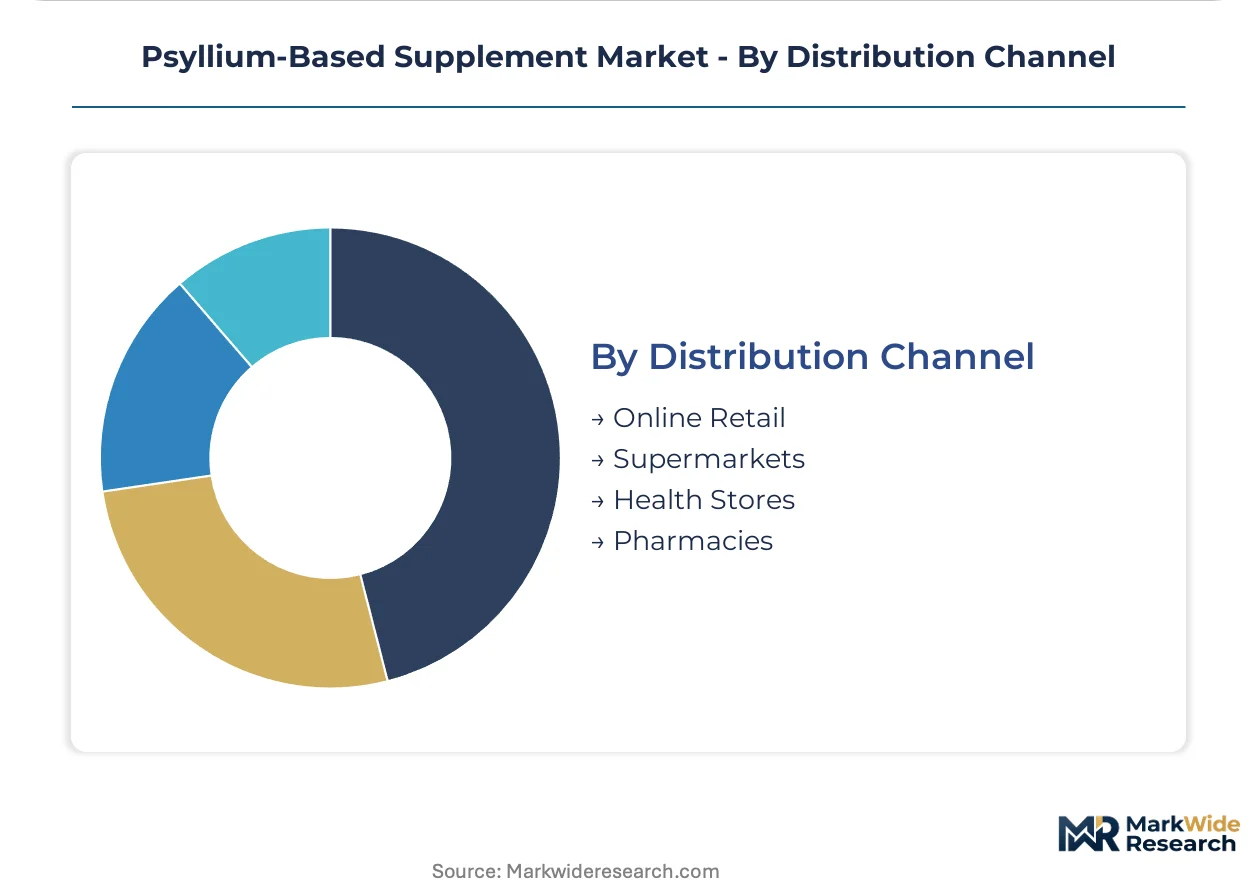
Distribution Channel:
Online retail and pharmacy channels diverge on working capital intensity—direct-to-consumer demands inventory risk absorption while pharmacy placement requires slotting fee negotiation.
- Online Retail:Direct-to-consumer infrastructure enables automated replenishment and first-party data capture. NOW Foods leverages this channel to control shelf positioning without wholesale margin sharing.
- Supermarkets:Mass-market reach demands price-competitive standard-grade powder. Maltodextrin-based prebiotic fiber substitution threatens psyllium placement in beverage aisles.
- Health Stores:Premium positioning accommodates cold-press processed organic powder. North American natural product retailers specify dual-certification for clean-label procurement compliance.
- Pharmacies:Unit-dose sachet formats command shelf-space premiums and expand airport duty-free placement. Patanjali Ayurved Limited anchors presence through Ayurvedic retail network density in Indian urban metros.
Pharmacy channels capture the highest margin per unit. Online retail is climbing the fastest on volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Psyllium cultivation originated in the Mediterranean basin before commercial scaling shifted to the Indian subcontinent during the colonial era. Gujarat and Rajasthan now supply the majority of global raw material, with processing infrastructure concentrated around Ahmedabad and Gandhinagar.
United States
FDA dietary supplement GMPs govern import clearance protocols for psyllium husk entering through East and West Coast ports. The agency's structure-function claim framework permits bowel health messaging that EFSA restricts. NOW Foods leverages direct-to-consumer infrastructure to control shelf positioning in health stores across California and New York.
India
FSSAI fortification guidelines mandate micronutrient inclusion in functional food matrices, pulling husk demand from pharmaceutical into nutraceutical channels. The regulator's clean-label certification mandates compress formulation transparency timelines for domestic manufacturers. Gujarat's contract manufacturers around Gandhinagar dominate powder processing for North American export.
Germany
EFSA's pending fiber-specific health claims opinions determine whether European market access expands for psyllium entrants. The regulator's restrictive gastrointestinal benefit wording forces brands into vague positioning. Hamburg and Frankfurt health stores specify dual-certification for clean-label procurement compliance.
United Kingdom
Post-Brexit divergence from EU health claims regulation creates parallel compliance requirements for psyllium supplements. The UK's national pharmaceutical regulator maintains distinct batch-record formats. London and Southeast England concentrate diabetic consumer segments driving pharmacy channel placement.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate oversees psyllium supplement licensing through the Natural Product Number system. The regulator's evidence requirements for fiber claims align more closely with FDA than EFSA frameworks. Toronto and Vancouver health stores anchor premium organic powder distribution.
Psyllium-Based Supplement Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and channel-control dimensions. The vendor base organizes into three tiers: Ayurvedic heritage brands with retail network density, direct-to-consumer specialists with subscription infrastructure, and B2B powder suppliers without branded competition. Strategic archetypes include vertical integrators controlling cultivation-through-retail value chains, contract manufacturers serving private-label demand, and clean-label certifiers capturing organic price premiums. Dominant competitive moves center on backward integration into Rajasthan cultivation clusters and geographic expansion through airport duty-free placement.
Within the Ayurvedic heritage tier, Patanjali Ayurved Limited and Himalaya Wellness Company occupy positions emphasizing traditional whole-husk formats through domestic Indian retail density. NOW Foods exemplifies the direct-to-consumer archetype with automated replenishment infrastructure targeting North American fitness enthusiasts. Satnam Psyllium Industries anchors the B2B powder supply segment, sustaining volume throughput to contract manufacturers without competing at branded retail.
| Leading Market Players |
|---|
| Patanjali Ayurved Limited |
| Yerba Prima |
| NOW Foods |
| Satnam Psyllium Industries |
| Viva Naturals |
| Tata Consumer Products Limited |
| Jyot Overseas Pvt. Ltd. |
| Gayatri Psyllium Industries |
| Himalaya Wellness Company |
| Others |
Value Network & Pricing Analysis
Backward integration into Rajasthan cultivation clusters anchors supply security and pricing power for processors serving North American health stores. Captive husk sourcing insulates premium brands from monsoon-driven spot volatility while compressing procurement spreads between organic and standard grades.
Pricing Analysis
Three-tier pricing structure across organic, high-purity, and standard levels separates contract manufacturers by certification investment depth. USDA Organic dual-certification extracts the widest premium from North American natural product retailers, while standard-grade Rajasthan supply feeds price-sensitive Ayurvedic bulk channels. Pricing pressure stems from maltodextrin-based prebiotic substitution in mass-market beverage applications. Fitness enthusiasts show lowest price sensitivity through subscription lock-in; health-conscious consumers in online retail exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Gujarat and Rajasthan rain-fed cultivation, where monsoon dependency concentrates annual yield risk among processors. Raw material supply draws from Plantago ovata seed husks, cold-press processing equipment, and third-party laboratory certification capacity in Ahmedabad. Tariff exposure looms for cross-border brands navigating FDA-FSSAI batch-record conflicts. Distribution runs through direct-to-consumer platforms, Ayurvedic retail networks, and pharmacy unit-dose placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Diabetic consumer segments are pulling formulation investment toward clinically validated glycemic response specifications.
For Market Incumbents: Anticipate synthetic fiber substitution in mass-market beverage channels by deepening organic certification moats. NOW Foods and Patanjali should compress FSSAI-FDA compliance timelines through unified batch-record formats. Backward integration into Gandhinagar processing infrastructure defends margin position against spot husk volatility. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription infrastructure targeting coastal US fitness enthusiasts with neutral-taste rapid-dispersing powder. European market entry demands pre-positioned EFSA-compliant messaging ahead of enforcement window tightening. Airport duty-free pharmacy placement in Indian urban metros offers the most penetrable white-space for unit-dose sachet formats. For Investors and Strategic Acquirers: Roll-up economics work for dual-certified organic processors because certification queue compression in Ahmedabad creates scarcity value for compliant supply. Five-to-ten year viability hinges on diabetic meal-replacement convergence with protein isolate systems. Watch EFSA fiber-specific health claims opinions as the inflection signal for European market access expansion or contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Clusters | Captive Rajasthan supply insulates processors from monsoon-driven spot price volatility. |
| Dual-Certification Investment | USDA Organic and India Organic compliance opens premium tier access in North American health stores. |
| Direct-to-Consumer Platform Launch | Automated replenishment captures fitness enthusiast subscription velocity in coastal US metros. |
| EFSA Pre-Positioning Strategy | Compliant messaging development ahead of fiber-specific health claims opinions secures European market entry. |
| Airport Duty-Free Pharmacy Placement | Unit-dose sachet formats command shelf-space premiums in Indian Ayurvedic retail networks. |
Research Methodology
Multiple input streams — regulatory filings from FDA and FSSAI, customs export records from Gujarat ports, and health store procurement audits — were reconciled through bottom-up and top-down triangulation. Primary interviews with contract manufacturing executives, Ayurvedic retail network managers, third-party laboratory directors in Ahmedabad, and diabetic nutrition protocol specialists informed supply chain and demand modeling. Secondary validation drew from EFSA pending opinions, FSSAI fortification guideline releases, and North American natural product retailer clean-label procurement mandates.
Data-stream reconciliation across the analysis window applied segmentation dimensions spanning product type, purity grade, end-user health status, and distribution channel. CAGRs were derived from installed capacity tracking in Gandhinagar processing clusters and diabetic consumer segment repeat-purchase velocity in pharmacy channels. Forecast inputs incorporated monsoon yield variance patterns and EFSA regulatory timeline uncertainty.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme monsoon failure or EFSA claim restriction scenarios. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Ferrous Fumarate Market
Nutritional Supplements
North America Prenatal Supplements Market
Nutritional Supplements
South Africa Collagen Peptides Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Multi Nutritional Supplement Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market
Nutritional Supplements
High-Selenium Yeast Market
Nutritional Supplements
US Hangover Cure Products Market
Nutritional Supplements
Global Vitamin Supplements Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Garlic Extract Supplement Market
Nutritional Supplements
North America Collagen Supplements Market
Nutritional Supplements
Zinc Supplement Market