
 Saudi Arabia Fruits and Vegetables Market | 2026-2036
Saudi Arabia Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Fruits and Vegetables Market Outlook
Pre-packaged portion formats are decoupling bulk produce from traditional wholesale channels, giving households and food service providers direct access to calibrated SKUs without intermediary repacking. Abdullah Al-Othaim Markets leverages its hyperlocal store network to dominate same-day vegetable turnover in Eastern Province catchments. LULU Group International anchors its Gulf sourcing hub in Riyadh, securing direct farm contracts that bypass conventional auction floors. Carrefour competes through centralized distribution centers that control temperature integrity from port to shelf.
Saudi Arabia fruits and vegetables encompass fresh and minimally processed plant products distributed through temperature-controlled supply chains, with shelf-life parameters typically ranging from three days for leafy greens to four weeks for citrus under modified atmosphere storage. Their primary commercial purpose spans direct household consumption, ingredient supply to restaurant chains, and export re-export through Jeddah Islamic Port. Citrus fruits lead volume throughput at wholesale terminals, while online retail represents the fastest-growing distribution channel as digital payment penetration deepens. Food service providers command the highest per-order value among end user segments, though households generate the greatest transaction frequency.
SFDA mandates govern pesticide residue thresholds and cold chain documentation for domestic circulation, while SASO technical regulations specify packaging material standards for polyethylene crates and corrugated cartons. MOHAP coordinates with municipal authorities in Mecca and Medina to enforce seasonal price stabilization mechanisms during pilgrimage surges. Stakeholders must monitor how SFDA's traceability platform requirements will reshape supplier qualification criteria and inventory recording obligations across the kingdom's produce value chain.
Market Dynamics
SFDA traceability mandates and cold chain digitization are compressing supplier qualification timelines while concentrating procurement authority among vertically integrated retail networks across Riyadh and Jeddah.
Growth Catalysts
- Pre-cut Vegetable Lines:Food service providers in Riyadh and Jeddah are expanding procurement of calibrated portion formats that bypass traditional wholesale repacking stages.
- SFDA Cold Chain Protocols:Enforcement of updated food safety documentation requirements is accelerating investment in temperature-controlled logistics infrastructure.
- Central Region Wholesale Terminal:Riyadh's consolidated distribution infrastructure anchors volume throughput for citrus and leafy greens circulating to Eastern Province retail networks.
Market Restraints
- Water Input Volatility:Agricultural production costs fluctuate with desalinated water pricing and groundwater extraction limits enforced by the Ministry of Environment, Water and Agriculture.
- Import Concentration Risk:Over half of domestic fruit supply transits through Jeddah Islamic Port, creating single-point vulnerability for perishable cargo clearance delays.
- Polyethylene Packaging Standards:SASO technical regulations for corrugated cartons and plastic crates impose material specification costs that squeeze margin at wholesale tier.
Strategic Opportunities
- Eastern Province Catchments:Hyperlocal store networks in Dammam and Al-Khobar remain underpenetrated for same-day vegetable turnover versus Riyadh benchmarks.
- Modified Atmosphere Storage:Convergence of sensor telemetry and automated gas-flush systems extends citrus shelf life from days to weeks, enabling inventory pooling across retail banners.
- Digital Payment Penetration:Online retail channels for fresh produce are capturing transaction frequency from traditional souk formats as mobile wallet adoption deepens.
Industry Challenges
- Cold Chain Technician Scarcity:Refrigeration engineering and HACCP audit skills lag demand as SFDA documentation requirements multiply across port-to-shelf networks.
- Traceability Platform Integration:Legacy inventory recording systems at municipal wholesale terminals require reconfiguration to interface with SFDA's centralized supplier qualification database.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Fruits and Vegetables Market |
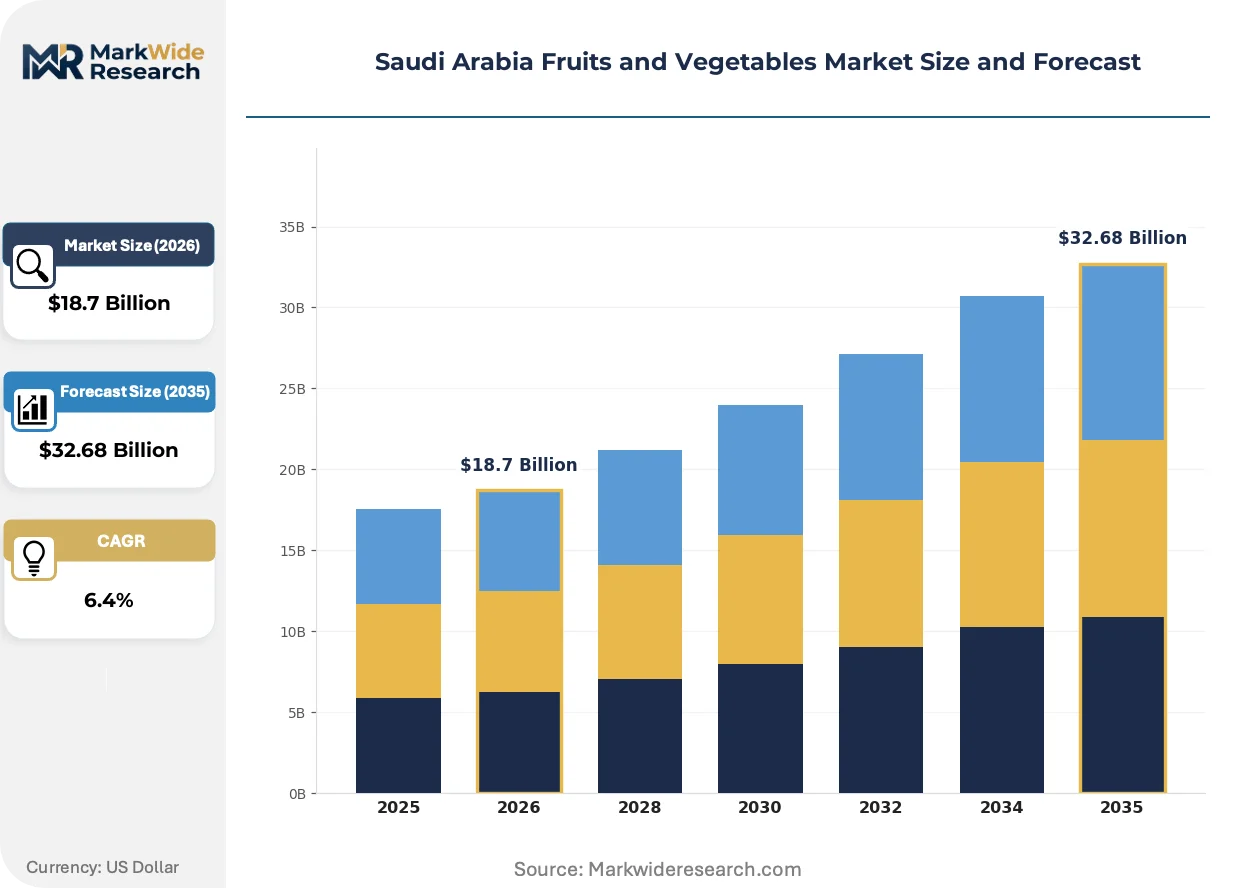
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Fruits, Leafy Greens, Root Vegetables, Stone Fruits Distribution Channel: Supermarkets, Wholesalers, Farmers’ Markets, Online Retail End User: Households, Food Service Providers, Retailers, Exporters Packaging Type: Plastic Crates, Cartons, Bags, Shrink Wrap |
| Companies Covered | Carrefour, Abdullah Al-Othaim Markets, Spar International, LULU Group International, Tamimi Markets, Panda, Danube, Bin Dawood, Al Rai Food Industries Est, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Fruits and Vegetables Market Strategic Shifts
Sensor-enabled logistics and regulatory digitization are compressing the gap between harvest and retail shelf while fragmenting procurement authority across new channel formats.
Blockchain-integrated shipment tracking is decentralizing custody verification for temperature-sensitive cargo. Large retail banners are piloting distributed ledger systems that bypass centralized port authority documentation. This architecture is decentralizing liability assignment from terminal operators to individual trucking fleets and cold storage facilities.
SFDA's phased implementation of electronic traceability certificates is mandating real-time pesticide residue data submission. Domestic distributors must retrofit procurement workflows to capture farm-level batch codes. Fresh produce importers face the steepest compliance curve as cross-border documentation standards diverge from Gulf Cooperation Council harmonization timelines.
Household buyers are consolidating weekly purchases through subscription-based produce boxes that displace daily souk visits. Food service providers in Riyadh's hospitality corridor are mirroring this pattern with scheduled delivery contracts replacing spot-market buying. The Central Region exhibits the fastest behavioral transition as digital-native retailers capture frequency from traditional wholesale terminals.
Saudi Arabia Fruits and Vegetables Market Segmentation
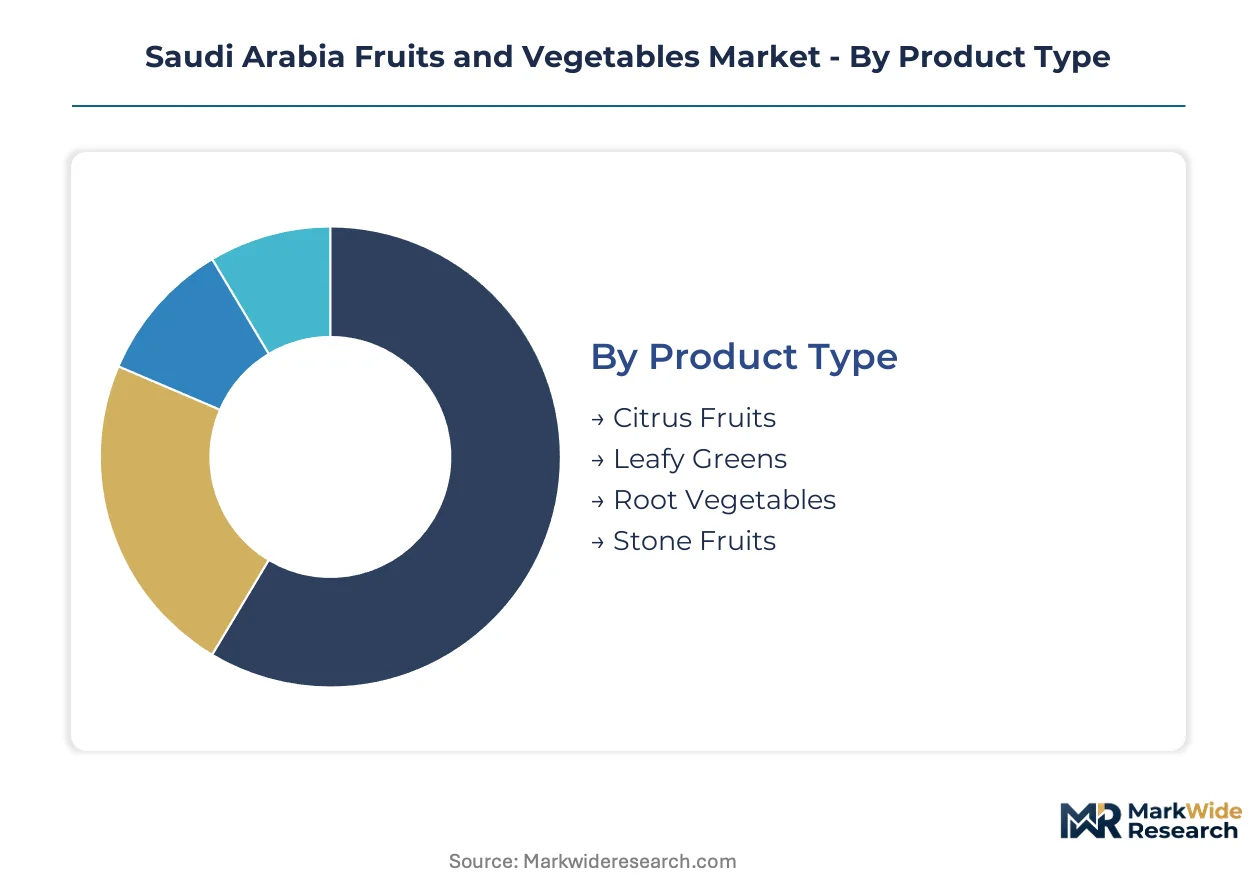
Saudi Arabia's fruits and vegetables market fragments across four critical dimensions that determine cold chain investment intensity and margin capture. Each segmentation axis reveals distinct capital requirements, from modified atmosphere storage infrastructure to last-mile temperature integrity systems.
Product Type:
Capital intensity varies sharply across fresh produce categories, with shelf-life parameters dictating refrigeration infrastructure scale and throughput velocity.
- Citrus Fruits:Oranges, lemons, and grapefruits tolerate extended storage under controlled atmosphere conditions, enabling inventory pooling across Riyadh's wholesale terminals. Volume concentrates at Central Region distribution hubs serving Eastern Province retail networks.
- Leafy Greens:Spinach, lettuce, and herbs demand three-day shelf-life windows and continuous cold chain integrity from farm to shelf. Premium positioning in Jeddah's food service corridor absorbs disproportionate logistics investment per kilogram.
- Root Vegetables:Carrots, potatoes, and beets offer longer ambient tolerance, reducing per-unit refrigeration costs for wholesalers operating outside temperature-controlled infrastructure.
- Stone Fruits:Peaches, plums, and apricots require precise ethylene management during ripening, constraining supplier qualification to specialized cold storage operators.
Citrus fruits absorb the bulk of installed cold storage capacity; leafy greens are expanding most quickly as pre-cut formats penetrate food service procurement.
Distribution Channel:
Channel selection determines custody transfer complexity and documentation burden under SFDA traceability mandates.
- Supermarkets:Carrefour and LULU Group International operate centralized distribution centers that maintain temperature integrity from port arrival through shelf placement. Same-day replenishment cycles in Riyadh and Jeddah compress inventory holding periods.
- Wholesalers:Municipal terminals in Riyadh aggregate volume from domestic farms and Jeddah Islamic Port imports, functioning as price discovery mechanisms for Eastern Province buyers. Legacy inventory systems face SFDA platform integration deadlines.
- Farmers' Markets:Direct producer-to-consumer sales in Mecca and Medina bypass formal cold chain documentation, though seasonal pilgrimage surges trigger MOHAP price stabilization enforcement.
- Online Retail:Digital payment penetration enables subscription produce boxes that displace daily souk visits. Mobile wallet adoption accelerates transaction frequency capture from traditional wholesale formats.
Supermarkets command the steepest capital commitment per outlet; online retail is gaining share fastest as digital-native retailers consolidate weekly purchase patterns.
End User:
Customer type dictates order granularity, payment terms, and quality specification stringency across the value chain.
- Households:Individual consumers generate highest transaction frequency through hyperlocal store networks, with Abdullah Al-Othaim Markets dominating same-day vegetable turnover in Eastern Province catchments.
- Food Service Providers:Hotels and restaurant chains in Riyadh's hospitality corridor command highest per-order values, driving demand for calibrated pre-cut portions that eliminate in-house prep labor.
- Retailers:Independent grocers rely on wholesale terminal pricing with limited backward integration, exposing margins to polyethylene packaging cost volatility under SASO regulations.
- Exporters:Re-export operations through Jeddah Islamic Port require cross-border documentation alignment with Gulf Cooperation Council harmonization timelines, creating compliance complexity for fresh produce importers.
Food service providers concentrate procurement authority for premium-tier produce; households are expanding fastest as subscription formats capture frequency from spot-market buying.
Packaging Type:
Material specification standards under SASO technical regulations impose tiered compliance costs that reshape competitive positioning at wholesale tier.
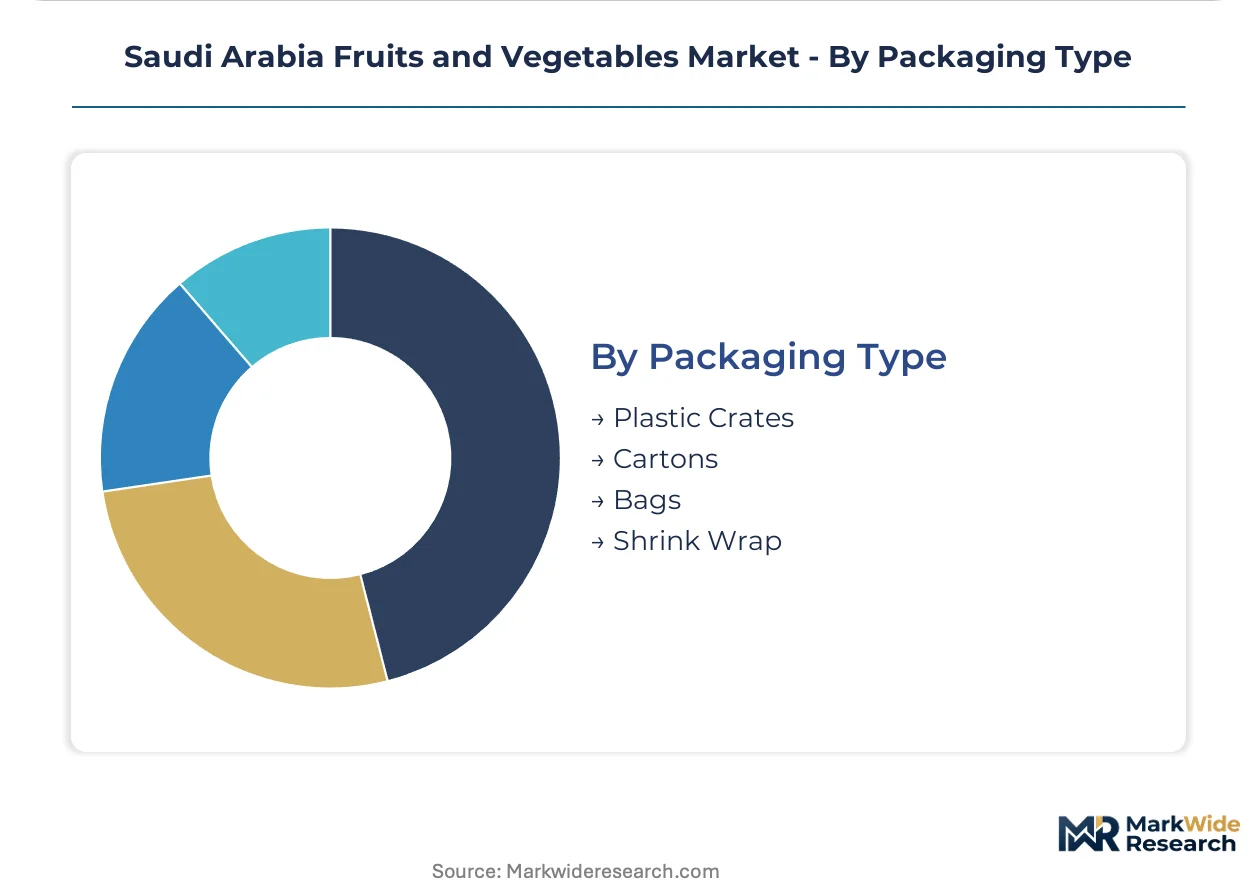
- Plastic Crates:Reusable polyethylene containers dominate citrus and root vegetable circulation, with standardized dimensions enabling automated handling at Riyadh's consolidated distribution infrastructure.
- Cartons:Corrugated fiberboard formats for leafy greens and stone fruits face moisture resistance specifications that elevate material costs for suppliers serving supermarket banners.
- Bags:Polyethylene film packaging for portioned produce encounters thickness and recyclability mandates that squeeze margin for wholesale repacking operations.
- Shrink Wrap:Film enclosure for palletized loads protects temperature integrity during intercity transit from Central Region terminals to Eastern Province destinations.
Plastic crates represent the dominant installed base; cartons are climbing fastest as sustainable packaging specifications tighten across retail procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's domestic production covers roughly one-third of fruit and vegetable consumption, with the balance arriving through Jeddah Islamic Port and overland corridors from Jordan and Egypt. This supply gap shapes infrastructure investment patterns across the kingdom's five macro-regions.
Riyadh
Central Region demand concentrates in Riyadh's wholesale terminal infrastructure, where citrus volume pools before redistribution to Eastern Province retail networks. SFDA traceability mandates are compressing supplier qualification timelines for distributors operating from this hub. The Riyadh-based consolidated distribution infrastructure anchors temperature-controlled throughput for leafy greens circulating nationwide.
Eastern Province
Food service procurement in Dammam and Al-Khobar is expanding pre-cut vegetable lines for hospitality and catering sectors. Abdullah Al-Othaim Markets leverages hyperlocal store density to dominate same-day vegetable turnover across this catchment. Municipal authorities in Dammam are coordinating with MOHAP on seasonal price stabilization ahead of pilgrimage surges affecting nearby transit routes.
Western Region
Jeddah Islamic Port handles over half of domestic fruit imports, creating concentrated clearance risk for perishable cargo from Egypt and Turkey. Carrefour operates centralized distribution centers here that maintain cold chain integrity from port arrival through shelf placement. Retail procurement in Mecca and Medina triggers MOHAP enforcement of price ceilings during Umrah and Hajj peak periods.
NEOM Northwest
Emerging demand from giga-project construction crews is pulling dedicated produce supply chains into Tabuk province. LULU Group International is securing direct farm contracts that bypass conventional auction floors for this developing catchment. SASO packaging regulations for polyethylene crates are being enforced earlier here as a pilot zone for next-generation logistics standards.
Saudi Arabia Fruits and Vegetables Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Saudi Arabia's fruits and vegetables value chain. The market exhibits tiered concentration: multinational retail banners control import-to-shelf logistics, while regional family-owned distributors dominate wholesale terminal price discovery. Three archetypes define competitive positioning: vertically integrated retail networks, hyperlocal store operators, and import-dependent wholesale distributors. Dominant competitive moves include backward integration into direct farm contracting and centralized distribution center expansion.
Within the multinational retail tier, Carrefour and LULU Group International represent divergent sourcing strategies—Carrefour through centralized temperature-controlled infrastructure, LULU through Gulf hub consolidation in Riyadh. Among domestic operators, Abdullah Al-Othaim Markets exemplifies the hyperlocal archetype with Eastern Province store density enabling same-day inventory turns. These three entities anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| Carrefour |
| Abdullah Al-Othaim Markets |
| Spar International |
| LULU Group International |
| Tamimi Markets |
| Panda |
| Danube |
| Bin Dawood |
| Al Rai Food Industries Est |
| Others |
Value Chain & Pricing Dynamics
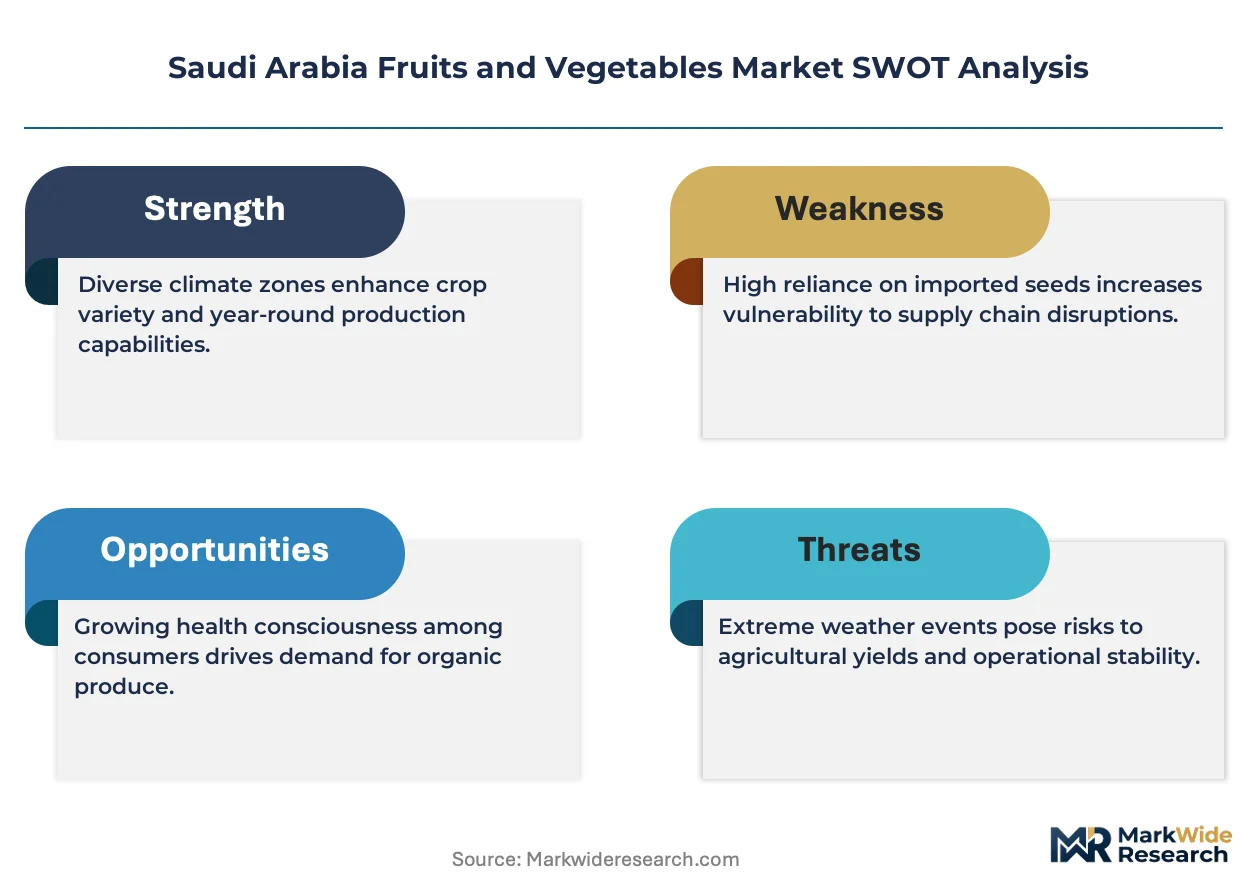
Cold chain technician scarcity in Riyadh and Jeddah widens pricing-tier spreads as labor-cost differentials between certified operators and general handlers force premium-mid-economy pricing differentiation across perishable categories. SFDA documentation requirements multiply audit burdens, concentrating margin capture among vertically integrated retail networks that internalize compliance costs.
Pricing Analysis
Margin tightening in wholesale tiers reflects polyethylene packaging cost volatility under SASO technical regulations for corrugated cartons and plastic crates. Three-tier pricing structure across premium, standard, and economy levels separates supermarket banners with centralized distribution from municipal terminal operators and independent grocers. Cost-down pressure on economy tiers accelerates because import concentration through Jeddah Islamic Port exposes spot buyers to clearance delay risks. Food service providers in Riyadh's hospitality corridor show least price sensitivity for pre-cut vegetable lines, while household buyers in Eastern Province catchments exhibit highest sensitivity to subscription produce box pricing.
Supply Chain Analysis
Reverse logistics for polyethylene crates and corrugated cartons flows through Riyadh's consolidated distribution infrastructure, where reusable container pooling reduces per-trip packaging costs for citrus and root vegetable circuits. Geographic supply concentration centers on Egypt, Turkey, and Jordan for overland fruit corridors, with Jeddah Islamic Port handling the bulk of maritime imports. Raw material dependencies rest on desalinated water pricing, polyethylene resin specifications, and modified atmosphere storage equipment. Single-point vulnerability at Jeddah Islamic Port creates structural risk for perishable cargo clearance delays. Distribution runs through temperature-controlled networks anchored by Carrefour and LULU Group International centralized distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's fruits and vegetables market operates as a supply-constrained system where cold chain infrastructure bottlenecks prop pricing power among qualified operators. Water input volatility and import concentration limit rapid capacity expansion.
For Market Incumbents: Lock in direct farm contracting relationships that bypass conventional auction floors, securing captive supply of citrus and leafy greens ahead of SFDA traceability mandate deadlines. Expand centralized distribution center footprint in Eastern Province catchments to capture same-day vegetable turnover from Abdullah Al-Othaim Markets' hyperlocal dominance. Cold chain technician scarcity threatens margin compression for operators dependent on third-party logistics.
For New Entrants and Emerging Players: Sensor-enabled logistics platforms offer technology-first wedge into wholesale terminal digitization gaps, where legacy inventory systems face SFDA platform integration deadlines. Target underpenetrated Eastern Province food service procurement in Dammam and Al-Khobar for pre-cut vegetable lines, where hospitality sector expansion outpaces qualified supplier growth. Deploy subscription-based produce box models with mobile wallet integration to displace daily souk visits in Central Region catchments.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists given SFDA cold chain protocol enforcement accelerating compliance investment requirements. Long-term viability favors operators with backward integration into modified atmosphere storage infrastructure and direct farm contracting capabilities across the projection horizon. Monitor desalinated water pricing announcements and groundwater extraction limit enforcement by the Ministry of Environment, Water and Agriculture as inflection indicators for domestic production cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Farm Contracting | Bypasses Riyadh auction floors, securing citrus volume for Eastern Province redistribution networks. |
| Modified Atmosphere Storage Investment | Extends stone fruit and citrus shelf life from days to weeks, enabling inventory pooling. |
| SFDA Traceability Platform Integration | Qualifies suppliers for supermarket banner procurement as documentation mandates tighten. |
| Eastern Province Distribution Expansion | Captures Dammam and Al-Khobar food service procurement growth ahead of competitor density. |
| Subscription Produce Box Launch | Consolidates weekly household purchases through mobile wallet-enabled digital channels. |
Study Parameters
SFDA regulatory filings, SASO technical regulations, and municipal trade data formed the secondary backbone, cross-referenced with customs records through Jeddah Islamic Port and Ministry of Environment, Water and Agriculture production statistics. Primary interviews with cold chain logistics directors, supermarket category buyers, food service procurement managers, and wholesale terminal operators combined with secondary validation. Bottom-up and top-down triangulation reconciled farm-level production estimates with retail throughput data across Riyadh, Jeddah, and Eastern Province catchments.
Historical trendline analysis of citrus and leafy greens volume flows through Central Region terminals informed base-case trajectory development across the projection horizon. Segmentation modeling captured product type, distribution channel, end user, and packaging type dimensions alongside regional regulatory cluster variations. CAGRs derived from fitted trend analysis adjusted for water input volatility and import concentration risk exposure. Forecast inputs incorporated SFDA traceability implementation phasing and digital payment penetration trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pilgrimage surge disruptions and groundwater extraction limit enforcement. Projections reflect assumptions around cold chain infrastructure investment continuity and cross-border documentation alignment with Gulf Cooperation Council harmonization timelines. Practitioners should monitor SFDA audit intensity, desalinated water tariff adjustments, and polyethylene packaging specification updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Frozen Vegetables Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Global Bean Sprouts Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Fresh Pumpkin Market
Fruits and Vegetables
Plums and Sloes Market