
 Oman Fruits and Vegetables Market | 2026-2036
Oman Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Fruits and Vegetables Market Analytics
Hotel and restaurant chains is redrawing procurement patterns across the Oman Fruits and Vegetables Market as hospitality operators expand direct farm partnerships. Suhail Bahwan Group leverages its diversified agribusiness portfolio to secure consistent supply lines. Gulf Mushroom Products Co. specializes in controlled-environment cultivation that reduces import dependency for specialty produce. Oman Food Investment Holding Company anchors state-backed food security mandates through strategic domestic farming assets.
Oman fruits and vegetables encompass fresh and minimally processed plant products cultivated under arid-climate conditions, typically requiring drip irrigation systems and greenhouse infrastructure to achieve viable yields in salinity-prone soils. These products serve commercial foodservice, retail distribution, and industrial processing channels across the Sultanate. Leafy Greens and Citrus Fruits dominate volume flows through Supermarkets and Wholesalers, where cold-chain reliability determines shelf-life outcomes and price realization. Online Retail represents the fastest-expanding distribution channel as digital grocery platforms gain traction among urban households in Muscat and Salalah.
The Ministry of Agriculture and Fisheries enforces phytosanitary standards that govern import substitution targets and local cultivation subsidies. FSSAI-aligned safety protocols, adapted through Oman Food Investment Holding Company quality frameworks, shape processor compliance requirements for export-oriented operations. Stakeholders must monitor groundwater allocation policies and desalination cost trajectories that determine greenhouse expansion economics in interior governorates.
Market Dynamics
Hotel and restaurant procurement consolidation is restructuring supply relationships across the Oman Fruits and Vegetables Market, forcing growers to bypass traditional wholesale intermediaries and establish direct fulfillment contracts with hospitality groups.
Growth Catalysts
- Ministry of Agriculture and Fisheries food security mandates:Subsidized greenhouse construction and preferential water allocations are expanding domestic cultivation acreage in Al Batinah South and North governorates.
- Controlled-environment agriculture:Hydroponic and aeroponic systems are enabling year-round production of leafy greens and tomatoes in salinity-compromised soils where open-field farming fails.
- Muscat hospitality corridor:Five-star hotel chains and international restaurant franchises are sourcing 60-70% of fresh produce requirements from certified Omani farms under traceability protocols.
Market Restraints
- Groundwater depletion thresholds:Ministry of Regional Municipalities and Water Resources extraction limits are constraining well-irrigation expansion in interior governorates where desalination remains uneconomical.
- Import dependency for temperate fruits:Apples, pears, and stone fruits rely on shipments from Iran, India, and European suppliers, exposing buyers to currency fluctuation and shipping disruption risks.
- Seasonal labor scarcity:Harvest peaks in January-March and September-November face acute shortages as temporary agricultural workers migrate to construction and logistics sectors offering higher wages.
Strategic Opportunities
- Dhofar Governorate expansion:Salalah's monsoon microclimate and underutilized agricultural land offer untapped potential for tropical fruit cultivation and off-season vegetable production.
- E-commerce grocery platforms:Digital direct-to-consumer channels are capturing urban household demand in Muscat and Seeb, bypassing traditional supermarket markups and reducing post-harvest losses.
- Export certification alignment:FSSAI-equivalent safety frameworks and GCC standard harmonization are opening shelf space in UAE and Saudi retail chains for Omani-certified produce.
Industry Challenges
- Post-harvest cold chain gaps:Inadequate refrigerated transport capacity between Batinah growing regions and Muscat distribution hubs causes spoilage rates exceeding acceptable thresholds for premium retail contracts.
- Phytosanitary compliance timelines:Ministry of Agriculture and Fisheries inspection and certification procedures create 48-72 hour delays that conflict with hospitality just-in-time delivery requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Fruits and Vegetables Market |
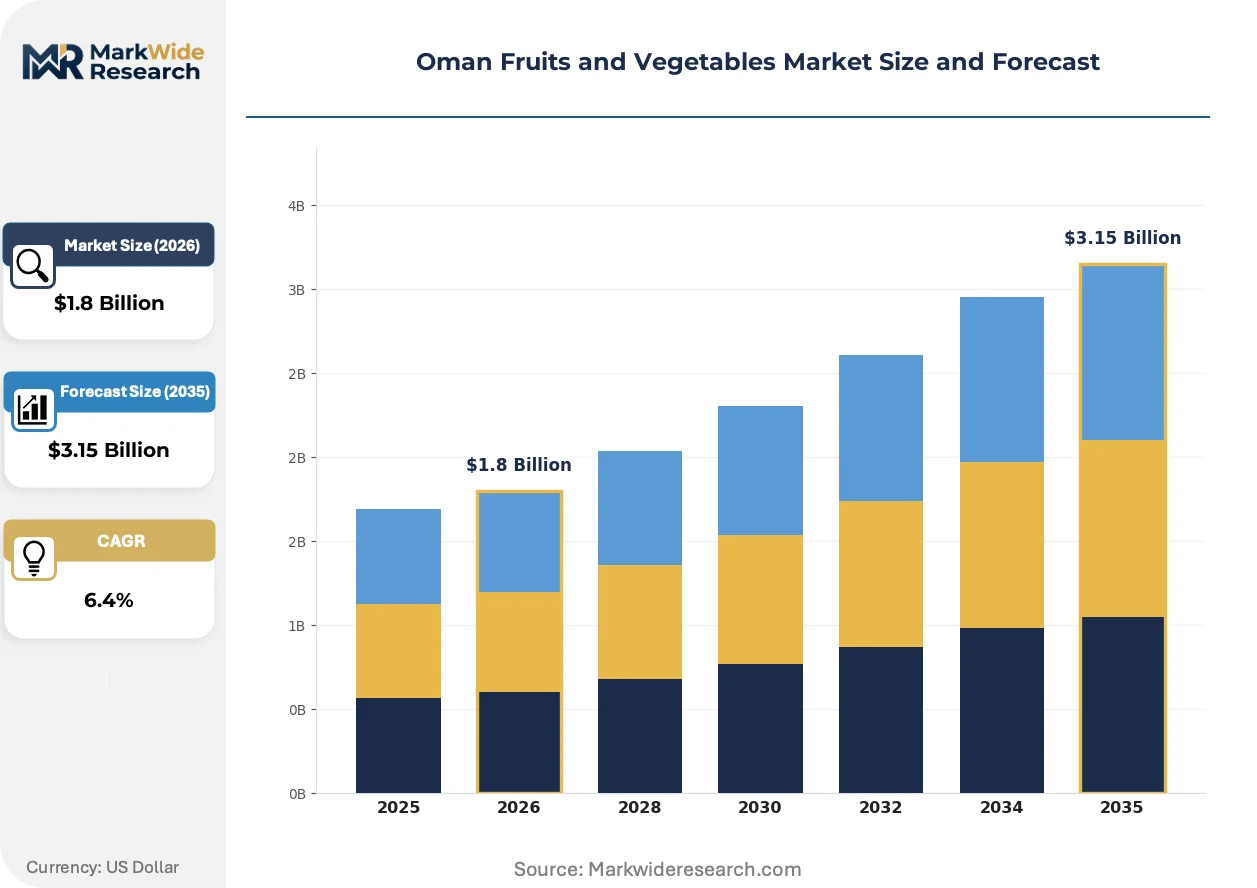
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus Fruits, Leafy Greens, Tubers, Berries Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Wholesalers End User: Households, Restaurants, Food Processing, Retailers Packaging Type: Plastic Bins, Cardboard Boxes, Clamshells, Bulk Packaging |
| Companies Covered | Suhail Bahwan Group, Gulf Mushroom Products Co., Oman Food Investment Holding Company, Kadam Trading Est Vegetable & Fruits, Oman Agro Industries, Al Jazeera Agricultural Co., Al Khonji Group, Al Fawaz International Trading, Al Maya Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Fruits and Vegetables Market Evolving Landscape
Technology adoption is compressing traditional growing cycles while regulatory pressure and buyer behavior shifts are forcing simultaneous adaptation across cultivation, distribution, and retail channels in Oman's produce sector.
Automated climate control systems using IoT sensors and AI-driven irrigation algorithms are fragmenting the dominance of experience-based farm management. Large-scale greenhouse operators in Al Buraymi and Al Dhahirah are deploying these platforms to optimize water use efficiency and predict harvest windows. The technology is fragmenting competitive advantage away from generational farming knowledge toward data-analytics capabilities, favoring capital-backed entrants over traditional family operations.
Ministry of Agriculture and Fisheries enforcement of traceability documentation under its food security framework is mandating blockchain-enabled supply chain tracking from farm gate to retail shelf. Processors and exporters must now maintain digitized records of pesticide applications, harvest dates, and cold-chain handoffs. Wholesale distributors serving hotel chains are absorbing the highest compliance burden, retrofitting legacy inventory systems to meet real-time verification requirements.
Direct sourcing contracts between hospitality groups and certified farms are displacing spot-market purchasing through central produce markets. Restaurant chains in Muscat's Al Khuwair and Qurum districts now specify varietal requirements, harvest maturity standards, and delivery frequencies in multi-year agreements. This pattern concentrates procurement volume among a shrinking pool of large-scale growers capable of meeting volume and consistency thresholds, marginalizing smallholder participation in premium segments.
Oman Fruits and Vegetables Market Segmentation
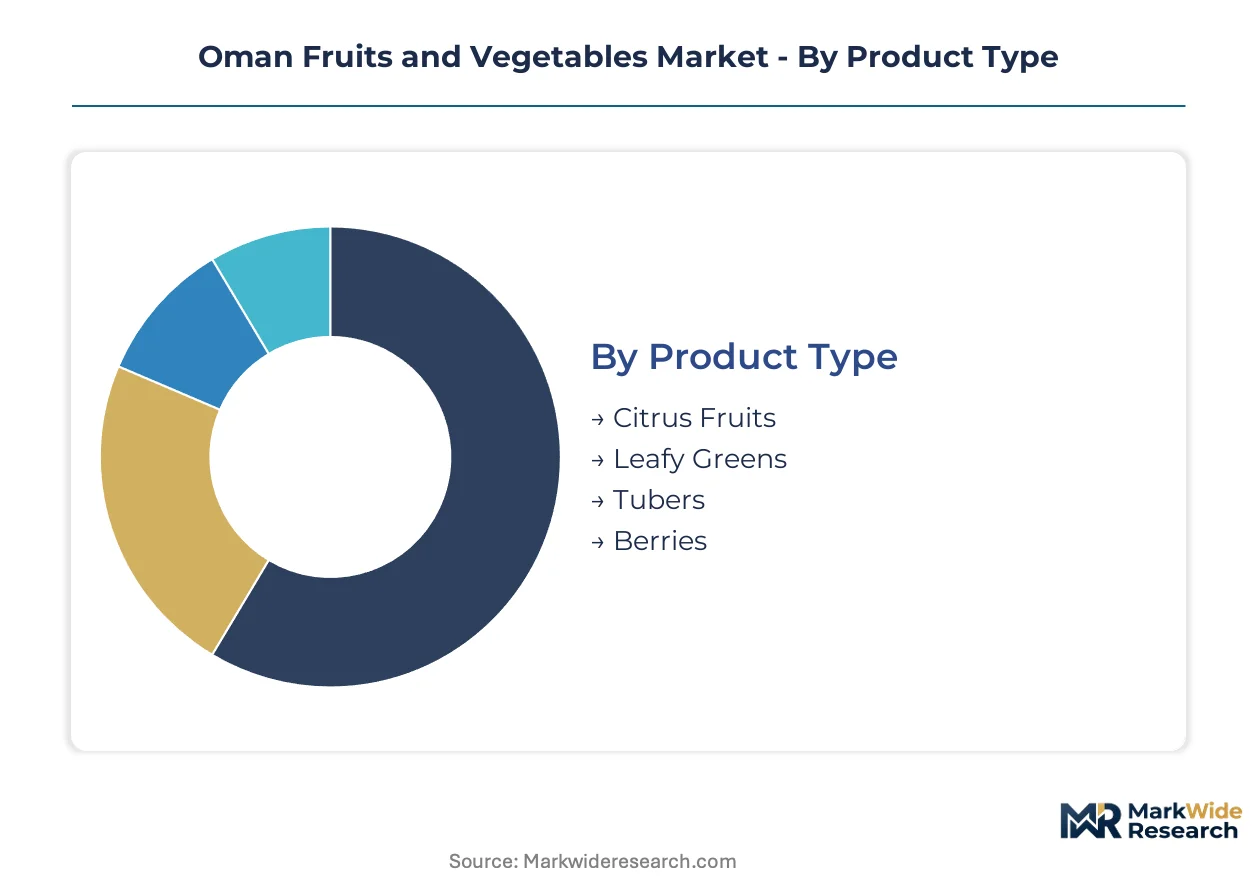
Segmentation in Oman's produce sector reveals how arid-climate cultivation constraints and hospitality-driven demand reshape category economics. Each dimension exposes different pressure points: water-intensive crops face regulatory ceilings, while cold-chain reliability determines channel viability across the Sultanate's dispersed population centers.
Product Type:
Domestic cultivation concentrates on heat-tolerant categories suited to greenhouse and drip-irrigation systems, while import dependency persists for temperate-climate items that cannot achieve commercial yields in Omani conditions.
- Citrus Fruits:Oranges, lemons, and limes dominate Batinah coastal plain acreage under Ministry of Agriculture and Fisheries subsidy programs. Muscat Governorate hotels source 60-70% of citrus requirements from certified domestic farms under direct procurement contracts.
- Leafy Greens:Spinach, lettuce, and herbs thrive in controlled-environment agriculture systems using hydroponic and aeroponic methods. Al Buraymi and Al Dhahirah greenhouse clusters supply year-round output to supermarket chains, bypassing seasonal import cycles.
- Tubers:Potatoes and sweet potatoes face groundwater extraction limits in interior governorates where desalination costs prohibit expansion.
- Berries:Strawberries and blueberries require intensive climate control, limiting cultivation to capital-backed operations near Muscat and Salalah.
Leafy Greens holds the largest share; momentum sits with Citrus Fruits as hospitality procurement consolidation deepens.
Distribution Channel:
Channel economics diverge sharply based on cold-chain investment requirements and buyer consolidation patterns, with digital platforms disrupting traditional wholesale markups.
- Supermarkets:Lulu Hypermarket and Carrefour anchor fresh produce retail in Muscat and Salalah, operating dedicated receiving facilities with temperature-controlled backrooms. These chains specify FSSAI-aligned safety protocols that filter supplier eligibility.
- Online Retail:Digital grocery platforms capture urban household demand through direct-to-consumer delivery models, reducing post-harvest handling stages and spoilage losses.
- Farmers' Markets:Weekend souks in Nizwa and Rustaq serve price-sensitive consumers with minimal packaging and same-harvest sales cycles.
- Wholesalers:Central produce markets in Al Azaiba and Salalah intermediate between smallholders and independent retailers, absorbing phytosanitary compliance burdens.
Supermarkets command volume leadership; Online Retail climbs fastest as smartphone penetration and delivery infrastructure mature.
End User:
End-use demand splits between traceability-sensitive hospitality buyers and price-driven household consumption, with food processing emerging as a volume sink for grade-B output.
- Restaurants:Five-star hotel chains and international franchises in Al Khuwair and Qurum districts specify varietal requirements, harvest maturity standards, and delivery frequencies in multi-year direct contracts with certified farms.
- Households:Urban families in Muscat and Seeb prioritize convenience and shelf-life reliability, shifting volume toward supermarket and digital channels.
- Food Processing:Juice manufacturers and frozen vegetable packers absorb sub-premium grades, providing revenue floor for growers facing hospitality rejection rates.
- Retailers:Independent grocery stores and corner shops rely on wholesaler intermediation, limiting traceability documentation capabilities.
Restaurants drive premium pricing; Food Processing expands most quickly as domestic processing capacity receives state-backed investment.
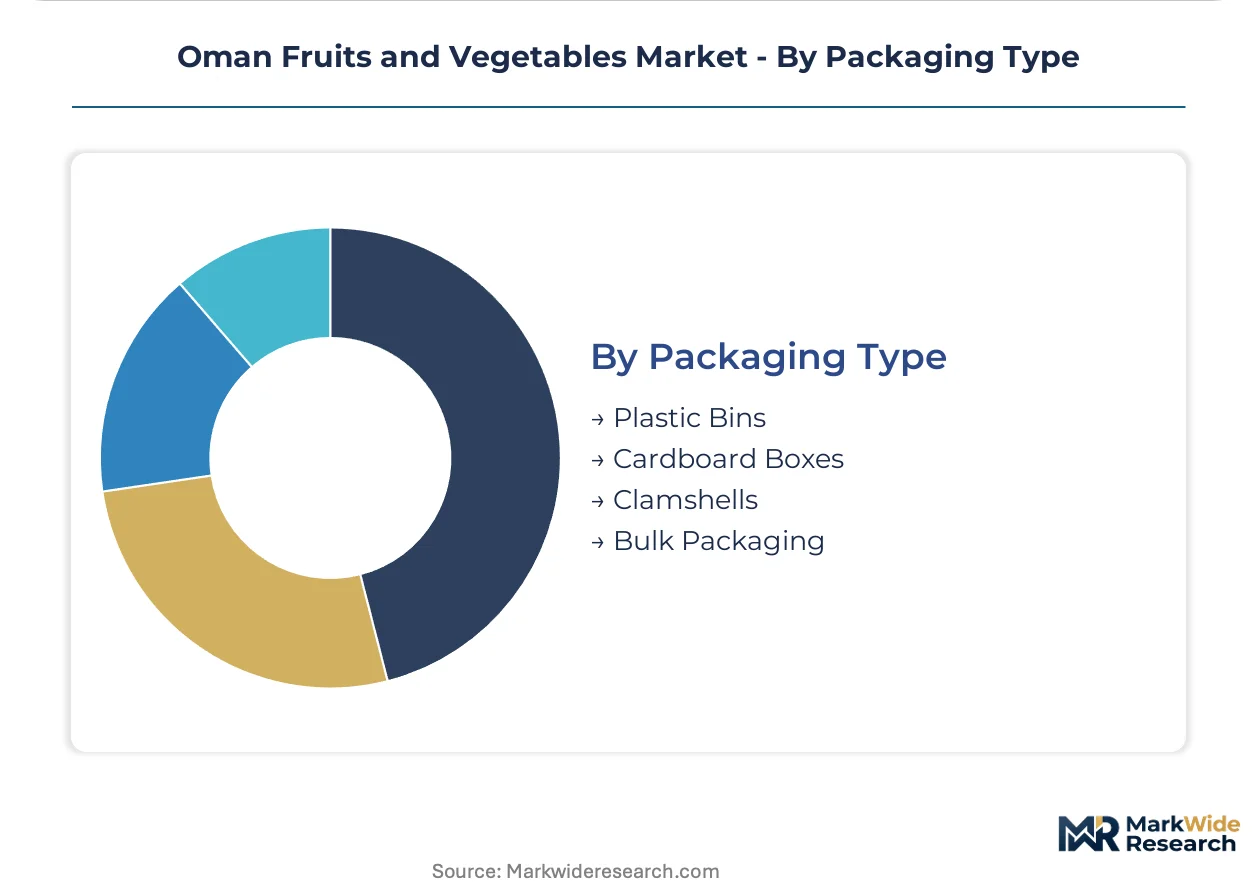
Packaging Type:
Packaging selection reflects trade-offs between shelf-life extension, cost minimization, and regulatory compliance across export and domestic destinations.
- Clamshells:Rigid plastic containers with ventilation apertures protect berries and cherry tomatoes through multi-handling distribution chains, meeting UAE retail chain specifications for cross-border shipments.
- Cardboard Boxes:Corrugated fiberboard with moisture-resistant coatings dominates citrus and leafy green shipments, balancing structural protection with recyclability mandates from Ministry of Environment and Climate Affairs.
- Plastic Bins:Reusable totes circulate between large-scale growers and supermarket distribution centers, reducing per-shipment packaging costs for high-volume contracts.
- Bulk Packaging:Open crates and mesh bags serve wholesale and processing channels where immediate consumption or repackaging eliminates retail presentation requirements.
Cardboard Boxes holds the largest share; Clamshells gain share fastest as berry cultivation expands and export certification demands rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotel chains and restaurant groups in Muscat Governorate and the Batinah coastal plain anchor procurement volume, while hospitality-driven demand is reshaping cultivation patterns across Oman's interior governorates.
Muscat Governorate
Five-star hotel properties and international restaurant franchises in Al Khuwair and Qurum districts specify harvest maturity standards and delivery frequencies in multi-year contracts. Ministry of Agriculture and Fisheries traceability documentation mandates digitized records of pesticide applications and cold-chain handoffs. Greenhouse clusters near Seeb supply year-round leafy greens to hospitality buyers bypassing traditional wholesale channels.
Al Batinah North Governorate
Citrus cultivation dominates acreage under subsidized drip-irrigation programs targeting import substitution. Ministry of Agriculture and Fisheries preferential water allocations expand domestic cultivation capacity for oranges and lemons. Sohar port logistics infrastructure supports distribution to Muscat hospitality corridors within 24-hour harvest windows.
Al Batinah South Governorate
Tomato and cucumber greenhouse operations serve supermarket chains with FSSAI-aligned safety protocols. Ministry of Regional Municipalities and Water Resources extraction limits constrain open-field expansion, favoring controlled-environment systems. Rustaq agricultural zone hosts weekend farmers' markets connecting smallholders directly to price-conscious households.
Dhofar Governorate
Salalah's monsoon microclimate enables off-season tropical fruit cultivation and vegetable production counter-cyclical to northern governorates. Ministry of Agriculture and Fisheries food security initiatives identify underutilized agricultural land for state-backed development. Port infrastructure connects Salalah clusters to UAE retail chains seeking GCC-standard certified produce.
Al Buraymi Governorate
Large-scale greenhouse operators deploy IoT sensors and AI-driven irrigation algorithms to optimize water use efficiency in salinity-compromised soils. Ministry of Environment and Climate Affairs recyclability mandates shape packaging specifications for corrugated fiberboard shipments. Border proximity to UAE markets positions Al Buraymi clusters for cross-border retail certification alignment.
Oman Fruits and Vegetables Market Competitive Landscape
Player mix skews toward diversified conglomerates with agribusiness portfolios and state-backed investment vehicles. Consolidation pressure concentrates procurement volume among large-scale growers capable of meeting hospitality traceability thresholds. Strategic archetypes include vertically integrated holding companies, controlled-environment specialists, and trading houses with wholesale distribution networks. Competitive moves center on direct farm partnerships with hotel chains and greenhouse capacity expansion in water-privileged zones.
Within the diversified conglomerate tier, Suhail Bahwan Group and Al Khonji Group occupy positions spanning multiple sectors with agribusiness arms securing consistent supply lines. Gulf Mushroom Products Co. exemplifies the controlled-environment specialist archetype through its focus on reducing import dependency for specialty produce. Oman Food Investment Holding Company anchors state-backed food security mandates through strategic domestic farming assets, representing the sovereign investment vehicle pattern in agricultural development.
| Leading Market Players |
|---|
| Suhail Bahwan Group |
| Gulf Mushroom Products Co. |
| Oman Food Investment Holding Company |
| Kadam Trading Est Vegetable & Fruits |
| Oman Agro Industries |
| Al Jazeera Agricultural Co. |
| Al Khonji Group |
| Al Fawaz International Trading |
| Al Maya Group |
| Others |
Value Network & Pricing Analysis
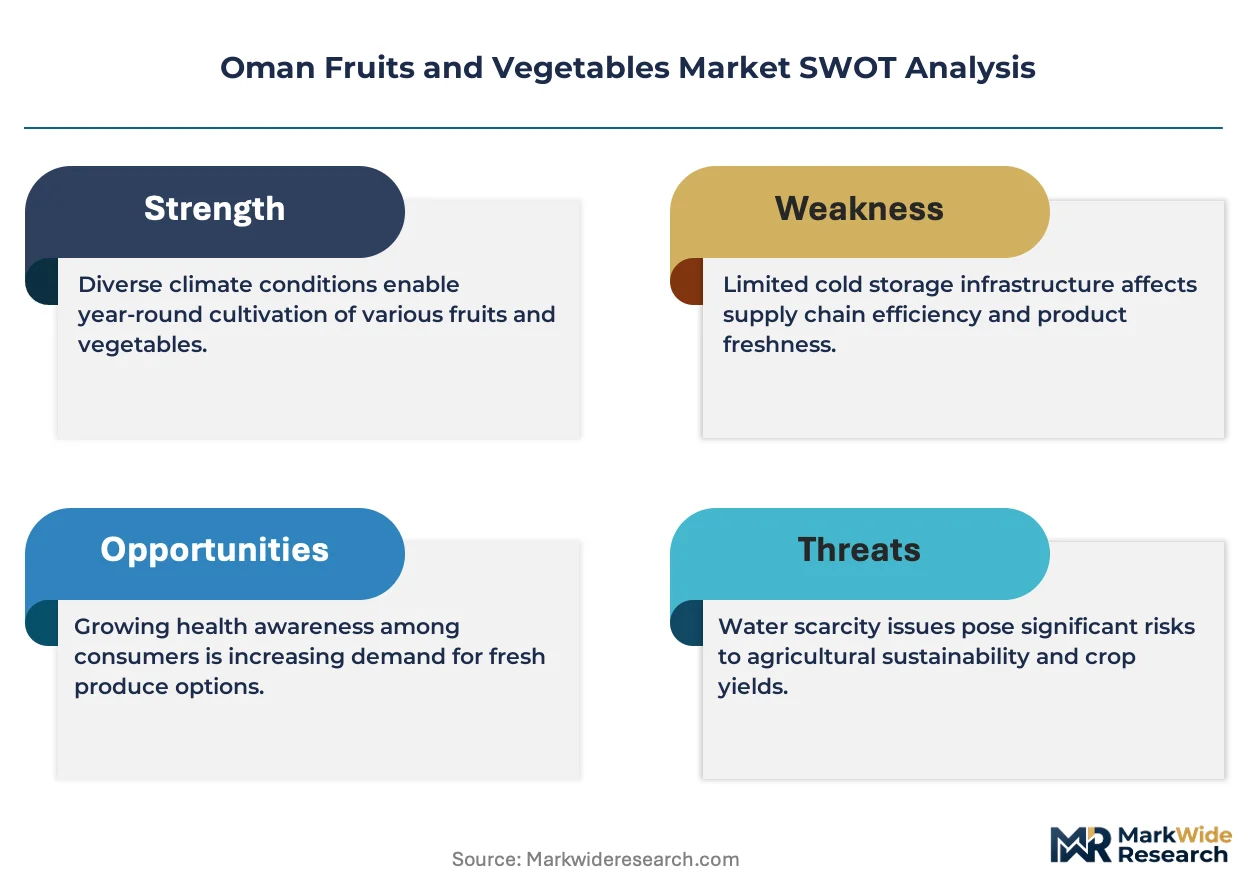
Ministry of Agriculture and Fisheries phytosanitary certification gates both farm-level supply qualification and price realization across hospitality and retail channels simultaneously, creating tiered access where traceability documentation separates premium contract tiers from spot-market alternatives.
Pricing Analysis
Prior-generation open-field cultivation commands economy pricing through wholesale channels, while current-generation controlled-environment greenhouse systems capture standard-tier premiums through supermarket contracts. Next-generation AI-optimized climate control and blockchain traceability platforms enable hospitality-facing premium tiers. Pricing stratifies across premium, standard, and economy tiers based on certification grade and cold-chain reliability. Cost compression in economy tiers intensifies as groundwater extraction limits raise irrigation expenses. Independent retailers and price-conscious households exhibit highest price sensitivity; five-star hotel chains demonstrate lowest sensitivity due to traceability mandates.
Supply Chain Analysis
Just-in-time delivery preferences dominate hospitality procurement, forcing 24-hour harvest-to-delivery windows that conflict with Ministry of Agriculture and Fisheries inspection timelines. Geographic supply concentrates in Oman, UAE, and Iran for temperate fruit imports. Raw material dependencies rest on desalinated water, greenhouse infrastructure, and specialized growing substrates. Single-source vulnerability runs through Batinah coastal plain concentration for domestic citrus and leafy greens. Distribution feeds from farm-gate through cold-chain intermediaries to hospitality clusters in Muscat and Salalah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from imported produce achieving FSSAI-equivalent certification at lower landed costs, requiring defensive repositioning around traceability and local provenance.
For Market Incumbents: Shield market position by deepening backward integration into desalination and renewable-powered greenhouse infrastructure, securing water allocation privileges before Ministry of Regional Municipalities and Water Resources tightens extraction ceilings. Invest in blockchain-enabled traceability platforms to maintain hospitality contract access against UAE and Saudi import competitors.
For New Entrants and Emerging Players: Anchor in Dhofar Governorate's underutilized agricultural land and monsoon microclimate, where tropical fruit cultivation faces minimal incumbent competition. Target Salalah-based off-season vegetable production for UAE retail chains seeking GCC-standard certified alternatives. Pursue direct e-commerce grocery partnerships to bypass wholesale markup structures.
For Investors and Strategic Acquirers: Ministry of Agriculture and Fisheries food security mandate expansion reshapes the acquisition landscape, privileging assets with preferential water allocations and existing hospitality certifications. Five-to-ten-year viability favors controlled-environment specialists with scalable greenhouse platforms over open-field operators facing regulatory constraints. Watch groundwater allocation policy revisions as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Capacity Expansion | Ministry of Agriculture and Fisheries subsidies reduce capital intensity for hydroponic greenhouse development in Al Batinah governorates. |
| Direct Hospitality Supply Contracts | Multi-year agreements with Suhail Bahwan Group properties lock in volume commitments bypassing wholesale intermediaries. |
| Blockchain Traceability Implementation | Digitized pesticide and cold-chain records satisfy FSSAI-aligned protocols for UAE retail export eligibility. |
| Dhofar Agricultural Land Development | Salalah monsoon microclimate enables counter-seasonal production capturing premium windows when northern governorates face heat stress. |
| E-commerce Platform Partnership | Direct-to-consumer channels in Muscat and Seeb reduce post-harvest losses and capture margin otherwise absorbed by supermarket markups. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with greenhouse operators, hospitality procurement directors, Ministry of Agriculture and Fisheries officials, and cold-chain logistics providers; and secondary validation through customs trade records, Ministry of Regional Municipalities and Water Resources extraction data, and hospitality sector supply chain disclosures. Bottom-up cultivation acreage estimates triangulated against top-down consumption surveys across Muscat, Salalah, and Batinah population centers.
Across the analysis window, the forecast framework modeled segmentation dimensions including product type, distribution channel, end-user category, and regional production cluster. CAGRs were derived from trend extrapolation of cultivation expansion rates, import substitution progress, and hospitality procurement consolidation patterns. Specific inputs incorporated desalination cost trajectories, greenhouse technology adoption curves, and e-commerce penetration rates among urban households.
Decision-makers should treat outputs as directional under assumptions of continued Ministry of Agriculture and Fisheries subsidy stability and no abrupt groundwater allocation restrictions; material deviation would warrant model refresh. Revision becomes warranted when desalination cost spikes or import tariff shifts cross thresholds altering domestic cultivation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Asia-Pacific Shiitake Mushroom Market
Fruits and Vegetables
North America Canned Fruits Market
Fruits and Vegetables
Turkish Figs Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Dried Berries Market