
 Cyanidin Market | 2026-2036
Cyanidin Market Size, Share, and Industry Trends Forecast 2026-2036
Cyanidin Market Analytics
Cosmetic companies are redrawing procurement priorities for anthocyanin-derived colorants, pulling volume from traditional food dye channels. Synthite Industries Ltd leverages integrated spice extraction infrastructure to supply cosmetic-grade cyanidin at scale. Sensient Technologies Corporation anchors North American distribution through specialized colorant divisions. Chr. Hansen Holding A/S differentiates via fermentation-based pigment platforms that compete with botanical extraction.
Cyanidin is a water-soluble anthocyanin pigment with a flavylium cation core, typically extracted from berries, grapes, and purple corn via solvent or supercritical CO2 methods, functioning primarily as a natural colorant and antioxidant in consumer products. Powder formulations dominate commercial volume due to stability and handling advantages, though liquid extracts capture premium positioning in beverage applications. Dietary supplements represent the fastest-expanding application channel as antioxidant claims gain clinical traction. Direct sales channels concentrate margin pools by bypassing distributor markups for large nutraceutical contracts.
REACH in Europe and FDA color additive regulations in the United States both constrain solvent residues and purity thresholds, compelling extraction technology upgrades. EFSA novel food assessments further gate European market entry for new cyanidin sources. Stakeholders must monitor evolving purity standards and extraction method certifications to secure downstream contracts.
Market Dynamics
Supercritical CO2 extraction technology is redrawing competitive boundaries in cyanidin supply chains, compressing margins for solvent-dependent processors while rewarding capital-intensive operators with REACH-compliant output streams.
Growth Catalysts
- EFSA novel food assessments:Regulatory clarity around purple corn and berry-derived cyanidin sources accelerates new product introductions across European nutraceutical channels.
- Cosmetic-grade pigment demand:Clean-label colorant procurement from L'Oréal and Estée Lauder subsidiaries pulls volume into personal care applications at premium purity tiers.
- Hamburg-Frankfurt R&D corridor:German functional ingredient clusters concentrate formulation expertise, creating localized demand density for high-specification cyanidin extracts.
Market Restraints
- Raw material seasonality:Bilberry and elderberry harvest volatility in Nordic and Eastern European growing regions destabilizes input cost structures for batch processors.
- REACH solvent residue thresholds:ECHA-mandated extraction purity standards force capital retooling for ethanol-dependent facilities, freezing out smaller botanical extractors.
- Synthetic anthocyanin competition:Fermentation-derived pigments from Chr. Hansen's platform threaten price positioning in mass-market food colorant segments.
Strategic Opportunities
- Brazilian Amazon berry sources:Underexploited açaí and jabuticaba feedstocks offer novel cyanidin profiles for differentiated antioxidant positioning in North American supplements.
- Direct-to-nutraceutical contracts:Bypassing distributor markups through large-volume supply agreements captures margin pools currently held by specialty chemical intermediaries.
- Supercritical CO2 equipment leasing:Technology-as-a-service models lower barrier to entry for mid-scale processors seeking compliance without full capital commitment.
Industry Challenges
- Analytical chemist scarcity:Qualified personnel for anthocyanin quantification and stability testing command premium wages, constraining quality control scaling.
- ISO 17025 accreditation timelines:Laboratory certification delays for purity verification extend contract qualification periods by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyanidin Market |
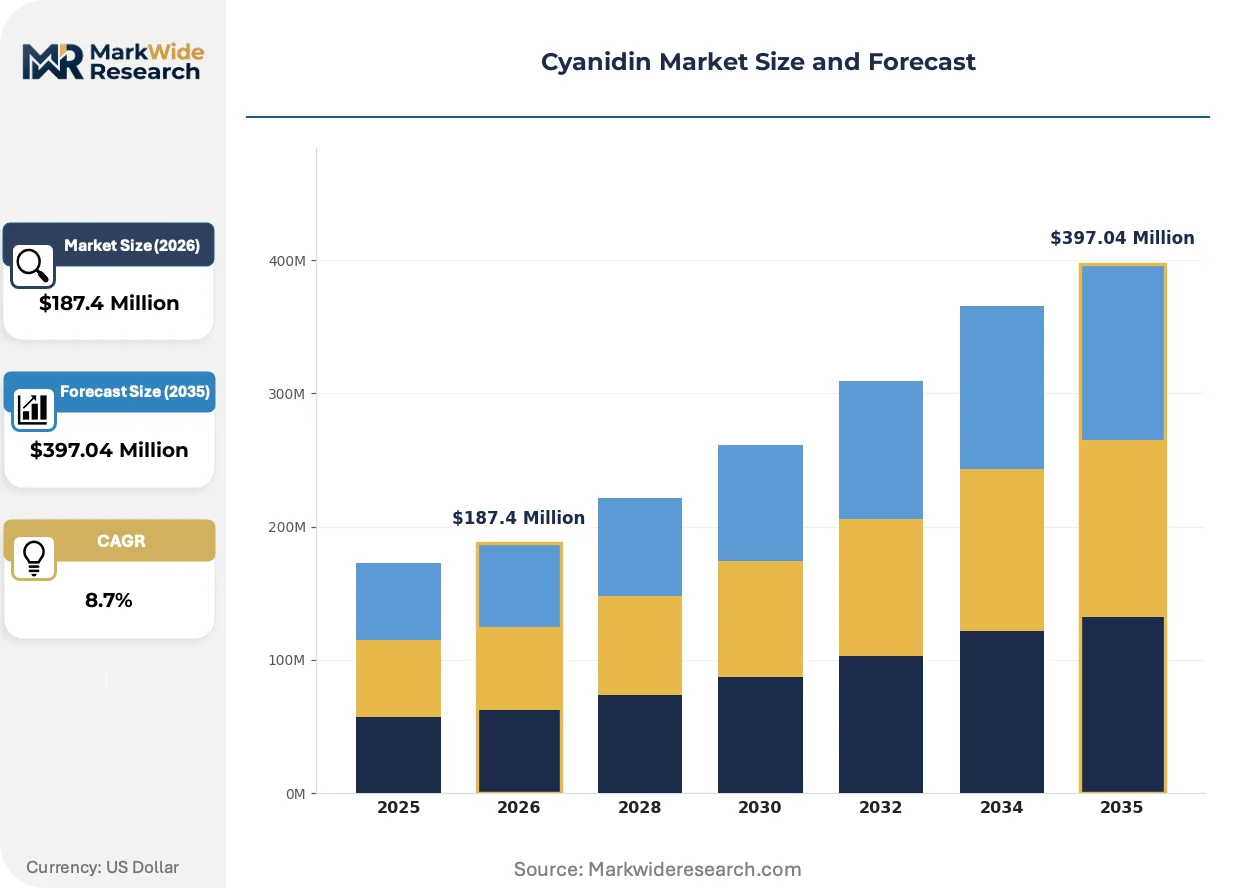
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Extract, Granules Application: Food & Beverages, Pharmaceuticals, Cosmetics, Dietary Supplements End User: Food Manufacturers, Cosmetic Companies, Nutraceutical Firms, Research Institutions Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Synthite Industries Ltd, Sensient Technologies Corporation, Symrise AG, Chr. Hansen Holding A/S, Naturex S.A., Archer Daniels Midland Company, GNT Group, Kalsec Inc., D.D. Williamson & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyanidin Market Evolving Landscape
Extraction methodology and procurement architecture are undergoing parallel transformation, with technology choices increasingly determining market access rather than merely operational efficiency.
Supercritical CO2 extraction is bifurcating the supplier base into capital-intensive certified operators and stranded solvent-dependent competitors. Nutraceutical contract manufacturers in Germany and Switzerland are migrating capacity fastest, locking in multi-year supply agreements that exclude ethanol-extracted alternatives. This technology divide is compressing available supplier pools for REACH-compliant cosmetic applications.
REACH solvent residue standards tightened through ECHA's 2023-2024 guidance updates, eliminating grandfathered ethanol extraction pathways for skin-contact applications. Cosmetic formulators in France and Italy now mandate CO2-derived certificates of analysis, forcing mid-tier Spanish and Portuguese extractors into equipment overhaul or market exit. The regulatory drag concentrates volume with pre-compliant German and Dutch processors.
Ingredient buyers are consolidating supplier rosters from fragmented spot-market sourcing toward audited partnership programs with traceability documentation. Large supplement brands in California and New York now require batch-level berry provenance and extraction method disclosure, displacing commodity brokers. This procurement consolidation is most visible in direct sales channels where contract manufacturers negotiate exclusive cyanidin supply arrangements.
Cyanidin Market Segmentation
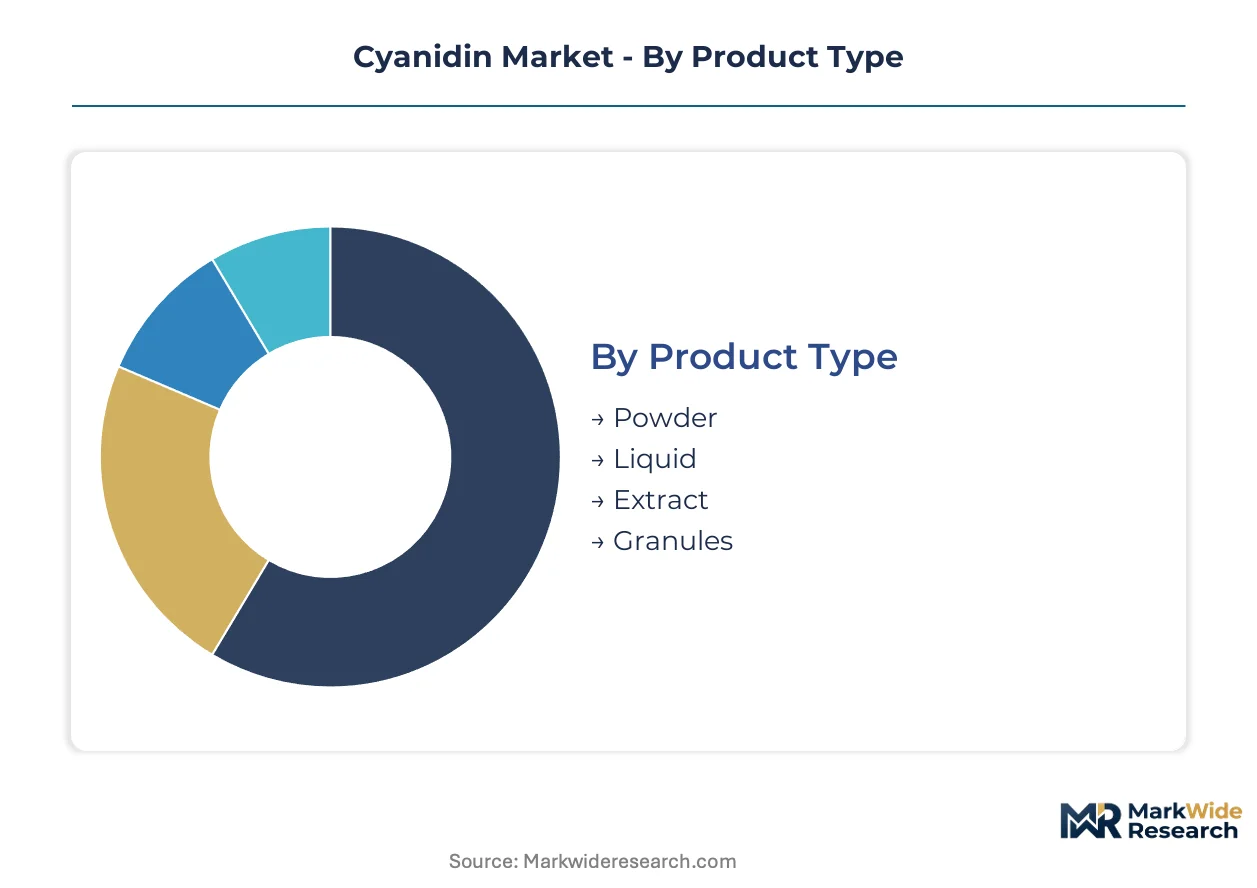
Cyanidin procurement patterns diverge sharply across product formats and end-use specifications, with regulatory compliance thresholds and handling requirements determining margin capture. Application-driven segmentation reveals how antioxidant claims and colorant purity grades redirect volume between commodity and specialty channels.
Product Type:
Premium margins concentrate in stabilized formats that reduce degradation losses during formulation, while bulk powder trades on throughput efficiency.
- Powder:Spray-dried or freeze-dried formulations dominate commercial volume due to extended shelf stability and simplified logistics. German nutraceutical contract manufacturers specify powder grades for tablet compression and capsule filling operations, with REACH-compliant CO2-extracted variants commanding price premiums over solvent-processed alternatives.
- Liquid:Aqueous or glycerin-based solutions serve beverage fortification and cosmetic serum applications where dispersibility requirements override stability concerns. California functional drink brands source liquid cyanidin for ready-to-drink antioxidant positioning, though cold-chain requirements constrain distribution radius.
- Extract:Standardized anthocyanin concentrates target pharmaceutical and high-specification cosmetic use. Swissmedic-registered suppliers in Basel and Zurich control quality documentation for clinical trial material.
- Granules:Agglomerated particles improve flow properties for automated manufacturing lines. Italian food processors specify granule grades for instant drink mixes and fortified confectionery.
Powder holds installed capacity across European extraction facilities. Liquid is rotating up the share rankings in North American beverage applications.
Application:
Volume flows follow end-use purity tiers, with pharmaceutical and cosmetic specifications filtering out commodity-grade suppliers.
- Food & Beverages:Natural colorant replacement for synthetic dyes drives bakery, confectionery, and beverage adoption. EFSA-approved sources from purple corn and elderberry concentrate in German and French formulation houses.
- Pharmaceuticals:API-grade cyanidin for cardiovascular and ophthalmic research programs requires GMP-certified extraction and batch documentation. Swiss and German CMOs dominate qualified supply.
- Cosmetics:Clean-label pigment demand from L'Oréal and Estée Lauder subsidiaries pulls volume into skin-care and color cosmetic formulations. REACH skin-contact standards mandate CO2-derived certificates.
- Dietary Supplements:Antioxidant capsules and tablets represent the steepest expansion trajectory as clinical validation of berry polyphenols accelerates. Direct-to-brand contracts bypass distributor markups.
Dietary supplements concentrate new capacity investment. Cosmetics is climbing the fastest in per-kilogram value realization.
End User:
Procurement sophistication varies by buyer technical capability, with research institutions and multinational nutraceutical firms driving specification intensity.
- Food Manufacturers:Large-scale bakery and beverage processors prioritize cost stability and color consistency over extraction method provenance. Seasonal contracting hedges against berry harvest volatility.
- Cosmetic Companies:L'Oréal, Estée Lauder, and Unilever subsidiaries mandate traceability documentation and REACH-compliant extraction certificates, consolidating supplier rosters to audited partners.
- Nutraceutical Firms:Thorne, Life Extension, and German pharmacy brands (Doppelherz, Orthomol) specify high-purity grades for antioxidant positioning. Direct sales channels capture margin pools.
- Research Institutions:Academic and clinical trial programs require analytical-grade material with full characterization data. Max Planck Institute and ETH Zurich groups source through specialized chemical distributors.
Nutraceutical firms hold long-term offtake agreements. Cosmetic companies are rotating up the share rankings in premium-grade procurement.
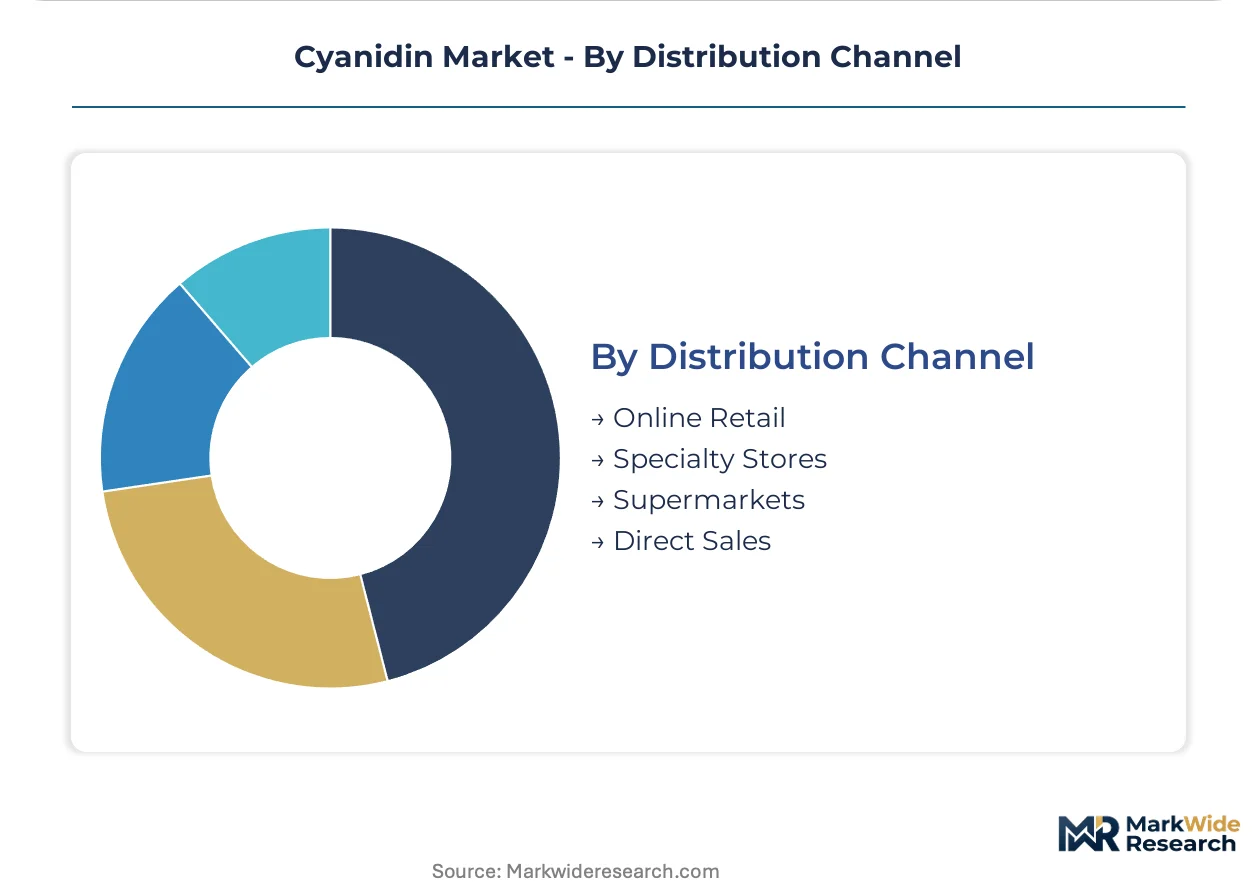
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with large volume buyers bypassing intermediaries.
- Online Retail:E-commerce platforms serve small-scale supplement brands and research laboratories with standardized catalog grades. Amazon Business and specialty chemical marketplaces aggregate spot demand.
- Specialty Stores:Regional distributors with technical sales support target mid-tier food and cosmetic manufacturers requiring formulation guidance.
- Supermarkets:Mass-market retail channels move consumer-facing supplement products rather than industrial ingredients. Limited relevance for B2B cyanidin volume.
- Direct Sales:Large nutraceutical and cosmetic manufacturers negotiate exclusive supply agreements with extraction facilities, capturing 15-25 point margin improvements over distributor-mediated procurement.
Direct sales holds installed capacity for qualified large buyers. Online retail is rotating up the share rankings in small-order research and startup segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container terminals anchor European cyanidin import flows, handling concentrated berry extract shipments from Nordic and Baltic suppliers before distribution to processing clusters along the Rhine corridor.
Germany
EFSA novel food assessments accelerate purple corn and elderberry-derived cyanidin approvals for nutraceutical applications. REACH solvent residue thresholds enforced by ECHA mandate supercritical CO2 extraction certificates for skin-contact cosmetic uses. The Hamburg-Frankfurt R&D corridor concentrates formulation expertise, with contract manufacturers in Hesse locking in multi-year supply agreements that exclude ethanol-extracted alternatives.
United States
FDA color additive regulations constrain solvent residues and purity thresholds for berry-derived pigments entering food and supplement channels. California functional beverage brands drive liquid cyanidin procurement for ready-to-drink antioxidant positioning, though cold-chain requirements limit distribution radius. Direct-to-brand contracts from Thorne and Life Extension capture margin pools previously held by specialty chemical intermediaries.
Switzerland
Swissmedic registration requirements control quality documentation for API-grade cyanidin destined for cardiovascular and ophthalmic research programs. Basel and Zurich extraction facilities dominate qualified pharmaceutical supply, with GMP-certified batch documentation mandatory for clinical trial material. The country's functional ingredient clusters specialize in high-specification cosmetic and pharmaceutical grades rather than commodity food colorants.
France
ANSM oversight of cosmetic ingredient safety reinforces REACH skin-contact standards for anthocyanin-derived colorants. L'Oréal and Estée Lauder subsidiaries mandate traceability documentation and CO2-derived certificates of analysis, consolidating supplier rosters to audited partners. Cosmetic formulators in the Île-de-France region now exclude ethanol-extracted alternatives from procurement specifications.
Brazil
ANVISA novel food pathways for Amazonian berry sources remain underdeveloped, delaying açaí and jabuticaba cyanidin commercialization for North American supplement markets. The country's northern growing regions offer underexploited feedstocks with differentiated antioxidant profiles. São Paulo-based processors face capital constraints for supercritical CO2 equipment upgrades needed to meet European import standards.
Cyanidin Market Competitive Landscape
Concentration sits with integrated botanical extractors and fermentation-based pigment platforms rather than fragmented spot-market brokers. The supplier base bifurcates between capital-intensive certified operators with REACH-compliant CO2 extraction capacity and stranded solvent-dependent competitors facing equipment overhaul or exit. Strategic archetypes include integrated spice extraction conglomerates, specialized colorant divisions of multinational ingredient houses, and fermentation-based pigment specialists. Dominant competitive moves encompass technology licensing partnerships for supercritical equipment access and backward integration into captive berry cultivation to hedge raw material seasonality.
Within the integrated extraction tier, Synthite Industries Ltd and Sensient Technologies Corporation exemplify contrasting geographic anchoring strategies. The Indian limited company leverages subcontinental spice infrastructure for cosmetic-grade supply at scale, while the American corporation anchors North American distribution through specialized colorant divisions. Chr. Hansen Holding A/S occupies a distinct position as a Danish fermentation-based platform operator competing with botanical extraction through proprietary pigment technologies.
| Leading Market Players |
|---|
| Synthite Industries Ltd |
| Sensient Technologies Corporation |
| Symrise AG |
| Chr. Hansen Holding A/S |
| Naturex S.A. |
| Archer Daniels Midland Company |
| GNT Group |
| Kalsec Inc. |
| D.D. Williamson & Co., Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with German nutraceutical contract manufacturers lock in multi-year supply access while anchoring price visibility against raw material seasonality in Nordic and Baltic growing regions. These structures insulate large buyers from elderberry and bilberry harvest volatility that destabilizes spot-market pricing for mid-tier processors.
Pricing Analysis
Volume-discount tiering separates REACH-certified CO2-extracted grades from solvent-processed alternatives, with cosmetic formulators paying premiums for skin-contact purity documentation. Price differentiation hinges on extraction method certification and batch-level provenance traceability demanded by L'Oréal and Estée Lauder subsidiaries. Cost compression in ethanol-dependent processing tiers is intensifying because ECHA-mandated equipment retooling freezes out smaller botanical extractors. Food manufacturers exhibit highest price sensitivity due to color consistency requirements overriding extraction method provenance, while pharmaceutical buyers prioritize GMP documentation over unit economics.
Supply Chain Analysis
Strategic stockpiling of freeze-dried berry concentrates dominates German and Swiss processor preferences, hedging against Nordic harvest volatility that just-in-time procurement cannot absorb. Supply concentrates in Germany, India, and Switzerland, with Hamburg's port terminals anchoring European import flows before Rhine corridor distribution. Raw material dependencies center on elderberry, bilberry, and purple corn feedstocks. Single-source vulnerability runs through Baltic berry cultivation zones exposed to climate variability. Distribution runs through direct sales channels for qualified large buyers, with specialty chemical intermediaries serving fragmented spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supercritical CO2 extraction technology is disrupting competitive boundaries, with REACH compliance mandates creating a regulatory inflection that rewards capital-intensive operators while stranding solvent-dependent competitors.
For Market Incumbents: Compound defensive positioning through backward integration into captive berry cultivation in Nordic growing regions, hedging raw material seasonality that destabilizes batch processors. Lock in multi-year direct sales contracts with Thorne and Life Extension that exclude ethanol-extracted alternatives from qualified supplier rosters, while accelerating ISO 17025 laboratory accreditation to compress contract qualification timelines. For New Entrants and Emerging Players: Anchor in Brazilian Amazon berry sources, exploiting underexploited açaí and jabuticaba feedstocks before ANVISA novel food pathways mature. Target North American supplement brands seeking differentiated antioxidant positioning with novel cyanidin profiles unavailable from European suppliers. Pursue supercritical CO2 equipment leasing models as a technology-as-a-service entry strategy that lowers capital barriers. For Investors and Strategic Acquirers: German and Dutch extraction facilities with pre-compliant CO2 capacity represent the most defensible acquisition archetype, given regulatory drag concentrating volume with REACH-certified operators. Long-term viability frames around 5-10 year windows where solvent-dependent processors face equipment overhaul or exit. Watch EFSA novel food assessment timelines as the critical inflection signal for new source commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | ECHA-mandated extraction upgrades lock in REACH-compliant output streams for cosmetic applications. |
| Backward Integration into Berry Cultivation | Captive Nordic and Baltic feedstock supply hedges harvest volatility destabilizing input costs. |
| Direct-to-Nutraceutical Supply Agreements | Bypassing distributor markups captures 15-25 point margin improvements for large contract manufacturers. |
| ISO 17025 Laboratory Accreditation | Certification delays currently extend contract qualification periods by 8-14 months for new suppliers. |
| Amazonian Berry Source Development | ANVISA pathway navigation unlocks differentiated antioxidant profiles for North American supplement positioning. |
Research Methodology
Initial hypotheses were tested against primary input from extraction facility plant managers, nutraceutical procurement leads, cosmetic formulation directors, and regulatory affairs specialists at ECHA-notified bodies, then refined through secondary validation. Trade data from Eurostat and UN Comtrade, EFSA novel food assessment registers, SEC filings from listed ingredient houses, and Swissmedic GMP certification databases anchored quantitative baselines. Bottom-up capacity surveys across German and Swiss processing clusters triangulated against top-down demand estimates from dietary supplement shipment records.
Variance decomposition across product format, application purity tier, extraction method, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by price realization differentials between powder, liquid, and extract grades. Forecast inputs incorporated supercritical CO2 equipment installation pipelines and EFSA assessment queue timelines.
Material uncertainties — regulatory guidance updates, berry harvest yield deviations, and analytical chemist labor market tightness — sit outside the modeled envelope. Forecasts reflect assumptions around REACH solvent residue threshold stability and novel food approval velocity. Revision becomes warranted when EFSA assessment backlogs exceed historical clearance rates or when Nordic climate patterns trigger consecutive harvest shortfalls.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Global Garcinia Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Basil Leaves Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Fruit and Vegetable Pulp Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Dried Grapes Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Spring Market
Fruits and Vegetables
North Africa Fruits and Vegetables Processing Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Goji Berries Market