
 United States E-Bike Market | 2026-2036
United States E-Bike Market Size, Share, and Industry Trends Forecast 2026-2036
United States E-Bike Market Intelligence
Domestic assembly capacity across the American Southwest is hardening as brands respond to tariff exposure on Chinese frames and battery packs. Rad Power Bikes leverages its Seattle-based design headquarters and direct-to-consumer channel to control pricing across the mass-market tier. Trek Bicycle Corporation anchors its position through a dealer network spanning over twelve hundred US retail locations, while Specialized differentiates via in-house motor development and premium carbon frame integration.
United States e-bikes are electrically assisted bicycles incorporating hub-mounted or mid-drive motors, rechargeable lithium-ion battery packs typically ranging from four hundred to over seven hundred fifty watt-hours, and pedal-assist or throttle-based propulsion systems designed to augment human power for urban commuting, cargo hauling, and recreational trail riding. City e-bikes and cargo e-bikes lead volume shipments as last-mile delivery fleets and suburban households prioritize utility over sport performance, while folding e-bikes represent the fastest-growing product category among apartment dwellers in dense metropolitan corridors where storage constraints dominate purchase decisions.
The Consumer Product Safety Commission enforces federal mechanical and electrical safety standards for low-speed electric bicycles, while the National Highway Traffic Safety Administration maintains jurisdiction over road-operated variants exceeding twenty miles per hour, and state departments of transportation layer additional classification rules that determine where riders may legally operate. These overlapping frameworks create a compliance mosaic that manufacturers must navigate to avoid market access barriers. Stakeholders should monitor pending federal tariff reviews and state-level rebate program exhaustion timelines as decisive variables shaping near-term competitive positioning.
Market Dynamics
Federal tariff exposure on Chinese battery cells and frame assemblies is forcing domestic brands to reconfigure supply chains around Mexican and Vietnamese contract manufacturing, compressing margin structures while accelerating nearshoring investments across the American Southwest.
Growth Catalysts
- Inflation Reduction Act clean vehicle credits:Federal tax incentives reduce effective purchase prices for qualifying e-bikes, stimulating demand among price-sensitive urban commuters in dense metropolitan corridors.
- Last-mile delivery fleet electrification:Logistics operators are replacing gasoline-powered vans with cargo e-bikes to navigate congestion zones and avoid parking penalties in city centers.
- Lithium iron phosphate chemistry:Safer, longer-cycle battery formulations are displacing legacy lithium-ion packs in premium and utility segments, extending vehicle lifespan and reducing thermal risk.
Market Restraints
- Section 301 tariff exposure:Remaining duties on Chinese-manufactured frames and motor controllers elevate landed costs for mass-market brands lacking alternative sourcing.
- Raw material concentration:Refined lithium and rare earth magnet supply chains concentrate in Chinese processing facilities, creating input price volatility exposure.
- Speed classification fragmentation:NHTSA jurisdiction over vehicles exceeding twenty miles per hour conflicts with CPSC low-speed electric bicycle definitions, creating compliance ambiguity for manufacturers.
Strategic Opportunities
- Suburban secondary markets:Sun Belt metropolitan expansion zones in Texas, Florida, and Arizona exhibit low e-bike penetration relative to coastal urban cores, presenting whitespace for dealer network expansion.
- Battery-swapping infrastructure:Delivery fleet operators are piloting subscription-based energy services that eliminate charging downtime and reduce upfront capital requirements.
- State rebate stacking:California's Clean Vehicle Rebate Project combines with municipal incentives in San Francisco and Los Angeles to drive effective pricing below mass-market bicycle equivalents.
Industry Challenges
- Electrical systems integration talent:Shortage of engineers with combined expertise in power electronics, thermal management, and bicycle mechanical systems constrains product development velocity.
- Multi-jurisdictional certification timelines:Separate CPSC mechanical testing, FCC electromagnetic compliance, and fifty-state regulatory variations extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States E-Bike Market |
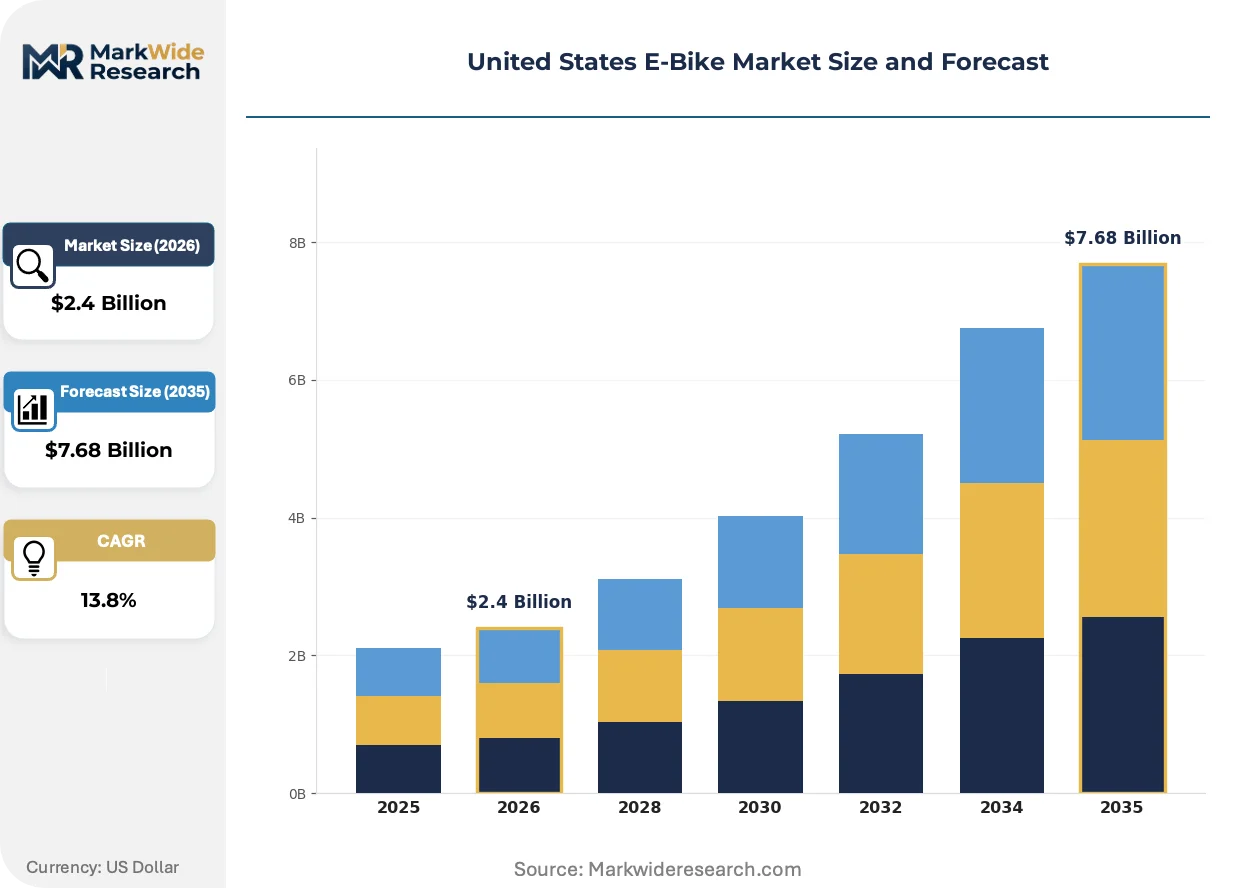
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.68 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain E-Bikes, City E-Bikes, Folding E-Bikes, Cargo E-Bikes Battery Capacity: Below 400 Wh, 400-600 Wh, 600-800 Wh, Above 800 Wh Application: Personal Use, Commercial Use, Delivery Services, Leisure End User: Individuals, Tourists, Delivery Personnel, Government Agencies |
| Companies Covered | Rad Power Bikes, Trek Bicycle Corporation, Aventon Bikes, Giant Manufacturing Co., Lectric eBikes, Specialized, Cannondale, Ride1UP, Juiced Bikes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States E-Bike Market Strategic Shifts & Innovations
Powertrain architecture and energy distribution models are undergoing fundamental restructuring as hub-mounted motors yield to mid-drive systems and battery-swapping networks challenge traditional ownership economics.
Mid-drive motor systems integrating torque sensors with bottom-bracket placement are decentralizing performance advantages previously concentrated in high-torque hub configurations. Cargo fleet operators and touring enthusiasts are adopting these configurations for improved weight distribution and drivetrain efficiency. The technology is decentralizing service and repair ecosystems away from proprietary hub-motor specialists toward standard bicycle mechanic competencies.
EPA emissions standards for light mobility categories are tightening certification requirements for throttle-equipped variants that exceed pedal-assist velocity thresholds. Manufacturers must now submit powertrain efficiency documentation and lifecycle carbon assessments to maintain market access. Class-3 speed pedelec producers face the steepest compliance burden, with several brands withdrawing from California and New York markets rather than absorbing certification costs.
Fleet procurement managers at logistics and food delivery platforms are consolidating vendor relationships around integrated hardware-software-service bundles that include predictive maintenance and guaranteed uptime clauses. Traditional retail channel distributors are losing volume to direct procurement teams at DoorDash, Instacart, and Amazon Flex operations. This concentration is most visible in Los Angeles, New York, and Chicago metropolitan zones where delivery density justifies dedicated vehicle pools.
United States E-Bike Market Segmentation
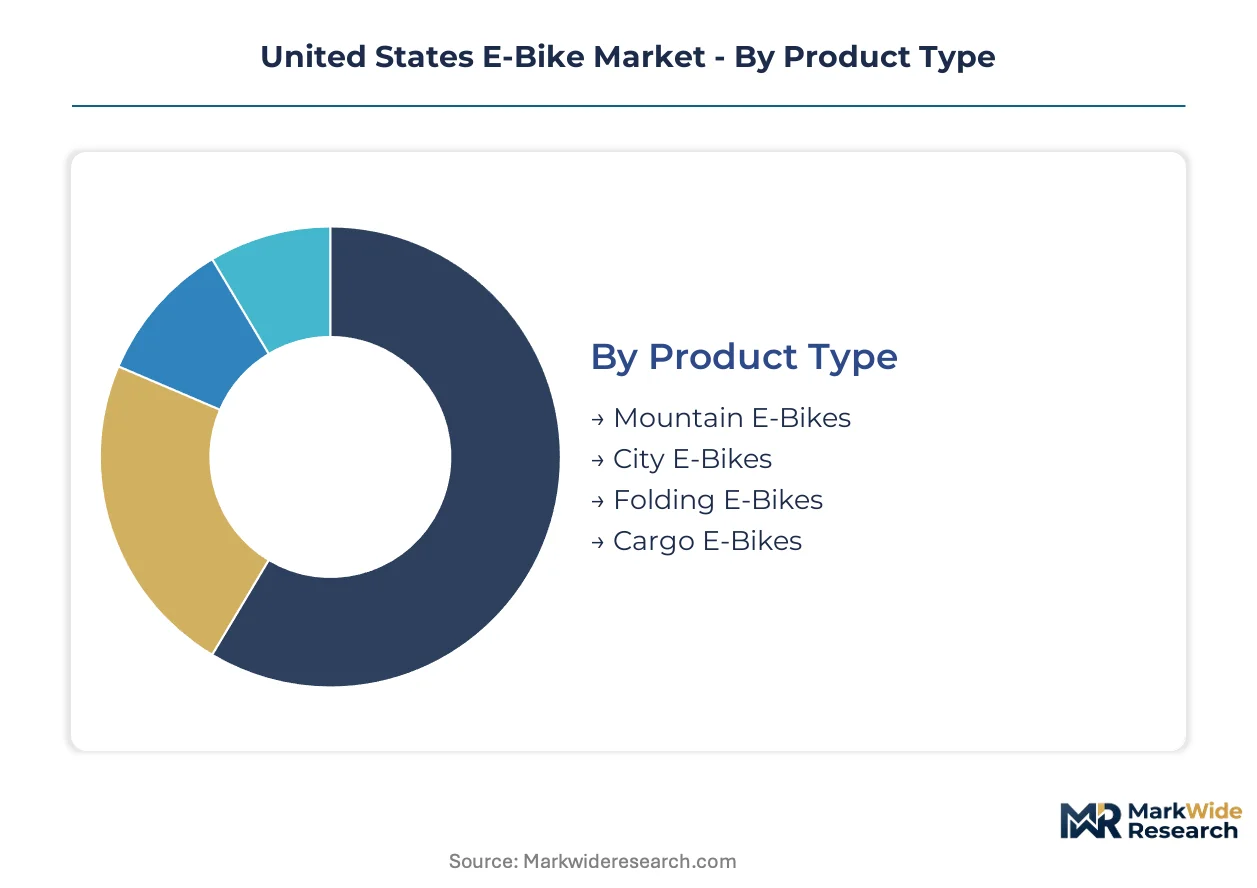
E-bike segmentation in the United States reveals distinct demand profiles across product architecture, energy storage, and operational purpose. Manufacturers configure supply chains and pricing strategies around these divisions, as each segment carries unique regulatory exposure and margin structure.
Product Type:
Integration depth varies sharply: city and cargo variants function as embedded urban infrastructure, while mountain and folding designs serve standalone recreational or convenience needs.
- City E-Bikes:Step-through frames with integrated lighting and fender systems dominate urban commuter purchases. Demand concentrates in California and New York metropolitan corridors where municipal bike lane investments reduce collision risk perception and state rebate programs compress effective pricing.
- Cargo E-Bikes:Extended wheelbase platforms with reinforced rear or front racks support child transport and commercial loads up to four hundred pounds. Last-mile delivery fleets in Chicago, Los Angeles, and Seattle are standardizing procurement around Class-2 throttle-equipped variants to minimize rider fatigue during shift work.
- Mountain E-Bikes:Full-suspension frames with high-torque mid-drive motors target trail access in Colorado, Utah, and Pacific Northwest recreation zones.
- Folding E-Bikes:Hinge-frame designs with reduced wheel diameters address storage constraints in Manhattan and San Francisco high-rise dwellings.
Volume placements concentrate in city e-bikes; the faster expansion belongs to cargo e-bikes.
Battery Capacity:
Cost tier stratification separates entry-level commuters from premium touring enthusiasts and commercial operators requiring extended range.
- 400-600 Wh:Lithium-ion packs with nickel-manganese-cobalt cathodes deliver sixty to eighty miles of pedal-assisted range. This tier captures the majority of personal-use purchases in Texas and Florida suburban markets where trip distances exceed dense urban norms but charging infrastructure remains sparse.
- Above 800 Wh:Dual-battery configurations or oversized single packs enable century-mile touring and full-shift commercial operation without mid-day charging. Specialized applications in Rocky Mountain tourist rental fleets and rural mail delivery routes in Montana and Wyoming drive niche adoption.
- Below 400 Wh:Compact packs integrated into folding frame seatposts prioritize weight reduction over range.
- 600-800 Wh:Single-pack architectures balancing range and frame weight for enthusiast commuters in Pacific Coast metropolitan zones.
Procurement volume clusters in 400-600 Wh configurations; the steepest expansion trajectory is appearing in above-800 Wh systems for commercial fleet specification.
Application:
Customer type differentiation separates individual ownership economics from enterprise procurement models with service-level agreements and predictive maintenance clauses.
- Delivery Services:Platform-mediated logistics operators including DoorDash, Instacart, and Amazon Flex procurement teams specify Class-2 or Class-3 variants with reinforced frames and theft-deterrent electronics. Chicago, New York, and Los Angeles metropolitan zones exhibit the densest fleet deployment as delivery radius economics justify dedicated vehicle pools over gig worker reimbursement models.
- Personal Use:Individual purchasers prioritize purchase price, aesthetic integration, and local service availability through dealer networks or direct-to-consumer channels. Suburban Sun Belt households in Arizona and Texas are exhibiting rising interest as gasoline price volatility and recreational trail access expand use cases beyond pure commuting.
- Commercial Use:Corporate campus shuttle programs and security patrol fleets in Silicon Valley and Washington DC federal installations.
- Leisure:Weekend recreational riders in Vermont and Oregon wine country tourism corridors.
Shipment volume concentrates in personal use; delivery services are gaining share fastest as fleet electrification mandates accelerate vendor consolidation.
End User:
Maturity variation across user categories creates divergent product requirements: experienced cyclists demand performance customization while novice adopters prioritize safety systems and intuitive controls.
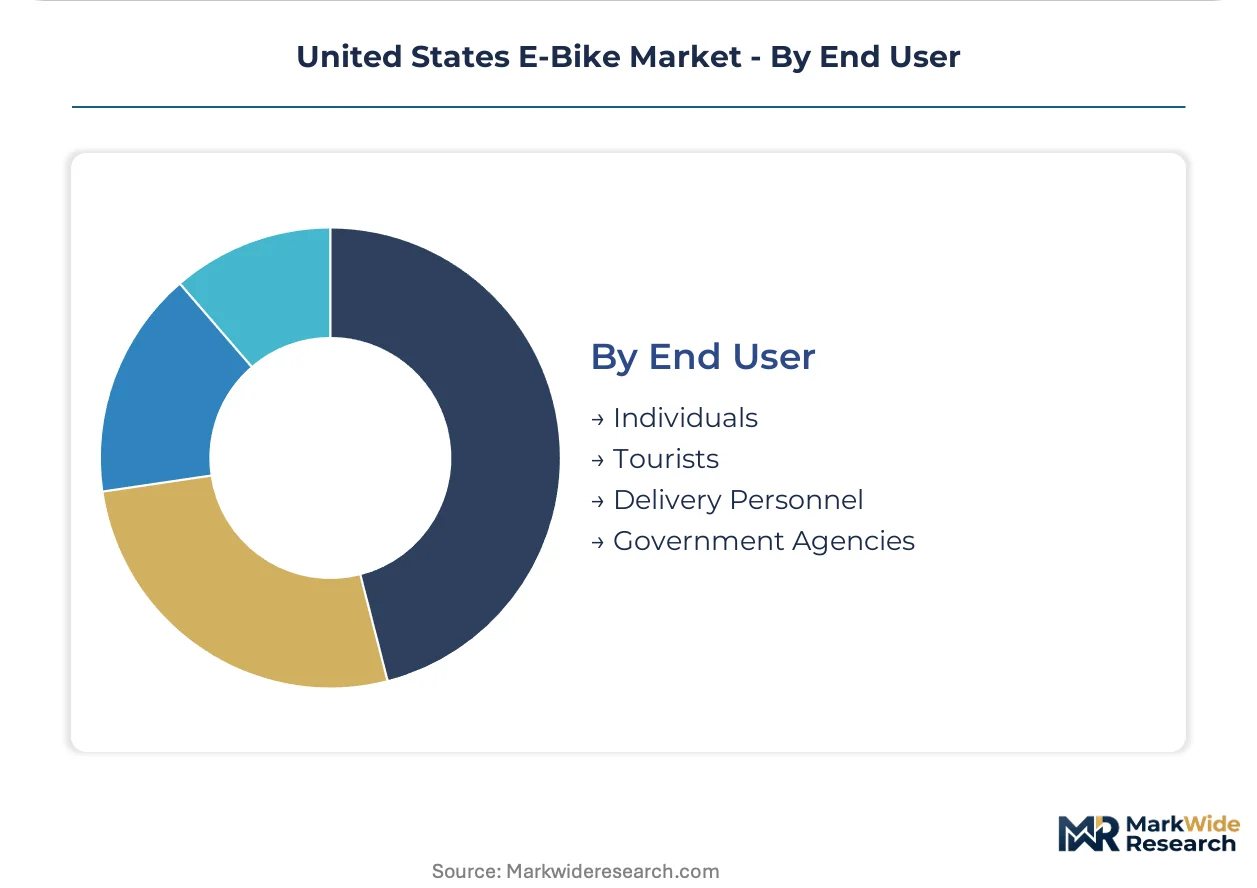
- Individuals:Experienced cyclists transitioning from acoustic bicycles and car-dependent commuters seeking parking cost avoidance constitute the core purchasing base. California and Washington state residents demonstrate the highest per-capita adoption rates as state-level incentives stack with federal tax credits and municipal infrastructure investments reduce perceived risk.
- Delivery Personnel:Gig economy workers operating on platform-determined schedules require reliable throttle operation, all-weather durability, and rapid repair turnaround. New York City and San Francisco have witnessed the densest concentration of individually owned delivery-specified vehicles as parking enforcement and congestion pricing penalize gasoline-powered alternatives.
- Tourists:Short-term rental users in Miami Beach and Santa Monica coastal corridors.
- Government Agencies:Federal park service and municipal police departments in Washington state and Colorado piloting fleet electrification.
Individual purchasers dominate volume placement; delivery personnel represent the segment climbing fastest as platform labor force expansion continues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium deposits in Nevada's Clayton Valley and cobalt refining capacity in Texas anchor domestic battery supply chains for e-bike assembly operations across the American Southwest.
California
Urban commuters in San Francisco and Los Angeles drive volume demand as the state's Clean Vehicle Rebate Project stacks with municipal incentives. EPA emissions standards for light mobility categories tighten certification requirements for throttle-equipped variants exceeding twenty miles per hour. Silicon Valley corporate campus shuttle programs and security patrol fleets pilot standardized procurement of Class-2 cargo configurations.
Texas
Sun Belt metropolitan expansion zones in Dallas-Fort Worth and Houston exhibit rising household interest as gasoline price volatility expands use cases beyond pure commuting. State departments of transportation layer classification rules determining where riders may legally operate across varying speed thresholds. Austin's tech corridor hosts emerging dealer network expansion targeting suburban secondary markets with 400-600 Wh configurations.
New York
Manhattan apartment dwellers prioritize folding e-bike designs addressing storage constraints in high-rise dwellings while delivery personnel concentrate in Brooklyn and Queens. The Consumer Product Safety Commission enforces federal mechanical and electrical safety standards for low-speed electric bicycles operating on congested bridge corridors. Congestion pricing enforcement in Manhattan penalizes gasoline-powered alternatives, accelerating platform-mediated logistics operator fleet conversion.
Illinois
Last-mile delivery fleets in Chicago standardize procurement around Class-2 throttle-equipped variants to minimize rider fatigue during shift work across dense metropolitan zones. National Highway Traffic Safety Administration jurisdiction over road-operated variants exceeding twenty miles per hour creates compliance ambiguity for manufacturers serving multi-state operators. South Side logistics hubs host consolidated vendor relationships around integrated hardware-software-service bundles with predictive maintenance clauses.
Washington
Experienced cyclists transitioning from acoustic bicycles demonstrate the highest per-capita adoption rates as state-level incentives stack with federal tax credits. Federal tariff exposure on Chinese battery cells forces supply chain reconfiguration around Mexican contract manufacturing for Seattle-based design headquarters. Rad Power Bikes leverages its direct-to-consumer channel to control pricing across the mass-market tier from Pacific Northwest distribution infrastructure.
United States E-Bike Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel optimization and fleet procurement consolidation. The vendor base distributes across mass-market direct sales, premium dealer networks, and commercial fleet supply contracts. Three archetypes dominate: vertically integrated assemblers with domestic design headquarters, legacy bicycle manufacturers with expanded electrified portfolios, and specialist entrants focused on cargo configurations for logistics operators. Competitive moves concentrate on supply chain nearshoring investments and strategic partnerships with battery-swapping infrastructure providers.
Within the mass-market tier, Rad Power Bikes and Lectric eBikes exemplify direct-to-consumer channel optimization, while Trek Bicycle Corporation anchors legacy manufacturer positioning through extensive retail presence. Specialized occupies a position representing premium-tier differentiation through in-house motor development. Aventon Bikes and Ride1UP sit within the emerging specialist category targeting urban commuters with simplified procurement pathways.
| Leading Market Players |
|---|
| Rad Power Bikes |
| Trek Bicycle Corporation |
| Aventon Bikes |
| Giant Manufacturing Co. |
| Lectric eBikes |
| Specialized |
| Cannondale |
| Ride1UP |
| Juiced Bikes |
| Others |
Cost & Logistics Intelligence
Lithium carbonate spot indices cascading through battery pack procurement contracts stratify landed costs across mass-market and premium assembly tiers, compressing margins for brands lacking Mexican or Vietnamese contract manufacturing alternatives while amplifying pricing power for vertically integrated producers with captive cell supply.
Pricing Analysis
Warranty bundling separates Rad Power Bikes' direct-to-consumer extended service contracts from Trek Bicycle Corporation's dealer-network maintenance packages, creating three-tier pricing structure across premium, standard, and economy levels based on motor certification grade and after-sales coverage depth. Price differentiation stems from UL 2849 electrical safety certification investment and hub-motor versus mid-drive architecture complexity. Cost compression in the sub-$1,500 tier is intensifying because Section 301 tariff exposure on Chinese frame assemblies elevates landed costs for mass-market brands. Fleet procurement managers at DoorDash and Instacart exhibit lowest price sensitivity due to guaranteed uptime clauses, while individual apartment dwellers in Manhattan demonstrate highest sensitivity to upfront capital outlay.
Supply Chain Analysis
Assembly technician availability in Mexicali and Tijuana maquiladora zones anchors nearshoring investments for Seattle-based design headquarters seeking tariff mitigation, while Vietnamese motor controller specialists remain concentrated in Ho Chi Minh City industrial corridors. Raw material dependencies draw from Nevada Clayton Valley lithium brine operations, Texas cobalt refining capacity, and Chinese rare earth magnet processing facilities. Supply chain risk centers on single-source vulnerability for 21700-format cylindrical cells produced in concentrated Chinese gigafactories. Distribution runs through Pacific Northwest direct-to-consumer fulfillment centers, twelve-hundred-location dealer networks for legacy manufacturers, and dedicated fleet procurement teams at Amazon Flex operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive battery cell production and proprietary motor development determine margin defense against tariff-exposed competitors.
For Market Incumbents: Anchor dealer network loyalty through exclusive service territory allocations and predictive maintenance software integration, defending against direct-to-consumer entrants by emphasizing local repair turnaround speed. Invest in in-house motor development capabilities to reduce dependency on Chinese hub-motor suppliers facing escalating tariff exposure. Prioritize UL 2849 certification investment as a barrier to mass-market competitors lacking capital for third-party testing protocols. For New Entrants and Emerging Players: Enter via battery-swapping infrastructure partnerships targeting Chicago and Los Angeles delivery fleet operators, where subscription-based energy services eliminate upfront capital barriers for gig economy workers. Target Sun Belt metropolitan expansion zones in Dallas-Fort Worth and Houston with simplified 400-600 Wh configurations for suburban households exhibiting rising interest. Pursue municipal rebate program alignment in California's Clean Vehicle Rebate Project jurisdictions to compress effective pricing below acoustic bicycle equivalents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-drive motor specialists with FCC electromagnetic compliance expertise in Pacific Northwest technology corridors, where electrical systems integration talent scarcity constrains product development velocity. Long-term viability hinges on five-to-ten-year fleet electrification mandate durability across platform logistics operators. Monitor pending federal tariff review announcements as inflection indicators for supply chain reconfiguration urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Footprint Expansion | Mexican contract manufacturing mitigates Section 301 tariff exposure on Chinese frame imports. |
| Battery Chemistry Transition | Lithium iron phosphate adoption extends cycle life for commercial fleet operators in Chicago delivery zones. |
| Direct-to-Consumer Channel Optimization | Seattle-based fulfillment infrastructure controls pricing across mass-market tier without dealer margin stacking. |
| Fleet Procurement Consolidation | Integrated hardware-software-service bundles capture volume from DoorDash and Instacart vendor rationalization. |
| Regulatory Certification Investment | UL 2849 and FCC compliance creates market access barriers for undercapitalized competitors. |
Research Approach
Independent corroboration across CPSC enforcement actions, EPA emissions standard dockets, and NHTSA jurisdiction determinations underwrites the qualitative findings, supplemented by primary interviews with e-bike product development directors, fleet procurement managers at platform logistics operators, dealer network operations heads, and lithium-ion battery supply chain specialists. Secondary validation draws from SEC 10-K filings of publicly traded bicycle manufacturers, customs import records for HTS 8711.60.00 classifications, and state transportation department regulatory filings. Bottom-up shipment estimates triangulate against top-down consumer expenditure models across the analysis window.
Comparable-period anchoring to pre-Inflation Reduction Act baseline years establishes trajectory calibration for federal incentive impact assessment across the projection horizon. Segmentation dimensions modeled include product architecture, battery capacity tier, application purpose, and end-user maturity level. CAGRs derive from installed base replacement cycles, fleet electrification mandate adoption curves, and state rebate program exhaustion timelines. Forecast inputs incorporate lithium carbonate price volatility scenarios and tariff rate uncertainty bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated Section 301 tariff escalation or municipal incentive program suspension. Projections reflect assumptions regarding CPSC-NHTSA jurisdictional clarity resolution and EPA emissions certification pathway stability for Class-3 speed pedelec variants. Material deviation in federal clean vehicle credit extension timelines or Nevada lithium extraction permit approvals warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Motorbike Carburetor Market
Bikes and Motorcycles
Motorcycle Shock Absorbers Market
Bikes and Motorcycles
Motorcycle Transmission Control Unit Market
Bikes and Motorcycles
Automotive Bicycle Rack Market
Bikes and Motorcycles
Global Bicycle Derailleur Market
Bikes and Motorcycles
Spain E-Bike Market
Bikes and Motorcycles
United Arab Emirates E-Bike Market
Bikes and Motorcycles
Bicycle Mechanical Disc Brake Market
Bikes and Motorcycles
Two Wheeler Fenders Market
Bikes and Motorcycles
Sweden Electric Bike Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Folding Bicycle Market
Bikes and Motorcycles
E-Cargo Bike Market
Bikes and Motorcycles
Motorsports Motorcycle Market
Bikes and Motorcycles
Motorcycle Instrument Cluster Market
Bikes and Motorcycles
Folding Bikes Market